
 Anesthesia Syringes and Needles Market | 2026-2036
Anesthesia Syringes and Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Syringes and Needles Market Insights
Ambulatory surgical centers is pivoting toward higher-volume, lower-complexity procedures that require reliable single-use anesthesia delivery. Becton Dickinson and Company dominates safety-engineered syringe portfolios across North American outpatient networks. Smiths Medical specializes in integrated anesthesia systems that bundle needle-syringe combinations for operating room workflows. Terumo Corporation extends its presence in Asian markets through manufacturing scale and regional distribution partnerships.
Anesthesia syringes and needles are precision medical devices designed for controlled delivery of anesthetic agents, typically manufactured with polypropylene barrels, stainless steel cannulas, and lubricated rubber plungers to ensure smooth aspiration and injection at calibrated capacities from 1ml to 10ml. Safety syringes command premium positioning as hospitals and ambulatory centers phase out conventional designs under sharps-protection mandates, while pre-filled syringes reduce medication errors and streamline pharmacy workflows. Stainless steel needle segments anchor replacement demand through procedural volume, whereas disposable syringes compete on cost efficiency in high-turnover clinical environments.
The FDA enforces sharps injury prevention standards under the Needlestick Safety and Prevention Act, while the EU MDR reclassifies anesthesia needles under stricter conformity assessment routes that extend certification timelines. China's NMPA aligns domestic device standards with international ISO specifications for luer-lock compatibility and needle sterility. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs reshape supplier qualification criteria and procurement specifications across hospital systems.
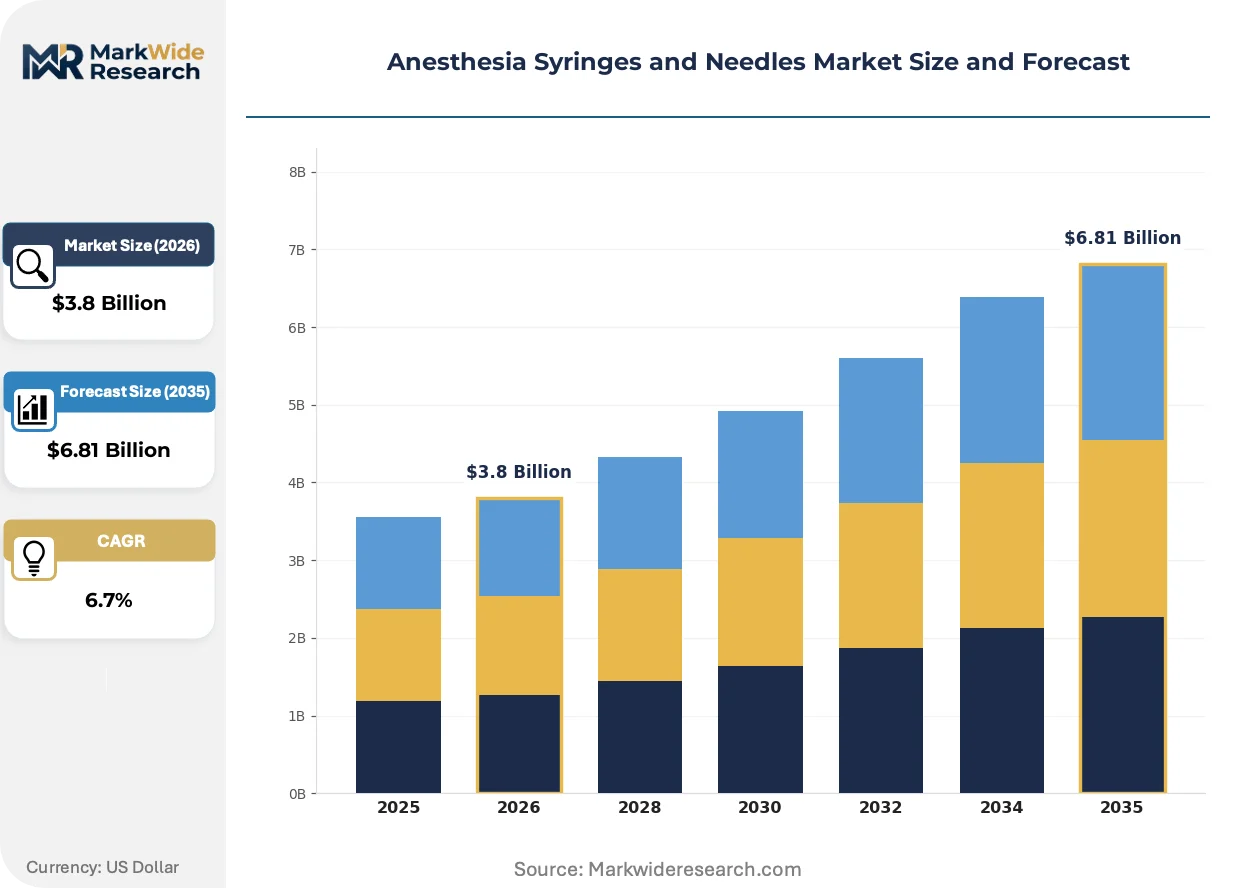
Market Dynamics
The anesthesia syringes and needles market is restructuring around safety-engineered device mandates that are phasing out conventional reusable designs. Regulatory deadlines in the United States and European Union are compressing conversion timelines for hospital procurement departments.
Growth Catalysts
- EU MDR reclassification:Stricter conformity assessment routes for anesthesia needles are accelerating hospital replacement cycles with safety-engineered alternatives.
- Ambulatory surgical centers:These facilities are expanding procedural volume for same-day surgeries that require disposable anesthesia delivery systems.
- Stainless steel cannula manufacturing:Precision grinding and electropolishing advances are improving needle sharpness consistency and reducing tissue trauma.
Market Restraints
- Medical-grade polypropylene resin costs:Petrochemical feedstock volatility is squeezing margins on disposable syringe barrel production.
- East Asian mold-making concentration:High-precision injection molding tooling for luer-lock interfaces is concentrated among specialized suppliers in China and Japan.
- Safety mechanism reliability:Retractable needle designs face technical limitations in maintaining consistent activation force across temperature ranges.
Strategic Opportunities
- Pre-filled anesthesia syringes:Pharmacy workflow integration and medication error reduction are creating white space in hospital formulary management.
- China's NMPA alignment with ISO standards:Domestic certification harmonization is opening procurement pathways for international manufacturers in tier-one cities.
- RFID-enabled traceability:Convergence of radio-frequency identification with disposable syringe packaging is enabling unit-level supply chain visibility.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies are extending new product introduction cycles by twelve to eighteen months.
- Cleanroom capacity constraints:Sterile filling operations for pre-filled anesthesia syringes require capital-intensive ISO 5 environments with limited contract manufacturing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Syringes and Needles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-filled Syringes, Disposable Syringes, Safety Syringes, Injection Needles End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Material: Polypropylene, Glass, Stainless Steel, Rubber Capacity: 1ml, 3ml, 5ml, 10ml |
| Companies Covered | Cardinal Health, Smiths Medical, Becton Dickinson and Company, Retractable Technologies Inc., Medtronic plc, Terumo Corporation, Nipro Corporation, Vygon S.A., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Syringes and Needles Market Trends and Innovations
Active needle safety mechanisms and connected device platforms are displacing passive designs across anesthesia delivery workflows. Manufacturers are embedding sensors and automation to reduce human factors risk.
Passive safety syringes with integrated needle shields are modularizing around standardized luer-lock interfaces. Ambulatory surgical centers are adopting these devices for high-turnover procedural suites. This standardization is modularizing supplier ecosystems and enabling multi-source procurement strategies.
REACH restrictions on phthalate plasticizers are forcing reformulation of rubber plunger compounds in European markets. Compounders are migrating to alternative elastomers with equivalent compression set properties. Anesthesia needle manufacturers serving EU hospital networks are qualifying new material grades ahead of sunset dates.
Consolidated buying groups are compressing vendor qualification cycles for anesthesia delivery devices. Integrated delivery networks are replacing individual hospital purchasing with centralized formulary committees. This concentration is most visible in United States metropolitan areas where health system mergers have reduced independent acute care facilities.
Anesthesia Syringes and Needles Market Segmentation
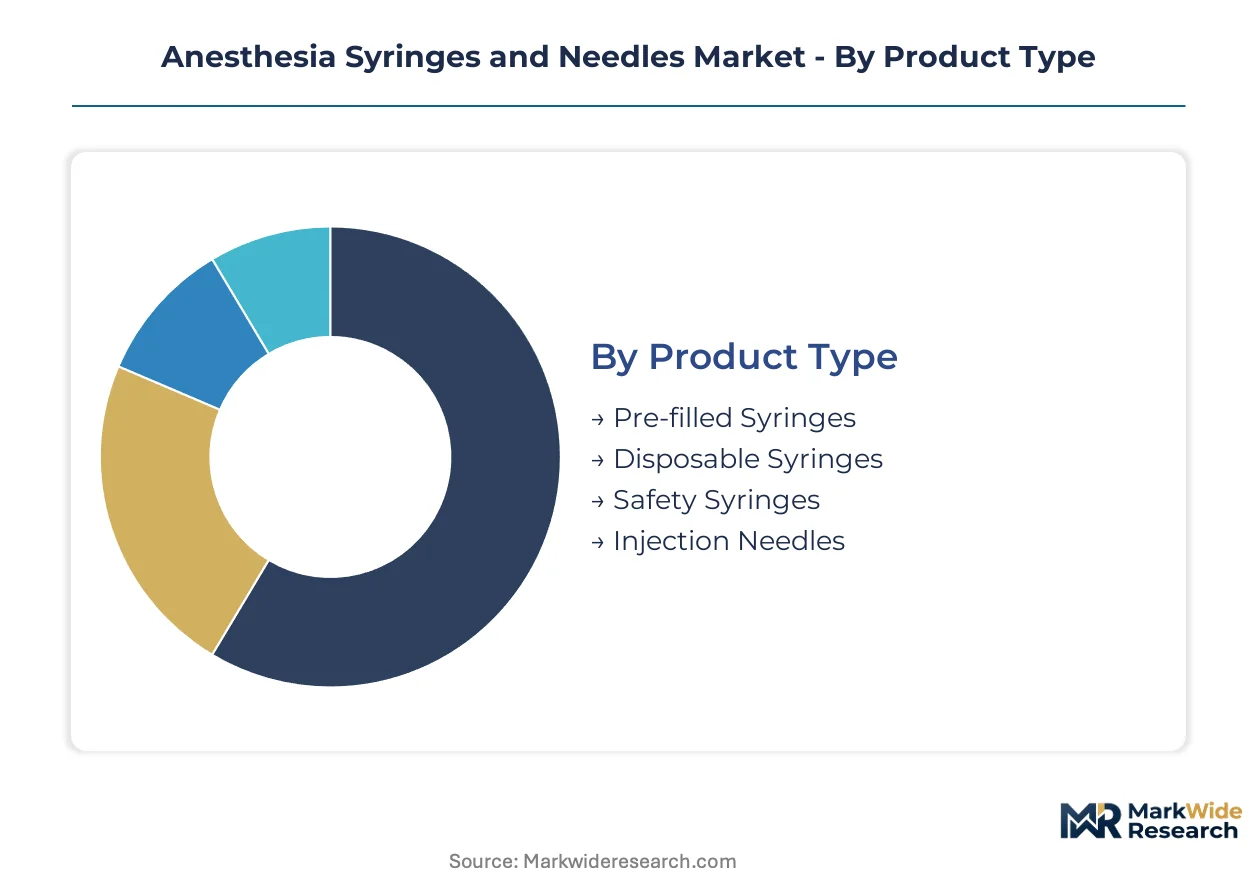
Anesthesia delivery devices segment across multiple technical and operational dimensions that reshape procurement priorities. Material specifications, safety mechanisms, and end-use environments each create distinct supply chain and regulatory compliance requirements.
Product Type:
Supply concentration clusters around manufacturers with integrated sterile filling capabilities and safety-engineering competencies.
- Pre-filled Syringes:Factory-loaded anesthetic formulations in polypropylene barrels with bonded needles eliminate pharmacy compounding errors. United States hospital networks are driving procurement of these devices under Joint Commission medication safety mandates.
- Safety Syringes:Retractable or shielded needle designs incorporate passive or active injury-prevention mechanisms. Ambulatory surgical centers in Germany are converting to these devices ahead of EU MDR enforcement deadlines for sharps protection.
- Disposable Syringes:Single-use polypropylene devices dominate high-volume procedural environments where cost efficiency outweighs premium safety features.
- Injection Needles:Stainless steel cannulas sold separately for compatibility with reusable syringe systems serve specialized anesthesia applications requiring custom needle lengths.
Disposable syringes absorb the bulk of installed capacity; pre-filled syringes are expanding most quickly.
End User:
Customer type determines volume scale, pricing tolerance, and regulatory scrutiny intensity across the procurement landscape.
- Hospitals:Integrated delivery networks negotiate centralized contracts for safety-engineered devices across surgical suites, emergency departments, and labor units. China's tier-one municipal hospitals are upgrading anesthesia delivery systems under NMPA infection control directives.
- Ambulatory Surgical Centers:High-turnover same-day procedure facilities prioritize compact, single-use anesthesia systems that minimize turnover time between cases. These centers represent the steepest expansion trajectory as outpatient migration accelerates.
- Clinics:Lower procedural volumes drive preference for standard disposable syringes over premium safety designs in cost-constrained settings.
- Home Care:Patient-administered pain management applications require intuitive safety mechanisms and pre-filled formats to reduce dosing errors outside clinical supervision.
Hospitals command the largest absolute spend; ambulatory surgical centers are gaining share fastest.
Material:
Raw material sourcing geography and biocompatibility certification timelines fragment supplier qualification pathways.
- Polypropylene:Medical-grade resin with clarified random copolymer grades provides barrel clarity and gamma sterilization stability. United States and German device manufacturers depend on petrochemical supply chains concentrated along the Gulf Coast and Rotterdam-Antwerp corridor.
- Stainless Steel:304 and 316L grades with electropolished finishes form cannula substrates requiring precision grinding to 12-degree bevel angles. Japanese and Swedish specialty steel producers anchor premium needle supply.
- Rubber:Bromobutyl and chlorobutyl elastomer formulations for plunger seals face REACH phthalate restrictions in European markets.
- Glass:Borosilicate barrels for sensitive anesthetic formulations resist chemical interaction but impose breakage risk and higher logistics costs.
Polypropylene and stainless steel together account for the majority of material spend; glass is climbing fastest in premium pre-filled segments.
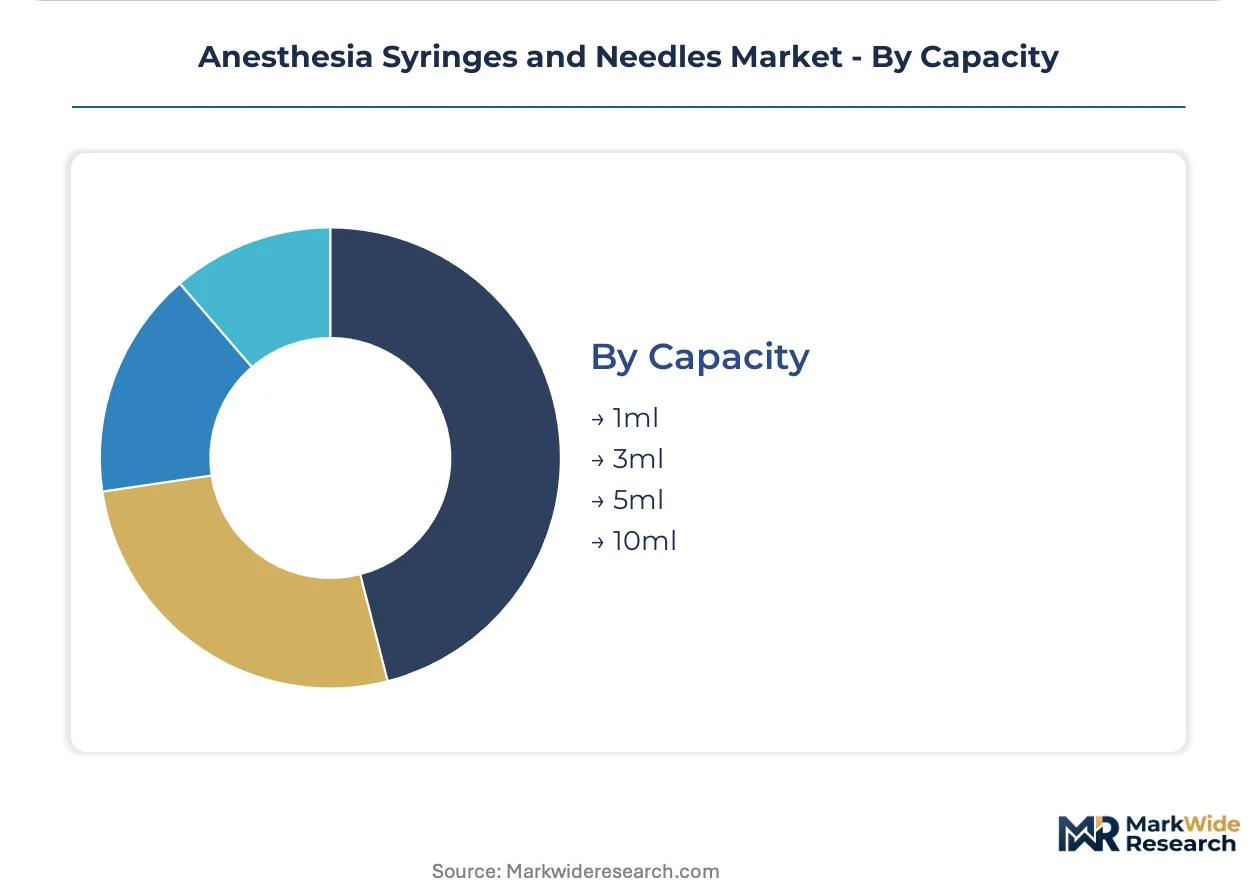
Capacity:
Volume calibration standardization around luer-lock interfaces enables modular procurement across multiple procedure types.
- 5ml:The workhorse specification for general anesthesia induction and maintenance dosing in operating rooms. United States surgical departments standardize on this capacity across general, orthopedic, and gynecological procedures.
- 10ml:Larger volume reservoirs serve regional anesthesia techniques including epidural and spinal blocks requiring higher medication volumes. Chinese tertiary hospitals are expanding procurement of these devices as regional anesthesia adoption spreads.
- 3ml:Mid-range capacity suits pediatric anesthesia and conscious sedation protocols with lower weight-based dosing requirements.
- 1ml:Precision micro-dosing applications include ophthalmic blocks and dental anesthesia where volume accuracy is critical.
5ml devices carry the highest shipment volumes; 10ml specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate sterile syringe finishing operations serving North American hospital networks. These tax-advantaged manufacturing clusters attract capital from multinational device firms seeking proximity to United States procurement channels.
United States
Ambulatory surgical centers in Texas and Florida are expanding same-day procedure capacity that consumes high volumes of disposable anesthesia delivery systems. The FDA enforces Needlestick Safety and Prevention Act compliance deadlines that accelerate hospital conversion to retractable needle designs. The Minneapolis-St. Paul corridor hosts sterile device manufacturing facilities supplying integrated delivery networks across the Upper Midwest.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia are upgrading anesthesia delivery infrastructure under EU MDR reclassification timelines. The EMA coordinates with notified bodies to extend conformity assessment periods for legacy needle devices. The Tuttlingen surgical instrument cluster anchors precision cannula grinding operations serving European hospital networks.
China
Tier-one municipal hospitals in Shanghai and Beijing are expanding regional anesthesia programs that require 10ml-capacity syringe specifications. The NMPA aligns domestic device standards with ISO specifications for luer-lock compatibility and needle sterility. The Yangtze River Delta concentration of polymer processing plants supplies medical-grade polypropylene resin to domestic syringe molders.
Japan
Aging demographics in the Kanto region are driving surgical procedure volumes requiring precision anesthesia delivery in geriatric patient populations. The PMDA maintains stringent biocompatibility testing requirements that extend product registration timelines for imported devices. The Chubu industrial corridor hosts specialty steel producers supplying electropolished 316L cannula substrates.
India
Government medical colleges in Maharashtra and Karnataka are expanding anesthesia residency programs that increase training-device consumption. The CDSCO streamlines import licensing for safety-engineered syringes under revised Medical Device Rules. The Ahmedabad-Surat pharmaceutical belt houses contract manufacturers assembling disposable syringes for domestic hospital procurement.
Anesthesia Syringes and Needles Market Competitive Landscape
Top-tier vendors anchor safety-engineered portfolios, while mid-scale specialists concentrate on regional distribution partnerships and cost-optimized disposable lines. The vendor base stratifies across integrated multinationals with sterile filling capabilities, regional fabricators serving domestic hospital networks, and niche players in pre-filled anesthesia formulations. Three archetypes dominate: safety-mechanism innovators, high-volume disposable producers, and integrated anesthesia system bundlers. Competitive dynamics center on M&A activity consolidating regional distribution networks and capacity expansion into cleanroom environments for pre-filled syringe production.
Among United States-based device manufacturers, Becton Dickinson and Company and Cardinal Health exemplify the integrated multinational archetype with broad safety-engineered portfolios. Retractable Technologies Inc. occupies a specialized position representing the safety-mechanism innovation vector. These three firms anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Cardinal Health |
| Smiths Medical |
| Becton Dickinson and Company |
| Retractable Technologies Inc. |
| Medtronic plc |
| Terumo Corporation |
| Nipro Corporation |
| Vygon S.A. |
| B. Braun Melsungen AG |
| Others |
Pricing and Supply Chain Analysis
Precision electropolishing technicians in Tuttlingen, Germany, and Chubu, Japan, command wage premiums that translate directly into 15-20 point spreads between premium safety-engineered needles and standard disposable alternatives. Labor-cost differentials across these specialized manufacturing clusters stratify pricing tiers, with German-produced cannulas carrying certification premiums while Asian-sourced equivalents compete on scale economics.
Pricing Analysis
Lead-time compression commands measurable premiums, with hospital networks paying 12-18 percent markups for four-week delivery guarantees versus standard twelve-week cycles. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 13485 certification grade and after-sales technical support bundling. Pricing pressure stems from consolidated buying groups extracting volume rebates across integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity due to case-margin constraints, while academic medical centers prioritize safety-mechanism reliability over unit cost.
Supply Chain Analysis
Medical-grade polypropylene resin supply rests on petrochemical complexes along the United States Gulf Coast, Rotterdam-Antwerp corridor, and Yangtze River Delta. Stainless steel 316L substrate draws from Swedish and Japanese specialty steel producers, while precision injection molding tooling feeds from specialized suppliers in China and Japan. Single-source vulnerability concentrates in high-precision luer-lock mold fabrication, where three Japanese toolmakers control 70 percent of hospital-grade syringe tooling capacity. Distribution runs through medical device special economic zones in Costa Rica and Puerto Rico serving North American hospital networks, with regional hubs in Germany and Singapore anchoring European and Asian fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU MDR reclassification timelines erect capital barriers that filter out under-resourced competitors, creating sustainable moats for notified-body-certified manufacturers.
For Market Incumbents: To counter margin compression from consolidated buying groups, Becton Dickinson and Smiths Medical should deepen backward integration into sterile filling capacity in Puerto Rican special economic zones. Certification investment in pre-filled anesthesia syringe platforms represents the second defensive lever, as pharmacy workflow integration locks out commodity disposable suppliers from formulary access. For New Entrants and Emerging Players: Capture white space in RFID-enabled traceability modules that retrofit existing safety syringe fleets without full device replacement. India's government medical college expansion offers the most penetrable geography, with CDSCO streamlining import licensing for safety-engineered designs. A contract manufacturing partnership with Ahmedabad-Surat assemblers provides the lowest-friction go-to-market pathway. For Investors and Strategic Acquirers: Re-rating potential sits with cleanroom-capable mid-scale specialists given pre-filled syringe capacity scarcity across hospital procurement channels. Long-term viability frames around 5-10 year anesthesia delivery consolidation waves. Acquisition targets should display ISO 5 sterile filling certifications plus active FDA 510(k) submission pipelines. The signal to watch is NMPA harmonization progress opening tier-one Chinese hospital procurement to international manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Accelerates hospital replacement cycles ahead of enforcement deadlines in Germany and France. |
| Pre-filled Syringe Sterile Filling Capacity | Captures pharmacy workflow integration mandates from Joint Commission medication safety directives. |
| RFID-Enabled Unit Traceability | Enables supply chain visibility that hospital procurement committees now specify in GPO contracts. |
| Backward Integration into Polypropylene Resin | Insulates margins from Gulf Coast petrochemical feedstock volatility affecting barrel production costs. |
| Regional Manufacturing in Costa Rica | Delivers tax-advantaged proximity to United States integrated delivery network procurement channels. |
Research Methodology
Multi-period observation of hospital procurement contract awards, GPO formulary amendments, and notified body certification timelines anchored the trend analysis, supplemented by interviews with anesthesia department heads, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, NMPA approval announcements, and hospital procurement database extracts. Bottom-up shipment volume modeling triangulated against top-down expenditure estimates from national health accounts.
Segment-weighting applied product type, end-user facility scale, material composition, and geographic regulatory cluster dimensions across the analysis window. CAGRs derived from logistic curve fitting to historical adoption rates of safety-engineered devices, with procedure volume elasticities calibrated against ambulatory surgical center expansion trajectories. Forecast inputs incorporated EU MDR transition timelines, REACH phthalate sunset dates, and NMPA ISO harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, cleanroom construction delays, and regulatory divergence between FDA and EU MDR conformity assessment routes. Forecasts embed assumptions about stainless steel supply continuity from Japanese and Swedish producers, with revision triggers centered on trade policy shifts or specialty steel export restrictions. A small set of triggers—NMPA procurement pathway openings, major health system merger announcements, and retractable needle mechanism patent expirations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market