
 Safety Box for Syringe Market | 2026-2036
Safety Box for Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Box for Syringe Market Analytics
India is reshaping manufacturing footprints for safety box suppliers as domestic production capacity expands to serve immunization and hospital networks. Becton Dickinson leverages its integrated medical device portfolio to bundle sharps disposal with injection systems. Terumo Corporation anchors its position through specialized hospital channel relationships across Asia-Pacific markets. Smurfit Kappa competes via sustainable fiber-based alternatives that address plastic reduction mandates.
A safety box for syringe is a puncture-resistant container engineered from high-density polyethylene, galvanized steel, or corrugated fiberboard composites, designed to receive used needles and syringes without exposing handlers to bloodborne pathogens. The container typically incorporates a one-way aperture, liquid-resistant seams, and fill-line indicators to prevent overfill and accidental sharps exposure. Single-use plastic variants dominate current hospital procurement volumes due to cost efficiency and infection control protocols, while composite materials are gaining traction where incineration restrictions limit disposal options. Laboratories and home care segments present divergent capacity requirements, with 5-unit and 10-unit formats prevailing in decentralized settings versus 50-unit systems for high-throughput clinical environments.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement shape product design specifications and market access thresholds in the United States, while India's CDSCO and BIS certification requirements govern import and domestic manufacturing compliance. The EU MDR and REACH chemical restrictions additionally influence material selection for European market entry. Stakeholders must monitor evolving extended producer responsibility frameworks and needlestick prevention legislation as these regulatory instruments increasingly mandate safety-engineered disposal systems alongside injection devices themselves.
Market Dynamics
OSHA Bloodborne Pathogens Standard enforcement and WHO needle safety guidelines are compressing disposal protocol timelines, forcing procurement departments to consolidate supplier relationships around certified puncture-resistant containment systems with integrated fill-monitoring features.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Revised enforcement protocols in the United States mandate safety-engineered sharps disposal alongside injection devices, expanding mandatory replacement cycles for non-compliant containers in hospital systems.
- India's national immunization program:Injection safety infrastructure scaling creates concentrated demand for high-volume safety box procurement across public health networks and district hospital chains.
- Galvanized steel and fiberboard composites:Incineration restrictions in European jurisdictions accelerate material substitution away from single-use plastics toward reusable or biodegradable containment formats.
Market Restraints
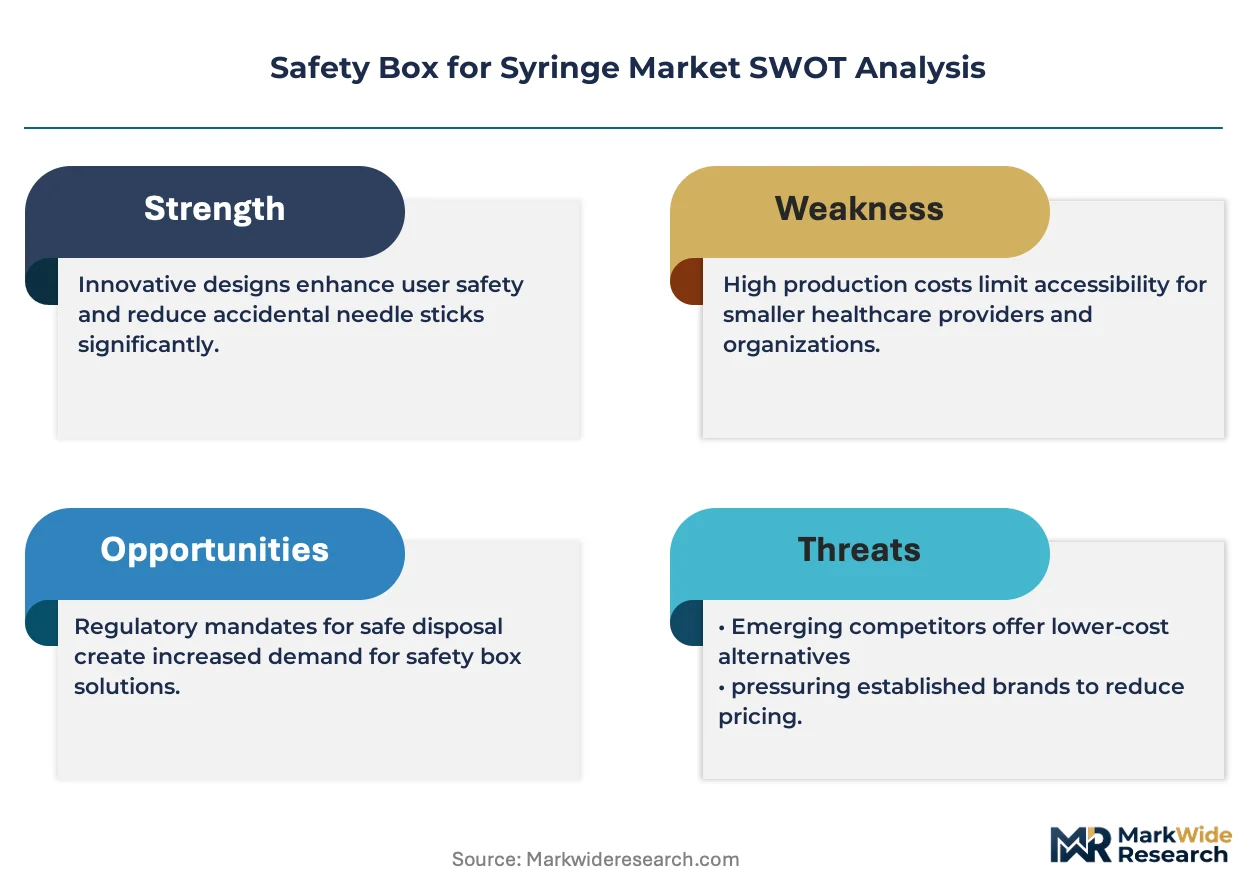
- High-density polyethylene resin volatility:Petrochemical feedstock cost swings compress margins for plastic-dominant manufacturers serving price-sensitive public health tenders.
- CDSCO and BIS certification complexity:India's dual-layer import and domestic manufacturing compliance creates extended validation timelines for new market entrants.
- Autoclave sterilization systems:Reusable sharps processing technologies in centralized hospital waste facilities threaten single-use safety box volume in tertiary care settings.
Strategic Opportunities
- Home care and decentralized settings:5-unit and 10-unit compact formats address underpenetrated diabetes management and self-injection therapy markets in suburban and rural United States.
- EU Green Deal extended producer responsibility:Packaging waste frameworks incentivize fiber-based safety box development with take-back logistics integration.
- Smart fill-level sensors:IoT-enabled capacity monitoring converges with hospital inventory management systems to enable predictive restocking and reduce overfill incidents.
Industry Challenges
- FDA 510(k) clearance timelines:Novel material submissions for composite safety boxes face extended premarket notification review periods averaging 180 days.
- REACH chemical restriction compliance:European material selection requires ongoing substance screening as ECHA updates restricted substance lists affecting colorants and stabilizers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Box for Syringe Market |
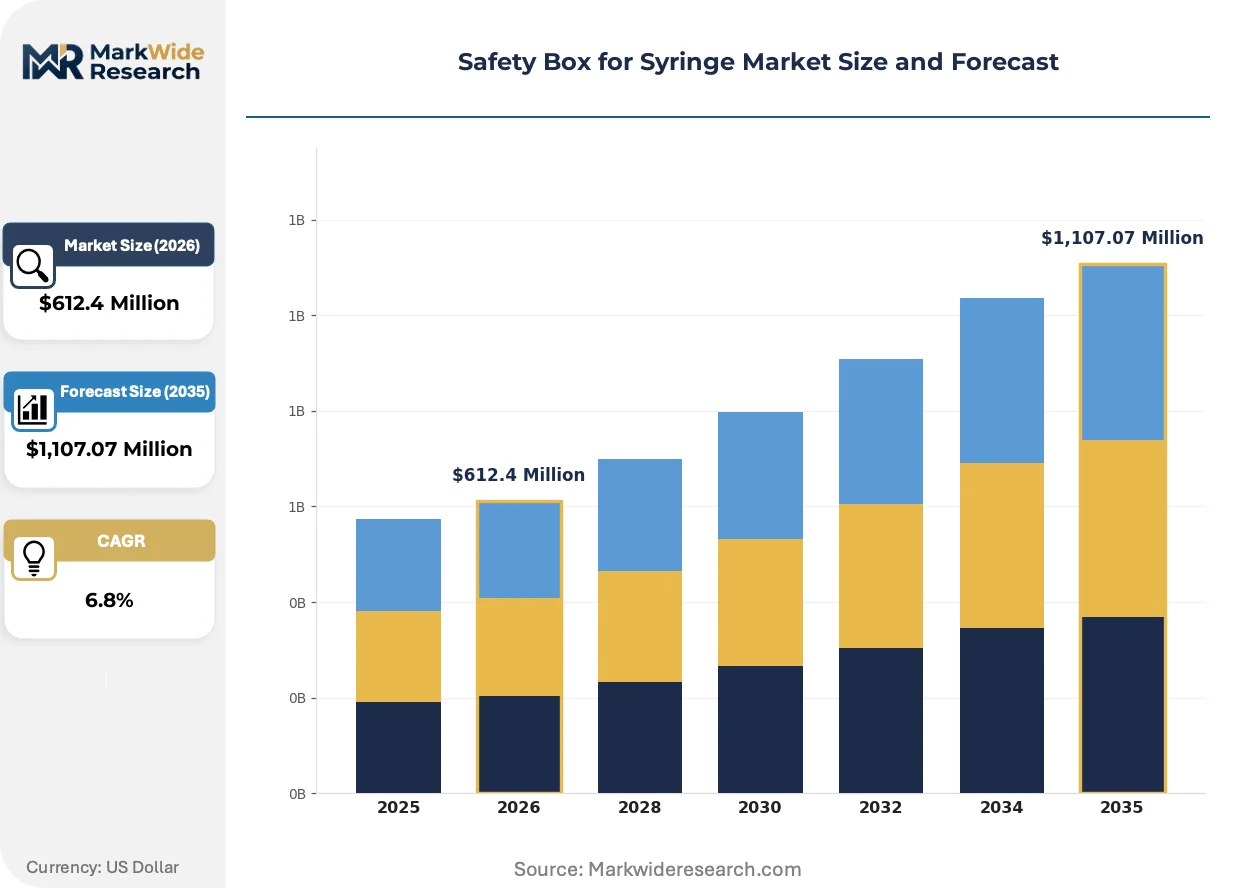
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Biohazard, Disposable Material: Plastic, Metal, Glass, Composite End User: Hospitals, Clinics, Home Care, Laboratories Capacity: 5 Units, 10 Units, 20 Units, 50 Units |
| Companies Covered | Medix Safe, Sanpro Wastes, HMD Healthcare, Smurfit Kappa, TimSafe Safety Box, 3M, Becton Dickinson, Terumo Corporation, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Box for Syringe Market Evolving Landscape
Material science advances and connected device integration are redefining safety box functionality beyond passive containment, with procurement criteria increasingly weighting traceability and environmental disposal pathways alongside puncture resistance.
Corrugated fiberboard composites with liquid-resistant polymer coatings are migrating from niche European hospital networks to mainstream procurement catalogs as incineration bans spread across German and French waste jurisdictions. Municipal health authorities in the Netherlands pilot these formats for community needle exchange programs. The technology is compressing virgin plastic dependency in regions with strict post-use disposal accountability.
REACH chemical restrictions and EU MDR material documentation requirements are forcing reformulation of colorants and stabilizers in high-density polyethylene safety boxes. Manufacturers serving European Union markets now submit extended substance declarations to ECHA. Hospital procurement departments in Italy and Spain increasingly specify REACH-compliant alternatives in tender specifications.
Hospital procurement departments now bundle safety box orders with injection device contracts under single-source agreements, compressing standalone container vendor access. Group purchasing organizations in the United States consolidate specification standards across member health systems. This concentration is most visible in integrated delivery networks spanning multiple states.
Safety Box for Syringe Market Segmentation
Safety box procurement patterns diverge sharply across clinical settings, with infection control protocols, disposal infrastructure, and injection volume dictating specification requirements. Material selection and capacity sizing now determine vendor qualification thresholds in tender processes.
Product Type:
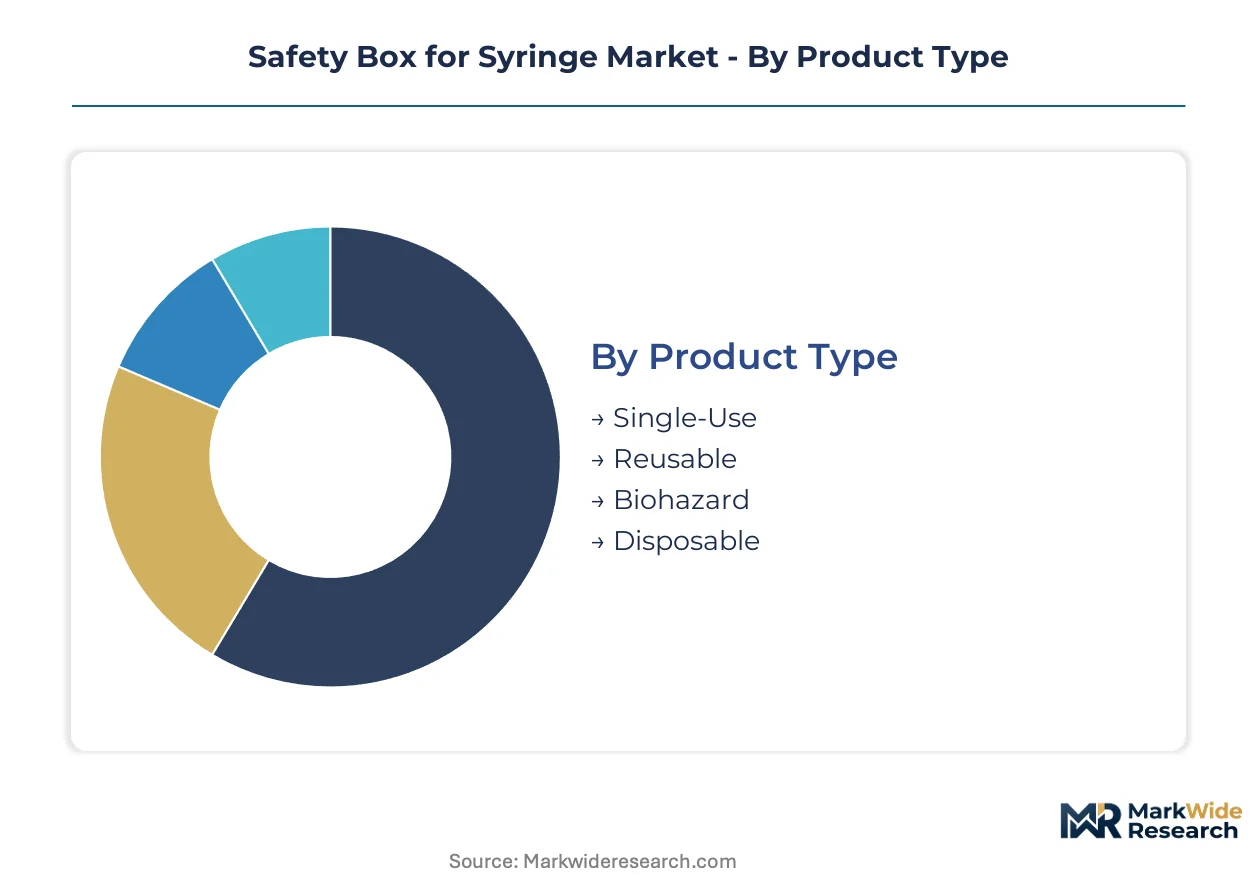
Mature formats dominate hospital procurement volumes while emerging designs address sustainability mandates and specialized containment needs.
- Single-Use:High-density polyethylene construction with one-way apertures and liquid-resistant seams prevents handler exposure in high-throughput clinical environments. Demand concentrates in United States hospital systems where OSHA Bloodborne Pathogens Standard enforcement mandates safety-engineered disposal alongside injection devices.
- Reusable:Galvanized steel shells with replaceable inner liners withstand autoclave sterilization cycles for centralized waste processing facilities. German and Dutch hospital networks accelerate adoption as incineration restrictions tighten across European Union jurisdictions.
- Biohazard:Color-coded polyethylene variants with integrated fill-line indicators serve laboratory and research settings requiring pathogen segregation protocols.
- Disposable:Lightweight fiberboard composites with polymer coatings address community needle exchange programs and decentralized immunization campaigns in India.
Single-Use handles the majority of throughput; Reusable is expanding most quickly on share as sustainability mandates intensify.
Material:
Cost tiers separate commodity procurement from premium specifications, with regulatory compliance costs widening the gap between base and certified grades.
- Plastic:Virgin and recycled high-density polyethylene variants offer puncture resistance at scale for immunization programs and hospital networks. India's national health mission drives concentrated orders for plastic-dominant formats as district hospital chains expand injection safety infrastructure.
- Metal:Galvanized steel construction supports multi-cycle sterilization and extended service life in tertiary care settings with centralized waste autoclave facilities.
- Glass:Borosilicate-lined containers serve specialized laboratory applications requiring chemical inertness and thermal stability for hazardous pharmaceutical waste.
- Composite:Corrugated fiberboard with liquid-resistant coatings gains traction in French and Italian procurement catalogs where EU Green Deal extended producer responsibility frameworks incentivize biodegradable alternatives.
Plastic commands the volume base; Composite climbs the fastest as REACH chemical restrictions and incineration bans reshape material specifications.
End User:
Customer type determines capacity requirements, with procurement authority centralizing in integrated health networks while fragmenting across decentralized care settings.
- Hospitals:High-capacity 50-unit systems with IoT-enabled fill monitoring integrate with inventory management platforms in United States integrated delivery networks. Group purchasing organizations consolidate specification standards across multi-state member systems.
- Clinics:Mid-range 20-unit formats balance throughput and storage constraints in outpatient dialysis and oncology infusion centers.
- Home Care:Compact 5-unit and 10-unit designs address underpenetrated diabetes management and self-injection therapy markets in suburban United States.
- Laboratories:Specialized biohazard-rated containers with pathogen segregation features serve research and diagnostic facilities requiring CDC-compliant disposal protocols.
Hospitals absorb the dominant procurement volume; Home Care gains share fastest as chronic disease management shifts to decentralized settings.
Capacity:
Volume segmentation aligns with injection frequency and waste collection logistics, from individual patient use to centralized high-throughput processing.
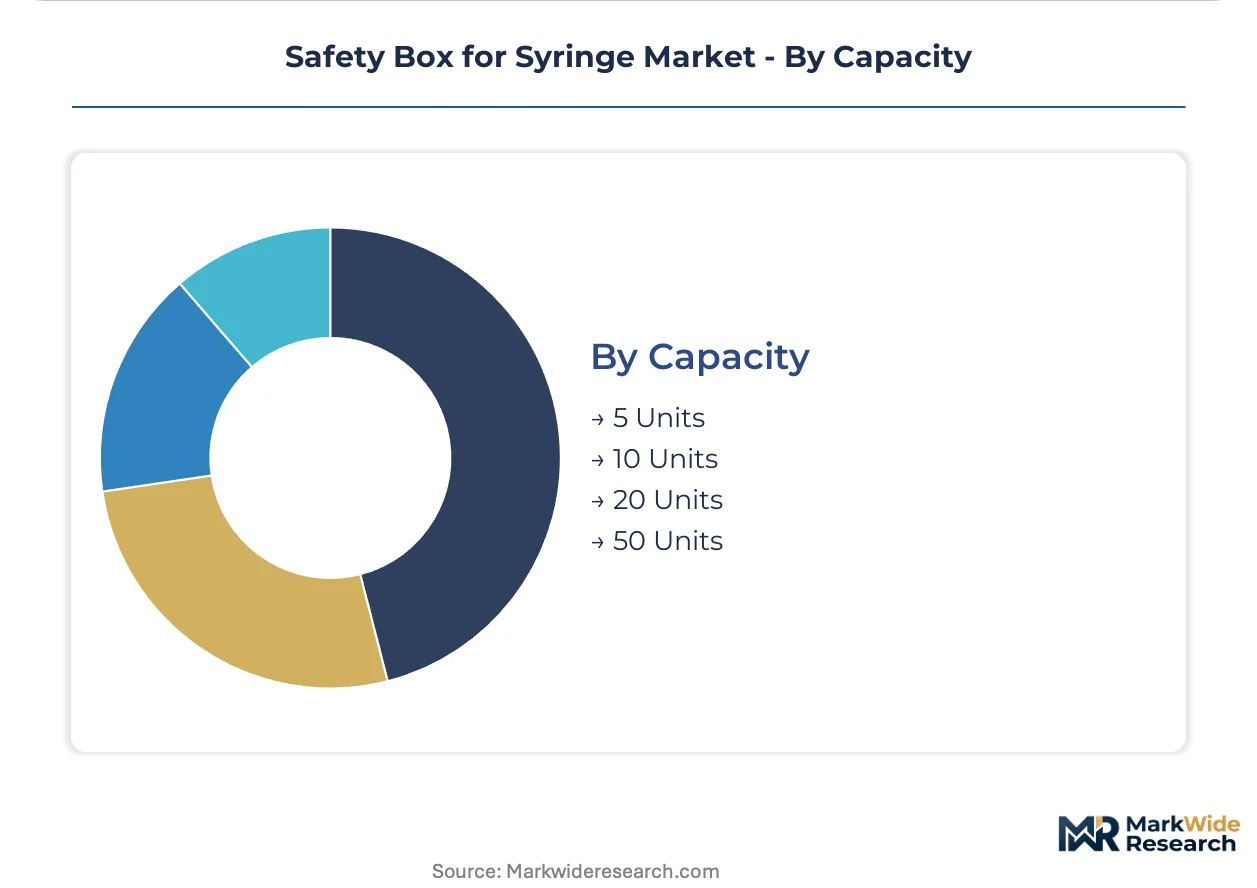
- 5 Units:Pocket-sized containers support single-patient home care regimens and travel kits for insulin-dependent diabetes management.
- 10 Units:Compact formats suit small clinic settings and community health worker field kits in India's rural immunization outreach programs.
- 20 Units:Mid-capacity designs balance storage efficiency and collection frequency in outpatient specialty clinics.
- 50 Units:High-volume systems with reinforced seams and tamper-evident closures serve emergency departments and operating theaters in tertiary hospital networks.
50 Units handles the majority of institutional throughput; 10 Units shows the steepest expansion trajectory as point-of-care delivery models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Safety box consumption patterns diverge sharply across geographies. The United States favors high-capacity single-use systems with IoT integration, while India prioritizes cost-efficient disposable formats for immunization scale-up. European procurement increasingly mandates fiber-based alternatives as incineration restrictions tighten.
United States
Hospital procurement departments drive demand for 50-unit systems with fill-monitoring sensors. OSHA Bloodborne Pathogens Standard enforcement mandates safety-engineered disposal alongside injection devices, compressing replacement cycles. Integrated delivery networks in Texas and Florida consolidate specifications through group purchasing organizations.
India
The national immunization program generates concentrated orders for 10-unit disposable formats across district hospital chains. CDSCO and BIS certification requirements govern import and domestic manufacturing compliance, extending validation timelines for entrants. Manufacturing clusters in Gujarat and Maharashtra expand domestic production capacity to serve public health networks.
Germany
Tertiary care facilities accelerate adoption of reusable galvanized steel systems with autoclave sterilization compatibility. EU Green Deal extended producer responsibility frameworks incentivize biodegradable alternatives over virgin plastic. Hospital networks in Bavaria and North Rhine-Westphalia pilot fiberboard composites for centralized waste processing.
France
REACH chemical restrictions and MDR material documentation requirements force reformulation of colorants and stabilizers in polyethylene containers. Municipal health authorities in Paris and Lyon pilot corrugated fiberboard formats for community needle exchange programs. Procurement catalogs increasingly specify REACH-compliant alternatives in tender specifications.
Netherlands
Community health programs drive demand for compact 5-unit and 10-unit formats in decentralized settings. Incineration bans across Dutch waste jurisdictions accelerate material substitution toward polymer-coated fiberboard. Municipal authorities in Amsterdam and Rotterdam integrate take-back logistics with extended producer responsibility frameworks.
Safety Box for Syringe Market Competitive Landscape
Capability concentration sits with integrated medical device conglomerates; scale advantage sits with specialized containment fabricators and sustainable packaging specialists. The vendor base stratifies across three tiers: diversified healthcare conglomerates bundling disposal with injection systems, mid-cap specialists in puncture-resistant materials, and regional converters serving public health tenders. Dominant competitive moves include strategic partnerships with group purchasing organizations and backward integration into polymer and fiberboard raw material streams.
Among diversified healthcare conglomerates, Becton Dickinson and Terumo Corporation exemplify the integrated-device archetype, leveraging hospital channel relationships to bundle sharps disposal with injection portfolios. Smurfit Kappa occupies a distinct position as a sustainable packaging specialist, anchoring the fiber-based alternative segment where EU regulatory mandates displace conventional plastics. These three entities represent the primary competitive vectors—device integration, regional manufacturing scale, and material sustainability—shaping procurement criteria across North American, Asia-Pacific, and European markets respectively.
| Leading Market Players |
|---|
| Medix Safe |
| Sanpro Wastes |
| HMD Healthcare |
| Smurfit Kappa |
| TimSafe Safety Box |
| 3M |
| Becton Dickinson |
| Terumo Corporation |
| Merck |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility in high-density polyethylene resin compresses margin structures across plastic-dominant manufacturers while simultaneously widening pricing tier spreads between virgin-grade certified containers and economy recycled variants. This input cost instability forces procurement departments toward long-term contract structures that reshape supplier-buyer relationships across hospital systems and public health networks.
Pricing Analysis
United States hospital systems command 40-60% premiums over Indian public health tenders for equivalent capacity safety boxes. Three-tier pricing structure across premium FDA-cleared, standard CE-marked, and economy BIS-certified levels separates procurement catalogs by validation stringency. Cost compression in economy tiers is intensifying as India's domestic manufacturing capacity expands to serve national immunization scale-up. Public health tenders in South Asia exhibit highest price sensitivity; integrated delivery networks in Texas and Florida demonstrate lowest sensitivity due to bundled device-contract structures.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts virgin polyethylene supply flows for North American safety box fabricators. Manufacturing concentrates in China, India, and Germany for raw material processing and finished container assembly. Raw material dependencies rest on high-density polyethylene resin, galvanized steel sheet, and liquid-resistant polymer coatings for fiberboard composites. Single-source vulnerability in specialized polymer additives for REACH compliance creates chokepoints for European market entry. Distribution runs through group purchasing organizations in the United States, centralized government procurement in India, and hospital supply cooperatives across German and Dutch networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable autoclave-sterilizable containment systems threaten single-use safety box volumes in tertiary care settings, forcing incumbents to defend substitution erosion through material innovation and service bundling.
For Market Incumbents: Build regulatory certification moats by accelerating FDA 510(k) submissions for composite material variants ahead of REACH chemical restriction expansions. Deepen backward integration into fiberboard raw material streams to capture EU Green Deal extended producer responsibility margins. Anchor hospital channel relationships through IoT-enabled fill-monitoring integration that raises switching costs for procurement departments. For New Entrants and Emerging Players: Home care diabetes management in suburban United States represents the most penetrable white-space segment for compact 5-unit and 10-unit formats. India's district hospital chains offer concentrated entry points through CDSCO-certified domestic manufacturing partnerships. Target municipal needle exchange programs in Dutch and French jurisdictions with polymer-coated fiberboard alternatives that align with incineration bans. For Investors and Strategic Acquirers: EU MDR implementation timelines reshape the acquisition landscape toward targets with established ECHA substance documentation capabilities. Five-to-ten-year viability favors specialized containment fabricators with hospital GPO relationships over commodity plastic converters. Monitor OSHA Bloodborne Pathogens Standard enforcement intensity as the signal indicating replacement cycle acceleration and contract consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Compressed premarket timelines secure first-mover positioning in composite material segments ahead of REACH expansions. |
| Backward Integration into Fiberboard | Captive supply of sustainable substrates locks in EU Green Deal compliance margins against virgin plastic competitors. |
| IoT Sensor Partnership Development | Smart fill-level integration with hospital inventory platforms raises procurement switching costs and contract stickiness. |
| CDSCO Manufacturing Certification | Domestic Indian production qualification opens public health tender access for national immunization program volumes. |
| GPO Contract Consolidation | Single-source agreements spanning multi-state integrated delivery networks compress standalone vendor market access. |
Research Methodology
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings in this study. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and public health procurement officers combined with secondary validation against FDA 510(k) clearances, ECHA substance registrations, CDSCO import approvals, and OSHA enforcement records. Bottom-up tender analysis and top-down manufacturer capacity assessment triangulate volume estimates.
Calibration against historical replacement cycles and immunization program procurement waves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-user setting, capacity tier, and regional regulatory cluster. CAGRs derive from weighted average of demand elasticity estimates and supply capacity expansion trajectories. Incineration restriction spread rates and extended producer responsibility framework adoption curves serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autoclave sterilization system manufacturers or fiberboard packaging conglomerates would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Respiratory Masks Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Forensic Swabs Market