
 Global Biohazard Bag Market | 2026-2036
Global Biohazard Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biohazard Bag Market Analysis
Project finance for sterilization infrastructure is narrowing the competitive field to operators with balance-sheet capacity for multi-year service contracts. Thermo Fisher Scientific leverages its laboratory supply chain density to bundle biohazard bags with consumables programs. Stericycle anchors its position through captive collection routes that lock in bag purchasing volumes. Daniels Health competes on reusable container systems that reduce single-bag consumption rates.
Biohazard bags are engineered containment vessels manufactured from high-density polyethylene or linear low-density polyethylene with thicknesses typically ranging from 1.5 to 3 mil, designed to isolate infectious, toxic, or genetically modified materials during storage and transport. Their primary purpose is to prevent occupational exposure and environmental release of regulated medical waste from point of generation to final treatment. Plastic bags dominate current procurement volumes across hospital systems, while specialty bags incorporating color-coded labeling and tear-resistant seams capture disproportionate margin pools in laboratory applications. Healthcare facilities represent the most mature demand channel, whereas waste disposal companies are expanding fastest as outsourcing of treatment deepens.
FDA 510(k) clearance pathways, OSHA bloodborne pathogen standards, and EU MDR technical documentation requirements collectively dictate material composition, seam integrity testing, and traceability labeling across major supply corridors. These frameworks elevate compliance costs for new entrants while insulating incumbent certifiers from price-driven competition. Stakeholders must monitor how extended producer responsibility mandates in France and Germany redirect bag specification authority from purchasers to waste treatment operators.
Market Dynamics
Extended producer responsibility mandates in France and Germany are redirecting bag specification authority from hospital purchasers to waste treatment operators, consolidating procurement decisions into fewer hands and favoring suppliers with integrated service capabilities.
Growth Catalysts
- EU MDR technical documentation:Stricter material compliance thresholds for traceability labeling are forcing healthcare facilities to upgrade containment inventories, creating replacement demand for certified biohazard bags.
- India's hospital network expansion:Rising bed capacity in tertiary care centers across Maharashtra and Karnataka is amplifying procurement volumes for infectious waste containment products.
- Color-coded LDPE formulations:Laboratory end-users are specifying tear-resistant seams and multi-ply constructions that command premium positioning in research corridor clusters.
Market Restraints
- HDPE resin price volatility:Feedstock cost swings tied to naphtha cracking margins compress converter profitability and destabilize contract pricing.
- Single-source sterilization infrastructure:Autoclave capacity concentrates in Germany's clinical research corridor around Heidelberg and Mannheim, creating geographic supply risk.
- Reusable container substitution:Rigid containment systems reduce per-procedure bag consumption rates in high-volume healthcare settings.
Strategic Opportunities
- Brazil's ANVISA compliance gap:Underpenetrated hospital networks in São Paulo and Minas Gerais lack certified containment supply chains, opening first-mover positioning for compliant exporters.
- RFID-embedded traceability:Convergence of polymer extrusion with IoT tagging enables real-time waste chain-of-custody verification for liability-sensitive generators.
- OSHA bloodborne pathogen enforcement:Intensified workplace safety inspections in US acute care facilities are accelerating specification upgrades to thicker-mil certified constructions.
Industry Challenges
- Seam integrity validation:ASTM tear-testing protocols require capital-intensive laboratory infrastructure that smaller converters struggle to fund.
- Legacy waste management software:Integration friction with hospital ERP systems delays RFID-enabled bag deployment and traceability adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biohazard Bag Market |
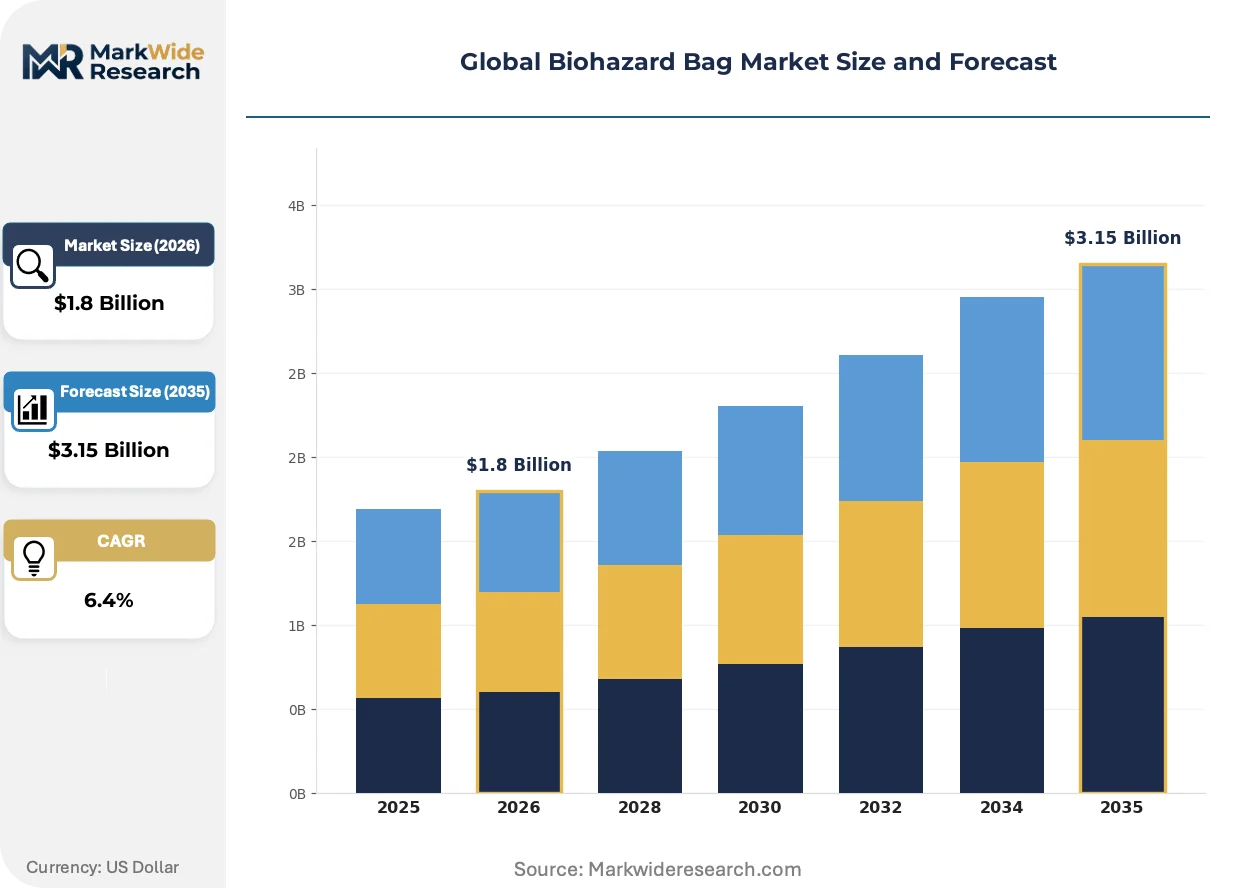
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Reusable Bags, Specialty Bags Application: Healthcare Facilities, Laboratories, Waste Management, Emergency Services End User: Hospitals, Clinics, Research Institutions, Waste Disposal Companies Certification: ISO 9001, CE Mark, FDA Approved, ASTM Standards |
| Companies Covered | Thermo Fisher Scientific, International Plastics Inc., Transcendia, SP Bel-Art, Daniels Health, Stericycle, BioMedical Waste Solutions, Dana Poly, Inc, Abdos Labtech Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biohazard Bag Market Emerging Trajectories
Digital traceability layers are embedding into physical containment products, while regulatory documentation burdens and procurement consolidation reshape how specifications flow from regulators to end-users.
RFID-tagged biohazard bags are virtualizing chain-of-custody documentation for infectious waste streams. Academic medical centers in the US are piloting these systems to automate compliance reporting. The technology is virtualizing manual logbook processes and compressing audit preparation cycles from weeks to hours.
France's extended producer responsibility framework now assigns financial liability for safe disposal to bag manufacturers rather than healthcare purchasers. This reallocates specification authority toward waste treatment operators with captive collection networks. German clinical research facilities are responding by consolidating vendors into multi-year service contracts bundling bags with logistics.
Hospital systems are compressing supplier rosters from fragmented regional distributors to national distributors with direct manufacturer relationships. This channel consolidation displaces independent medical supply houses in secondary markets. The pattern is most visible in India's corporate hospital chains, where centralized procurement desks now mandate direct sourcing from certified converters.
Global Biohazard Bag Market Segmentation
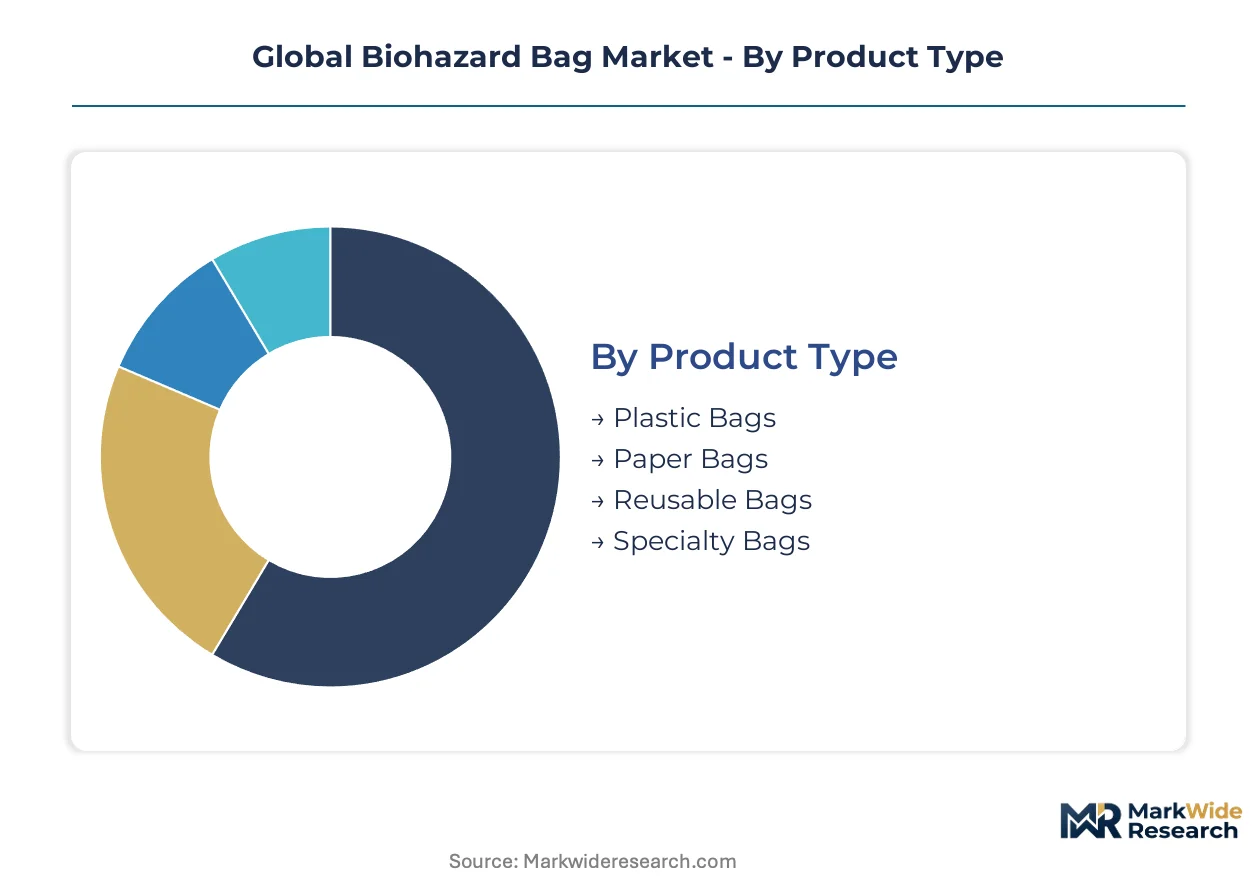
Biohazard bag procurement varies sharply by containment durability requirements and regulatory exposure. Material specifications and certification tiers fragment supplier margins across use cases from routine clinical waste to high-containment laboratory protocols.
Product Type:
Product selection tracks the tension between single-use convenience and total cost of containment across infection risk tiers.
- Plastic Bags:High-density polyethylene or linear low-density polyethylene constructions dominate hospital procurement with thicknesses from 1.5 to 3 mil. Demand concentrates in India's expanding tertiary care networks in Maharashtra and Karnataka where OSHA-aligned standards are tightening material specifications.
- Specialty Bags:Multi-ply laminates with color-coded labeling and tear-resistant seams serve laboratory containment protocols. Germany's clinical research corridor around Heidelberg and Mannheim drives premium positioning for genetically modified material handling.
- Paper Bags:Kraft-based biodegradable alternatives target incineration-compatible waste streams with lower liquid exposure risk.
- Reusable Bags:Rigid polymer containers reduce per-procedure consumption in high-volume surgical settings.
The dominant share belongs to Plastic Bags, while Specialty Bags is closing the gap fastest.
Application:
Application segmentation reflects divergent chain-of-custody requirements from point-of-generation to final treatment.
- Healthcare Facilities:Acute care hospitals generate the largest procurement volumes for infectious waste containment. India's corporate hospital chains are consolidating supplier rosters from regional distributors to direct manufacturer relationships.
- Laboratories:Research institutions specify ASTM-tested seam integrity for genetically modified organism protocols. EU MDR technical documentation requirements are forcing inventory upgrades in Germany's academic medical centers.
- Waste Management:Outsourced treatment operators in France now control bag specifications under extended producer responsibility mandates.
- Emergency Services:Field-deployable containment for trauma and mass casualty incidents demands rapid-seal mechanisms.
Healthcare Facilities maintains volume leadership, though Waste Management is expanding most quickly as outsourcing deepens.
End User:
End-user concentration shapes pricing leverage and contract structure across the procurement landscape.
- Hospitals:Multi-bed facilities with captive sterilization infrastructure anchor demand for certified high-mil constructions. OSHA bloodborne pathogen enforcement in US acute care settings is accelerating specification upgrades.
- Waste Disposal Companies:Integrated operators with captive collection routes lock in multi-year service contracts bundling logistics with bag supply. France and Germany's extended producer responsibility frameworks consolidate procurement authority with this segment.
- Clinics:Outpatient facilities prioritize cost-optimized standard-mil bags for lower-risk waste streams.
- Research Institutions:Academic laboratories specify tear-resistant multi-ply bags for liability-sensitive genetically modified material handling.
Hospitals command the largest procurement volumes, while Waste Disposal Companies is gaining share fastest through vertical service integration.
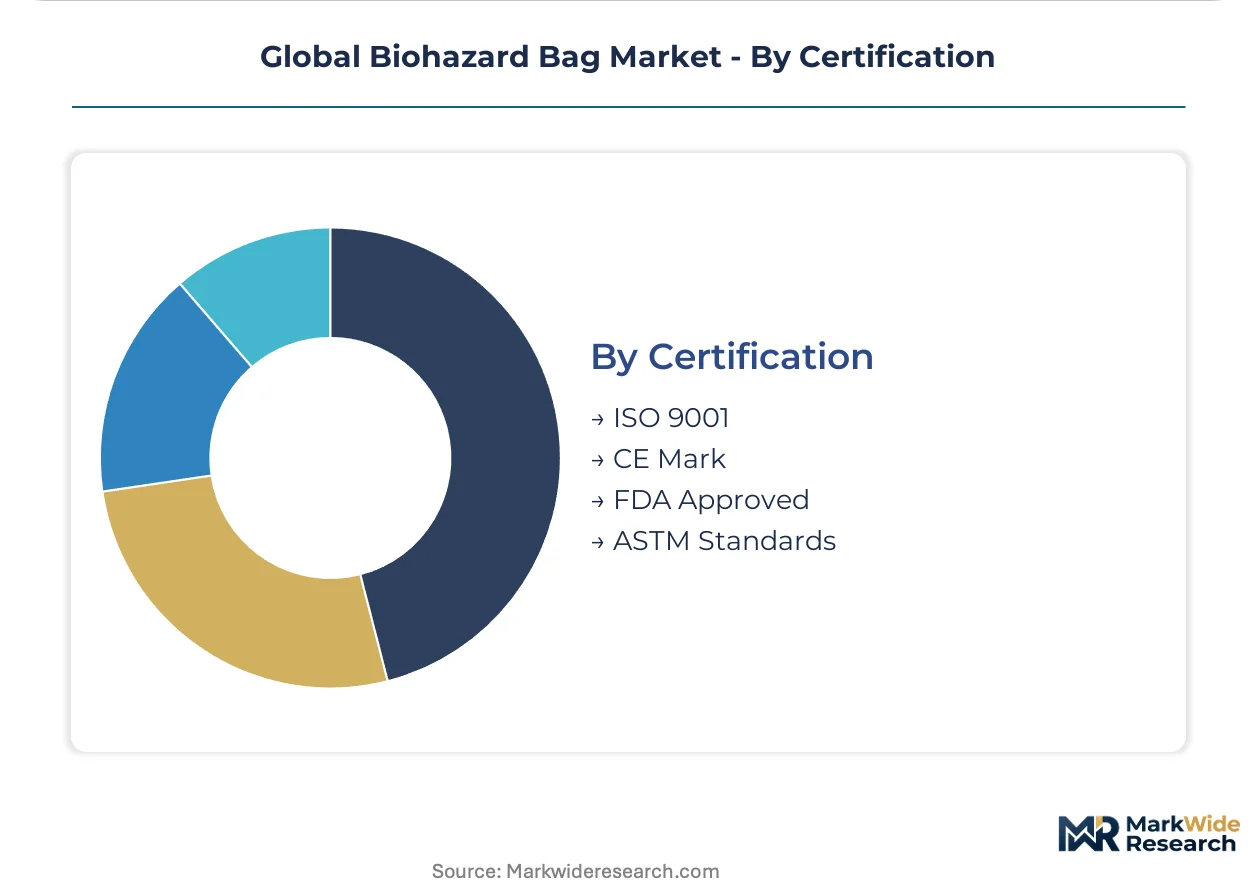
Certification:
Certification tiers create compliance moats that insulate incumbent suppliers from price-driven competition.
- FDA Approved:510(k) clearance pathways dictate material composition and seam integrity testing for US market entry. Enforcement intensity in acute care facilities is thickening specification requirements.
- CE Mark:EU MDR technical documentation requirements elevate traceability labeling standards across European supply corridors. German clinical research facilities are responding with multi-year vendor consolidation.
- ISO 9001:Quality management certification provides baseline supplier qualification for hospital procurement desks.
- ASTM Standards:Tear-testing protocols require capital-intensive laboratory infrastructure that smaller converters struggle to fund.
FDA Approved holds the strongest position in North American procurement, while CE Mark is tightening its grip fastest through EU MDR implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement desks in India, Germany, and the United States concentrate the largest certified containment purchasing volumes. Waste treatment operators in France and Brazil are consolidating specification authority through extended producer responsibility frameworks and compliance gap exploitation.
United States
OSHA bloodborne pathogen enforcement in acute care facilities is accelerating specification upgrades to thicker-mil certified constructions. FDA 510(k) clearance pathways dictate material composition and seam integrity testing for domestic market entry. The Southeast hospital corridor spanning Florida and Georgia anchors procurement volume for infectious waste containment products.
Germany
EU MDR technical documentation requirements are forcing inventory upgrades in academic medical centers across Baden-Württemberg. Extended producer responsibility mandates redirect bag specification authority from hospital purchasers to waste treatment operators. The clinical research corridor around Heidelberg and Mannheim drives premium positioning for genetically modified material handling protocols.
India
Rising bed capacity in tertiary care centers across Maharashtra and Karnataka is amplifying procurement volumes for infectious waste containment products. CDSCO medical device regulations are tightening material compliance thresholds for imported containment products. Corporate hospital chains in Delhi-NCR and Mumbai are consolidating supplier rosters from regional distributors to direct manufacturer relationships.
France
Extended producer responsibility frameworks now assign financial liability for safe disposal to bag manufacturers rather than healthcare purchasers. ANSM medical device oversight coordinates with waste management regulators on containment traceability requirements. The Île-de-France hospital network is consolidating vendors into multi-year service contracts bundling bags with logistics.
Brazil
Underpenetrated hospital networks in São Paulo and Minas Gerais lack certified containment supply chains, opening first-mover positioning for compliant exporters. ANVISA medical device regulations are tightening import documentation requirements for infectious waste products. The São Paulo metropolitan health system is accelerating procurement standardization for tertiary care expansion.
Global Biohazard Bag Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement authority with integrated waste operators and laboratory supply chains. The vendor base organizes around three strategic archetypes: integrated service providers with captive collection networks, laboratory supply bundlers leveraging consumables density, and certified converters with direct hospital relationships. Dominant competitive moves include multi-year service contract expansion and RFID-enabled traceability integration.
Among integrated service providers, Stericycle and Daniels Health exemplify the channel-control archetype through waste logistics bundling. Thermo Fisher Scientific occupies a position within the laboratory supply bundler tier, leveraging consumables program density. These three companies represent the competitive vectors shaping procurement consolidation: vertical service integration, supply chain bundling, and certified direct sourcing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| International Plastics Inc. |
| Transcendia |
| SP Bel-Art |
| Daniels Health |
| Stericycle |
| BioMedical Waste Solutions |
| Dana Poly, Inc |
| Abdos Labtech Private Limited |
| Others |
Supply Flow & Price Mechanics
HDPE resin price volatility tied to naphtha cracking margins compresses converter profitability and simultaneously fragments supply chain resilience, forcing buyers to absorb cost pass-throughs in premium tiers while standard-mil procurement faces destabilized contract pricing.
Pricing Analysis
Cost-plus contracts indexed to polyethylene resin benchmarks dominate hospital procurement, with three-tier pricing structure across premium, standard, and economy levels separating FDA-cleared multi-ply constructions from uncertified imports. Price differentiation hinges on certification grade and volume scale, with integrated waste operators locking in multi-year service contracts at favorable rates. Cost compression in standard-mil segments is intensifying because smaller converters lack balance-sheet capacity to hedge resin exposure. Clinics exhibit highest price sensitivity, while academic medical centers prioritize liability protection over unit cost.
Supply Chain Analysis
Extended payment terms from hospital procurement desks and supply-chain finance facilities strain converter working capital, particularly for mid-tier manufacturers serving India's expanding tertiary care networks. Raw material sourcing concentrates in Saudi Arabia, South Korea, and the US Gulf Coast for virgin HDPE resin, with color-masterbatch additives drawing from Germany and China. Single-source sterilization infrastructure in Germany's Heidelberg-Mannheim corridor creates geographic chokepoint risk. Distribution runs through national medical supply distributors with direct manufacturer relationships, displacing fragmented regional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where certification burdens and captive collection networks create switching costs that insulate incumbents from price-driven competition.
For Market Incumbents: Harden compliance infrastructure against EU MDR documentation requirements and OSHA enforcement intensification to maintain specification authority. Expand autoclave partnerships in Germany's clinical research corridor to secure sterilization capacity. Invest in RFID-embedded traceability systems to lock in multi-year service contracts with liability-sensitive generators. For New Entrants and Emerging Players: Establish a beachhead in Brazil's São Paulo metropolitan health system by securing ANVISA import documentation ahead of tertiary care expansion. Target underpenetrated hospital networks in Minas Gerais lacking certified containment supply chains. Lead with compliant export positioning rather than price competition to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape toward converters with existing technical documentation capabilities and direct hospital relationships. Five-to-ten year viability favors certified manufacturers with captive sterilization partnerships over commodity resin converters. Monitor ANVISA enforcement intensity in Brazil as the signal for first-mover window closure.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | FDA 510(k) clearance and CE Marking pathways insulate margins from uncertified import competition. |
| RFID Traceability Integration | Real-time chain-of-custody verification compresses audit cycles and locks in multi-year hospital contracts. |
| Backward Integration into Resin Hedging | Direct polyethylene supply agreements with Saudi and US Gulf producers stabilize converter cost structures. |
| Captive Sterilization Partnership | Autoclave capacity commitments in Germany's Heidelberg-Mannheim corridor secure geographic supply priority. |
| Extended Producer Responsibility Alignment | Service bundling with waste treatment operators in France and Germany consolidates procurement authority. |
Methodological Framework
Operator-level perspectives from hospital procurement managers, biomedical waste coordinators, GPO contracts managers, and polymer converter sales directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO medical device registrations, and hospital supply chain disclosures. Bottom-up procurement volume estimates triangulated against top-down resin consumption data from customs and trade sources.
Scenario-bracketing around resin price volatility, regulatory enforcement intensity, and hospital network expansion rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application tier, end-user concentration, and certification grade. CAGRs derived from weighted average of historical procurement trajectories and capacity expansion pipelines. Industry-specific inputs incorporated autoclave utilization rates and extended producer responsibility mandate implementation timelines.
Sensitivities concentrate around naphtha cracking margin volatility, EU MDR documentation compliance costs, and ANVISA enforcement acceleration in Brazil. Forecasts reflect documented assumptions on hospital bed expansion and outsourcing penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Human Acellular Dermis Market
Medical Supplies
Global Needles Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Blood Glucose Test Strip Packaging Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Breast Shells Market
Medical Supplies
Specimen Transport Bags Market