
 Face Mask Market | 2026-2036
Face Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Face Mask Market Intelligence
N95-grade filtration certification is unwinding commodity pricing across the face mask landscape. 3M leverages its proprietary electrostatic media technology to sustain premium positioning in industrial and healthcare channels. Honeywell International Inc. anchors North American supply security through domestic melt-blown polypropylene production. Kimberly-Clark Corporation differentiates via hospital-focused distribution control and private-label surgical mask portfolios.
A face mask is a barrier device worn over the nose and mouth, typically constructed from multi-layer melt-blown polypropylene or woven cotton with filtration efficiencies measured against ASTM F2100 or EN 14683 standards, designed to block particulate matter, pathogens, or aerosols in occupational, clinical, and consumer environments. Surgical masks and N95 respirators dominate hospital procurement budgets with mature margin pools, while cloth masks face demand compression as institutional buyers prioritize certified disposable options. Material segmentation reveals polypropylene's grip on medical-grade output, though cotton retains consumer skincare adjacencies through beauty-oriented sheet masks sold via online retail and pharmacy channels.
The U.S. FDA enforces 510(k) clearance for surgical masks and NIOSH certification for N95 respirators, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable barrier devices. China's NMPA and SAMR coordinate national standards for disposable medical masks under GB 19083, directly shaping export eligibility for domestic manufacturers. Stakeholders must monitor divergence between regional filtration benchmarks and emerging material sustainability mandates as the primary vectors of competitive risk and product redesign obligation.
Market Dynamics
Filtration certification divergence between N95-grade respirators and commodity surgical masks is restructuring procurement hierarchies across healthcare and industrial channels. Manufacturers now face simultaneous pressure from tightening FDA 510(k) pathways and China's GB 19083 export eligibility requirements.
Growth Catalysts
- NIOSH Certification Expansion:U.S. hospital systems are mandating N95-grade protection for aerosol-generating procedures, elevating respirator procurement above commodity mask purchasing.
- Industrial Hygiene Mandates:OSHA's updated permissible exposure limits for silica and particulate matter are forcing construction and manufacturing employers to upgrade from basic dust masks to certified respirators.
- Melt-Blown Capacity Concentration:China's Zhejiang and Guangdong provinces now host over sixty percent of global polypropylene microfiber production, enabling export-scale cost advantages for domestic manufacturers.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer prices tied to naphtha cracking margins create margin compression for mask producers without backward integration into petrochemical supply.
- Single-Source Geography Risk:Concentration of electrostatic charging equipment and melt-blown die manufacturing in Germany and Japan creates bottleneck vulnerability for new market entrants.
- Reuse Protocol Limitations:Current FDA guidance restricts N95 decontamination cycles to limited methods, constraining hospital budget relief from extended-use strategies.
Strategic Opportunities
- India Preventive Health Infrastructure:The country's PLI scheme for medical textiles offers twenty-five percent incentive on incremental sales for domestic mask manufacturing capacity.
- Biodegradable Filter Media:Convergence of polylactic acid biopolymers with electrospinning technology opens certification pathways for single-use masks under EU Green Deal circular economy mandates.
- Direct Hospital Contracting:Bypassing distributor markups through GPO-negotiated direct sourcing agreements is capturing procurement officers seeking supply security post-pandemic.
Industry Challenges
- Electrostatic Media Engineering Talent:Scarcity of specialists capable of optimizing charge retention in melt-blown polypropylene limits R&D velocity for filtration efficiency improvements.
- 510(k) Submission Timelines:FDA review periods for novel respirator designs now extend eighteen to twenty-four months, delaying revenue recognition for product pipeline investments.
- Legacy ERP Integration:Hospital procurement systems built on outdated platforms struggle to track lot-level traceability required under EU MDR Article 27 device identification rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Mask Market |
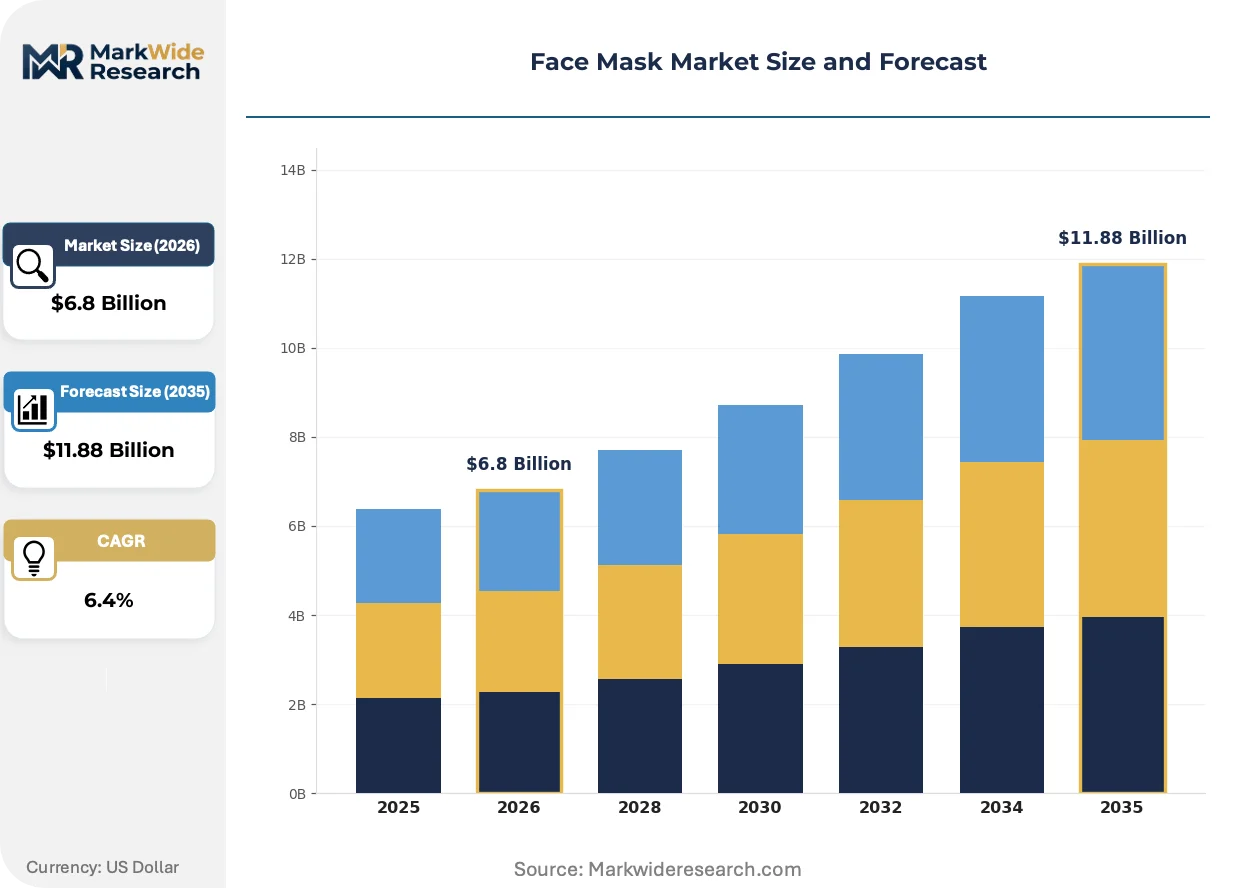
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical, N95, Cloth, Disposable Material: Polypropylene, Cotton, Polyester, Silk End User: Healthcare Providers, Retail Customers, Manufacturing Workers, General Public Distribution Channel: Online Retail, Pharmacies, Hospitals, Supermarkets |
| Companies Covered | 3M, Honeywell International Inc., Kimberly-Clark Corporation, L'Oréal, Procter & Gamble, Estée Lauder, Cardinal Health Inc., DuPont, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Mask Market Strategic Shifts & Innovations
Active filtration media innovation and regulatory harmonization efforts are compressing product lifecycles while opening new certification categories. Material science advances and procurement digitization are simultaneously reshaping manufacturing economics and distribution pathways.
Electrospun nanofiber membranes are displacing conventional melt-blown polypropylene in premium respirator segments. German industrial safety officers are specifying these materials for chemical processing environments where oil-based aerosol exposure demands higher filtration efficiency. The technology is displacing commodity-grade N95s in European occupational health budgets by extending service intervals and reducing fit-test failure rates.
The EU Medical Device Regulation's 2021 implementation is forcing reusable barrier device manufacturers to submit clinical evidence packages previously exempt under the Medical Device Directive. French and Italian mask producers are restructuring quality management systems to meet Annex XIV post-market surveillance requirements. Surgical mask importers into the European Economic Area now face notified body audits that add twelve to eighteen months to market entry timelines.
Hospital procurement officers are consolidating supplier relationships around vertically integrated manufacturers capable of lot-level traceability and surge capacity guarantees. Group purchasing organizations in the U.S. Southeast are awarding multi-year sole-source contracts to domestic producers with captive melt-blown capacity. This concentration is most visible in Texas and Florida health systems that experienced severe supply disruption during 2020-2021 demand spikes.
Face Mask Market Segmentation
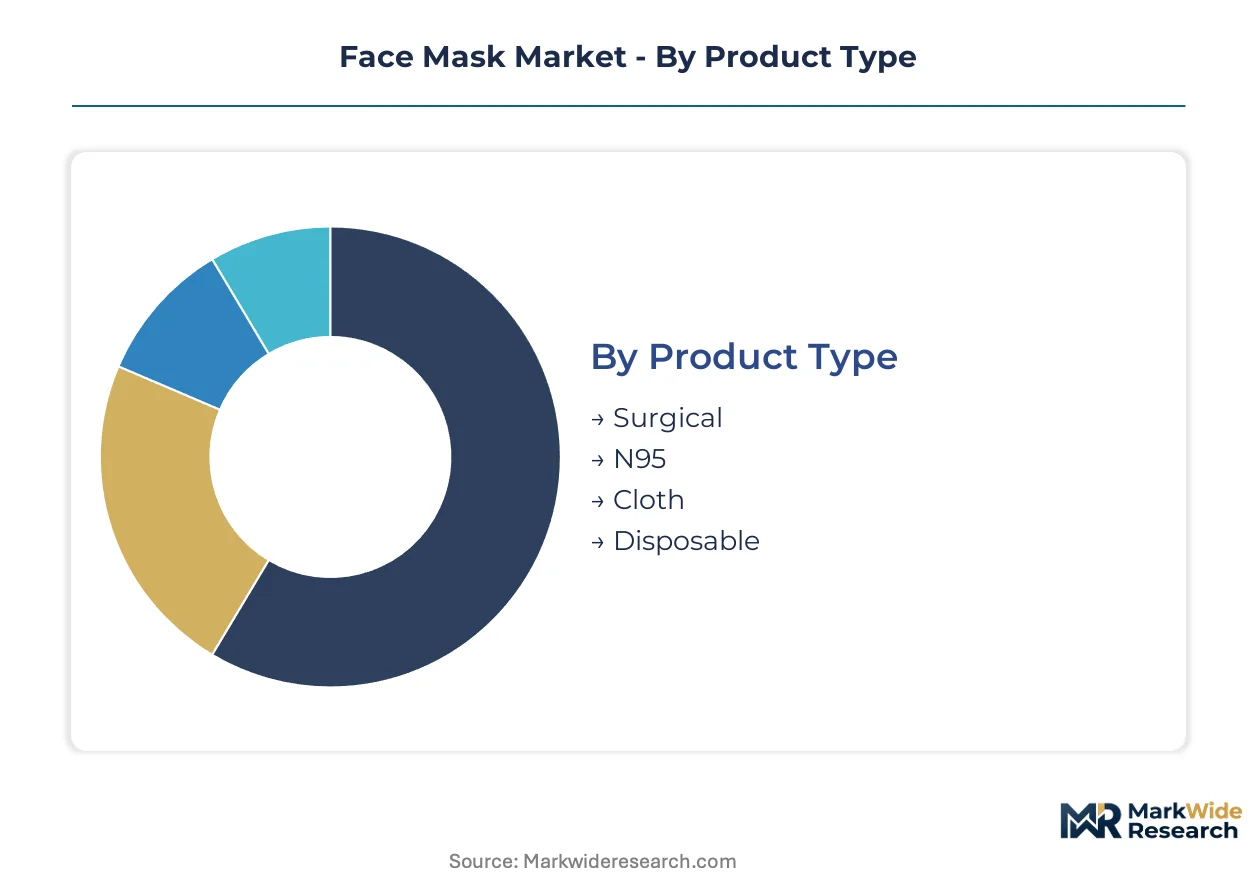
Segmentation in the face mask market determines procurement hierarchies and margin structures across institutional and consumer channels. Material composition and certification grade dictate which products flow through hospital supply chains versus retail shelf placement.
Product Type:
Hospital procurement officers source N95 and surgical masks through GPO-negotiated contracts, while retail channels carry cloth and disposable options for consumer self-selection.
- Surgical:Multi-layer melt-blown polypropylene construction meeting ASTM F2100 Level 1-3 standards. Hospital systems in Texas and Florida are consolidating sole-source contracts around domestic manufacturers with captive melt-blown capacity following pandemic supply disruptions.
- N95:Electrostatically charged polypropylene microfiber media requiring NIOSH certification for occupational use. OSHA's updated silica exposure limits are forcing construction employers to upgrade from basic dust masks, elevating respirator procurement above commodity purchasing.
- Cloth:Woven cotton or blended fabric barriers without standardized filtration certification, positioned primarily through online retail and pharmacy channels for consumer skincare and fashion adjacencies.
- Disposable:Single-use non-woven polypropylene masks for general public and light industrial applications, distributed through supermarkets and pharmacy chains.
By volume, disposable masks lead. By growth pace, N95 respirators are climbing the fastest.
Material:
Cost tiers separate medical-grade outputs from consumer-oriented alternatives, with feedstock integration determining competitive positioning.
- Polypropylene:Melt-blown microfiber media with electrostatic charge retention for N95 and surgical filtration. China's Zhejiang and Guangdong provinces concentrate over sixty percent of global production capacity, enabling export-scale cost advantages.
- Cotton:Natural fiber woven construction for reusable consumer masks and beauty-oriented sheet masks. Domestic Indian textile mills are expanding output under the PLI scheme for medical textiles.
- Polyester:Synthetic woven or non-woven substrates for industrial dust masks and consumer fashion applications.
- Silk:Premium natural fiber positioned for skincare-conscious consumers through online retail and specialty pharmacy channels.
Polypropylene dominates hospital procurement budgets. Silk is gaining share fastest among premium consumer segments.
End User:
Application requirements drive specification divergence between clinical protection and occupational safety standards.
- Healthcare Providers:Hospitals and clinics mandating N95-grade protection for aerosol-generating procedures under FDA 510(k) and EU MDR requirements. Procurement concentrates around vertically integrated manufacturers with lot-level traceability.
- Retail Customers:Individual consumers purchasing through online retail and pharmacy channels, prioritizing comfort and aesthetics over certification.
- Manufacturing Workers:Industrial employers responding to OSHA permissible exposure limit updates for silica and particulate matter.
- General Public:Mass-market consumers sourcing disposable and cloth masks through supermarkets and online retail for everyday use.
Healthcare providers command the highest unit economics. Manufacturing workers represent the steepest expansion trajectory as industrial hygiene mandates tighten.
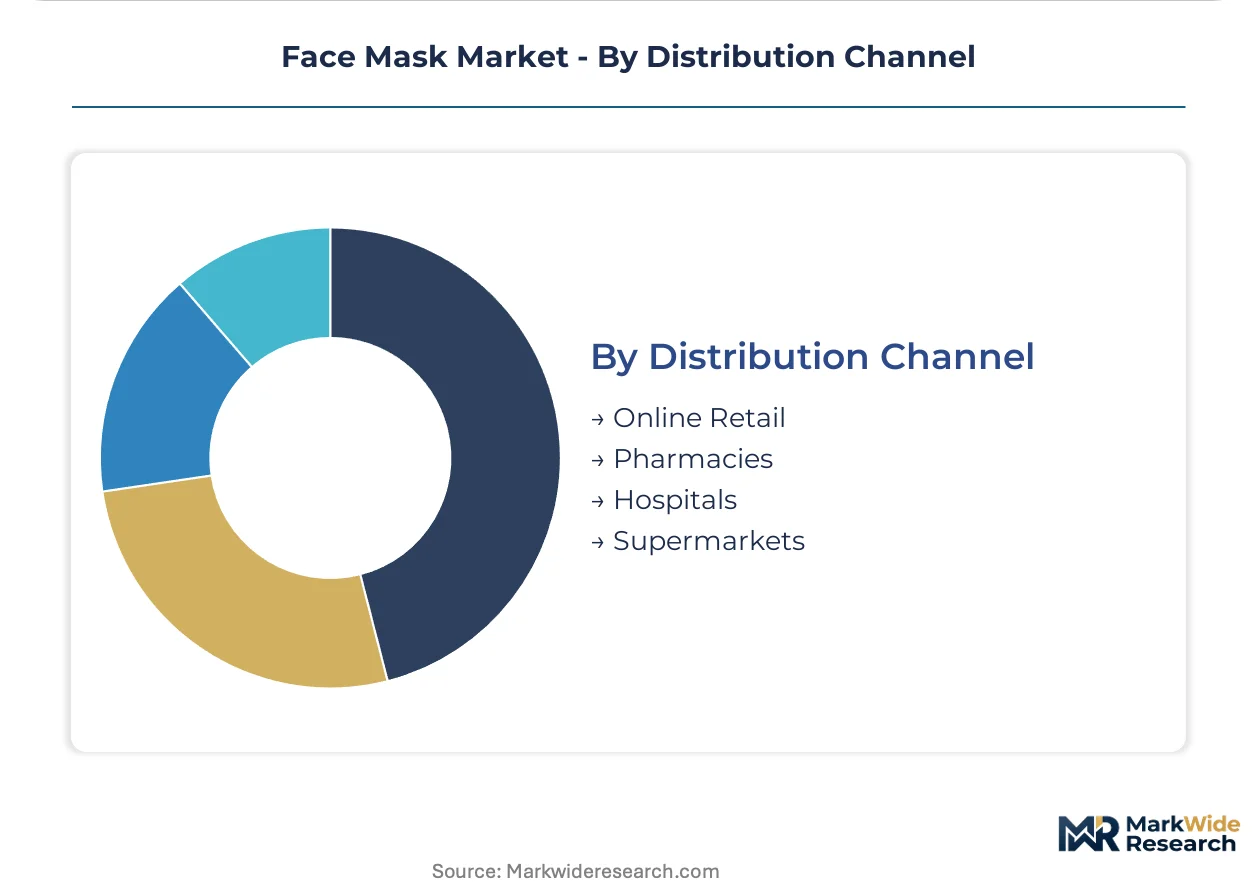
Distribution Channel:
Channel selection determines margin capture and supply security guarantees for institutional buyers versus convenience access for consumers.
- Online Retail:E-commerce platforms serving consumer segments with cloth masks and beauty-oriented sheet masks, bypassing traditional pharmacy distribution.
- Pharmacies:Brick-and-mortar and omnichannel drugstore chains stocking disposable masks and limited surgical options for walk-in demand.
- Hospitals:Direct contracting and GPO-negotiated supply agreements for N95 respirators and surgical masks with lot-level traceability requirements.
- Supermarkets:Mass-market retail chains carrying disposable mask SKUs for convenience purchasing by general public segments.
Supermarkets move the highest unit volumes. Hospital direct contracting is expanding most quickly as procurement officers prioritize supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export capacity from China's Zhejiang and Guangdong provinces dominates global supply flows, while import demand concentrates in hospital systems across the United States, Germany, and India. Regulatory divergence between FDA 510(k) pathways and EU MDR certification timelines is fragmenting trade corridors. Domestic manufacturing incentives in India and Brazil are reshaping regional self-sufficiency trajectories.
United States
Hospital procurement officers in Texas and Florida health systems are consolidating sole-source contracts around domestic melt-blown polypropylene producers following severe supply disruption during 2020-2021 demand spikes. OSHA's updated permissible exposure limits for silica are forcing construction employers to upgrade from basic dust masks to NIOSH-certified N95 respirators. The FDA enforces 510(k) clearance for surgical masks and eighteen-to-twenty-four-month review timelines for novel respirator designs.
China
Domestic manufacturers in Zhejiang and Guangdong provinces now host over sixty percent of global melt-blown polypropylene microfiber production, enabling export-scale cost advantages. The NMPA and SAMR coordinate national standards for disposable medical masks under GB 19083, directly shaping export eligibility. Electrostatic charging equipment and melt-blown die manufacturing concentrate in Germany and Japan, creating import dependency for precision components.
Germany
Industrial safety officers in chemical processing environments are specifying electrospun nanofiber membranes for oil-based aerosol exposure applications. The EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable barrier devices than the preceding Medical Device Directive. French and Italian mask producers are restructuring quality management systems to meet Annex XIV post-market surveillance requirements, with notified body audits adding twelve to eighteen months to market entry.
India
The PLI scheme for medical textiles offers twenty-five percent incentive on incremental sales for domestic mask manufacturing capacity expansion. Domestic textile mills in Tamil Nadu and Gujarat are expanding cotton and polypropylene output to capture hospital procurement budgets. CDSCO alignment with international filtration standards is accelerating as importers face EU MDR-equivalent evidence requirements for high-risk device categories.
Brazil
ANVISA is tightening import registration requirements for surgical masks and respirators to stimulate domestic production investment. São Paulo-based health system procurement is shifting from distributor-reliant sourcing to direct manufacturer contracting for supply security. Construction sector employers in Rio de Janeiro and Minas Gerais are responding to updated occupational exposure limits with certified respiratory protection mandates.
Face Mask Market Key Industry Players
Concentration sits with diversified industrial conglomerates possessing captive melt-blown capacity and established hospital distribution networks. Three to five multinational holdings command premium-tier positioning through proprietary electrostatic media technology and NIOSH certification portfolios. Mid-scale regional fabricators compete on price for commodity surgical mask contracts. Dominant competitive moves include backward integration into petrochemical feedstock supply and multi-year sole-source contracting with group purchasing organizations.
Among diversified industrial holdings, 3M and Honeywell International Inc. exemplify archetypes combining proprietary filtration media with occupational safety channel penetration. Kimberly-Clark Corporation occupies a position emphasizing hospital-focused distribution control. L'Oréal and Estée Lauder represent consumer-facing specialists leveraging beauty-oriented sheet mask positioning through online retail and pharmacy channels. Cardinal Health Inc. anchors healthcare supply chain intermediation. DuPont exemplifies material science upstream positioning for non-woven substrate supply.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Kimberly-Clark Corporation |
| L'Oréal |
| Procter & Gamble |
| Estée Lauder |
| Cardinal Health Inc. |
| DuPont |
| Unilever |
| Others |
Cost & Logistics Intelligence
NIOSH certification requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified producers while enabling premium capture by electrostatic media specialists serving hospital systems and industrial employers.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across premium, standard, and economy tiers. Three-tier pricing structure separates N95 respirators with electrostatic charge retention from commodity surgical masks and unbranded disposable options. Cost compression in the surgical tier intensifies because China's Zhejiang and Guangdong manufacturers leverage captive melt-blown capacity. General public consumers demonstrate highest price sensitivity, while hospital procurement officers prioritize lot-level traceability over unit cost.
Supply Chain Analysis
Inventory buffers for electrostatic charging equipment stretch twelve to eighteen months due to German and Japanese manufacturing concentration. Melt-blown polypropylene microfiber supply centers on China, with secondary capacity in the United States and India expanding under PLI incentives. Feedstock draws from propylene monomer streams tethered to naphtha cracking economics. Single-source geography risk concentrates in precision die manufacturing. Distribution runs through group purchasing organizations for hospital systems and direct manufacturer contracting for industrial employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Face mask demand cycles with pandemic preparedness funding waves and OSHA regulatory refresh intervals, creating recoverable troughs for positioned suppliers.
For Market Incumbents: Shield margin pools by deepening backward integration into petrochemical feedstock supply and securing multi-year sole-source GPO contracts with Texas and Florida health systems. Electrospun nanofiber substitutes threaten conventional melt-blown positioning in European chemical processing channels. Certification investment in biodegradable filter media opens EU Green Deal procurement pathways. For New Entrants and Emerging Players: Lead with India's PLI scheme for medical textiles, where twenty-five percent incremental sales incentives reduce capital barriers for domestic polypropylene output. Biodegradable single-use masks for EU circular economy mandates represent the most penetrable white-space. Direct hospital contracting bypasses distributor markups and captures procurement officers prioritizing supply security. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrospinning equipment manufacturing as Chinese suppliers enter precision component markets. Long-term viability favors vertically integrated holdings with captive melt-blown capacity and NIOSH certification portfolios. Watch FDA 510(k) submission backlogs as inflection indicator for revenue recognition delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstock | Captive propylene supply insulates margin compression from naphtha cracking volatility. |
| Biodegradable Filter Media Certification | Polylactic acid electrospinning aligns with EU Green Deal circular economy procurement mandates. |
| Direct Hospital GPO Contracting | Sole-source agreements with Texas and Florida systems lock out distributor-reliant competitors. |
| Electrostatic Media Engineering Talent Acquisition | Scarce charge-retention specialists accelerate R&D velocity for filtration efficiency gains. |
| India PLI Scheme Capacity Expansion | Twenty-five percent incentive on incremental sales reduces payback period for domestic melt-blown investment. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement officers, industrial safety managers, melt-blown equipment engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, NIOSH certification databases, EU MDR notified body audit records, and customs trade data. Bottom-up capacity modeling across Zhejiang and Guangdong provinces triangulated with top-down hospital expenditure tracking.
Variance decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include product type, material composition, end-user application, and distribution channel complexity. CAGRs derive from installed base attrition rates and replacement cycle analysis. Forecast inputs incorporate OSHA permissible exposure limit enforcement trajectories and EU MDR Annex XIV surveillance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained NIOSH certification validity and propylene feedstock price stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and hospital procurement system digitization rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Liners Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Super Absorbent Dressings Market