
 Enteral Syringes Market | 2026-2036
Enteral Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Enteral Syringes Market Foresight
Integrated ENFit connector standardization is rewriting how enteral syringes interface with feeding systems, forcing redesigns across legacy product lines. B. Braun Melsungen AG leverages its European manufacturing footprint to sustain ENFit-compliant output at scale. Baxter International Inc. anchors North American hospital contracts through dedicated enteral nutrition portfolios. Terumo Corporation differentiates via precision molding capabilities that reduce connector tolerance failures.
Enteral syringes are specialized medical devices designed for the controlled delivery of liquid nutrition, medication, or fluids directly into the gastrointestinal tract through feeding tubes, typically constructed from medical-grade polypropylene or silicone with graduated barrel markings for dose accuracy and ENFit-compatible tips to prevent misconnection with intravenous lines. Their primary purpose is to ensure safe, accurate enteral administration in patients unable to consume food orally due to surgery, neurological impairment, or critical illness. Single-use syringes dominate hospital procurement due to infection control mandates, while reusable variants retain niche positions in cost-constrained long-term care facilities. Home care end users represent the fastest-expanding segment as discharge protocols shift toward outpatient enteral management. Plastic and polypropylene materials command the largest material share owing to sterilization compatibility and unit economics.
The FDA enforces enteral connector standards through its participation in ISO 80369-3, while the EMA coordinates with national competent authorities to align European device safety requirements. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for enteral feeding accessories, elevating compliance costs for smaller manufacturers. Stakeholders must monitor evolving connector standard harmonization between FDA and EU frameworks to anticipate redesign cycles and inventory transitions.
Market Dynamics
ENFit connector standardization is forcing comprehensive product redesigns across enteral syringe portfolios, eliminating legacy Luer-compatible inventory and compressing manufacturing timelines for compliant replacements.
Growth Catalysts
- ISO 80369-3 harmonization:The FDA's adoption of this international connector standard creates unified design specifications that reduce regional SKU complexity and accelerate cross-border distribution.
- Home care protocols:Discharge planning departments at major hospital systems are embedding enteral feeding training into outpatient handoff procedures, expanding addressable volume beyond acute settings.
- Polypropylene sterilization compatibility:Steam and gamma sterilization resilience enables single-use economics at scale while satisfying infection control mandates in surgical wards.
Market Restraints
- Medical-grade resin cost volatility:Polypropylene feedstock prices fluctuate with propylene monomer supply from Gulf Coast petrochemical complexes, squeezing margin predictability for molded component suppliers.
- Tooling concentration in German precision mold shops:ENFit-compliant connector cavities require tight tolerance machining that clusters with specialized European toolmakers, creating single-source vulnerability.
- Silicone alternative limitations:Elastomer barrel options face steam sterilization degradation that restricts reprocessing cycles, confining their use to niche pediatric applications.
Strategic Opportunities
- India outpatient expansion:CDSCO streamlined medical device registration pathways and Ayushman Bharat insurance coverage for home enteral nutrition are unlocking patient-managed feeding in tier-2 cities.
- Smart syringe integration:RFID-enabled barrel tracking converges with hospital inventory management systems to automate par-level replenishment and expiration monitoring.
- EU MDR clinical evidence templates:Standardized biocompatibility documentation requirements for enteral accessories reduce regulatory submission preparation costs for compliant manufacturers.
Industry Challenges
- ENFit transition inventory stranding:Health system warehouses retain substantial legacy connector syringe stocks that require write-down protocols and staff retraining before full protocol conversion.
- Precision molding skill scarcity:Connector tolerance specifications below 0.1mm demand experienced process engineers that medical device manufacturers compete for against automotive and consumer electronics sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enteral Syringes Market |
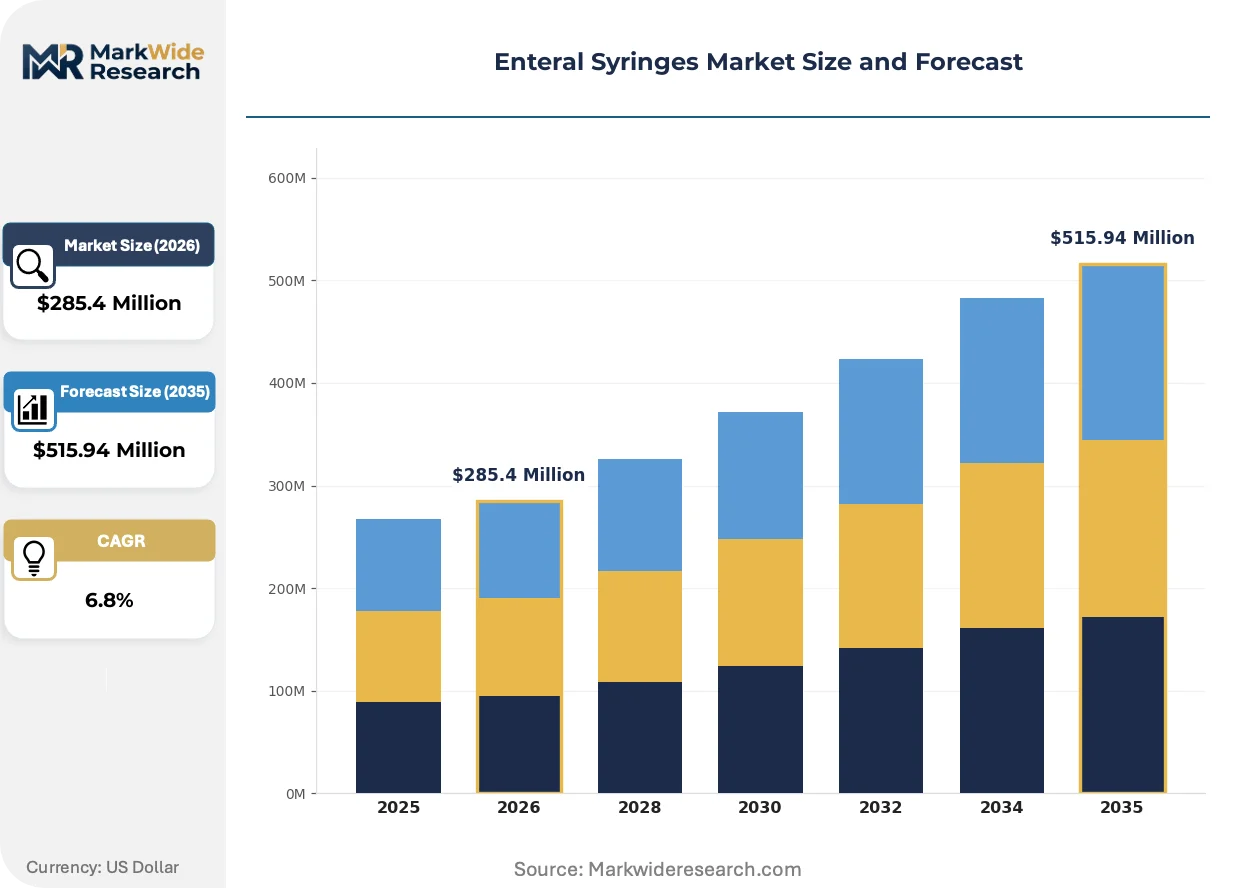
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Reusable, Graduated, Non-graduated End User: Hospitals, Home Care, Long-term Care Facilities, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Feeding Tube, Enteral Material: Plastic, Polypropylene, Silicone, Rubber |
| Companies Covered | B. Braun Melsungen AG, Baxter International Inc., Cardinal Health Inc., GBUK Group Ltd, Kentec Medical Inc., Terumo Corporation, Medela AG, Vygon SAS, Amsino International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enteral Syringes Market Shifts & Advancements
Active redesign cycles are compressing product lifecycles as manufacturers race to satisfy evolving connector standards while integrating digital traceability features into disposable devices.
Anti-microbial polypropylene formulations incorporating silver-ion additives are rendering obsolete standard medical-grade resins in high-risk neonatal intensive care units. Children's Hospital of Philadelphia and comparable pediatric centers are specifying these materials for immunocompromised patient populations. The technology is rendering obsolete conventional barrel sterilization assumptions by embedding sustained surface protection throughout product shelf life.
EU MDR Article 10 clinical evaluation requirements for enteral feeding accessories are elevating biocompatibility testing documentation burdens above legacy Medical Device Directive thresholds. Manufacturers must now submit ISO 10993 cytotoxicity and sensitization data for each resin formulation change, extending design verification timelines. Smaller European contract molders are responding by consolidating onto validated material platforms rather than custom compounding.
Hospital procurement departments are unbundling enteral syringe contracts from bundled feeding tube agreements, creating direct sourcing relationships with specialized device manufacturers. Materials management teams at academic medical centers are negotiating consignment inventory arrangements that shift carrying cost to suppliers. This disintermediation is most visible in the United States, where GPO contract restructuring has accelerated since 2023.
Enteral Syringes Market Segmentation
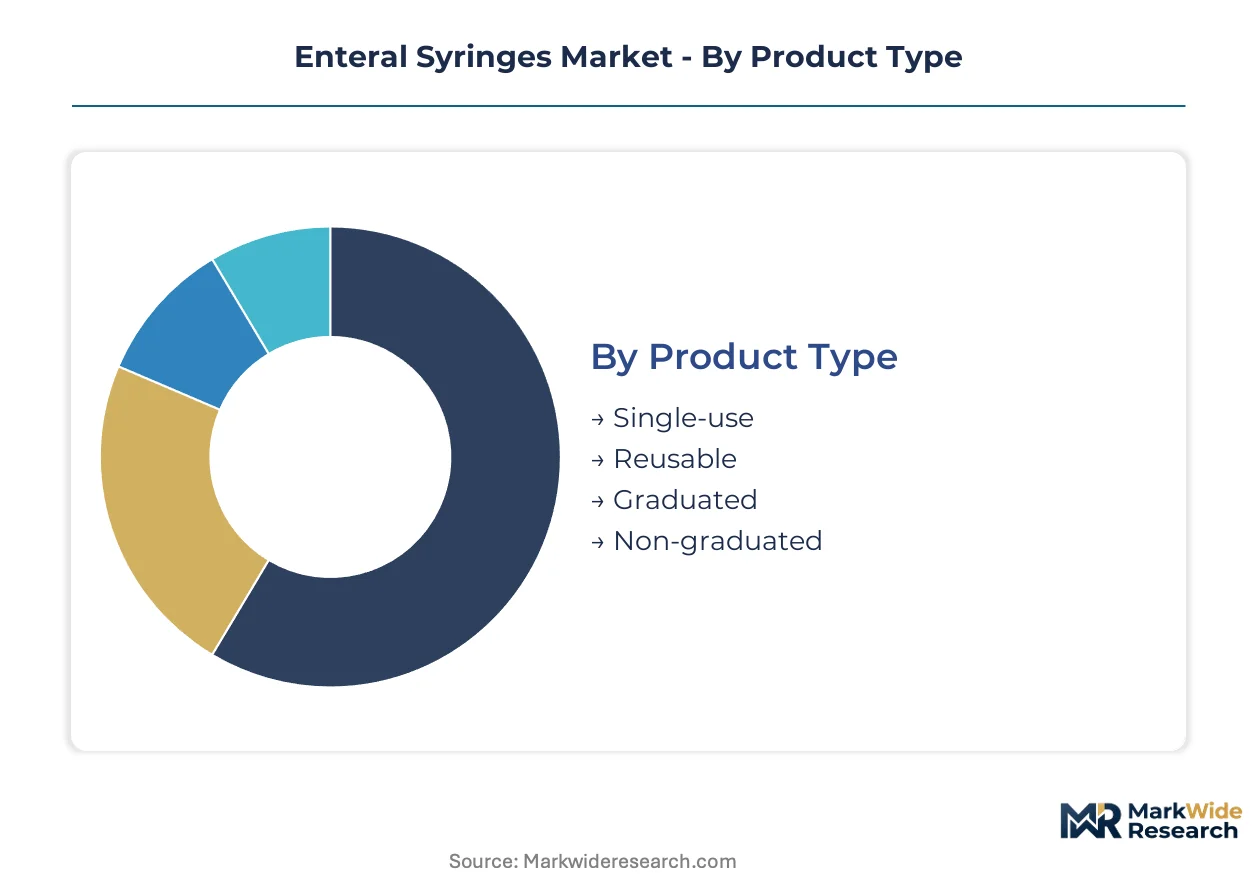
Enteral syringe procurement patterns diverge sharply across clinical settings and material specifications. Product design decisions cascade through sterilization protocols, connector compatibility mandates, and patient-managed care workflows.
Product Type:
Cost tier stratification separates infection-control premiums from capital-equipment amortization strategies in procurement budgets.
- Single-use:Medical-grade polypropylene construction enables gamma sterilization at scale. Demand concentrates in United States surgical wards where Joint Commission mandates eliminate reprocessing risks.
- Reusable:Autoclavable silicone or polypropylene variants withstand 50-100 sterilization cycles. Long-term care facilities in Germany and Japan specify these for cost containment under fixed reimbursement schedules.
- Graduated:Laser-etched barrel markings deliver 0.1ml dose precision for neonatal and pediatric applications.
- Non-graduated:Simplified barrels reduce unit cost for standardized adult feeding protocols where volume verification occurs at the pump.
Single-use holds installed capacity. Reusable is rotating up the share rankings.
End User:
Customer type determines whether procurement emphasizes clinical safety premiums or patient self-management economics.
- Hospitals:Acute care settings specify ENFit-compliant single-use syringes through GPO contracts with consignment inventory terms. United States health systems anchor volume through bundled enteral nutrition agreements.
- Home Care:Patient-managed feeding protocols demand intuitive connector designs and disposable economics. Medicare Advantage plans in Florida and Texas are expanding prior authorization coverage for home enteral supplies.
- Long-term Care Facilities:Medicaid reimbursement constraints favor reusable variants with centralized sterilization departments.
- Rehabilitation Centers:Transitional care settings bridge acute and home protocols with mixed inventory strategies.
Hospitals dominate procurement volume. Home Care is climbing the fastest as discharge planning accelerates.
Delivery Mode:
Application specificity dictates whether syringes interface with gastric tubes, oral medication protocols, or intravenous safety systems.
- Feeding Tube:ENFit-compatible tips prevent misconnection with intravenous lines per ISO 80369-3. Pediatric hospitals in Philadelphia and London specify these for immunocompromised neonatal populations.
- Enteral:Broad category encompassing jejunal and gastric access routes with varying viscosity tolerance for elemental formulas.
- Oral:Modified tip designs for medication administration to patients with dysphagia who retain partial swallowing function.
- Intravenous:Explicitly excluded from enteral syringe design scope; anti-misconnection standards render this category obsolete for new product development.
Feeding Tube commands specification intensity. Enteral is gaining share fastest as route-specific protocols proliferate.
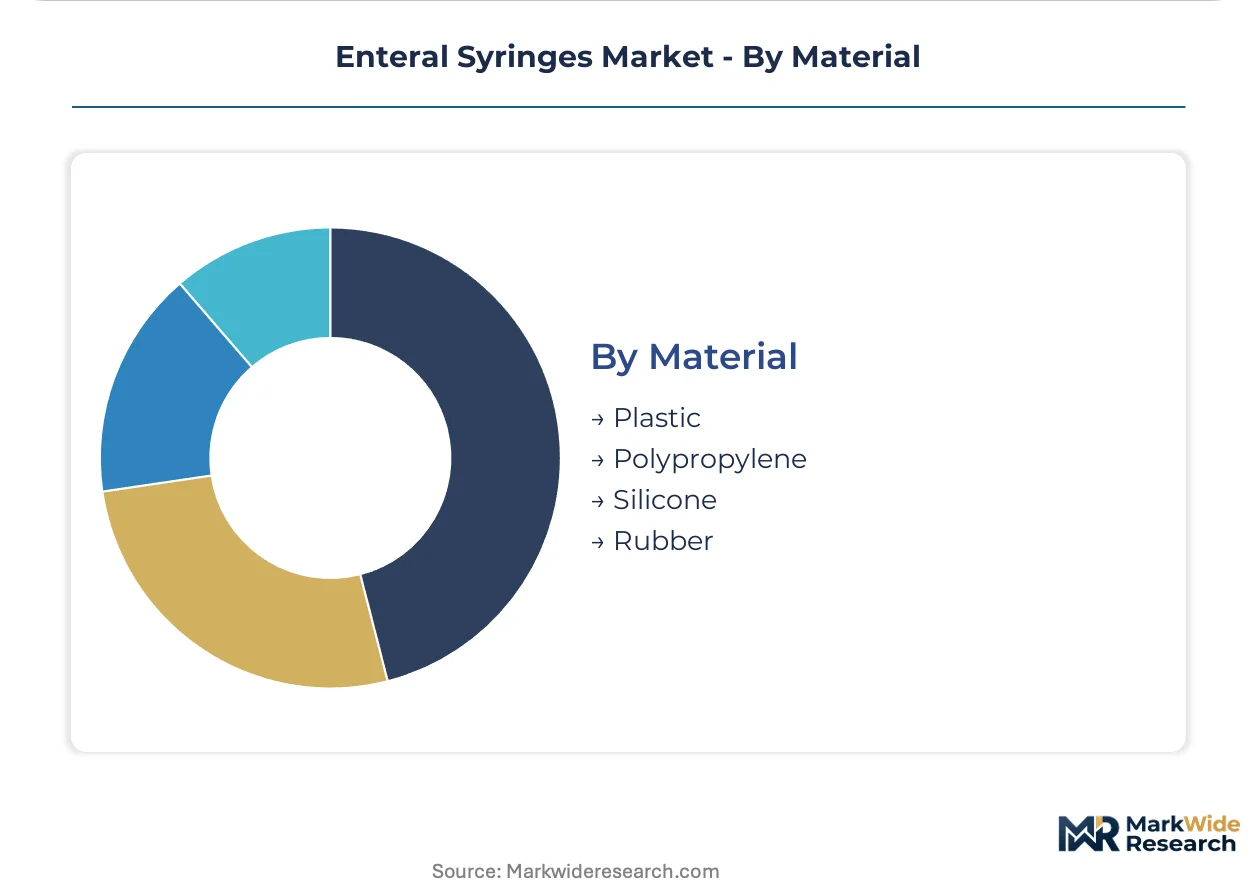
Material:
Supply concentration and sterilization compatibility drive material selection across manufacturing footprints.
- Polypropylene:Steam and gamma sterilization resilience enables single-use economics at scale. German precision molders cluster ENFit-compliant cavity production for European hospital supply chains.
- Plastic:General-purpose medical-grade resins serve cost-sensitive markets with shorter regulatory documentation requirements.
- Silicone:Elastomer barrels offer superior plunger seal integrity but face steam sterilization degradation limiting reprocessing cycles.
- Rubber:Natural and synthetic elastomer options retain niche positions in legacy product lines facing phase-out.
Polypropylene anchors manufacturing capacity. Silicone is rotating up the share rankings in pediatric segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in enteral syringes tilt toward net-import dependence across most major markets, with specialized ENFit-compliant manufacturing clustering in Germany, Japan, and the United States while demand spreads across aging populations worldwide.
United States
Medicare Advantage expansion in Florida and Texas drives home care syringe procurement through prior authorization coverage for outpatient enteral nutrition. The FDA enforces ISO 80369-3 connector standards through its device center, accelerating hospital inventory turnover toward compliant designs. Boston and Philadelphia anchor pediatric specification intensity, with Children's Hospital of Philadelphia mandating anti-microbial polypropylene formulations for immunocompromised neonatal populations.
Germany
Fixed reimbursement schedules under statutory health insurance sustain reusable syringe demand in long-term care facilities seeking cost containment through centralized sterilization departments. The EU Medical Device Regulation imposes stricter clinical evidence thresholds through notified body oversight, elevating compliance costs for enteral feeding accessories. Precision mold shops in Baden-Württemberg and Bavaria cluster ENFit-compliant cavity production, creating single-source vulnerability for tight-tolerance connector machining.
Japan
Aging demographics and stroke rehabilitation protocols expand enteral feeding volume through hospital discharge planning into home care settings. The Pharmaceuticals and Medical Devices Agency coordinates with the Ministry of Health, Labour and Welfare on connector standard harmonization with international frameworks. Osaka and Nagoya host medical device manufacturing clusters where autoclavable silicone syringe variants retain niche positions for pediatric reprocessing applications.
India
Ayushman Bharat insurance coverage for home enteral nutrition unlocks patient-managed feeding in tier-2 cities as discharge protocols shift toward outpatient management. The Central Drugs Standard Control Organization streamlined medical device registration pathways, reducing time-to-market for ENFit-compliant imports and domestic production. Maharashtra and Gujarat concentrate contract manufacturing activity serving both domestic hospital procurement and export markets across South Asia and the Middle East.
United Kingdom
National Health Service procurement frameworks unbundle enteral syringe contracts from bundled feeding tube agreements, creating direct sourcing relationships with specialized device manufacturers. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device safety requirements with residual EU MDR obligations through transitional recognition arrangements. London and the Southeast anchor academic medical center demand where materials management teams negotiate consignment inventory arrangements shifting carrying cost to suppliers.
Enteral Syringes Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: diversified medical device conglomerates with dedicated enteral nutrition portfolios, specialized precision molding contractors with validated ENFit cavity platforms, and regional distributors leveraging GPO contract restructuring to capture procurement disintermediation. Competitive moves concentrate on capacity expansion for compliant connector output and strategic partnerships with hospital systems for consignment inventory arrangements.
Among diversified medical technology conglomerates, B. Braun Melsungen AG and Baxter International Inc. occupy positions anchoring European and North American hospital supply chains respectively, while Terumo Corporation exemplifies the precision-molding specialist archetype with capabilities reducing connector tolerance failures. These three entities represent distinct competitive vectors: geographic manufacturing footprint leverage, dedicated contract anchoring, and technical differentiation through molding expertise.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Baxter International Inc. |
| Cardinal Health Inc. |
| GBUK Group Ltd |
| Kentec Medical Inc. |
| Terumo Corporation |
| Medela AG |
| Vygon SAS |
| Amsino International Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on German precision mold shops for ENFit-compliant connector cavities compresses pricing spreads between premium and standard tiers while tethering supply chain resilience to Bavarian machining capacity. Medical-grade polypropylene resin volatility from Gulf Coast petrochemical complexes further amplifies margin unpredictability across both procurement structures.
Pricing Analysis
Legacy Luer-compatible syringes trade at substantial discounts to ENFit-compliant current-generation products, while anti-microbial polypropylene formulations with silver-ion additives command premium positioning above standard medical-grade tiers. Three-tier pricing structure across premium ENFit anti-microbial, standard ENFit polypropylene, and economy legacy inventory reflects sterilization compatibility and connector standard certification levels. Cost compression in standard polypropylene tiers is intensifying because hospital procurement departments are unbundling contracts from feeding tube bundles and negotiating direct sourcing. Long-term care facilities under Medicaid reimbursement constraints exhibit highest price sensitivity, while pediatric hospitals specifying anti-microbial formulations demonstrate lowest sensitivity due to infection control mandates.
Supply Chain Analysis
Export control regimes limiting dual-use precision molding technology flows constrain capacity expansion outside established medical device manufacturing clusters in Germany, Japan, and the United States. ENFit connector production draws from medical-grade polypropylene resins, precision-machined steel mold cavities, and gamma sterilization infrastructure concentrated in Baden-Württemberg and Osaka. Single-source vulnerability in German tool shops creates structural risk for tight-tolerance connector machining. Distribution runs through group purchasing organization contracts with consignment inventory arrangements shifting carrying costs to manufacturers at major United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enteral syringe demand sits in early-cycle expansion as home care protocols and patient-managed feeding adoption accelerate discharge planning conversions. Medicare Advantage prior authorization expansion for outpatient enteral nutrition sustains penetration tailwinds.
For Market Incumbents: Insulate market position by securing captive supply agreements with Bavarian precision molders for ENFit cavity capacity, and accelerate backward integration into medical-grade polypropylene compounding to offset resin cost volatility from Gulf Coast feedstock exposure. Emerging contract manufacturers in India pose substitution threats through CDSCO-streamlined registration pathways. For New Entrants and Emerging Players: Pursue white-space capture in tier-2 Indian cities where Ayushman Bharat insurance coverage for home enteral nutrition is unlocking patient-managed feeding demand ahead of established supply infrastructure. Target pediatric anti-microbial formulation segments where specification intensity exceeds manufacturing competition. Lead with direct hospital system partnerships bypassing GPO intermediaries. For Investors and Strategic Acquirers: Precision molding contractors with validated ENFit cavity platforms and established FDA 510(k) submission track records represent the most defensible acquisition archetype. Long-term viability hinges on connector standard harmonization durability and home care protocol permanence. Watch for FDA-EU regulatory divergence on ISO 80369-3 implementation timelines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ENFit Cavity Capacity Expansion | Secures tight-tolerance machining output for FDA-compliant connector demand at German precision molders. |
| Anti-Microbial Formulation Development | Addresses Children's Hospital of Philadelphia specifications for immunocompromised neonatal populations. |
| Hospital System Direct Partnership | Bypasses GPO intermediaries through consignment inventory arrangements shifting carrying cost burden. |
| India Manufacturing Footprint | Captures CDSCO-streamlined registration benefits and Ayushman Bharat reimbursement expansion. |
| Smart Syringe RFID Integration | Automates par-level replenishment through convergence with hospital inventory management systems. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and enteral nutrition clinicians anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up demand modeling triangulates against top-down market sizing.
Calibration across the projection horizon employs segmented modeling by product type, end user setting, material specification, and regional regulatory cluster. CAGRs derive from installed base turnover rates, ENFit transition timelines, and home care discharge protocol adoption curves. Forecast inputs incorporate polypropylene resin price indices, precision molding capacity utilization, and Medicare Advantage prior authorization expansion trajectories.
Sensitivities concentrate around ENFit transition completion rates, German mold shop capacity constraints, and FDA-EU regulatory harmonization durability. Forecasts reflect documented assumptions on connector standard permanence and reimbursement policy stability. Material shifts in polypropylene feedstock supply or ISO 80369-3 standard revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Trauma Products Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Earwax Removal Aid Market
Medical Supplies
Germany Hospital Supplies Market
Medical Supplies
Foley Trays Market
Medical Supplies
Global Medical Foam Market