
 Global Urinary Drainage Bags Market | 2026-2036
Global Urinary Drainage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urinary Drainage Bags Market Foresight
Asset-light leasing models for home care equipment is narrowing the capital barrier for regional distributors entering the urinary drainage bags supply chain. Coloplast A/S leverages its direct-to-patient channel infrastructure across Nordic and North American markets. Medline Industries, Inc. sustains competitive throughput via captive distribution networks and private-label scale. Hollister Incorporated differentiates through hydrocolloid adhesive technology leadership in ostomy-adjacent urology portfolios.
Urinary drainage bags are closed-collection systems manufactured from polyvinyl chloride or thermoplastic elastomer films, typically incorporating anti-reflux valves and graduated volume markings for sterile urine management in catheterized patients. Leg bags dominate ambulatory use cases due to discreet profile and strap-secured mobility, while bedside bags capture higher per-unit volume in acute and post-acute institutional settings. Anti-bacterial coating technology commands premium positioning as infection control protocols tighten across hospitals and nursing facilities. Latex-free films are displacing legacy formulations as allergy documentation becomes standard in procurement workflows.
FDA 510(k) clearance requirements govern material biocompatibility and sterility assurance for US market access, while the EU Medical Device Regulation mandates notified body conformity assessment for CE-marked products sold across European member states. ISO 13485 quality management certification functions as a baseline qualification for original equipment manufacturer partnerships with hospital purchasing consortiums. Stakeholders must monitor evolving home care reimbursement codes and antimicrobial resistance surveillance data to align portfolio development with shifting site-of-care economics.
Market Dynamics
Site-of-care migration from acute hospitals to home settings is compressing product specifications and reimbursement pathways simultaneously. Manufacturers must now engineer for dual-use compatibility across institutional and ambulatory environments while navigating divergent sterility standards.
Growth Catalysts
- EU Medical Device Regulation (MDR) harmonization:CE-marked products gain streamlined cross-border access across 27 member states, consolidating procurement volumes for notified body-certified manufacturers.
- Thermoplastic elastomer film adoption:PVC-free formulations address institutional sustainability mandates and patient allergy documentation requirements in German and Japanese hospital systems.
- Home care reimbursement expansion:Medicare Advantage and analogous programs in Australia and Canada now cover closed-system drainage for outpatient catheter management.
Market Restraints
- Medical-grade polymer supply concentration:Base resin production clusters in US Gulf Coast and Northeast Asian petrochemical corridors expose converters to feedstock volatility and force majeure risk.
- FDA 510(k) pathway friction:Substantial equivalence determinations for anti-reflux valve innovations extend clearance timelines, delaying premium product launches.
- Intermittent catheter substitution:Clean intermittent self-catheterization protocols reduce indwelling catheter dependency in spinal cord injury and multiple sclerosis populations.
Strategic Opportunities
- Brazilian home care infrastructure:ANVISA's simplified medical device registration for Class II products opens direct-to-patient channels in underserved Southeast metropolitan corridors.
- Antimicrobial coating convergence:Silver-ion and chlorhexidine-impregnated films combine with hydrocolloid interfaces to command premium positioning in infection-prevention bundles.
- Digital health integration:Bluetooth-enabled volume sensors and cloud-connected drainage monitoring create recurring revenue streams through SaaS-enabled bag replacement programs.
Industry Challenges
- ISO 13485 auditor scarcity:Notified body capacity constraints extend quality management certification renewal cycles, freezing OEM partnership negotiations.
- Legacy ERP integration:Hospital purchasing consortiums demand EDI-compliant order-to-cash automation that mid-tier converters lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urinary Drainage Bags Market |
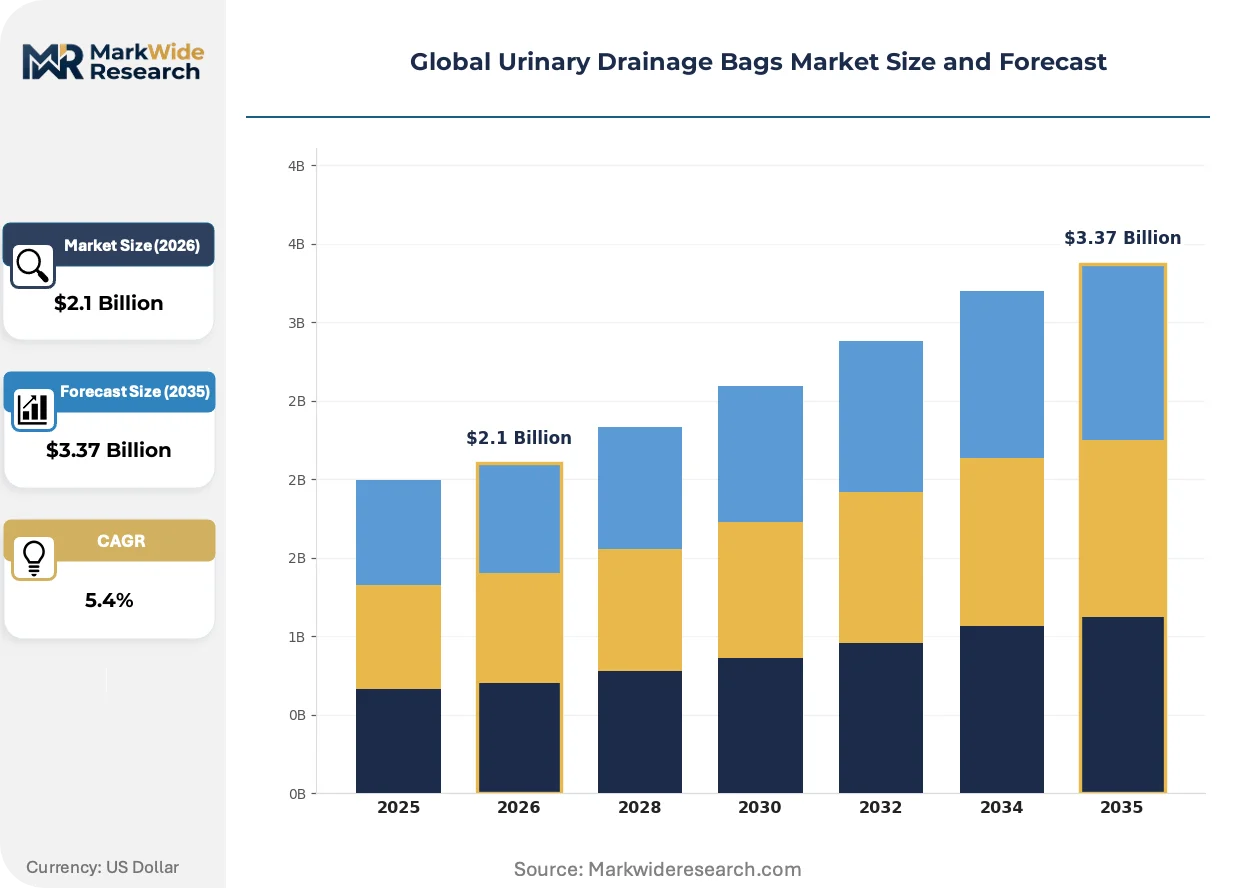
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leg Bags, Bedside Bags, Night Drainage Bags, Portable Drainage Bags, Pediatric Drainage Bags Material: Polyvinyl Chloride, Thermoplastic Elastomer, Silicone, Polyethylene, Latex-Free Films End User: Hospitals, Nursing Facilities, Home Care Settings, Rehabilitation Centers Technology: Anti-Reflux Valves, Odor Control, Hydrocolloid Adhesives, Leak-Proof Seals, Anti-Bacterial Coating |
| Companies Covered | ConvaTec Group PLC, Medline Industries, Inc., BD (Becton, Dickinson and Company), Flexicare Medical Limited, Hollister Incorporated, Coloplast A/S, B. Braun Melsungen AG, Amsino International, Inc., Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urinary Drainage Bags Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are collapsing the traditional separation between acute-care and home-use product lines. Manufacturers now engineer single SKUs for dual-environment deployment.
Anti-bacterial coating technology is migrating from premium hospital contracts to standard home care configurations. Long-term care facilities in the Netherlands and Sweden now specify silver-impregnated films as baseline procurement requirements. This migration from elective upgrade to default specification compresses margin differentiation for coating specialists while expanding addressable volume for integrated converters.
The EU Medical Device Regulation's Unique Device Identification mandate forces legacy labeling retrofits across European distribution networks. Manufacturers serving German, French, and Italian markets must revalidate packaging lines for GS1-compliant barcode serialization. Sterile kit assemblers absorb the highest compliance burden, as multi-component bags require nested UDI hierarchies that legacy ERP systems struggle to encode.
Hospital purchasing consortiums now unbundle after-sales technical support from product supply contracts. GPOs in the United States and group purchasing structures in the United Kingdom separately negotiate clinical training, inventory management, and waste disposal services. This disintermediation of service from supply forces manufacturers to build captive field service organizations or cede margin to third-party logistics partners.
Global Urinary Drainage Bags Market Segmentation
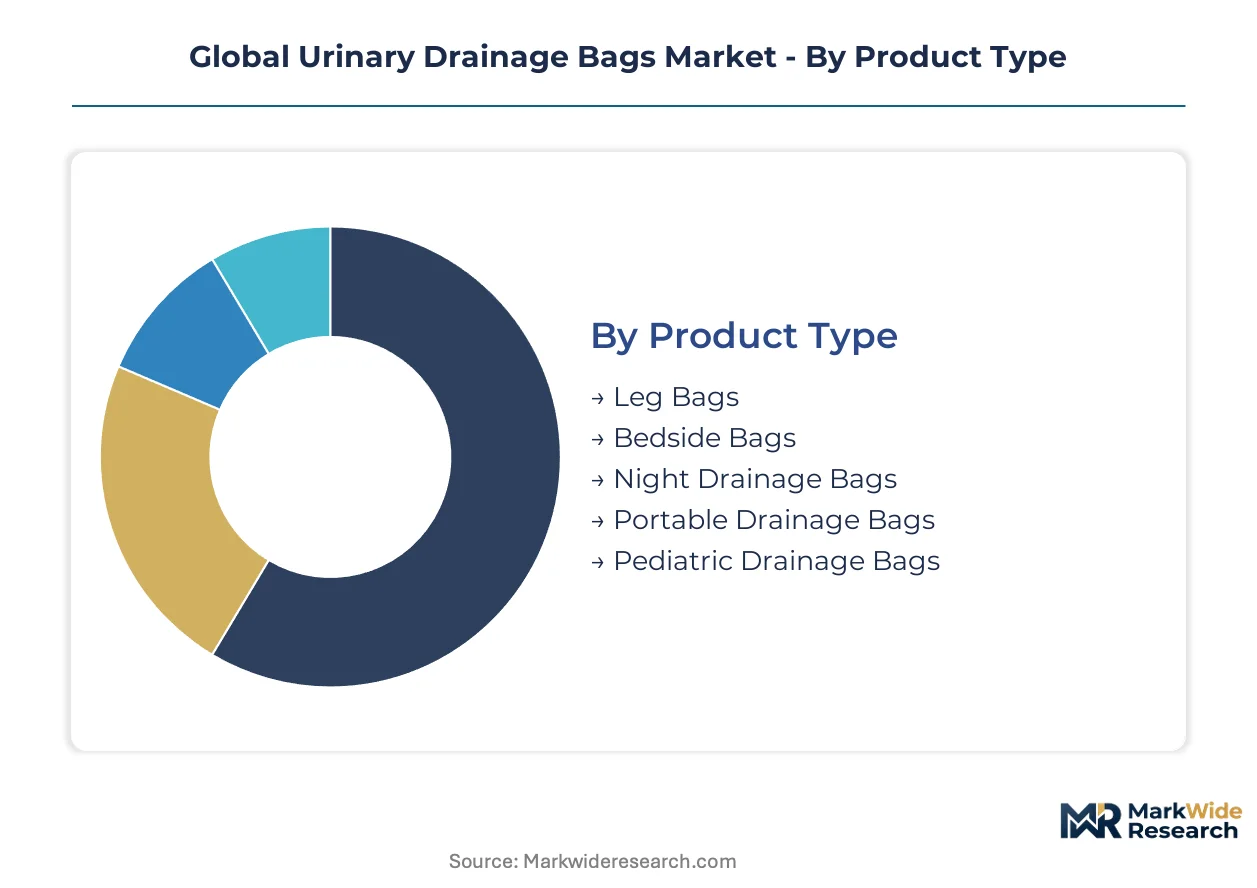
Product differentiation in urinary drainage bags hinges on site-of-care compatibility and infection control specifications. Manufacturers engineer segment-specific features that align with divergent sterility, mobility, and reimbursement requirements across acute and ambulatory environments.
Product Type:
After-sales service intensity varies sharply across product types, with bedside bags requiring institutional inventory management support while leg bags demand patient education and replacement logistics.
- Leg Bags:Strap-secured designs with discreet profiles enable ambulatory mobility for catheterized patients managing daily activities. Demand concentrates in German and Japanese home care markets where outpatient reimbursement supports long-term catheter management. Patient education and replacement logistics create higher service intensity than institutional alternatives.
- Bedside Bags:High-volume closed-collection systems with graduated markings serve acute and post-acute institutional settings. Hospitals in the United States and the Netherlands specify these for inpatient urology and post-surgical recovery. Bulk procurement contracts demand vendor-managed inventory and clinical training support.
- Night Drainage Bags:Extended-capacity designs with reinforced hanging mechanisms support nocturnal catheter management in home settings.
- Portable Drainage Bags:Compact, disposable formats address travel and short-duration mobility needs for intermittent catheter users.
- Pediatric Drainage Bags:Smaller-volume configurations with skin-sensitive adhesives serve neonatal and pediatric urology departments.
Bedside bags hold the largest share; momentum sits with leg bags as site-of-care migration accelerates.
Material:
Cost tier stratification separates commodity PVC formulations from premium polymer alternatives, with sustainability premiums reshaping procurement specifications in Northern European hospital systems.
- Polyvinyl Chloride:Standard medical-grade films dominate volume production due to established supply chains and conversion economics. German procurement consortiums now impose sustainability surcharges on PVC-based contracts, accelerating substitution pressure.
- Thermoplastic Elastomer:PVC-free formulations with enhanced flexibility and biocompatibility command premium positioning in allergy-sensitive patient populations. Japanese hospital systems mandate TEP documentation for long-term catheter patients.
- Silicone:High-purity formulations serve specialized pediatric and burn-unit applications requiring maximum biocompatibility.
- Polyethylene:Lightweight alternatives for single-use disposable segments in cost-constrained emerging markets.
- Latex-Free Films:Mandatory specifications in United States hospital procurement following FDA allergy documentation requirements.
Thermoplastic elastomer is expanding most quickly; polyvinyl chloride retains volume dominance.
End User:
Application requirements dictate divergent product specifications, with home care settings demanding simplified interfaces and institutional buyers prioritizing infection control bundles.
- Hospitals:Acute-care facilities specify anti-bacterial coatings and closed-system integrity for surgical and ICU applications. United States GPOs bundle drainage bags with catheter kits under outcome-based contracts.
- Home Care Settings:Outpatient management growth in Australia and Canada drives demand for patient-friendly designs with simplified emptying mechanisms.
- Nursing Facilities:Long-term care operators in Sweden and the Netherlands specify silver-impregnated films as baseline infection prevention.
- Rehabilitation Centers:Transitional care facilities require dual-use products compatible with both institutional and home discharge protocols.
Hospitals hold the largest share; home care settings show the steepest expansion trajectory.
Technology:
Margin concentration aligns with certification intensity, with anti-bacterial and anti-reflux innovations capturing premium positioning against commodity seal technologies.
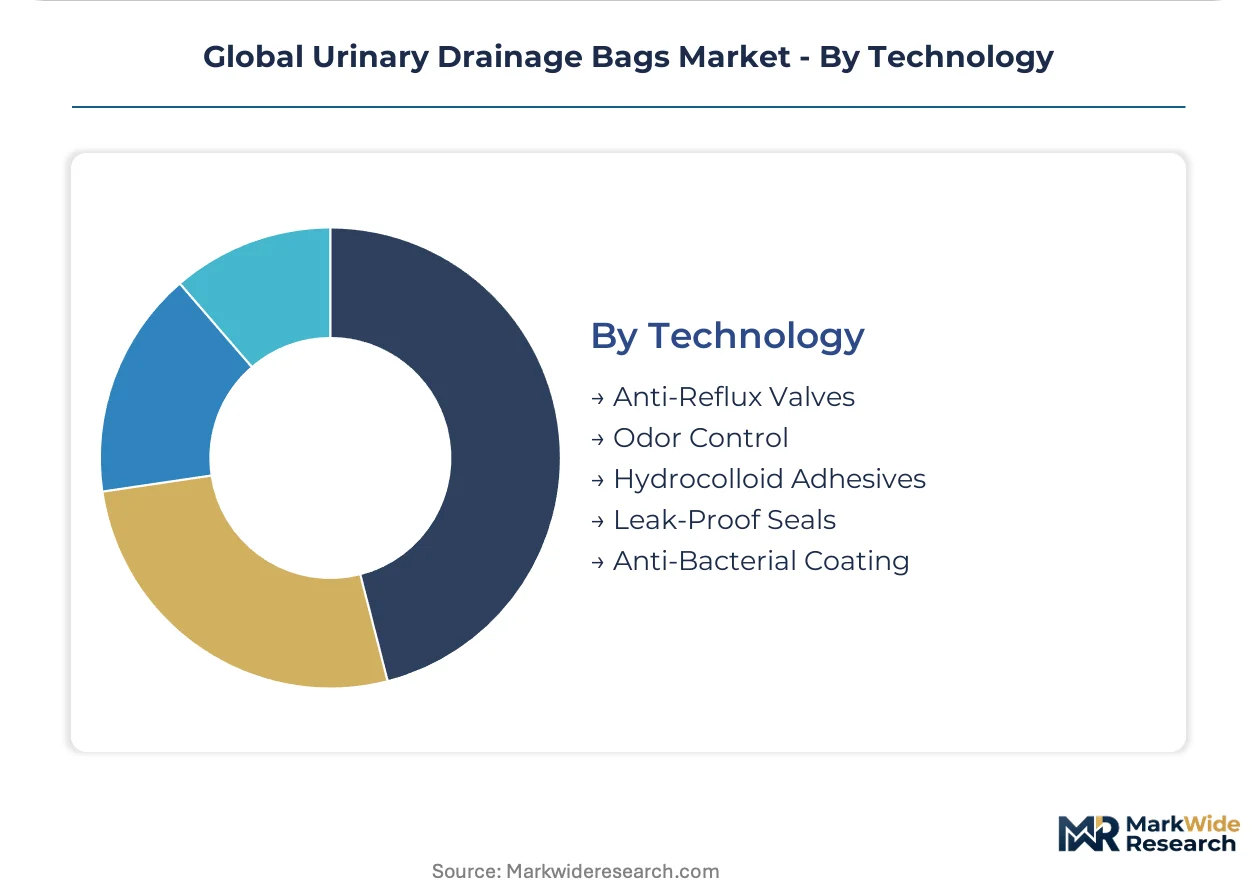
- Anti-Bacterial Coating:Silver-ion and chlorhexidine-impregnated films command infection-prevention premiums in hospital and nursing facility contracts. Dutch procurement now specifies these as standard rather than upgrade options.
- Anti-Reflux Valves:Mechanical barriers preventing retrograde contamination represent critical safety features in post-surgical applications. FDA 510(k) clearance requirements extend development timelines for valve design innovations.
- Odor Control:Activated carbon layers address quality-of-life priorities in home care and rehabilitation settings.
- Hydrocolloid Adhesives:Skin-friendly interfaces reduce dermatitis incidence in long-term catheter patients.
- Leak-Proof Seals:Heat-welded and mechanical closure systems form baseline specifications across all end-use categories.
Anti-reflux valves hold the largest share; anti-bacterial coating gains share fastest as infection protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German hospital procurement by roughly 15-20% per unit, reflecting divergent reimbursement elasticity and GPO consolidation intensity. Japanese buyers command premium specifications for PVC-free formulations that compress converter margins despite higher nominal prices.
United States
Medicare Advantage expansion for home-based catheter management drives volume migration toward ambulatory-compatible leg bags. FDA 510(k) clearance timelines for anti-reflux valve innovations extend 8-14 months, delaying premium product launches. Manufacturing concentration in the Midwest industrial corridor supports just-in-time delivery to hospital purchasing consortiums.
Germany
Hospital procurement consortiums impose sustainability surcharges on PVC-based contracts, accelerating thermoplastic elastomer substitution. EU MDR notified body certification requirements favor established CE-marked suppliers over new market entrants. The Rhine-Ruhr manufacturing belt hosts specialized film converters serving Dutch and Scandinavian export demand.
Japan
PMDA biocompatibility documentation mandates for long-term catheter patients elevate TEP formulations to standard specification. METI industrial standards for medical device plastics restrict legacy polymer formulations in public hospital procurement. The Kansai industrial region concentrates precision film extrusion capacity for allergy-sensitive product lines.
Brazil
ANVISA's simplified Class II medical device registration opens direct-to-patient channels in underserved Southeast metropolitan corridors. Private health insurance expansion in São Paulo and Rio de Janeiro creates demand for closed-system drainage in home care settings. Domestic converters in the São Paulo state industrial zone struggle with imported resin cost volatility.
Australia
National Disability Insurance Scheme reimbursement for outpatient catheter supplies expands addressable volume beyond acute hospital capture. TGA conformity assessment alignment with EU MDR reduces regulatory duplication for CE-marked imports. Sydney and Melbourne distribution hubs consolidate state-level procurement for rural home care nursing networks.
Global Urinary Drainage Bags Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film extrusion and valve subassembly. The vendor base organizes into three tiers: multinational medtech conglomerates with captive urology divisions, regional converters with notified body certification, and private-label assemblers serving GPO contracts. Strategic moves concentrate on backward integration into medical-grade polymer compounding and geographic licensing of antimicrobial coating IP.
Among European-domiciled platform players, Coloplast A/S and B. Braun Melsungen AG occupy positions emphasizing direct-to-patient channel control and institutional procurement scale respectively. Hollister Incorporated anchors the adhesive-interface specialization archetype, leveraging hydrocolloid technology cross-licensed from adjacent ostomy portfolios. These three exemplify divergent paths to margin defense: channel ownership, manufacturing scale, and materials science differentiation.
| Leading Market Players |
|---|
| ConvaTec Group PLC |
| Medline Industries, Inc. |
| BD (Becton, Dickinson and Company) |
| Flexicare Medical Limited |
| Hollister Incorporated |
| Coloplast A/S |
| B. Braun Melsungen AG |
| Amsino International, Inc. |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
The US Gulf Coast petrochemical corridor concentrates medical-grade PVC and thermoplastic elastomer resin production, and this feedstock clustering grants incumbent converters pricing leverage over regional distributors in Germany and Japan who face currency-adjusted import premiums. Converter margins compress when Northeast Asian force majeure events spike spot resin costs, forcing bedside bag specialists to absorb volatility or renegotiate annual hospital contracts.
Pricing Analysis
Configured-to-order leg bags with patient-specific strap configurations and anti-reflux valve specifications command 25-35% premiums over standard bedside bag SKUs sold through GPO tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating technology—silver-impregnated films sit at the top, PVC-free TEP formulations occupy the mid-tier, and commodity PVC bags anchor the bottom. Pricing pressure stems from Medicare Advantage reimbursement compression for home care equipment, which squeezes distributor markups on ambulatory products. Hospital purchasing committees show lowest price sensitivity for infection-prevention bundles, while cash-pay home care patients in Brazil and Southeast Asia drive volume through economy-tier private-label alternatives.
Supply Chain Analysis
Contract manufacturing for urinary drainage bags concentrates among specialized medical film converters in the US Midwest industrial corridor, the Rhine-Ruhr manufacturing belt, and the Kansai precision extrusion zone. Raw material supply draws from US Gulf Coast and Northeast Asian petrochemical corridors for base resins, German specialty chemical producers for antimicrobial additives, and Japanese precision molders for anti-reflux valve subassemblies. Single-source vulnerability sits with FDA-registered sterile packaging facilities in the Midwest, where capacity constraints extend lead times during seasonal demand surges. Distribution runs through hospital purchasing consortiums in the United States, CE-marked notified body-certified distributors in the EU, and direct-to-patient channels in Nordic markets where Coloplast maintains captive logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital purchasing consortium consolidation in the United States and group purchasing organization unification across the Netherlands, Sweden, and Germany, which compresses supplier margins and demands bundled service offerings.
For Market Incumbents: Insulate market position by deepening backward integration into medical-grade polymer compounding to capture resin margin and hedge feedstock volatility, while accelerating ISO 13485 certification renewal cycles ahead of notified body auditor scarcity. The threat of intermittent catheter substitution protocols in spinal cord injury populations demands R&D investment in dual-use drainage systems compatible with both indwelling and intermittent workflows. Channel control through direct-to-patient infrastructure in Nordic markets provides defensive moats against GPO pricing pressure. For New Entrants and Emerging Players: Brazilian home care corridors in São Paulo and Rio de Janeiro represent the most penetrable entry point given ANVISA's simplified Class II registration pathway and private insurance expansion for outpatient catheter management. Australian National Disability Insurance Scheme reimbursement channels offer secondary white-space opportunity with lower regulatory duplication for CE-marked imports. A go-to-market angle anchored in SaaS-enabled volume monitoring with Bluetooth sensors creates recurring revenue differentiation against commodity bag assemblers. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-dependency play because aging population outpatient management and site-of-care migration structurally expand addressable volume regardless of macroeconomic cycles. Acquisition targets should prioritize notified body-certified regional converters with existing CE marking and captive distribution in German or Japanese procurement corridors. The signal to watch is home care reimbursement code expansion in Medicare Advantage and analogous programs, which would validate ambulatory-compatible product R&D and trigger valuation rerating for leg bag specialists.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body certification unlocks streamlined cross-border access across 27 member states. |
| Hospital System Partnership | GPO contract integration secures vendor-managed inventory and clinical training revenue streams. |
| Software Companion Development | Bluetooth-enabled volume sensors create SaaS-enabled recurring replacement programs. |
| Reimbursement Strategy | Medicare Advantage code alignment validates premium positioning for home care drainage systems. |
| Backward Integration | In-house polymer compounding captures resin margin and hedges Gulf Coast feedstock volatility. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committee managers, GPO contracts administrators, biomedical engineers, and home care nursing coordinators anchors the qualitative findings against secondary validation through FDA 510(k) clearance databases, EU MDR notified body certification registries, CMS Medicare reimbursement code filings, and hospital procurement consortium contract disclosures. Bottom-up demand modeling triangulates against top-down macroeconomic demographic projections.
Calibration against historical volume trajectories and regulatory approval timelines informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material formulation, end-use environment, and coating technology tier. CAGRs derive from regression analysis of site-of-care migration rates and reimbursement elasticity by geography. Forecast inputs incorporate antimicrobial resistance surveillance data and polymer feedstock price indices.
Practitioners should monitor home care reimbursement code revisions and notified body certification backlog durations for early signals of demand inflection or supply constraint. Forecasts reflect assumptions around regulatory harmonization timelines and demographic outpatient management trends. Quarterly review of GPO contract renewal rates and resin spot price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Swab Cups Market
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
South America Syringe Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Face Mask Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Autoclaving Trays Market