
 Healthcare Cleanroom Consumables Market | 2026-2036
Healthcare Cleanroom Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Cleanroom Consumables Market Outlook
China is rewriting capacity dynamics in cleanroom consumables as domestic biopharma manufacturing scales. Kimberly-Clark Corporation leverages its nonwoven material science to anchor North American supply chains for sterile garments. DuPont competes through advanced polymer R&D in high-barrier fabrics, while Thermo Fisher Scientific Inc. extends its channel control by bundling consumables with analytical instrumentation.
Healthcare cleanroom consumables encompass garments, wipes, gloves, and mops engineered from polyester, polypropylene, vinyl, and nylon to maintain ISO-classified particulate thresholds below specified micron counts; these products prevent microbial and particulate contamination during aseptic drug compounding, cell culture operations, and medical device assembly. Garments command the largest revenue pool due to frequent change-out protocols in Grade A/B environments, while gloves exhibit the fastest structural expansion driven by biotechnology labs handling potent compounds. Contract Manufacturing Organizations represent a concentrated end-user segment where procurement consolidates around vendors offering validated sterile-to-the-bag supply models.
The FDA enforces current Good Manufacturing Practice standards that mandate documented particulate shedding limits for all consumables entering aseptic processing zones, while ISO 14644 cleanroom classification protocols shape international product specifications for airborne particle retention. The EU's MDR framework tightens traceability requirements for consumables contacting finished medical devices, compelling suppliers to deploy lot-level digital tracking. Stakeholders must monitor how regulatory divergence between FDA and EMA validation protocols affects dual-site manufacturing strategies and supplier qualification costs.
Market Dynamics
Single-use cleanroom garments are displacing reusable textiles across pharmaceutical manufacturing, driven by FDA aseptic processing guidance that tightens validation requirements for cross-contamination control in biologics production.
Growth Catalysts
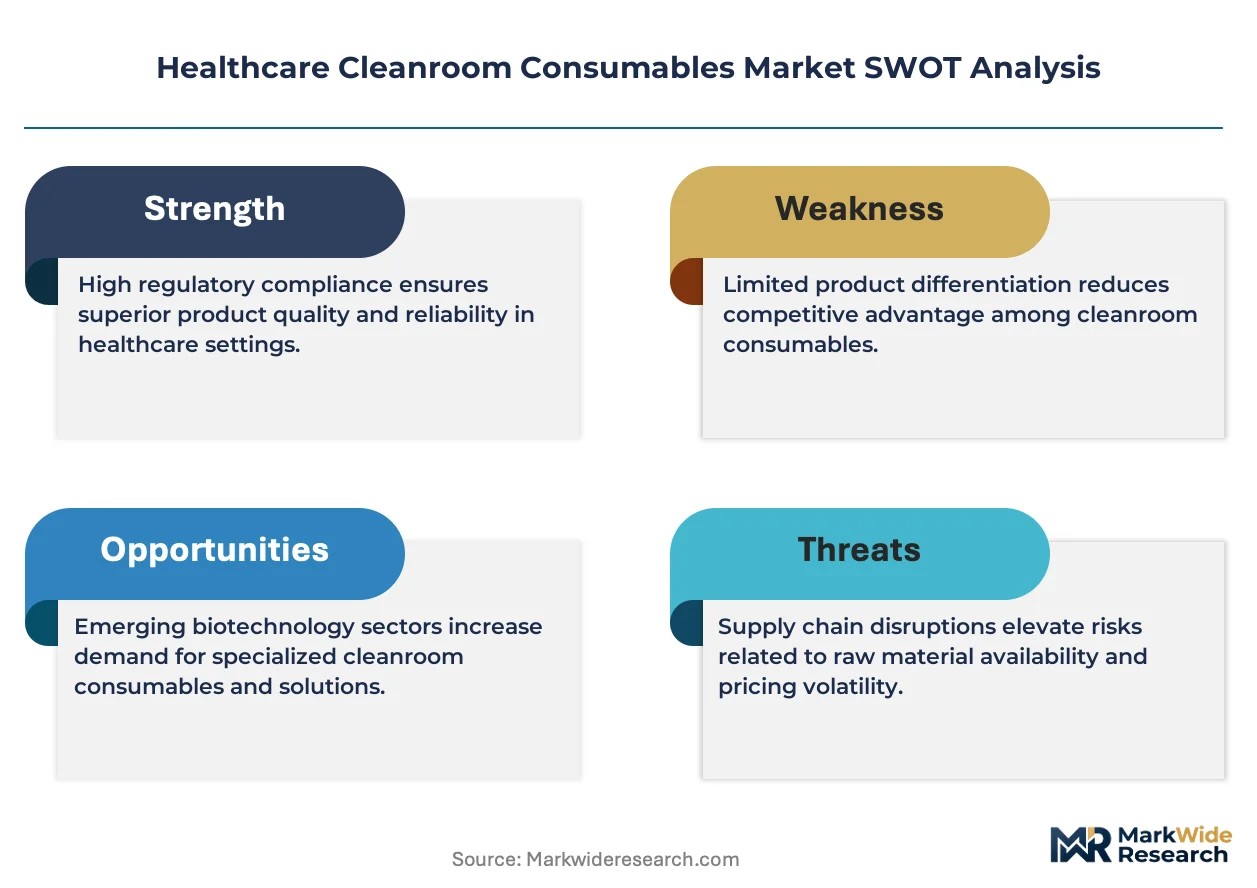
- Biologics capacity expansion:Cell culture and gene therapy manufacturing facilities in the United States require ISO 14644-1 Class 7 and Class 8 environments, generating sustained pull for validated consumables with documented particulate shedding profiles.
- FDA aseptic processing guidance:Updated enforcement of current Good Manufacturing Practice standards mandates sterile-to-the-bag supply models, accelerating qualification of single-use garments and wipes in Grade A/B cleanrooms.
- Polypropylene nonwoven innovation:Spunbond-meltblown-spunbond laminates now achieve bacterial filtration efficiency above specified thresholds while reducing garment weight, enabling longer wear cycles without compromising barrier integrity.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyester resin prices fluctuate with crude oil indices, compressing margins for garment manufacturers unable to pass through raw material cost swings.
- Asian supply concentration:Spunbond nonwoven fabric production clusters in China create single-source dependencies for North American and European converters, exposing supply chains to freight cost spikes and customs delays.
- Reusable textile substitution:Launderable polyester garments with embedded conductive fibers retain cost advantage in less critical ISO Class 8 environments, limiting addressable market for single-use alternatives.
Strategic Opportunities
- India biopharma manufacturing:CDSCO production-linked incentive schemes attract multinational biologics investments to Hyderabad and Bangalore, creating demand for sterile consumables with local validation support.
- EU MDR traceability mandates:Lot-level digital tracking requirements for consumables contacting finished medical devices open channel control opportunities for suppliers with integrated serialization platforms.
- Cell and gene therapy cleanrooms:Autologous therapy manufacturing requires patient-dedicated production suites, multiplying garment change-out frequency and consumable consumption per facility.
Industry Challenges
- ISO 14644 certification timelines:Third-party cleanroom classification audits for consumable manufacturing facilities extend supplier qualification cycles, delaying new product commercialization.
- Contamination control technician shortage:Aseptic technique training programs fail to match biopharma facility expansion, constraining operational scale-up even where consumable supply is secured.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Cleanroom Consumables Market |
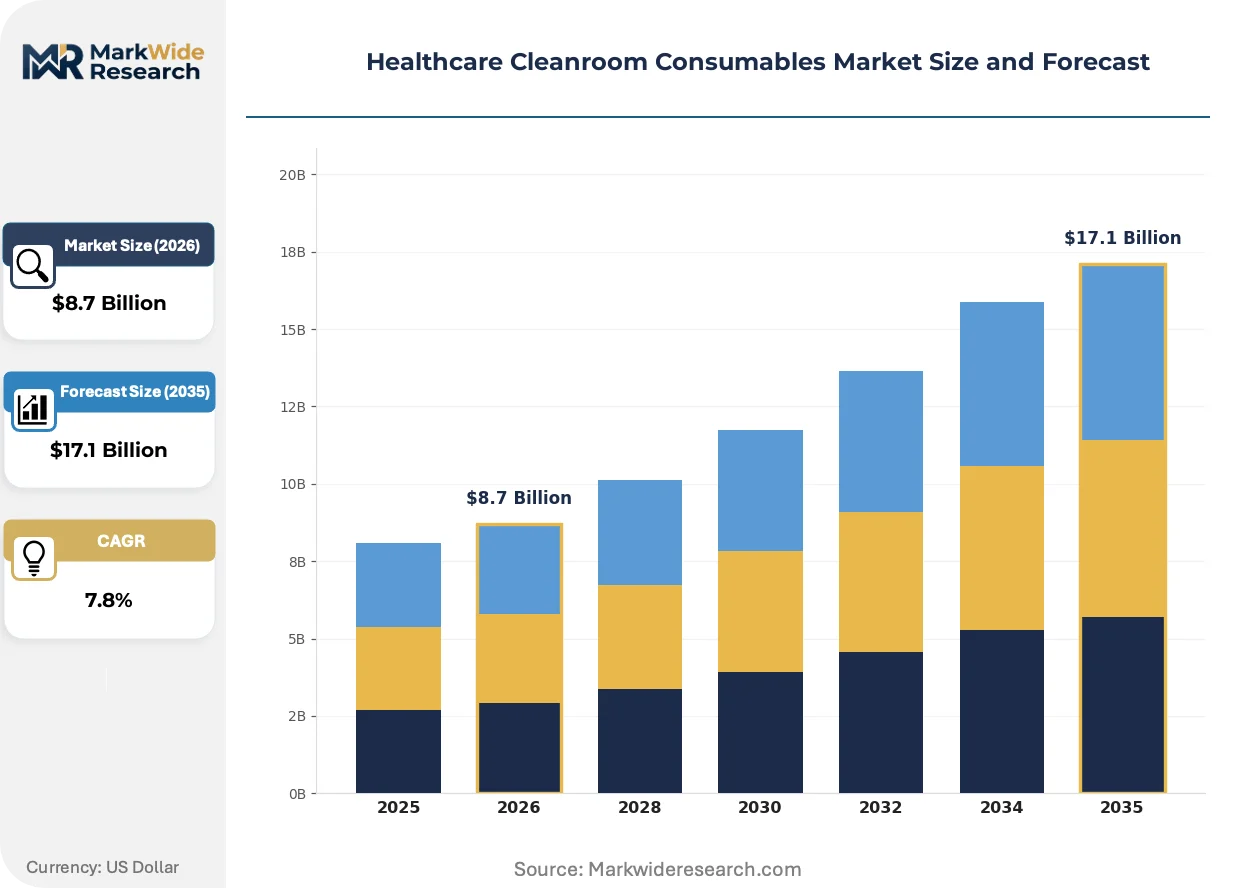
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garments, Wipes, Gloves, Mops Application: Pharmaceutical Manufacturing, Biotechnology Labs, Medical Device Production, Research Facilities Material: Polyester, Polypropylene, Vinyl, Nylon End User: Hospitals, Laboratories, Clinics, Contract Manufacturing Organizations |
| Companies Covered | DuPont, Kimberly-Clark Corporation, Valutek Inc., Texwipe Company, Nitritex Ltd., Thermo Fisher Scientific Inc., Steris, Contec Inc., Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Cleanroom Consumables Market Strategic Shifts
Digital validation platforms and sustainable material chemistries are restructuring how cleanroom consumables are specified, procured, and disposed across pharmaceutical and medical device manufacturing environments.
Recyclable polypropylene garments with validated mechanical recycling pathways are virtualizing the waste management calculus for pharmaceutical operators. Contract manufacturing organizations in the United States pilot closed-loop collection programs that return post-use garments to resin producers. This infrastructure is virtualizing disposal cost structures and enabling Scope 3 emissions reporting that large molecule manufacturers require for ESG disclosure.
The EU's Medical Device Regulation tightens biocompatibility documentation for consumables contacting finished devices, forcing suppliers to maintain extractables and leachables data packages. European notified bodies now require cytotoxicity and sensitization testing for glove and wipe polymers previously exempt under the Medical Device Directive. German and Swiss medical device manufacturers are consolidating supplier panels around vendors with pre-submitted technical files to accelerate product registration.
Consolidated vendor agreements are compressing the supplier base for contract manufacturing organizations, replacing transactional purchasing with multi-year sterile-to-the-bag supply contracts. Large CDMOs in Massachusetts and North Carolina now mandate single-source relationships for core garment categories, bundling wipes and gloves under unified quality agreements. This concentration rewards suppliers with redundant manufacturing sites and disqualifies regional converters lacking geographic redundancy.
Healthcare Cleanroom Consumables Market Segmentation
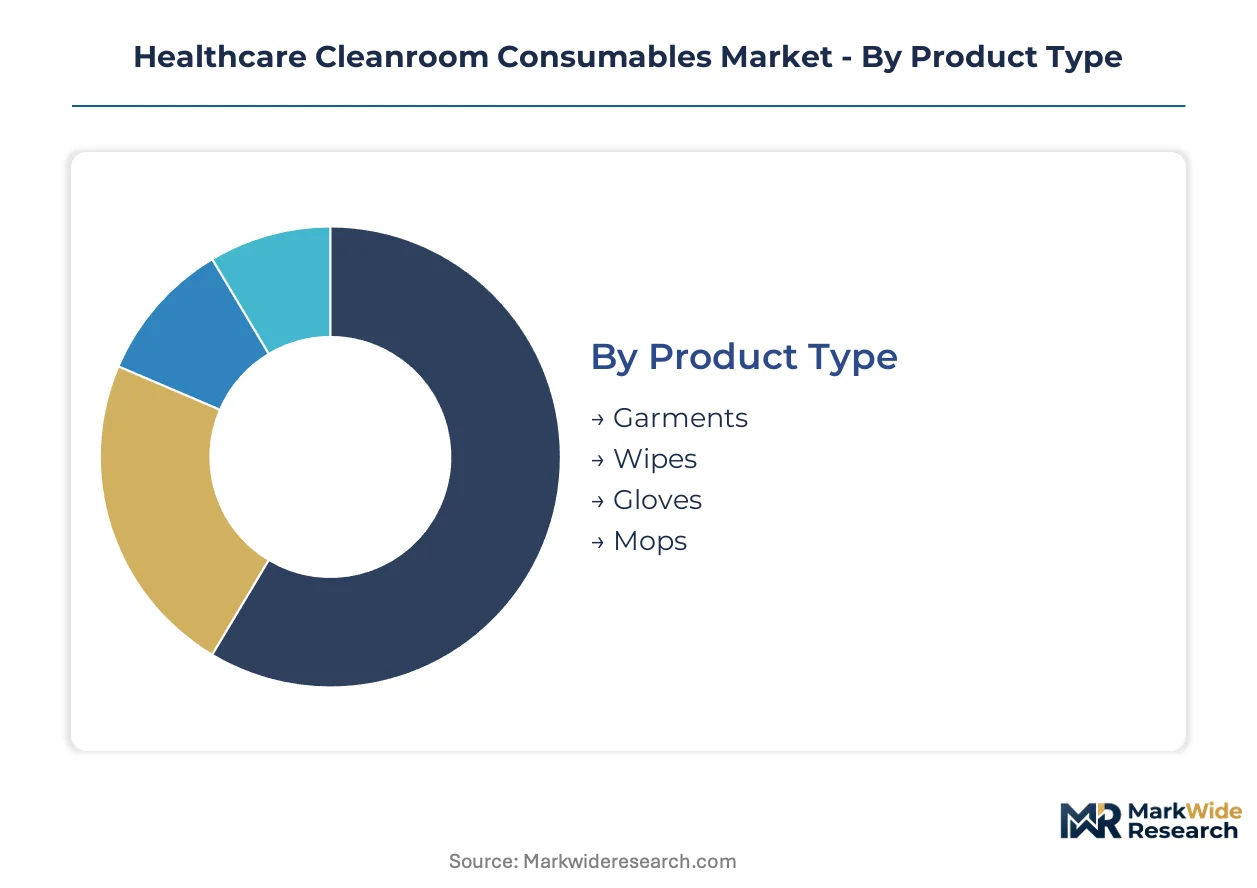
Cleanroom consumable procurement varies sharply across facility types and contamination control requirements. Material selection and change-out protocols differ between biologics manufacturing and medical device assembly, creating distinct demand profiles that suppliers must address through specialized product lines.
Product Type:
Cost tier separates these categories, with garments commanding premium pricing due to validation complexity while gloves and wipes compete on volume throughput.
- Garments:Engineered from spunbond-meltblown-spunbond laminates or polyester fabrics with embedded conductive fibers to meet ISO 14644-1 particulate thresholds. Pharmaceutical manufacturing facilities in the United States require sterile-to-the-bag supply models with documented shedding profiles, driving qualification costs upward.
- Gloves:Nitrile and neoprene formulations dominate biotechnology labs handling potent compounds, with demand concentrating in gene therapy manufacturing suites where double-gloving protocols multiply consumption rates.
- Wipes:Polyester-cellulose blends and pre-saturated isopropyl alcohol formats serve critical surface disinfection in Grade A/B environments.
- Mops:Flat mop systems with replaceable microfiber pads address floor contamination control in ISO Class 7 corridors.
Garments hold installed capacity. Gloves are rotating up the share rankings.
Application:
Application context determines barrier performance specifications and regulatory documentation burdens.
- Pharmaceutical Manufacturing:Aseptic processing of sterile injectables and biologics mandates FDA-validated consumables with extractables and leachables data packages. Facilities in Massachusetts and North Carolina consolidate procurement around vendors offering redundant manufacturing sites.
- Biotechnology Labs:Cell culture operations and gene therapy development require patient-dedicated consumable lots, multiplying garment change-out frequency per facility.
- Medical Device Production:EU MDR traceability mandates compel lot-level digital tracking for consumables contacting finished devices.
- Research Facilities:Academic and government labs operate under less stringent ISO Class 8 protocols, accepting lower-cost polypropylene alternatives.
Pharmaceutical Manufacturing anchors current revenue. Biotechnology Labs are climbing the fastest.
Material:
Supply concentration varies by polymer chemistry, with polypropylene feedstock tied to petrochemical indices.
- Polypropylene:Spunbond nonwoven fabrics achieve bacterial filtration efficiency above specified thresholds while reducing garment weight. Chinese production clusters create single-source dependencies for North American converters.
- Polyester:Continuous filament yarns with conductive carbon grids dissipate static in electronics-sensitive environments. Launderable variants retain cost advantage in less critical ISO Class 8 settings.
- Vinyl:PVC-based gloves serve lower-risk applications where chemical resistance requirements are moderate.
- Nylon:High-strength filaments reinforce high-wear garment zones and specialty wipe substrates.
Polypropylene dominates volume throughput. Polyester is gaining share fastest in reusable system alternatives.
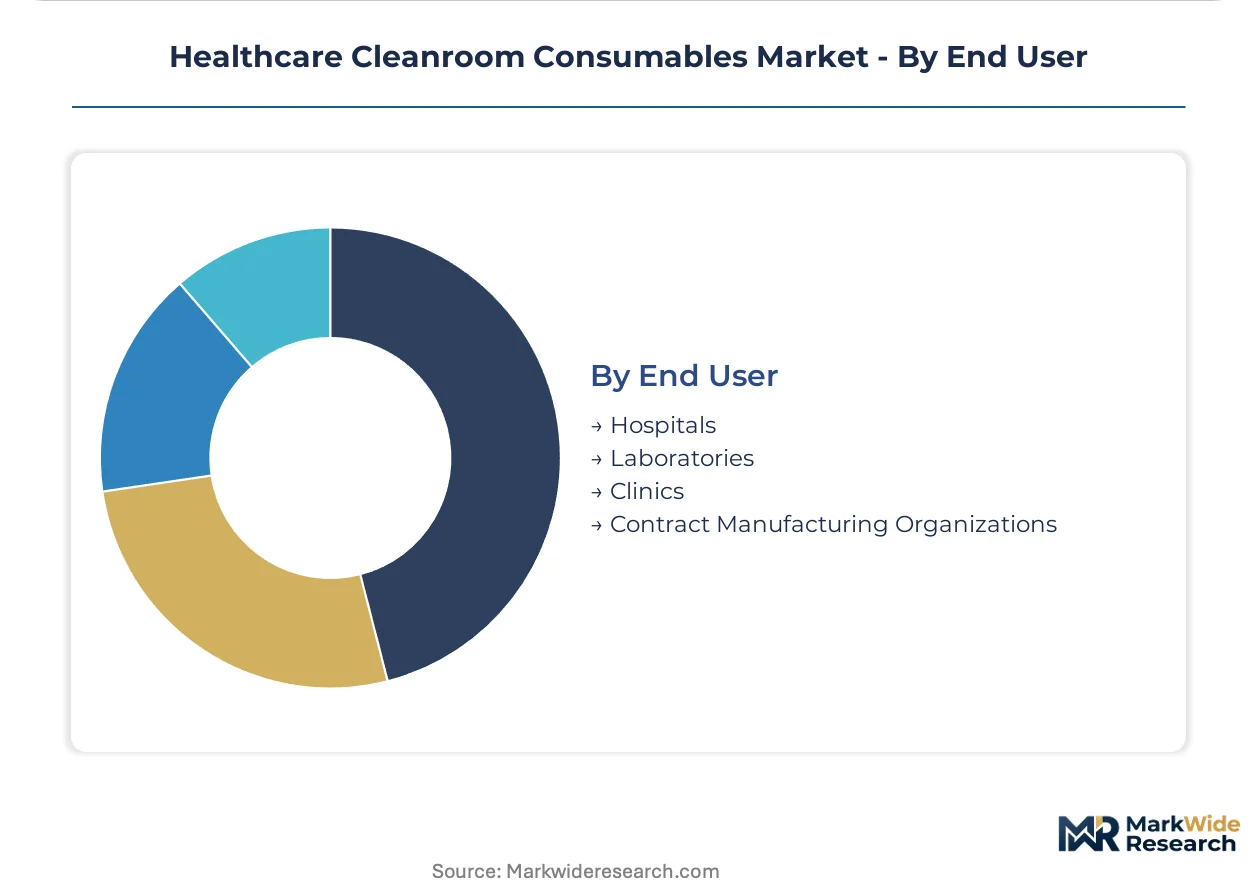
End User:
Customer type shapes procurement consolidation patterns and contract structures.
- Contract Manufacturing Organizations:Large CDMOs mandate single-source relationships for core garment categories, bundling wipes and gloves under multi-year quality agreements with unified sterile-to-the-bag supply models.
- Laboratories:Biotechnology and diagnostic labs require validated consumables with documented particulate shedding profiles for ISO 14644-1 compliance.
- Hospitals:Compounding pharmacies handling sterile preparations operate under USP <797> guidelines with moderate consumable specifications.
- Clinics:Outpatient surgical centers represent price-sensitive demand with limited barrier performance requirements.
Contract Manufacturing Organizations concentrate procurement volume. Laboratories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spunbond nonwoven fabric production clusters in China expose North American and European converters to freight volatility and customs delays. FDA enforcement in the United States and EMA protocols in Europe create divergent qualification requirements for suppliers serving dual-site manufacturing strategies.
United States
Biologics manufacturing capacity in Massachusetts and North Carolina generates concentrated demand for sterile-to-the-bag garment supply models. FDA aseptic processing guidance mandates documented particulate shedding limits for all consumables entering Grade A/B environments. Boston-Cambridge biotech corridor facilities consolidate procurement around vendors offering redundant manufacturing sites.
China
Domestic biopharma manufacturing scale-up in Shanghai and Suzhou is rewriting regional capacity dynamics for cleanroom consumables. NMPA alignment with international GMP standards accelerates local validation requirements for sterile garments. Yangtze River Delta production clusters now supply spunbond-meltblown-spunbond laminates to converters across Asia-Pacific.
Germany
Medical device manufacturers in Baden-Württemberg and Bavaria face tightened biocompatibility documentation under EU MDR implementation. EMA validation protocols for aseptic processing consumables diverge from FDA requirements, complicating dual-site supplier qualification. Stuttgart industrial corridor consolidates supplier panels around vendors with pre-submitted technical files.
India
CDSCO production-linked incentive schemes attract multinational biologics investments to Hyderabad and Bangalore manufacturing hubs. Central Drugs Standard Control Organization regulations require local validation support for sterile consumables entering commercial production. Telangana biopharma cluster expansion multiplies demand for patient-dedicated consumable lots in cell therapy suites.
Switzerland
Swissmedic oversight of sterile medicinal products maintains stringent traceability requirements for consumables contacting finished pharmaceuticals. Basel biopharma manufacturing concentration drives premium-tier procurement for validated barrier fabrics with extractables documentation. Alpine supply chain positioning enables just-in-time delivery to German and French border facilities.
Healthcare Cleanroom Consumables Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in material supply and regional conversion. The vendor base separates into three functional layers: multinational conglomerates with captive nonwoven capacity, mid-scale garment converters with sterile packaging infrastructure, and regional distributors handling logistics and local validation support. Consolidation pressure intensifies as contract manufacturing organizations mandate single-source relationships bundling garments, wipes, and gloves under unified quality agreements. Geographic redundancy and lot-level digital tracking capabilities now determine supplier survival.
Among North American material science conglomerates, DuPont and Kimberly-Clark Corporation occupy positions anchoring high-barrier fabric innovation and nonwoven supply chain control respectively. Thermo Fisher Scientific Inc. exemplifies the platform integration archetype, extending channel influence through consumable bundling with analytical instrumentation. These three entities represent distinct competitive vectors: advanced polymer R&D, spunbond manufacturing scale, and integrated laboratory supply ecosystems.
| Leading Market Players |
|---|
| DuPont |
| Kimberly-Clark Corporation |
| Valutek Inc. |
| Texwipe Company |
| Nitritex Ltd. |
| Thermo Fisher Scientific Inc. |
| Steris |
| Contec Inc. |
| Illinois Tool Works Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese spunbond nonwoven fabric production determines both pricing tier spreads and supply chain shape across North American and European cleanroom garment converters. Tariff exposure and freight cost volatility compress margins for mid-scale converters while rewarding multinational suppliers with redundant manufacturing sites and captive resin supply.
Pricing Analysis
FDA aseptic processing guidance dictates the pricing tier structure by mandating sterile-to-the-bag supply models with documented particulate shedding profiles. Three-tier pricing structure across premium, standard, and economy levels separates validated Grade A/B garments from ISO Class 7 consumables and unvalidated research-grade alternatives. Cost compression in the mid-tier is intensifying because petrochemical input volatility erodes converter margins. Contract manufacturing organizations exhibit the lowest price sensitivity due to bundled multi-year agreements, while academic research facilities face severe budget constraints.
Supply Chain Analysis
Large contract manufacturing organizations in Massachusetts and North Carolina hold concentrated procurement capacity, consolidating vendor panels around single-source relationships. Spunbond-meltblown-spunbond laminate production clusters in China, South Korea, and Germany anchor global supply. Raw material dependencies center on polypropylene resin, polyester continuous filament, and nitrile butadiene rubber. Single-source vulnerability in Yangtze River Delta fabric production exposes converters to customs delays and freight spikes. Distribution runs through sterile packaging facilities with lot-level digital tracking capabilities before reaching biopharma manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare cleanroom consumables represent an early-cycle expansion story as cell and gene therapy manufacturing multiplies garment change-out frequency per facility. Patient-dedicated production suite protocols create sustained pull for validated sterile-to-the-bag supply models.
For Market Incumbents: Pre-empt emerging biopharma manufacturing clusters in Hyderabad and Bangalore by establishing local validation support infrastructure before CDSCO incentive schemes mature. Secure redundant manufacturing sites to defend against single-source dependencies in Chinese spunbond production. Invest in recyclable polypropylene mechanical recycling pathways to capture ESG-driven procurement consolidation among large molecule manufacturers. For New Entrants and Emerging Players: Indian biopharma manufacturing expansion offers the most penetrable white-space target, with Telangana and Karnataka clusters lacking local sterile consumable validation capabilities. Cell therapy suites requiring patient-dedicated consumable lots present a second entry vector with premium pricing tolerance. Pursue CDSCO regulatory consulting partnerships as the primary go-to-market angle to accelerate commercial qualification timelines. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors mid-scale garment converters with sterile packaging infrastructure and geographic redundancy. Long-term viability hinges on suppliers capturing consolidated CDMO procurement contracts before vendor panel closure accelerates. Acquisition targets should demonstrate lot-level digital tracking platforms and pre-submitted EU MDR technical files. Watch for FDA enforcement actions on aseptic processing guidance as the inflection signal indicating qualification backlog severity.| Strategic Initiative | Industry Significance |
|---|---|
| Redundant Manufacturing Site Establishment | Mitigates single-source risk from Chinese spunbond clusters while satisfying CDMO geographic diversification mandates. |
| Closed-Loop Recycling Infrastructure | Enables Scope 3 emissions reporting for pharmaceutical operators under tightening ESG disclosure requirements. |
| CDSCO Validation Support Partnership | Accelerates market entry into Hyderabad and Bangalore biopharma corridors under production-linked incentive schemes. |
| Lot-Level Digital Tracking Platform | Complies with EU MDR traceability mandates for consumables contacting finished medical devices. |
| Extractables and Leachables Data Package Investment | Satisfies FDA biocompatibility documentation requirements for sterile processing consumables in Grade A/B environments. |
Study Parameters
Cross-validation between primary interviews with contamination control technicians, cleanroom facility managers, and regulatory affairs directors anchors the qualitative findings alongside secondary validation through FDA guidance documents, ISO 14644 certification records, and EMA aseptic processing inspection reports. Bottom-up triangulation across product type, application context, and material chemistry dimensions reconciles with top-down market sizing approaches.
Calibration against historical capacity expansion patterns in Massachusetts and North Carolina biologics manufacturing underpins the analytical framework across the projection horizon. Segmentation modeling incorporates cleanroom classification tier, end-user procurement structure, and regional regulatory cluster variations. CAGRs derive from facility expansion pipelines and change-out protocol evolution in cell therapy suites. Forecast inputs include biologics capacity buildout announcements and FDA inspection observation trends.
Practitioners should monitor petrochemical price indices, CDSCO regulatory harmonization milestones, and EU MDR notified body capacity constraints for early signals of forecast revision triggers. Quarterly review of FDA warning letter citations for aseptic processing violations and CDMO vendor consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Physiological Saline Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Laparoscopic Retrieval Bags Market