
 Sterile Container Market | 2026-2036
Sterile Container Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Container Market Outlook
Asset-light leasing models for sterilization equipment are reshaping competitive entry barriers in sterile container supply. STERIS leverages its installed base of sterilization systems to extend service contracts into container provisioning. B. Braun Melsungen AG anchors European hospital supply chains through backward integration into polymer sterilization trays. Medline Industries, Inc. competes on distribution density, positioning its container portfolio within broader surgical kit bundling programs.
Sterile containers are sealed, validated enclosures—typically polymer, glass, or composite constructions—engineered to maintain aseptic conditions for pharmaceuticals, medical devices, and biological specimens through terminal sterilization or aseptic processing. Their primary purpose is to prevent microbial ingress while permitting ethylene oxide, gamma irradiation, or steam-based sterilization without compromising barrier integrity. Plastic pouches dominate volume in healthcare disposables, where low-cost per-unit economics and compatibility with multiple sterilization modalities sustain margin pools in high-throughput hospital settings. Glass vials command premium positioning in parenteral pharmaceuticals, where USP Type I borosilicate requirements and extractables-leachables protocols differentiate suppliers serving biologics manufacturers.
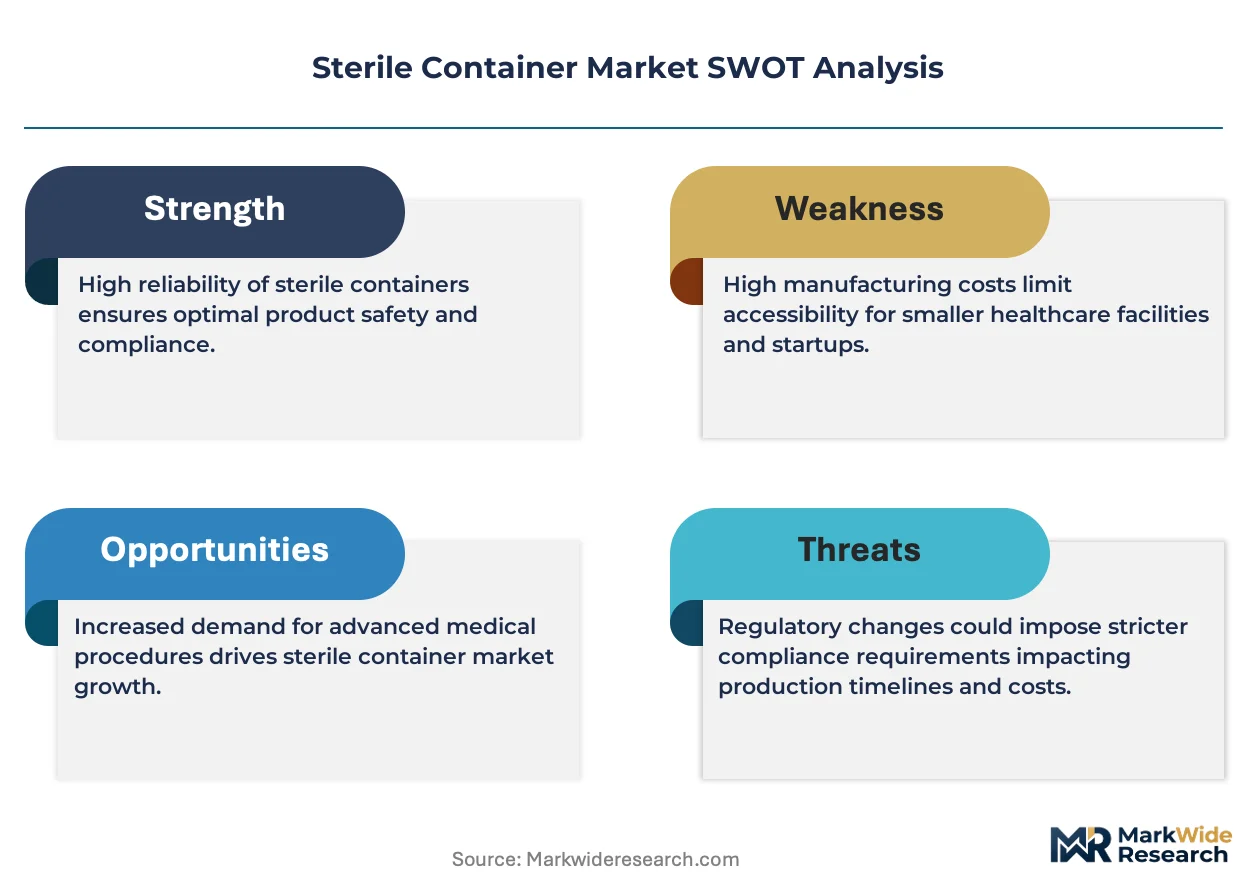
FDA guidance on container closure integrity testing and EU MDR technical documentation requirements are elevating validation burdens, filtering smaller suppliers from pharmaceutical-grade segments. ISO 11607 standards for sterile barrier systems shape design protocols across both medical device and drug packaging applications. Stakeholders must monitor evolving pharmacopeial extractables testing thresholds and regional sterilization modality preferences to align capacity investments with shifting compliance and customer specifications.
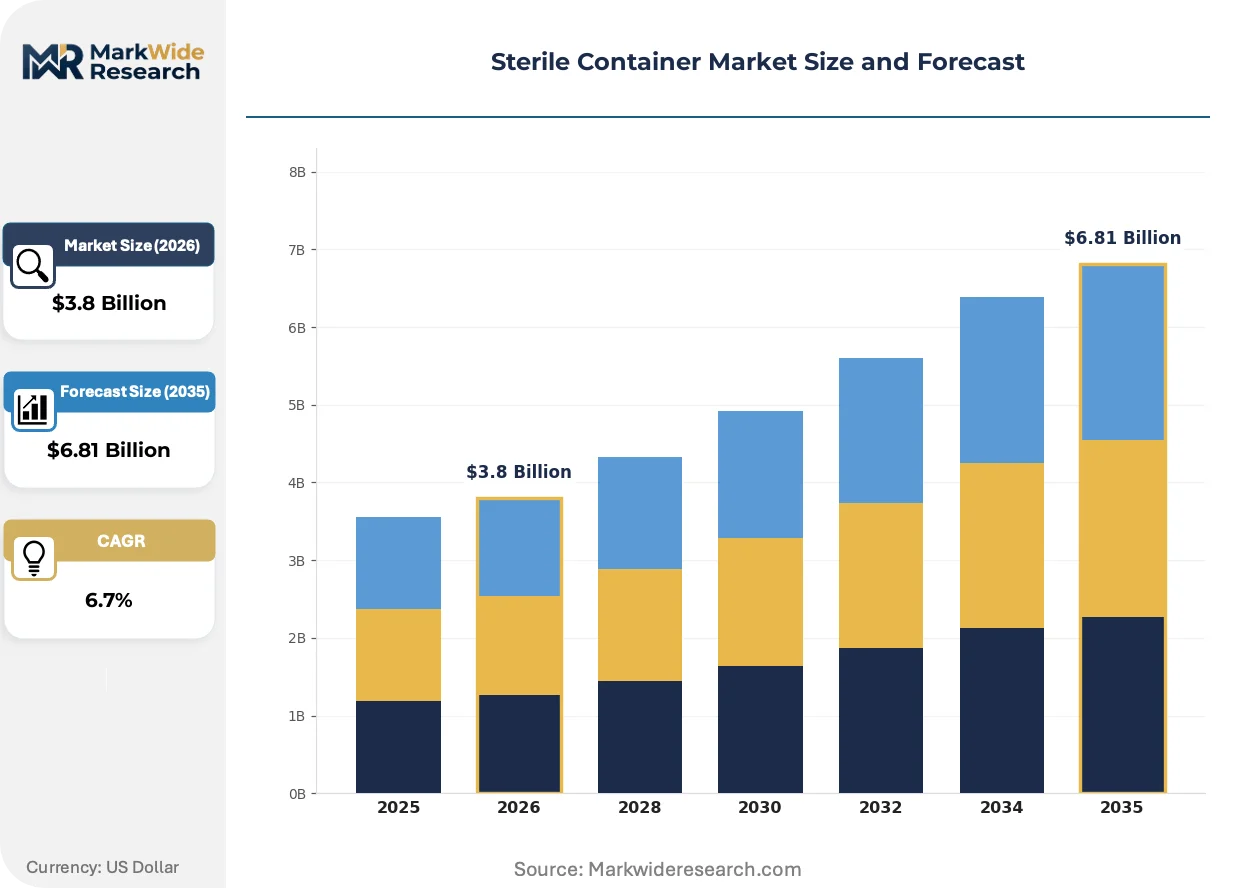
Market Dynamics
FDA container closure integrity guidance and EU MDR technical documentation mandates are compressing supplier qualification timelines while biologics manufacturers demand higher-performance barrier systems for temperature-sensitive therapies.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapy developers require specialized polymer and composite containers compatible with cryogenic storage and aseptic filling lines.
- EU MDR implementation:Medical device manufacturers must revalidate sterile barrier systems under stricter technical documentation requirements, creating replacement demand for compliant container portfolios.
- German sterilization infrastructure:Concentrated contract manufacturing clusters around Frankfurt and Munich anchor European supply chains for pharmaceutical-grade container provisioning.
Market Restraints
- Raw material concentration:USP Type I borosilicate glass supply concentrates among limited European and Asian specialty glass manufacturers, exposing pharmaceutical vial producers to input volatility.
- Validation cost escalation:Extractables-leachables testing protocols under USP 1661 and 1663 require extended analytical timelines that filter smaller suppliers from pharmaceutical segments.
- Polymer substitution limits:Cyclic olefin polymer alternatives face adoption barriers in high-value biologics where glass's oxygen barrier and regulatory precedent sustain incumbent positioning.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH Q1 stability guidelines and expanding biologics capacity create demand for validated sterile containers in parenteral drug production.
- Cold chain integration:Temperature-indicating smart labels converging with RFID tracking enable premium container differentiation for cell therapy logistics requiring chain-of-custody documentation.
- Reusable surgical container systems:Hospital sustainability mandates in Germany and France favor sterilizable polymer trays over single-use alternatives, opening service-based revenue models.
Industry Challenges
- Container closure integrity validation:Vacuum decay and helium leak testing methods require specialized equipment and trained analytical chemists that concentrate among contract laboratories.
- Legacy sterilization modality lock-in:Ethylene oxide-dependent supply chains face reconfiguration pressure as EPA emissions restrictions and hospital decontamination preferences shift toward gamma and e-beam alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Container Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Vials, Jars, Bags Material: Plastic, Glass, Metal, Composite End User: Pharmaceuticals, Healthcare Facilities, Laboratories, Biotechnology Size: Small, Medium, Large, Extra Large |
| Companies Covered | STERIS, Symmetry Surgical Inc., Aesculap, Wagner, Integra LifeSciences, B. Braun Melsungen AG, KLS Martin Group, Ritter Medical, Medline Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Container Market Strategic Shifts
Digital validation protocols and advanced barrier materials are compressing development timelines while regulatory harmonization efforts reshape competitive qualification requirements across pharmaceutical and medical device segments.
Digital twin simulation software is virtualizing container design validation by modeling sterilization modality compatibility and barrier integrity under stress conditions before physical prototyping. Biologics manufacturers in Switzerland and Massachusetts are adopting these platforms to accelerate qualification timelines. This virtualization compresses traditional 18-24 month validation cycles and reduces material waste from iterative physical testing.
REACH restrictions on phthalate plasticizers and EU MDR substance disclosure requirements are forcing reformulation of polymer container additives. Manufacturers serving European medical device markets must substitute legacy plasticizers with bio-based alternatives and document supply chain transparency. German dental and surgical instrument sterilization tray producers face the steepest compliance burdens under these overlapping chemical and medical device regulations.
Hospital group purchasing organizations are consolidating sterile container procurement under bundled surgical kit contracts that specify performance metrics rather than discrete product specifications. Medline and Owens & Minor are capturing volume through distribution density and kit assembly capabilities. This concentration is most visible in US integrated delivery networks where standardization across facility footprints drives single-source container commitments.
Sterile Container Market Segmentation
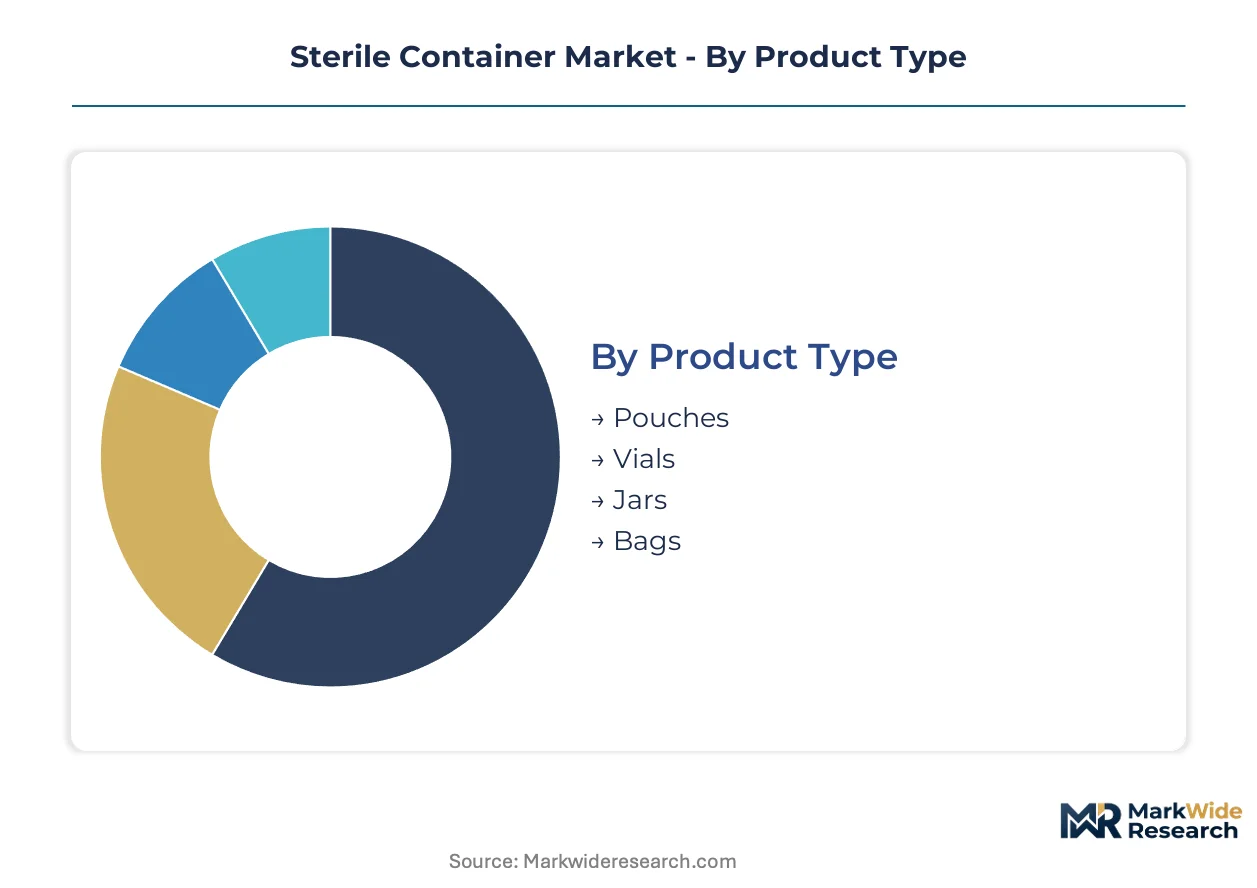
Sterile container procurement patterns diverge sharply across material grades, product formats, and end-use compliance requirements. Each segmentation dimension carries distinct validation protocols and margin structures that reshape supplier positioning.
Product Type:
Application requirements dictate format selection across terminal sterilization compatibility and barrier performance needs.
- Pouches:Multi-layer polymer laminates with breathable Tyvek or medical-grade paper windows accommodate ethylene oxide and gamma sterilization. Hospital central supply departments in Germany and France standardize on peelable pouch formats for surgical instrument sets, driven by single-use economics and throughput requirements in high-volume decontamination cycles.
- Vials:USP Type I borosilicate glass constructions with elastomeric closures and aluminum seals maintain parenteral drug stability. Swiss biologics manufacturers and Massachusetts cell therapy developers concentrate demand here, where extractables-leachables protocols and container closure integrity validation under FDA guidance sustain premium positioning.
- Jars:Wide-mouth polymer or glass configurations serve topical pharmaceutical and medical device sterilization needs.
- Bags:Flexible film constructions accommodate large-volume parenteral solutions and biological fluid containment.
Pouches command the established base. The steepest expansion runs through vials.
Material:
Cost tier and performance specifications segment the supply base across regulatory validation intensity.
- Plastic:Polyethylene, polypropylene, and cyclic olefin polymer formulations dominate disposable healthcare applications. Indian pharmaceutical manufacturers expanding under CDSCO's ICH-aligned guidelines are scaling polymer container adoption for parenteral generics, where cost per unit and sterilization modality flexibility outweigh glass's oxygen barrier advantages.
- Glass:Borosilicate and soda-lime compositions serve high-value biologics where oxygen ingress sensitivity and regulatory precedent matter. European specialty glass manufacturers concentrate supply, exposing vial producers to input volatility under REACH substance disclosure requirements.
- Metal:Aluminum and stainless steel enclosures serve reusable surgical instrument sterilization systems.
- Composite:Hybrid polymer-barrier constructions address cryogenic storage and specialized cell therapy logistics.
Plastic captures volume leadership. Composite materials are climbing the fastest.
End User:
Customer type determines validation depth, procurement scale, and service model requirements.
- Pharmaceuticals:Drug manufacturers require container closure integrity documentation, stability data, and DMFs for regulatory filings. EU MDR technical documentation mandates and FDA sterile drug guidance are compressing supplier qualification timelines for barrier systems serving biologics and injectable therapies.
- Healthcare Facilities:Hospital systems prioritize sterilization throughput and standardization across integrated delivery networks. German and French sustainability mandates favor reusable polymer tray systems over disposables, opening service-based revenue models for sterilization equipment lessors.
- Laboratories:Diagnostic and research applications demand specimen integrity across transport and storage.
- Biotechnology:Cell and gene therapy developers need cryogenic-compatible containers with chain-of-custody documentation.
Healthcare facilities anchor procurement volume. Biotechnology applications show the steepest expansion trajectory.
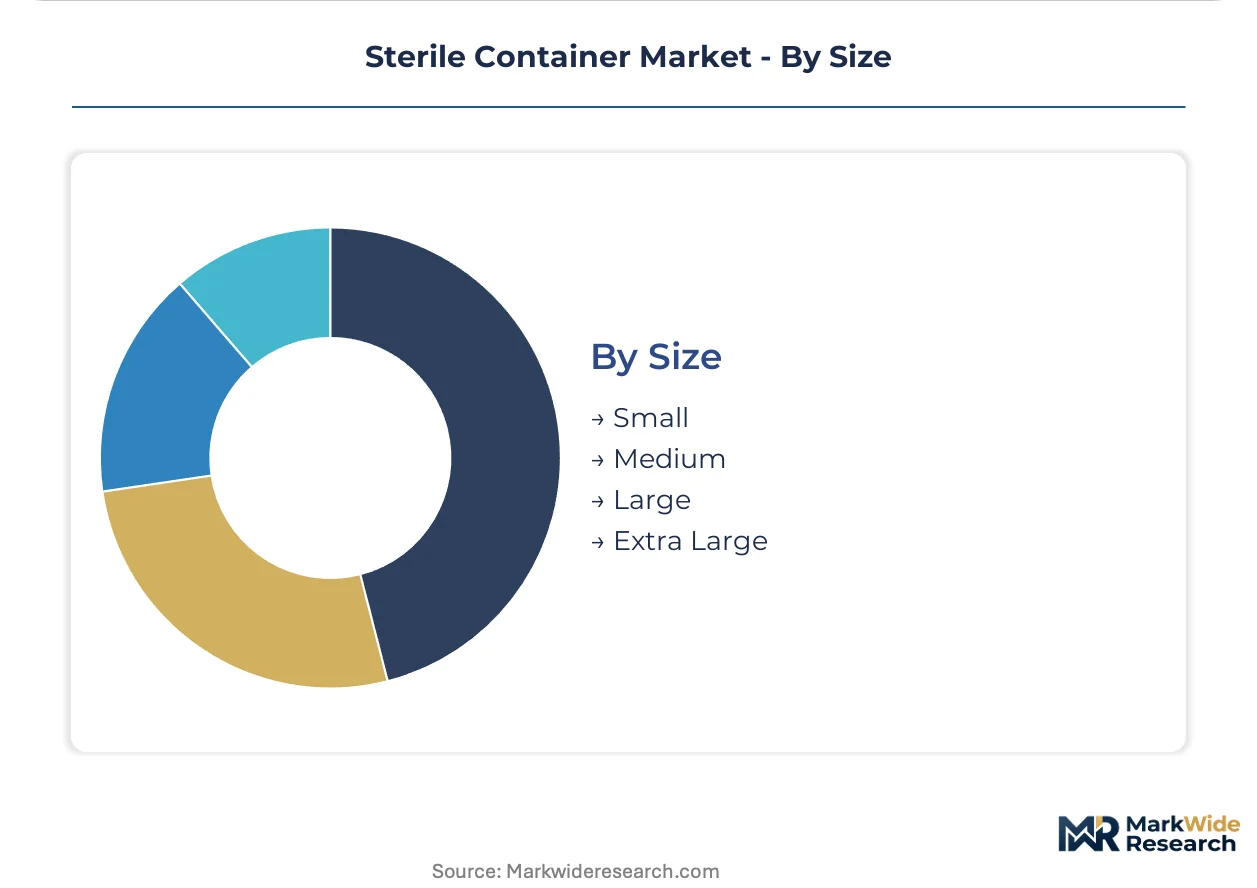
Size:
Volume scale segments manufacturing equipment requirements and distribution economics.
- Small:Single-dose vials and specimen containers serve precision dosing and diagnostic sampling.
- Medium:Standard surgical kits and multi-dose pharmaceutical formats balance handling efficiency with sterility maintenance.
- Large:Bulk solution containers and instrument sets accommodate centralized sterilization operations.
- Extra Large:Specialized bioreactor feed systems and bulk API storage configurations serve contract manufacturing scale.
Medium sizes dominate unit economics. Extra large formats are expanding most quickly on biologics manufacturing scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial sterile container trade surplus, exporting precision-engineered polymer trays and glass vials to pharmaceutical manufacturers across Europe and North America. Import dependence concentrates in specialized borosilicate glass feedstocks from Switzerland and Austria. Regional supply chains organize around sterilization service clusters and contract manufacturing hubs that dictate container specification standards.
Germany
Frankfurt and Munich anchor European pharmaceutical-grade container provisioning through concentrated sterilization infrastructure and contract manufacturing clusters. The country's national pharmaceutical regulator enforces EU MDR technical documentation requirements that compress supplier qualification timelines for barrier systems. Baden-Württemberg specialty glass manufacturers supply USP Type I borosilicate to domestic vial producers under REACH substance disclosure mandates.
United States
Massachusetts cell therapy developers and Swiss biologics manufacturers with US operations concentrate demand for high-performance glass vials with container closure integrity validation. FDA sterile drug guidance elevates extractables-leachables testing burdens that filter smaller suppliers from pharmaceutical segments. The Greater Boston corridor hosts digital twin simulation adoption for virtualizing container design validation before physical prototyping.
Switzerland
Swissmedic oversight of biologics manufacturing sustains premium positioning for borosilicate glass containers with oxygen barrier specifications. The country's pharmaceutical regulator maintains stringent stability data requirements that align with ICH Q1 guidelines. Basel and Zurich host specialized polymer and composite container development for cryogenic storage applications in cell and gene therapy logistics.
India
CDSCO alignment with ICH stability guidelines drives scaling of polymer container adoption for parenteral generics manufacturing. The national pharmaceutical regulator's quality standards are tightening validation protocols for sterile barrier systems in injectable drug production. Maharashtra and Gujarat pharmaceutical manufacturing clusters are expanding biologics capacity that demands validated container closure integrity documentation.
France
Hospital sustainability mandates favor reusable polymer tray systems over single-use alternatives in surgical instrument sterilization. The national medical device regulator enforces EU MDR substance disclosure requirements that force reformulation of container additives. Paris and Lyon healthcare procurement networks are consolidating sterile container purchasing under bundled surgical kit contracts with performance-based specifications.
Sterile Container Market Competitive Environment
On the supply side, the industry is consolidating around sterilization equipment lessors extending service contracts into container provisioning and distribution-intensive players capturing volume through surgical kit bundling. Three strategic archetypes dominate: sterilization infrastructure operators leveraging installed equipment bases, backward-integrated hospital supply chains controlling polymer tray production, and distribution-density competitors positioning containers within broader procedural kit assemblies. M&A activity concentrates on sterilization service capabilities and geographic expansion into Indian pharmaceutical manufacturing corridors.
Among sterilization infrastructure operators, STERIS exemplifies the equipment-to-service extension model, while B. Braun Melsungen AG occupies a position anchoring European hospital supply chains through in-house production of polymer sterilization trays. Medline Industries, Inc. sits within the distribution-density archetype, competing on surgical kit assembly capabilities and procurement consolidation across integrated delivery networks. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| STERIS |
| Symmetry Surgical Inc. |
| Aesculap |
| Wagner |
| Integra LifeSciences |
| B. Braun Melsungen AG |
| KLS Martin Group |
| Ritter Medical |
| Medline Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors govern landed cost dynamics for USP Type I borosilicate glass feedstocks, concentrating pricing power among German and Swiss specialty manufacturers while forcing polymer container producers to absorb volatility through contract structures.
Pricing Analysis
Pharmaceutical manufacturers anchor contract-based long-term offtake pricing across sterile container procurement. Three-tier pricing structure across premium, standard, and economy levels separates USP Type I borosilicate vials with full DMF documentation from polymer alternatives with basic ISO 11607 validation. Cost compression in standard-grade polymer pouches is intensifying because Indian pharmaceutical manufacturers are scaling generic injectables output. Hospital group purchasing organizations exhibit the sharpest price sensitivity, while cell therapy developers show minimal elasticity for cryogenic-compatible composite containers.
Supply Chain Analysis
Export-control restrictions on advanced polymer-barrier technologies limit composite container flows from Swiss and German developers to Indian pharmaceutical corridors. Raw material supply concentrates in Germany, Switzerland, and Austria for specialty borosilicate glass, while polymer resin production feeds from South Korean and Saudi Arabian petrochemical complexes. Single-source vulnerability concentrates in European specialty glass manufacturers serving FDA-regulated drug packaging. Distribution runs through sterilization service lessors extending equipment contracts into container provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable polymer surgical tray systems represent a substitution threat that incumbent disposable container suppliers must neutralize through service-model reinvention.
For Market Incumbents: Build regulatory documentation moats by pre-investing in extractables-leachables testing protocols under USP 1661 and 1663 ahead of FDA guidance tightening. Acquire sterilization equipment lessors in German contract manufacturing clusters to lock in hospital system relationships against reusable tray substitution. Backward integration into polymer compounding secures formulation control as REACH restrictions on phthalate plasticizers force additive reformulation.
For New Entrants and Emerging Players: Cryogenic-compatible composite containers for cell therapy logistics in Massachusetts and Basel represent the most penetrable entry point given validation bottleneck concentration among incumbent glass suppliers. Indian pharmaceutical manufacturing corridors under CDSCO's ICH-aligned guidelines offer white-space demand for validated polymer alternatives to borosilicate. Partner with digital twin simulation platforms to compress qualification timelines for biologics manufacturers facing compressed FDA review schedules.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underoptimized sterile barrier system portfolios lacking EU MDR technical documentation capabilities. Long-term viability hinges on exposure to biologics pipeline expansion rather than commodity hospital disposables. Watch FDA container closure integrity guidance revision timing as inflection indicator for validation service demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Pre-Investment | USP 1661 extractables testing capabilities filter smaller competitors from pharmaceutical-grade segments. |
| Sterilization Service Integration | Equipment lessors like STERIS extend container provisioning contracts through installed base leverage. |
| Cryogenic Composite Development | Cell therapy logistics in Basel and Massachusetts demand barrier systems compatible with liquid nitrogen storage. |
| Indian Manufacturing Corridor Expansion | CDSCO alignment with ICH Q1 guidelines creates validated container demand for parenteral generics scale-up. |
| Digital Twin Validation Adoption | Virtual prototyping platforms compress 18-month qualification cycles for biologics manufacturers in Switzerland. |
Study Parameters
Operator-level perspectives from sterilization equipment managers, pharmaceutical packaging engineers, hospital central supply directors, and contract manufacturing quality leads anchored the qualitative base. Primary interviews combined with secondary validation against FDA guidance documents, EU MDR technical documentation requirements, ISO 11607 standards filings, and REACH substance disclosure databases. Bottom-up container volume estimates triangulated against top-down pharmaceutical manufacturing capacity data across German, Swiss, and Indian production clusters.
Scenario-bracketing framed the analytical approach across the analysis window, modeling demand trajectories under varying biologics pipeline expansion rates and regulatory harmonization assumptions. Segmentation dimensions included material grade, sterilization modality compatibility, end-use compliance tier, and regional regulatory cluster. CAGRs derived from weighted average growth across product-format segments, with specific inputs from container closure integrity validation timelines and EU MDR implementation pacing.
Macroeconomic conditions sit as an overlay; deviation in freight rates through Rotterdam-Antwerp corridors or specialty glass feedstock availability would shift the trajectory. Material shifts in FDA sterile drug guidance stringency or EPA ethylene oxide emissions restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Saudi Arabia Medical Bandages Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
First Aid Kit Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Global Unna Boot Market