
 Argentina Passenger Vehicles Lubricants Market | 2026-2036
Argentina Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Passenger Vehicles Lubricants Market Outlook
Brazil's lubricant blending capacity expansion is reconfiguring supply dynamics across the Southern Cone. YPF S.A. leverages its captive refinery network to dominate domestic base stock supply. Shell Argentina S.A. competes through controlled access to premium synthetic formulations. ExxonMobil Argentina anchors its position via deep distribution into independent service workshops.
Argentina passenger vehicles lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission systems, with viscosity grades typically ranging from 0W-20 to 15W-40 under SAE classifications. These fluids serve the essential commercial purpose of extending engine operational life while maintaining fuel efficiency across Argentina's aging passenger car parc. Engine oil formulations command the largest volume share within product type segments, reflecting the density of vehicles requiring frequent drain intervals. Synthetic and semi-synthetic formulations are expanding fastest as IRAM-aligned workshops upgrade service standards. Retail outlets and service stations together capture the dominant margin pool in distribution channels due to bundled labor-and-fluid service models.
Argentina's Secretariat of Industry and Productive Development enforces IRAM lubricant labeling and performance standards that dictate minimum additive package requirements for domestic sale. The National Directorate of Chemicals and Fuels under the Ministry of Environment monitors waste oil collection and re-refining quotas that shape circular economy participation. Stakeholders must track pending Mercosur technical harmonization protocols that could unify specification requirements across member states.
Market Dynamics
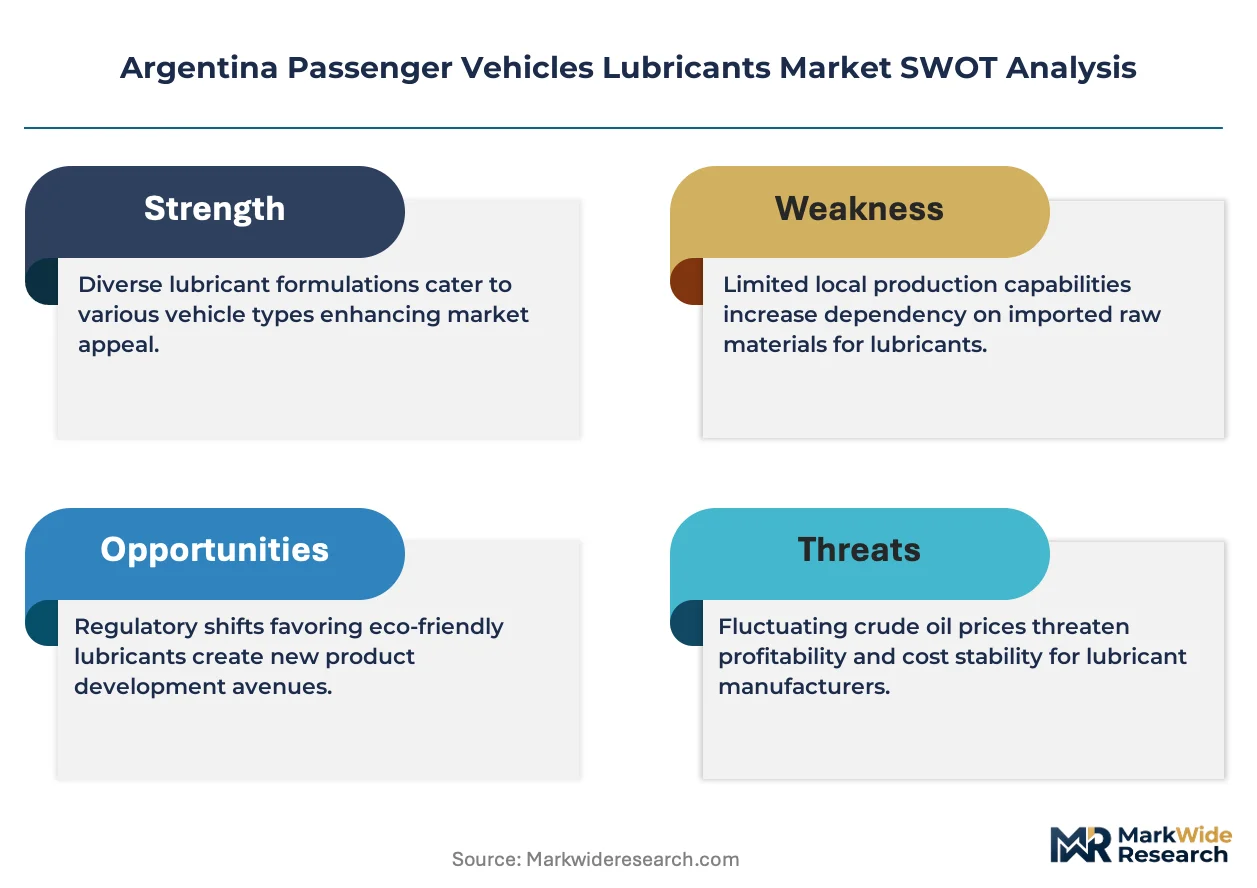
Argentina's passenger vehicle lubricants sector is undergoing structural recalibration as IRAM quality standards tighten additive package specifications and captive refinery supply chains lock in domestic base oil allocation. Fleet operators in Buenos Aires and Córdoba are compressing drain intervals through predictive maintenance protocols.
Growth Catalysts
- IRAM lubricant labeling standards:Mandatory performance specifications under the Secretariat of Industry and Productive Development are forcing formulation upgrades across service workshops.
- Urban fleet preventive maintenance expansion:Buenos Aires and Córdoba operators are institutionalizing shorter oil change cycles to minimize downtime costs.
- Pampas automotive service corridor density:The Rosario-La Plata axis concentrates vehicle population and service infrastructure, creating localized demand pull.
Market Restraints
- Base oil supply concentration:Domestic refinery capacity limitations tie blenders to YPF S.A.'s captive supply network, constraining formulation flexibility.
- Import substitution policy friction:Ministry of Productive Development restrictions on additive imports complicate access to advanced synthetic packages.
- Waste oil re-refining quota compliance:National Directorate of Chemicals and Fuels mandates impose collection infrastructure costs on smaller distributors.
Strategic Opportunities
- Mercosur technical harmonization protocols:Pending unification of specification requirements could open cross-border formulation standardization for Argentine blenders.
- Synthetic and semi-synthetic upgrade cycles:IRAM-aligned workshops represent an emerging channel for premium product conversion.
- Independent service workshop consolidation:Fragmented maintenance providers in secondary cities present acquisition targets for organized distribution networks.
Industry Challenges
- Formulation chemist scarcity:Specialized talent capable of balancing IRAM compliance with cost-optimized additive dosing remains concentrated at major blenders.
- Legacy parc compatibility complexity:Argentina's aging vehicle fleet requires multi-grade inventory management that strains working capital.
- Re-refining facility capex requirements:Circular economy participation demands investment in waste oil processing infrastructure that mid-tier distributors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Passenger Vehicles Lubricants Market |
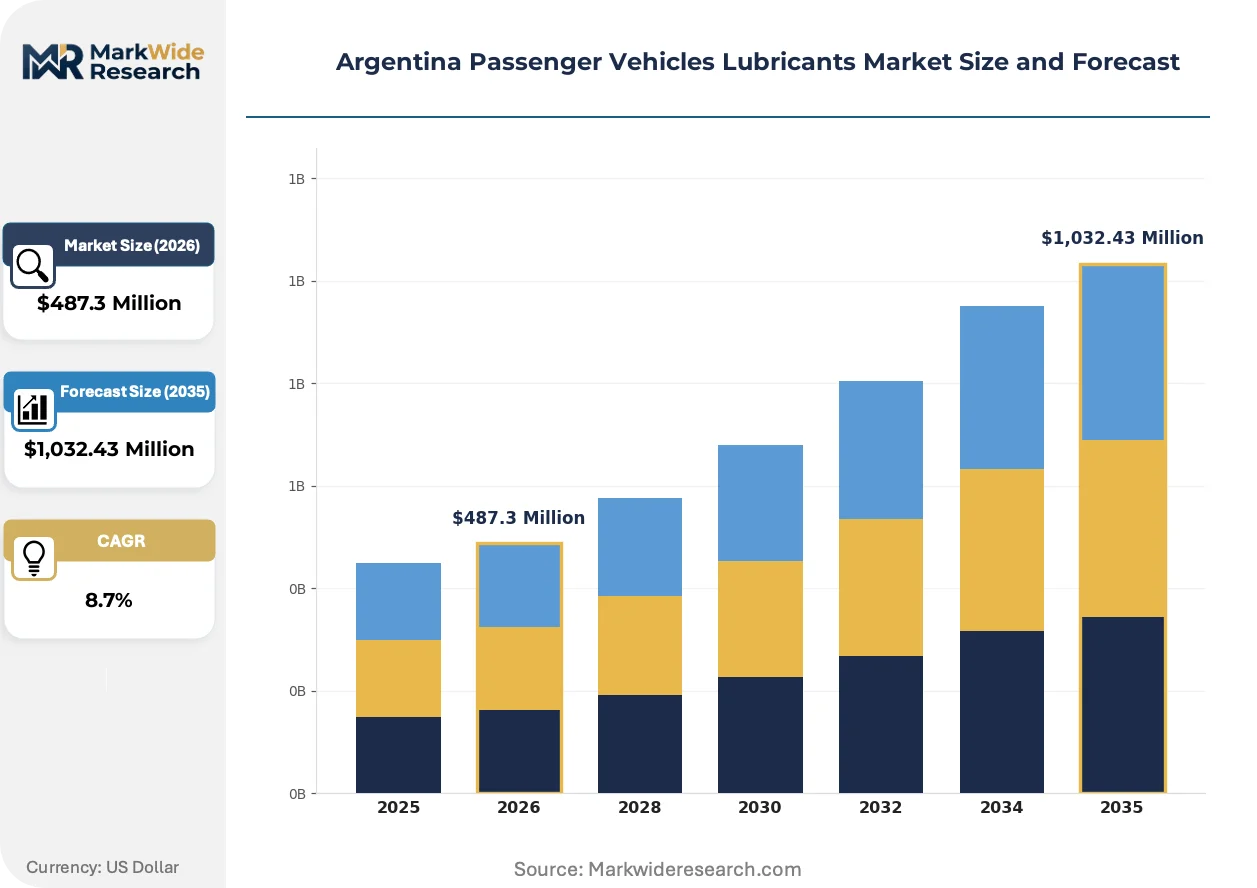
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid Formulation: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Oil Application: Automotive, Light Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Distribution Channel: Retail Outlets, Online Stores, Service Stations, Wholesale Suppliers |
| Companies Covered | YPF S.A., Petrobras Argentina S.A., Shell Argentina S.A., ExxonMobil Argentina, TotalEnergies, BP PLC (Castrol), Puma Energy, Fercol Lubricantes, Gulf Oil International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Passenger Vehicles Lubricants Market Strategic Shifts
Digital integration of maintenance scheduling and fluid monitoring is compressing traditional service intervals across Argentina's fleet sector. Workshop management systems now tie lubricant procurement directly to vehicle telematics.
Telematics-enabled oil condition monitoring is digitizing fleet maintenance decisions. Large operators in Buenos Aires are deploying sensor arrays that transmit viscosity degradation data in real time. This infrastructure is digitizing the relationship between drain intervals and actual engine stress, collapsing the historical time-based service model.
IRAM's lubricant performance certification protocols are tightening additive minimums for domestic sale. The Secretariat of Industry and Productive Development now requires documented cold-crank viscosity retention under modified test cycles. Passenger vehicles operating in Patagonia's temperature extremes face the most stringent compliance verification, pushing blenders toward pour-point depressant investments.
Fleet procurement is consolidating around bundled fluid-and-labor contracts that disaggregate traditional retail margins. Large operators in Córdoba are negotiating direct supply agreements that bypass service station networks. This concentration is most visible among urban logistics providers managing compressed TCO targets through volume-commitment pricing.
Argentina Passenger Vehicles Lubricants Market Segmentation
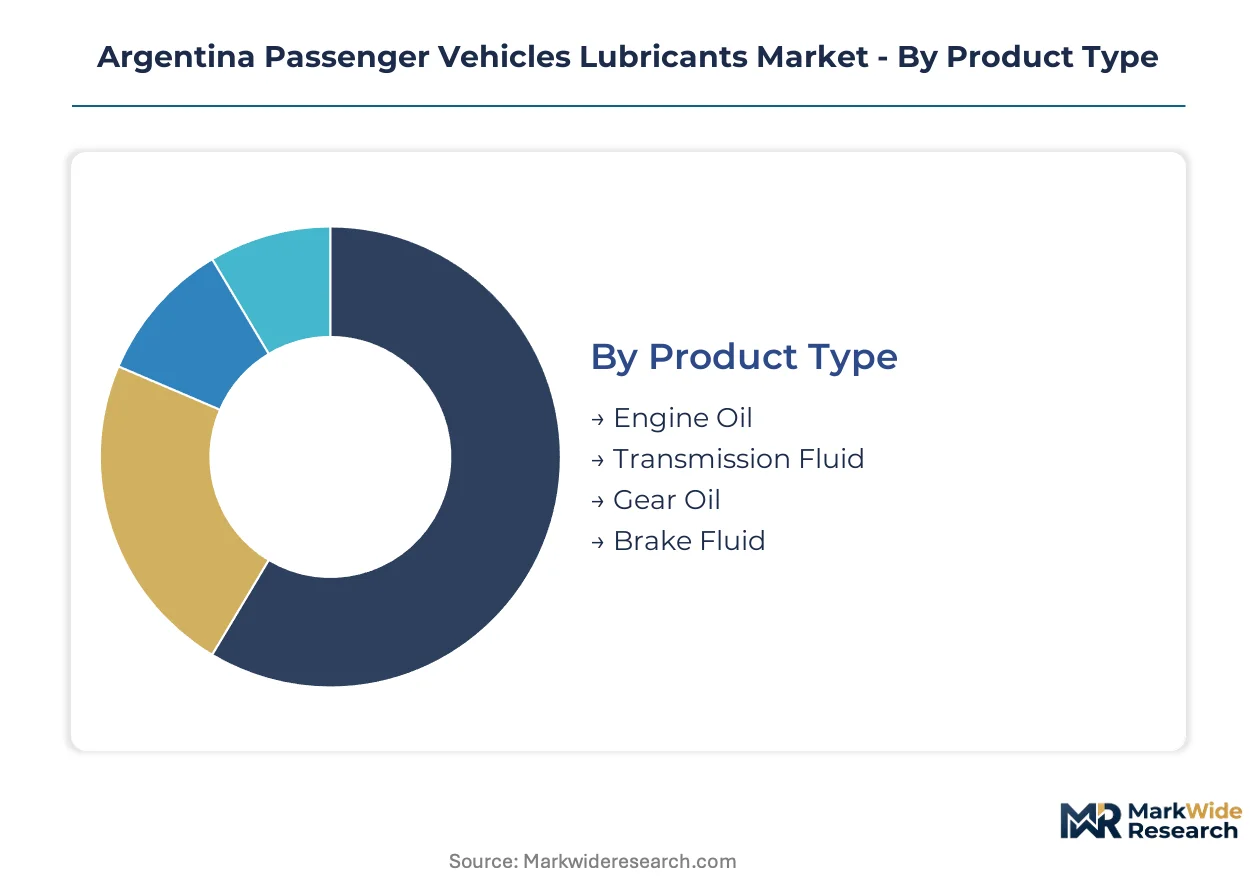
Argentina's lubricant market structure reflects the tension between legacy vehicle maintenance patterns and synthetic upgrade cycles. Segmentation by formulation type and distribution channel captures where margin pools are shifting as IRAM-aligned workshops professionalize service standards.
Product Type:
Application specificity determines additive package complexity and drain interval economics across Argentina's vehicle parc.
- Engine Oil:Formulations blend base stocks with detergent-dispersant and anti-wear additive packages calibrated to SAE viscosity grades from 0W-20 through 15W-40. Demand concentrates in Buenos Aires metropolitan workshops where fleet operators compress change intervals through predictive maintenance protocols. IRAM cold-crank viscosity standards push blenders toward pour-point depressant investments for Patagonia-servicing products.
- Transmission Fluid:Specialized friction-modified formulations serve automatic and dual-clutch architectures with distinct viscosity stability requirements. The Pampas automotive corridor from Rosario to La Plata generates concentrated pull as transmission rebuild specialists upgrade fluid specifications.
- Gear Oil:Extreme-pressure formulations protect hypoid gear sets through sulfur-phosphorus additive chemistry.
- Brake Fluid:Glycol-ether and silicone-based formulations meet DOT 3, DOT 4, and DOT 5.1 boiling point specifications.
Engine oil holds installed capacity. Transmission fluid is rotating up the share rankings.
Formulation:
Cost tier stratification separates commodity mineral sales from synthetic margin capture across service channels.
- Mineral Oil:Solvent-refined base stocks dominate legacy vehicle servicing in secondary cities where price sensitivity constrains workshop procurement. Argentina's aging passenger car parc sustains volume through compatibility requirements that strain working capital for multi-grade inventory management.
- Synthetic Oil:Poly-alpha-olefin and ester-based formulations deliver thermal stability for turbocharged engines and extended drain intervals. IRAM-aligned workshops in Córdoba represent the fastest-expanding channel as fleet operators institutionalize shorter change cycles to minimize downtime costs.
- Semi-Synthetic Oil:Blended formulations balance performance upgrade with cost containment for mid-tier service providers.
- Bio-Based Oil:Vegetable-derived base stocks serve niche environmental compliance applications.
Mineral oil anchors volume throughput. Synthetic formulations are climbing the fastest.
Application:
Customer type segmentation reveals where bundled fluid-and-labor contracts are disaggregating traditional retail margins.
- Automotive:Passenger car lubricants span internal combustion and emerging hybrid architectures with distinct thermal management requirements. Urban fleet operators in Buenos Aires negotiate direct supply agreements that bypass service station networks through volume-commitment pricing structures.
- Light Commercial Vehicles:High-load formulations protect engines under stop-start delivery cycles with enhanced soot-handling additive packages. Córdoba logistics providers managing compressed TCO targets drive procurement consolidation around integrated maintenance contracts.
- Motorcycles:Wet-clutch-compatible formulations balance engine and transmission lubrication in shared sump designs.
- Heavy-Duty Trucks:Extended-drain formulations serve long-haul operators through enhanced TBN retention chemistry.
Automotive absorbs the dominant share. Light commercial vehicles are gaining share fastest.
Distribution Channel:
Supply concentration shapes margin capture as procurement digitization compresses intermediary layers.
- Retail Outlets:Counter sales serve DIY maintenance segments with packaged lubricants in standard viscosity grades. The Pampas corridor's density of automotive service infrastructure sustains localized inventory positioning.
- Service Stations:Bundled fluid-and-labor models capture premium pricing through immediate installation capacity. Buenos Aires operators are deploying telematics-enabled oil condition monitoring that transmits viscosity degradation data in real time.
- Online Stores:Direct-to-workshop platforms aggregate procurement for independent service providers.
- Wholesale Suppliers:Volume distributors serve secondary city networks with consolidated logistics.
Service stations command premium positioning. Online stores are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
YPF S.A.'s captive refinery network locks domestic base oil allocation to Argentine blenders, while Brazilian capacity expansion redraws Southern Cone supply maps. This concentration shapes procurement patterns across Mercosur's automotive service corridors.
Buenos Aires Metropolitan Area
Urban fleet operators compress drain intervals through predictive maintenance protocols tied to telematics systems. The Secretariat of Industry and Productive Development enforces IRAM labeling standards that mandate additive package upgrades. The Greater Buenos Aires automotive service corridor concentrates premium synthetic demand as IRAM-aligned workshops professionalize.
Córdoba Industrial Belt
Logistics providers managing compressed TCO targets drive procurement consolidation around bundled fluid-and-labor contracts. The Ministry of Productive Development's import substitution policies restrict additive imports for advanced synthetic formulations. Córdoba's independent service workshop density presents acquisition targets for organized distribution networks.
Rosario-La Plata Pampas Corridor
The Pampas region's vehicle population density creates localized demand pull for multi-grade inventory positioning. National Directorate of Chemicals and Fuels mandates impose waste oil collection infrastructure costs on distributors. Transmission rebuild specialists along the Rosario-La Plata axis upgrade fluid specifications for automatic and dual-clutch architectures.
Patagonia Southern Region
Passenger vehicles operating in temperature extremes face stringent IRAM cold-crank viscosity compliance verification. The Secretariat of Industry and Productive Development requires documented pour-point depressant investments for region-servicing products. Neuquén and Comodoro Rivadavia service points stock specialized formulations for thermal stability under extreme operating conditions.
Mendoza Western Hub
Cross-border fleet traffic with Chile drives demand for Mercosur-harmonized lubricant specifications. Pending technical harmonization protocols could unify specification requirements across member states. Mendoza's position as a logistics gateway concentrates heavy-duty and light commercial vehicle servicing demand.
Argentina Passenger Vehicles Lubricants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The Argentine passenger vehicle lubricants sector structures around three tiers: national oil companies with captive refining, international majors with synthetic formulation access, and independent blenders serving price-sensitive channels. Market consolidation proceeds through workshop network acquisition and direct fleet supply agreements. Vertical integration into base stock supply and backward integration into additive sourcing represent the dominant competitive vectors.
Among Argentina-based integrated operators, YPF S.A. anchors the national oil company tier with captive refinery supply. Shell Argentina S.A. and ExxonMobil Argentina occupy positions within the international major segment, representing archetypes of premium synthetic formulation access and deep independent workshop distribution respectively. These three entities exemplify how supply chain configuration determines channel reach in a market constrained by import substitution policy friction.
| Leading Market Players |
|---|
| YPF S.A. |
| Petrobras Argentina S.A. |
| Shell Argentina S.A. |
| ExxonMobil Argentina |
| TotalEnergies |
| BP PLC (Castrol) |
| Puma Energy |
| Fercol Lubricantes |
| Gulf Oil International |
| Others |
Value Chain & Pricing Dynamics
The Rosario-La Plata freight corridor's diesel-indexed logistics costs cascade through Argentina's lubricant value chain, amplifying price spreads between YPF S.A.'s captive refinery supply and imported additive packages while compressing margins for independent blenders serving price-sensitive secondary markets.
Pricing Analysis
IRAM lubricant labeling standards dictate the pricing tier structure across Argentina's service channels, separating synthetic formulations aligned with Secretariat of Industry and Productive Development cold-crank viscosity mandates from mineral grades serving legacy vehicle compatibility requirements. Price differentiation hinges on additive package certification grade and volume-commitment scale, with Buenos Aires fleet operators extracting steepest discounts through bundled fluid-and-labor contracts. Cost compression in mineral-grade segments is intensifying because YPF S.A.'s base oil allocation constraints force smaller blenders into working capital strain. Independent service workshops in Córdoba and Rosario exhibit highest price sensitivity, while IRAM-certified facilities in metropolitan corridors show lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
Extended payment terms from YPF S.A.'s refinery network and supply-chain finance facilities at major distributors anchor working capital structures for mid-tier blenders unable to self-fund inventory cycles. Geographic supply concentration centers on Argentina's domestic refinery complex, Brazil's expanding blending capacity, and U.S. Gulf Coast additive manufacturing. Raw material dependencies encompass Group I/II base stocks, poly-alpha-olefin synthetics, and detergent-dispersant additive packages. Single-source vulnerability pervades the YPF S.A. base oil allocation system. Distribution runs through captive service station networks, independent workshop channels, and direct fleet supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's passenger vehicle lubricants sector reads as a service-attach opportunity where predictive maintenance contracts and telematics-enabled fluid monitoring expand recurring revenue faster than standalone product sales.
For Market Incumbents: Entrench control over the IRAM-certified workshop channel through exclusive additive supply agreements and backward integration into waste oil re-refining infrastructure. Synthetic formulation chemist scarcity at independent blenders threatens premium segment share; defend through certification co-investment programs with Córdoba and Buenos Aires fleet operators. For New Entrants and Emerging Players: Establish a beachhead in Patagonia's specialized cold-climate formulation segment where pour-point depressant investments create compliance barriers for commodity suppliers. The Neuquén-Comodoro Rivadavia corridor offers lowest competitive density among named regional markets. Pursue direct supply relationships with mining fleet operators bypassing traditional service station networks. For Investors and Strategic Acquirers: Independent workshop consolidators with captive waste oil collection infrastructure represent the most defensible acquisition archetype for medium-term value capture. Circular economy participation quotas from the National Directorate of Chemicals and Fuels create regulatory moats around re-refining assets. Monitor Mercosur technical harmonization protocol ratification as inflection signal for cross-border formulation standardization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Sourcing | Import substitution policy friction makes captive additive supply critical for formulation flexibility under IRAM standards. |
| Telematics-Enabled Service Contract Launch | Sensor-based viscosity monitoring compresses drain intervals and locks fleet operators into recurring revenue streams. |
| IRAM Certification Co-Investment Program | Workshop professionalization subsidies accelerate synthetic upgrade cycles in Buenos Aires metropolitan corridors. |
| Waste Oil Re-Refining Facility Buildout | National Directorate of Chemicals and Fuels quotas create regulatory-compliant circular economy participation. |
| Patagonia Specialized Formulation Development | Pour-point depressant investments for extreme cold-crank viscosity compliance open premium pricing in underserved southern regions. |
Study Parameters
A standing panel of lubricant blending plant managers, fleet procurement directors at Buenos Aires logistics operators, IRAM certification auditors, and independent service workshop owners provided ongoing calibration across the primary research phase. Secondary validation drew from Secretariat of Industry and Productive Development regulatory filings, National Directorate of Chemicals and Fuels waste oil collection reports, Mercosur technical harmonization protocol drafts, and customs data on additive imports. Bottom-up volume estimates from workshop-level procurement patterns were triangulated against top-down refinery production disclosures.
Scenario-bracketing framed demand projections across the modeling period, with segmentation dimensions spanning formulation type, viscosity grade tier, distribution channel structure, and regional service corridor density. CAGRs were derived from elasticity-adjusted consumption curves calibrated to vehicle parc aging patterns and synthetic conversion rates. Forecast inputs incorporated IRAM specification evolution timelines and fleet telematics penetration assumptions.
Stress conditions across base oil supply disruption, import substitution policy intensification, and Mercosur harmonization delay were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding drain interval compression rates and workshop certification expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market
Automotive Parts
Brake Shoe Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Supply System Market