
 South Korea Automotive Parts Zinc Die Casting Market | 2026-2036
South Korea Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Automotive Parts Zinc Die Casting Market Analytics
Aftermarket service revenue is reconfiguring margin pools away from pure component sales toward lifecycle support contracts in the South Korea Automotive Parts Zinc Die Casting Market. Ahresty Korea leverages its high-pressure die casting expertise to dominate engine component supply chains for domestic OEMs. Hyundai WIA anchors the premium transmission parts segment through captive manufacturing scale and backward integration into tooling design. Ryobi Die Casting Korea competes on vacuum die casting technology leadership for electric vehicle thermal management housings.
South Korea Automotive Parts Zinc Die Casting refers to the precision manufacturing process where zinc alloys, typically Zamak compositions with aluminum, magnesium, and copper additions, are injected under high pressure into hardened steel molds to produce complex net-shape automotive components with tolerances reaching ±0.02 mm. The process serves primarily to deliver corrosion-resistant, dimensionally stable parts for under-hood and chassis applications where weight reduction and electromagnetic shielding prove critical. Engine Components and Transmission Parts command the largest value share due to their specification intensity and OEM qualification barriers. Electric Vehicles represent the fastest-growing application dimension as thermal management housings and battery enclosure brackets shift from aluminum to zinc alloys for cost-sensitive platforms.
MFDS material safety directives and KSA quality standards govern zinc alloy composition limits and surface finish requirements for safety-critical brake and steering castings. MFDS regulates heavy metal leaching thresholds in recycled zinc feedstock, while KSA enforces dimensional repeatability protocols that tier-1 suppliers must document across production lots. Stakeholders must monitor how Korea's carbon neutrality roadmap reshapes foundry energy sourcing and whether green hydrogen trials at Ulsan industrial complexes alter smelting cost structures for domestic zinc suppliers.
Market Dynamics
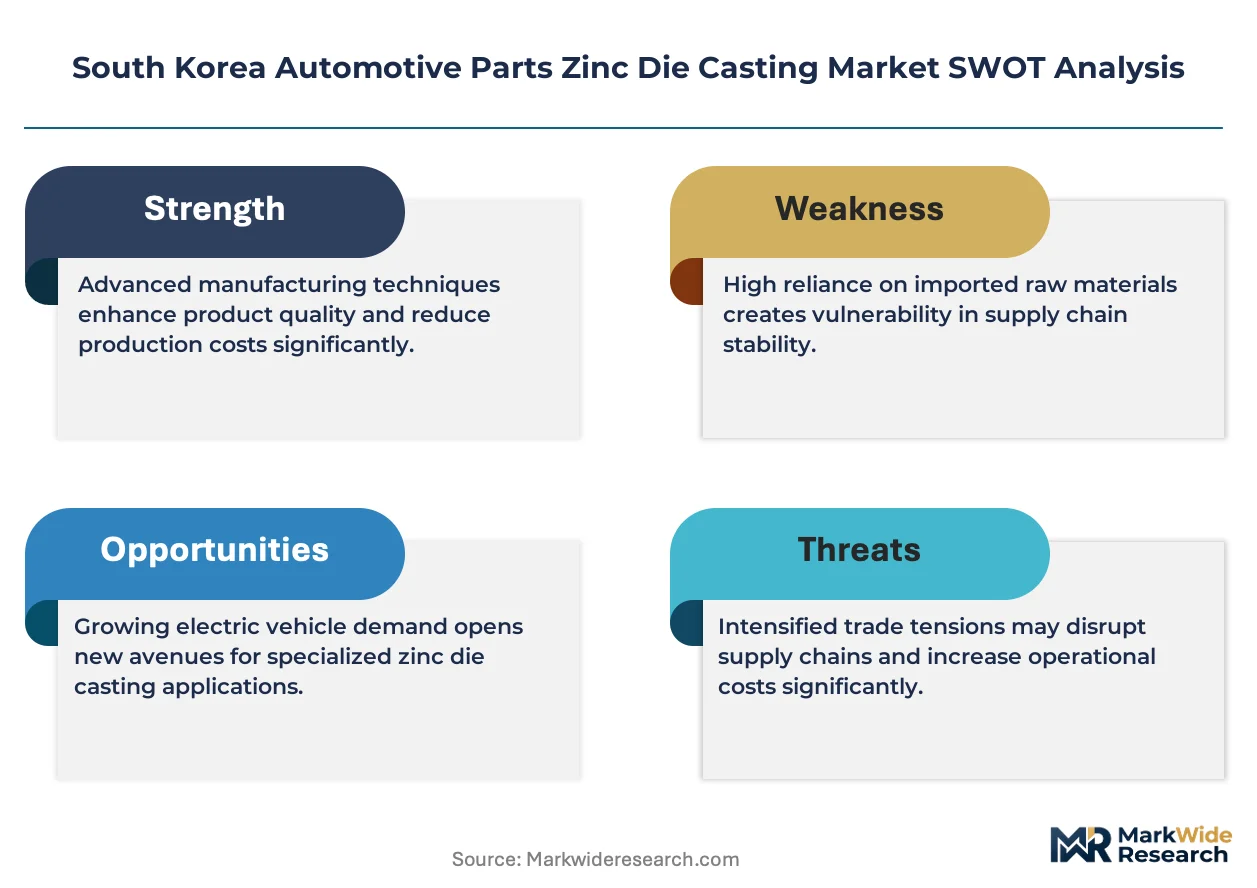
Hyundai Motor Group and Kia are accelerating EV platform rollouts, forcing zinc die casters to requalify alloys for thermal management housings and battery brackets that previously used aluminum. This powertrain electrification wave is compressing traditional engine component demand while opening new specification battles in electric vehicle architectures.
Growth Catalysts
- MFDS Material Safety Directives:Tightened heavy metal leaching thresholds for recycled zinc feedstock are pushing foundries toward higher-purity primary alloys, creating premium pricing tiers for certified suppliers serving brake and steering assemblies.
- Electric Vehicle Thermal Management:Battery enclosure brackets and inverter housings are shifting to zinc alloys for cost-sensitive EV platforms, generating fresh volume in applications where aluminum previously dominated.
- Gyeonggi-do Supplier Clustering:Tier-1 die casters concentrate near Hyundai WIA and Kia Motors complexes in this industrial corridor, reducing logistics costs and enabling just-in-sequence delivery models for powertrain components.
Market Restraints
- Primary Zinc Price Volatility:Smelter energy costs fluctuate with Korea's carbon neutrality roadmap and green hydrogen trials at Ulsan industrial complexes, compressing foundry margins on fixed-price OEM contracts.
- KSA Dimensional Repeatability Protocols:Documentation requirements across production lots create compliance overhead for smaller foundries, raising effective barriers to tier-1 qualification for safety-critical brake castings.
- Aluminum Substitution in Premium EVs:High-end electric vehicle platforms specify aluminum-magnesium alloys for weight reduction, capping zinc's addressable market in luxury battery housings and structural brackets.
Strategic Opportunities
- Ulsan Industrial Complex Green Hydrogen:Pilot programs for hydrogen-reduced zinc smelting could yield carbon-certified alloys that command premiums from OEMs with Scope 3 reduction targets.
- Vacuum Die Casting Convergence:Combining vacuum-assisted mold filling with real-time porosity monitoring enables thinner-wall thermal management housings for next-generation EV power electronics.
- Lifecycle Support Contracts:Aftermarket service revenue pools are migrating from pure component sales toward predictive maintenance agreements covering brake caliper and steering knuckle replacement cycles.
Industry Challenges
- Multi-physics Simulation Talent:Foundries lack engineers trained in coupled thermal-mechanical mold flow analysis required for EV thermal housing qualification, slowing new product introduction timelines.
- KSA Certification Timeline Compression:OEMs demand concurrent engineering validation while documentation protocols require sequential lot testing, creating schedule conflicts for tier-2 suppliers.
- Legacy ERP Integration:Real-time production traceability systems for MFDS compliance must interface with decades-old manufacturing execution platforms at family-owned foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Automotive Parts Zinc Die Casting Market |
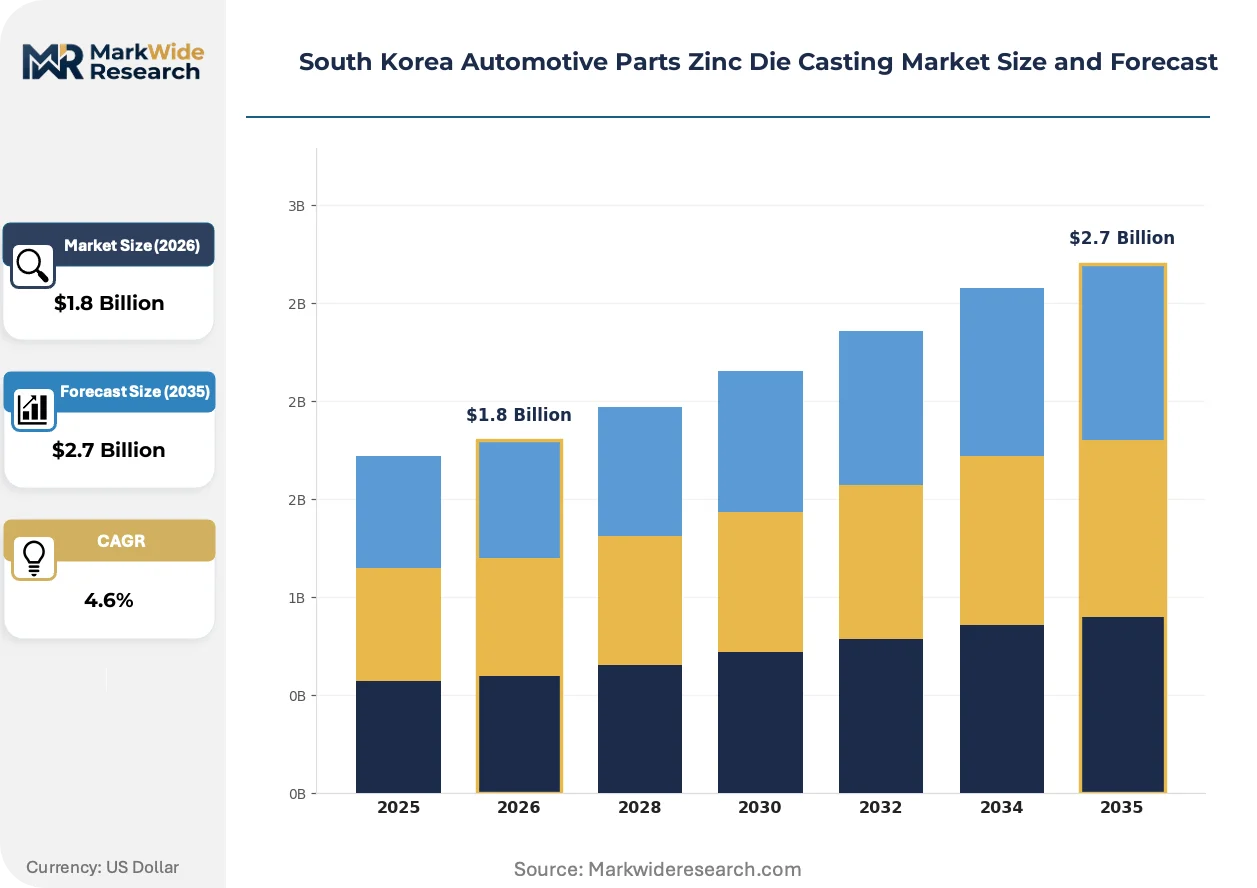
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Steering Systems, Chassis Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: High Pressure Die Casting, Low Pressure Die Casting, Vacuum Die Casting, Hot Chamber Die Casting Application: Light Vehicles, Heavy Vehicles, Commercial Vehicles, Electric Vehicles |
| Companies Covered | Ahresty Korea, Pace Industries, Hyundai WIA, Ashok Minda Group, Brillcast Manufacturing LLC, Dynacast Korea, Sandhar Technologies Ltd, Empire Casting Co, Ryobi Die Casting Korea, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Automotive Parts Zinc Die Casting Market Evolving Landscape
Digital twin technology and real-time process monitoring are virtualizing traditional die casting workflows. Korean foundries now face investment decisions between incremental automation and full architecture replacement.
Thin-wall vacuum die casting is virtualizing conventional high-pressure process limits. Tier-1 suppliers serving Hyundai and Kia are adopting this technology for EV inverter housings requiring 1.2 mm wall sections. The structural consequence is virtualizing the historical trade-off between zinc's castability and aluminum's weight advantage, enabling zinc to penetrate applications previously closed to the material.
MFDS has tightened recycled content documentation requirements under amended material safety frameworks. Foundries must now certify batch-level heavy metal content through third-party testing. Small and mid-size suppliers in the Gyeonggi-do corridor are consolidating testing contracts to share laboratory costs while larger players build in-house spectroscopy capabilities.
Procurement patterns are fragmenting as Hyundai and Kia diversify supplier bases for EV-dedicated platforms. Long-term sole-source agreements for engine components are giving way to dual-qualified supplier panels for thermal management castings. This behavioral shift is most visible in battery enclosure bracket sourcing, where OEMs now maintain three approved foundries per component family to mitigate supply disruption risks.
South Korea Automotive Parts Zinc Die Casting Market Segmentation
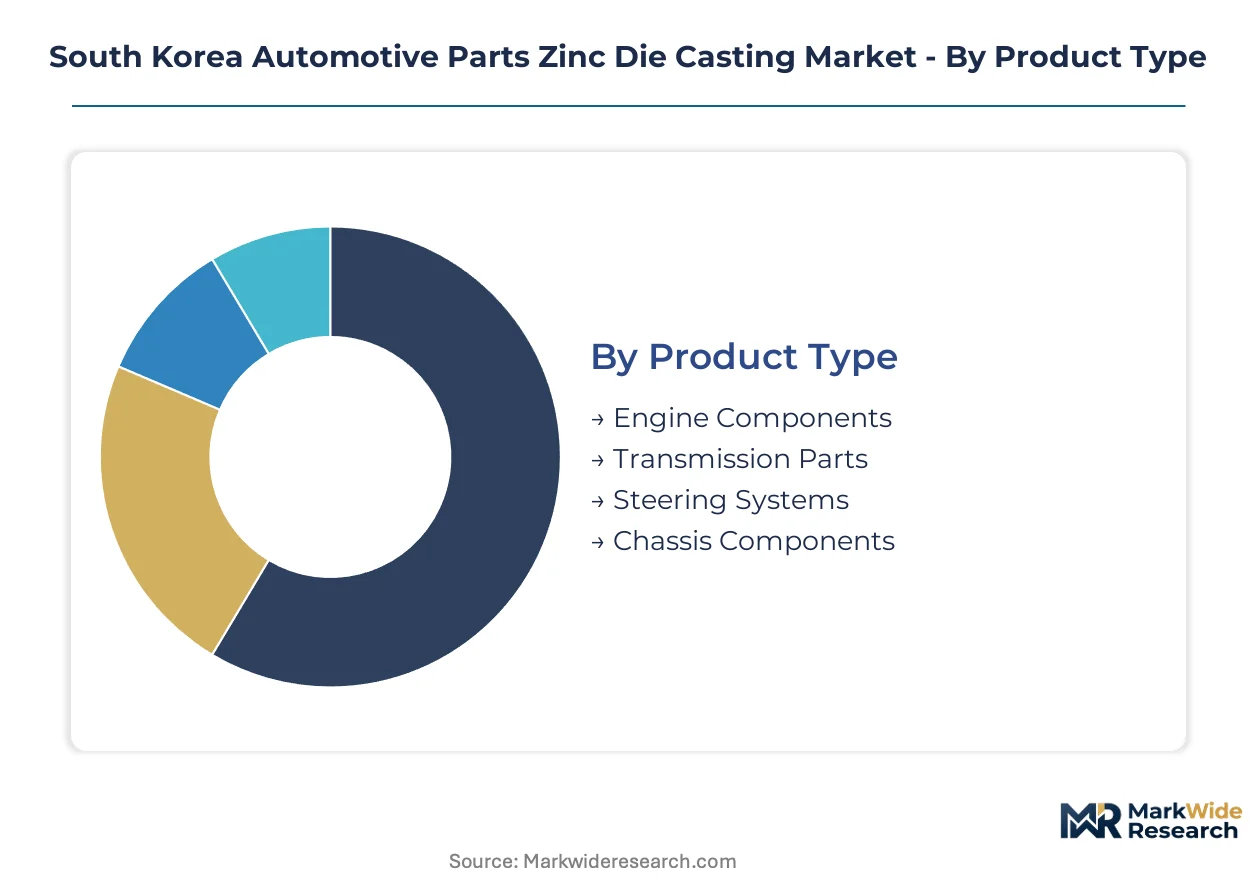
Zinc die casting segmentation in South Korea reflects divergent service intensity across product lifecycles. Aftermarket-driven segments demand predictive maintenance integration, while OEM-focused categories prioritize concurrent engineering validation. Understanding these structural differences enables suppliers to align capital deployment with margin durability.
Product Type:
After-sales service intensity varies dramatically across component families, with brake and steering castings requiring lifecycle traceability while engine parts emphasize warranty period coverage.
- Engine Components:Cylinder head covers, timing chain housings, and oil pump bodies utilize Zamak 5 alloys for dimensional stability under thermal cycling. Demand concentrates near Hyundai WIA complexes in Gyeonggi-do as captive suppliers qualify for powertrain platform sharing across Hyundai and Kia lineups. MFDS documentation requirements for recycled content create compliance overhead that favors integrated foundries with in-house spectroscopy.
- Transmission Parts:Valve bodies, clutch housings, and gear selector forks require tighter tolerances reaching ±0.02 mm for hydraulic sealing surfaces. Tier-1 suppliers in Ulsan industrial corridors dominate this specification-heavy segment where KSA dimensional repeatability protocols mandate sequential lot testing across production runs.
- Steering Systems:Rack housings and pinion supports serve safety-critical functions with elevated liability exposure.
- Chassis Components:Suspension brackets and crossmember nodes prioritize corrosion resistance over precision.
By volume, Engine Components leads. By growth pace, Transmission Parts is ahead.
End User:
Customer type determines contract structure, with OEMs demanding multi-year price-down schedules and aftermarket providers seeking inventory flexibility.
- OEMs:Hyundai Motor Group and Kia Motors specify zinc alloys for cost-sensitive platforms while reserving aluminum-magnesium for premium EV architectures. Direct sourcing agreements concentrate in Gyeonggi-do and Ulsan corridors where just-in-sequence delivery models compress logistics costs.
- Aftermarket Providers:Independent distributors and service chains source brake calipers and steering knuckles through consolidated procurement platforms. These stakeholders prioritize predictive maintenance data integration to capture lifecycle revenue pools beyond initial component sales.
- Tier-1 Suppliers:Ahresty Korea and Ryobi Die Casting Korea intermediate between foundries and vehicle assemblers, absorbing KSA certification overhead.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders represent fragmented demand with irregular volume profiles.
By revenue concentration, OEMs dominate. By margin expansion potential, Aftermarket Providers is climbing the fastest.
Technology:
Process selection trades capital intensity against specification ceiling, with vacuum-assisted methods commanding premiums for thin-wall EV applications.
- High Pressure Die Casting:Conventional HPDC dominates engine and transmission production with cycle times under 30 seconds per shot. Foundries throughout Gyeonggi-do corridor deploy this mature technology for volume production of Zamak alloy components where porosity tolerance permits.
- Vacuum Die Casting:Mold evacuation before metal injection enables 1.2 mm wall sections for EV inverter housings and battery enclosure brackets. Ryobi Die Casting Korea leads qualification efforts for Hyundai and Kia thermal management platforms where weight targets previously excluded zinc.
- Low Pressure Die Casting:Slower fill rates suit thicker-section chassis nodes with lower cosmetic requirements.
- Hot Chamber Die Casting:Zinc-specific machine architecture delivers fastest cycle times for small precision castings.
By installed base, High Pressure Die Casting leads. By technology investment velocity, Vacuum Die Casting is gaining share fastest.
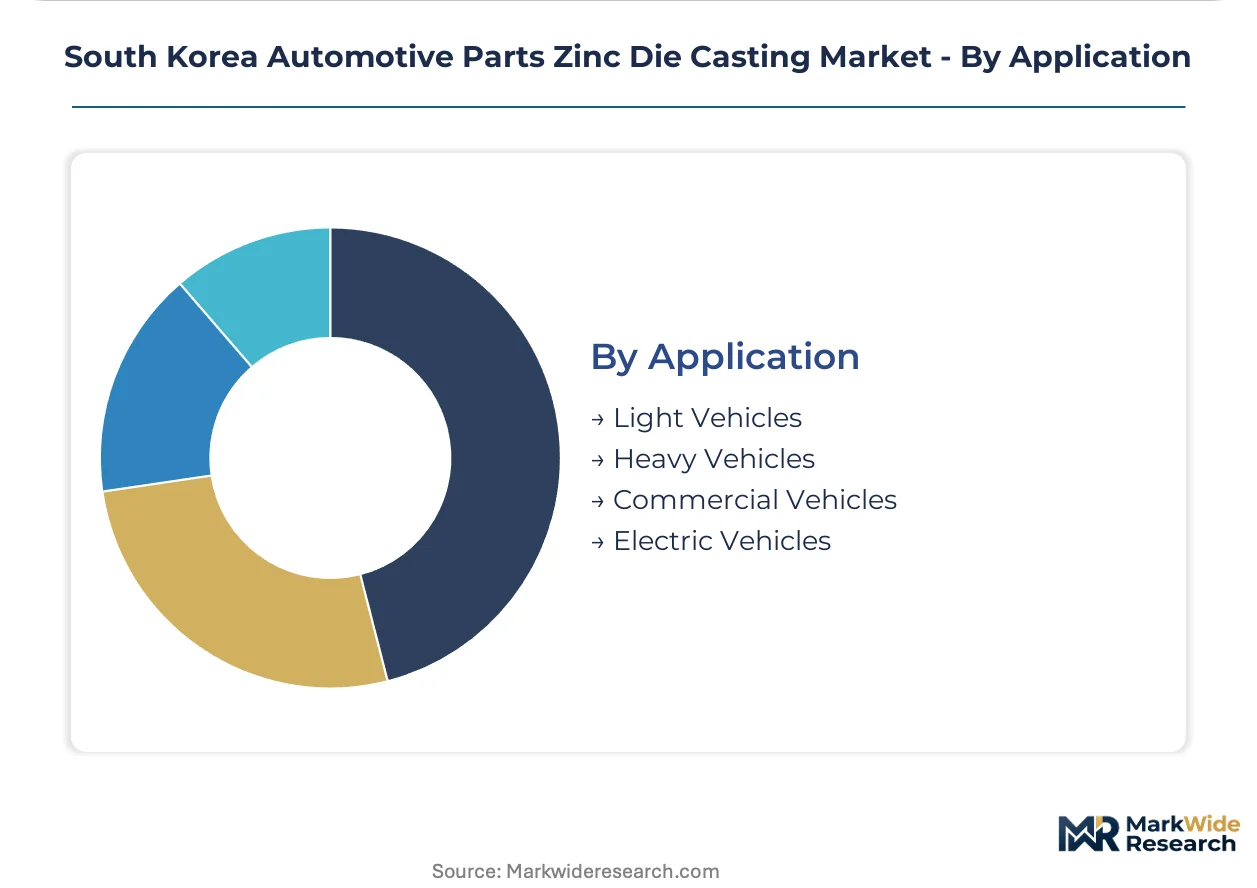
Application:
Vehicle electrification is fragmenting demand patterns, with EV platforms specifying zinc for cost brackets where aluminum previously dominated.
- Electric Vehicles:Battery enclosure brackets, inverter housings, and thermal management nodes shift to zinc alloys for mass-market EV platforms. Hyundai and Kia dual-source these components across three approved foundries per family to mitigate disruption risks in their expanding EV lineups.
- Light Vehicles:Passenger car production in South Korea sustains baseline demand for engine and transmission castings. Gyeonggi-do supplier clustering enables rapid model changeover as Hyundai and Kia refresh internal combustion platforms alongside EV rollouts.
- Heavy Vehicles:Commercial truck and bus applications prioritize durability over weight minimization.
- Commercial Vehicles:Fleet operators and logistics companies drive aftermarket replacement cycles with predictable maintenance intervals.
By current volume, Light Vehicles leads. By expansion trajectory, Electric Vehicles is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Die casting capacity clusters along South Korea's southeastern industrial spine, with foundry investments tracking Hyundai Motor Group and Kia Motors assembly footprints. Regional specialization reflects tier-1 supplier qualification requirements and MFDS regulatory jurisdiction.
Seoul Capital Area
Headquarters functions and engineering centers dominate this region, with Ahresty Korea and Ryobi Die Casting Korea maintaining design offices for concurrent EV platform development. MFDS regulatory filings concentrate here. Gwangmyeong and Hwaseong host tooling design specialists serving Gyeonggi-do production corridors.
Busan-Ulsan
Ulsan industrial complexes anchor the nation's heaviest die casting capacity, with Hyundai WIA operating captive foundries for transmission and powertrain components. Green hydrogen pilot programs at Ulsan smelters could reshape zinc alloy carbon certification. The region supplies thermal management castings for Kia's expanding EV lineup.
Daegu-Gyeongbuk
Secondary tier-2 foundries populate this corridor, serving brake and steering component demand with lower specification intensity than Ulsan counterparts. KSA dimensional repeatability protocols create qualification bottlenecks for smaller suppliers. Pohang steelworks proximity enables rapid tooling steel sourcing.
Daejeon-Sejong
Research institutes and materials testing laboratories cluster in this administrative hub, supporting MFDS batch-level heavy metal certification requirements. Korea Automotive Technology Institute (KATECH) facilities here validate zinc alloy formulations for EV thermal management applications before production transfer to Gyeonggi-do.
Gwangju-Honam
Smaller foundry operations serve regional commercial vehicle and aftermarket demand with limited OEM qualification. Labor cost differentials attract brake caliper producers for replacement market supply. The region lacks the just-in-sequence logistics infrastructure of Gyeonggi-do and Ulsan corridors.
South Korea Automotive Parts Zinc Die Casting Market Competitive Landscape
Captive manufacturers and independent specialists split the market between vertically integrated OEM supply and tier-1 merchant foundry services. Hyundai WIA anchors the captive segment through backward integration into tooling design and high-volume transmission component production. Independent specialists concentrate in Gyeonggi-do and Ulsan corridors, competing on KSA certification maintenance and MFDS compliance documentation. Strategic moves center on vacuum die casting technology licensing for EV thermal management qualification and dual-sourcing panel expansion by Hyundai and Kia.
Among Korea-based operators, Ahresty Korea, Hyundai WIA, and Ryobi Die Casting Korea occupy distinct competitive positions. Ahresty Korea exemplifies the high-pressure die casting specialist archetype serving domestic OEM powertrain platforms. Hyundai WIA represents captive manufacturing scale with integrated tooling capabilities. Ryobi Die Casting Korea sits within the vacuum-assisted technology tier targeting EV thermal management housing applications. These three entities collectively illustrate the market's segmentation between conventional engine component supply and emerging electric vehicle specification battles.
| Leading Market Players |
|---|
| Ahresty Korea |
| Pace Industries |
| Hyundai WIA |
| Ashok Minda Group |
| Brillcast Manufacturing LLC |
| Dynacast Korea |
| Sandhar Technologies Ltd |
| Empire Casting Co |
| Ryobi Die Casting Korea |
| Others |
Value Network & Pricing Analysis
Gyeonggi-do's supplier corridor concentrates high-pressure die casting capacity within 50 kilometers of Hyundai WIA and Kia Motors assembly complexes, compressing logistics costs and amplifying tier-1 foundries' pricing power over tier-2 competitors. This geographic clustering enables just-in-sequence delivery models that command premium contract terms while smaller foundries in Daegu-Gyeongbuk absorb margin erosion from distance-based logistics penalties.
Pricing Analysis
MFDS material safety directives dictate the pricing tier structure across South Korea's automotive zinc die casting market. Three-tier pricing structure across premium, standard, and economy levels separates KSA-certified suppliers serving brake and steering assemblies from uncertified foundries limited to non-structural chassis components. Price differentiation rests on batch-level heavy metal documentation and in-house spectroscopy capabilities. Cost compression in the standard tier is intensifying because OEMs demand concurrent engineering validation without price premiums. Aftermarket providers exhibit highest price sensitivity due to inventory holding costs, while captive manufacturers like Hyundai WIA show lowest sensitivity through backward integration into tooling design.
Supply Chain Analysis
Export control regimes on advanced die casting simulation software limit Korean foundries' access to coupled thermal-mechanical mold flow analysis tools, constraining EV thermal housing qualification timelines. Geographic supply concentration centers on South Korea, China, and Japan for zinc alloy feedstock and hardened steel mold materials. Raw material dependencies draw from Australian zinc concentrate, Chinese magnesium additions, and domestic copper scrap recycling. Single-source vulnerability runs through specialized vacuum die casting equipment suppliers in Germany and Japan. Distribution runs through tier-1 supplier intermediaries like Ahresty Korea and Ryobi Die Casting Korea before reaching Hyundai and Kia assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's automotive parts zinc die casting market sits at an inflection point where vacuum die casting technology for EV thermal management housings is displacing conventional high-pressure methods. MFDS tightening of recycled content documentation requirements accelerates consolidation toward integrated foundries with in-house testing capabilities.
For Market Incumbents: Entrench qualification advantages by deepening backward integration into tooling steel sourcing and expanding vacuum die casting capacity for Hyundai and Kia EV platform contracts. Aluminum substitution in premium EV architectures threatens zinc's addressable market in luxury battery housings, requiring defensive certification investments in thinner-wall casting capabilities. Captive supply of spectroscopy equipment mitigates MFDS compliance overhead that burdens tier-2 competitors. For New Entrants and Emerging Players: Mid-size foundries in Daegu-Gyeongbuk with existing brake and steering component expertise represent the most penetrable entry point for tier-1 qualification through KSA dimensional repeatability protocol investment. Aftermarket lifecycle support contracts for predictive maintenance integration offer white-space revenue pools beyond pure component sales. Go-to-market positioning should emphasize real-time production traceability systems that interface with legacy ERP platforms at family-owned foundries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vacuum die casting specialists with demonstrated EV thermal management housing qualifications over conventional high-pressure engine component suppliers. Long-term viability through the electrification transition hinges on thin-wall casting capabilities and OEM dual-sourcing panel inclusion. The signal to watch is Hyundai and Kia procurement pattern fragmentation toward three-approved-foundry panels per component family, indicating qualification velocity and supply security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Die Casting Capacity Expansion | Enables 1.2 mm wall sections for EV inverter housings previously closed to zinc alloys. |
| Backward Integration into Tooling Design | Hyundai WIA's captive tooling capabilities compress new product introduction timelines for transmission components. |
| Green Hydrogen Smelting Partnership | Ulsan pilot programs could yield carbon-certified zinc alloys commanding Scope 3 reduction premiums from OEMs. |
| Real-Time Process Monitoring Deployment | Digital twin virtualization of die casting workflows supports MFDS batch-level documentation requirements. |
| Aftermarket Lifecycle Support Contracts | Predictive maintenance agreements for brake caliper replacement cycles capture revenue beyond initial component sales. |
Research Methodology
The analysis maps engine components, transmission parts, steering systems, and chassis components, each validated through tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and foundry operations managers. Primary interviews with these stakeholders combined with secondary validation from Korea Automotive Technology Institute technical reports, MFDS regulatory filings, KSA certification databases, and vehicle production registries. Bottom-up capacity modeling and top-down demand triangulation from Hyundai and Kia EV rollout schedules anchored volume estimates.
Forecasts hold fixed MFDS regulatory timelines and Hyundai Motor Group platform sharing architectures while varying primary zinc price scenarios and green hydrogen smelting adoption rates. Segmentation dimensions modeled include product type, end user category, technology process, and vehicle application across the projection horizon. CAGRs derive from production capacity expansion announcements, OEM sourcing contract durations, and alloy substitution elasticity in thermal management applications. Industry-specific inputs incorporate vacuum die casting qualification timelines and KSA certification backlog estimates.
Practitioners should monitor green hydrogen smelting cost competitiveness and aluminum-zinc substitution rates in premium EV platforms for early signals of forecast revision triggers. Forecasts reflect assumptions regarding MFDS enforcement consistency and Hyundai-Kia dual-sourcing panel stability. Material shifts in carbon neutrality roadmap implementation or export control expansion on simulation software would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Small Engine Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Resin Silencer Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Struts System Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Global EV Speed Reducer Market