
 South Africa Commercial Vehicles Lubricants Market | 2026-2036
South Africa Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Commercial Vehicles Lubricants Market Analytics
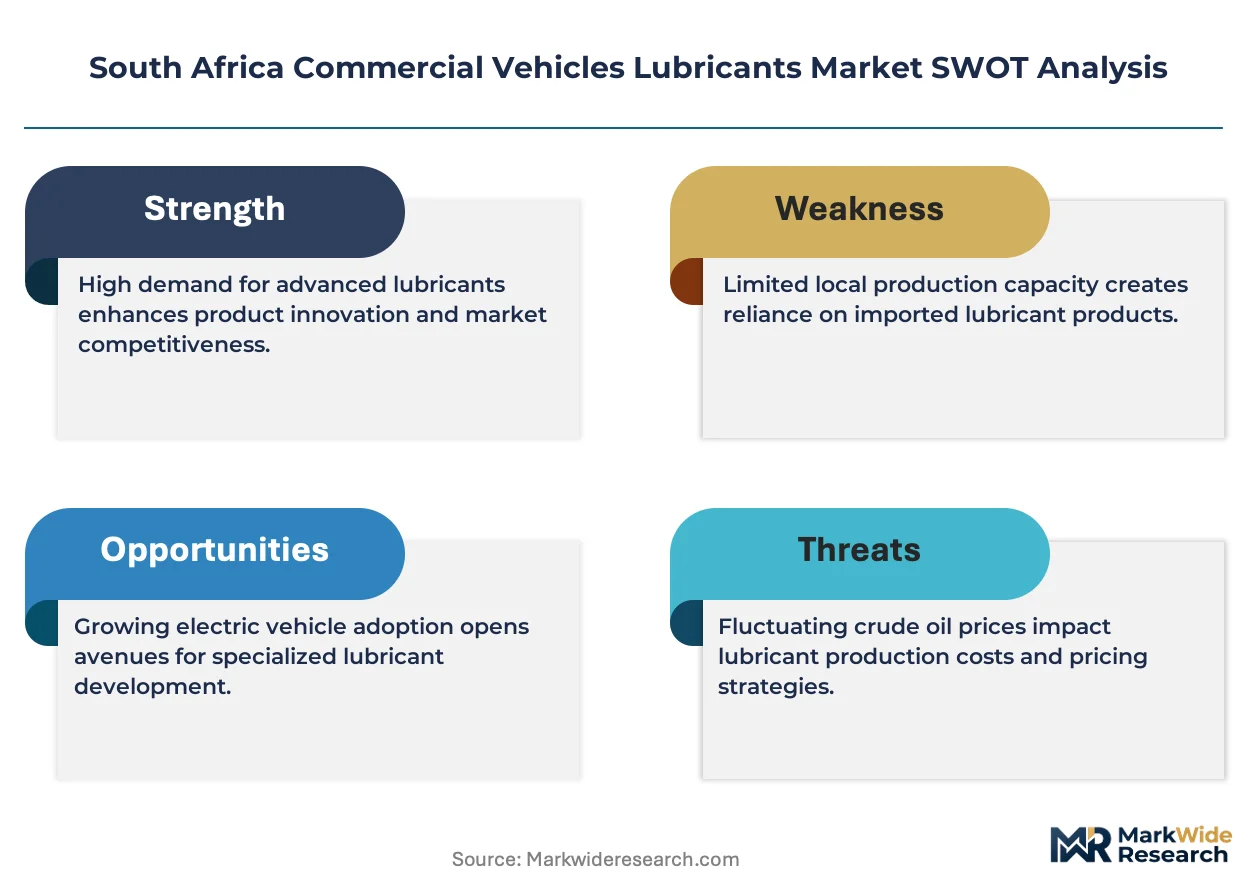
South Africa's blending capacity expansion around Durban is fragmenting as independent packers challenge established refiners. Sasol leverages its Fischer-Tropsch base oil output to anchor supply security for domestic formulators. Engen Petroleum competes through coastal terminal access and retail forecourt penetration. Shell plc differentiates via synthetic product ranges targeting extended-drain specifications for mining haul trucks.
Commercial vehicles lubricants are formulated hydrocarbon-based fluids with viscosity grades typically spanning SAE 15W-40 to 5W-30, incorporating detergent-dispersant, anti-wear, and antioxidant additive packages to protect diesel engines operating under high soot loading and thermal stress. Their primary commercial purpose is to reduce friction wear, neutralize acidic combustion byproducts, and extend component life in trucks, buses, and off-highway equipment subjected to Southern Africa's dust-heavy and temperature-extreme conditions. Engine oil commands the dominant volume share as fleet operators prioritize total cost of ownership over unit price, while hydraulic fluids represent the fastest-expanding category due to mechanization trends in construction and agriculture. Greases concentrate margin pools in mining applications where NLGI Grade 2 lithium complex formulations withstand extreme pressure and water washout.
South Africa's National Regulator for Compulsory Specifications enforces SANS 1099 and SANS 1322 standards that dictate minimum performance benchmarks for automotive lubricants, effectively filtering substandard imports from neighboring states. The Department of Mineral Resources and Energy oversees fuel quality regulations that indirectly shape lubricant additive chemistry through sulfur and particulate limits. BIS-equivalent alignment pressures from regional trade agreements with SADC partners are tightening conformity assessment requirements. Stakeholders must monitor how carbon border adjustment discussions in the EU affect South African automotive export-linked lubricant specifications.
Market Dynamics
Fleet operators in Gauteng and KwaZulu-Natal are extending oil drain intervals to compress total cost of ownership, forcing lubricant formulators to rebalance additive chemistry toward longer-life synthetic base stocks while maintaining SANS 1099 compliance.
Growth Catalysts
- Low-SAPS Mandate:South Africa's National Environmental Management Act enforcement is accelerating demand for low-ash engine oils compatible with exhaust aftertreatment systems on Euro V and VI trucks.
- Logistics Corridor Density:Heavy-duty freight operators along the Johannesburg-Durban-Cape Town axis consume disproportionate lubricant volumes as containerized cargo shifts from rail to road.
- Mechanization Uptake:Construction and agriculture sectors are expanding hydraulic fluid demand through precision equipment deployment in maize and platinum belt operations.
Market Restraints
- Group II/III Base Oil Import Dependence:South Africa lacks sufficient hydrocracking capacity, forcing blenders to source high-quality base stocks from Middle Eastern and Asian refiners subject to freight volatility.
- Fischer-Tropsch Paraffin Wax Competition:Sasol's synthetic fuel operations divert wax stream feedstocks away from lubricant base oil production during periods of diesel margin strength.
- SANS 1322 Testing Bottleneck:Limited in-country laboratory capacity for oxidation stability and shear stability verification delays product registration timelines for new market entrants.
Strategic Opportunities
- Eastern Cape Underpenetration:Port Elizabeth-Gqeberha automotive manufacturing cluster and Coega IDZ logistics growth create whitespace for localized blending and technical service presence.
- Extended-Drain Synthetics:Mining haul truck operators at Mogalakwena and Sishen are piloting 1,000-hour drain intervals, opening premium positioning for PAO and ester-based formulations.
- SADC Export Alignment:Harmonization pressures from regional trade protocols enable South African formulators to leverage BIS-equivalent certification for Zimbabwe, Zambia, and Mozambique market access.
Industry Challenges
- Additive Chemist Scarcity:South African universities produce insufficient lubricant formulation specialists, forcing recruiters to compete with fuel and chemical sectors for experienced tribologists.
- Used Oil Collection Infrastructure:Reverse logistics for waste lubricant recovery remain underdeveloped outside major metropolitan areas, complicating sustainability reporting and re-refining feedstock security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Commercial Vehicles Lubricants Market |
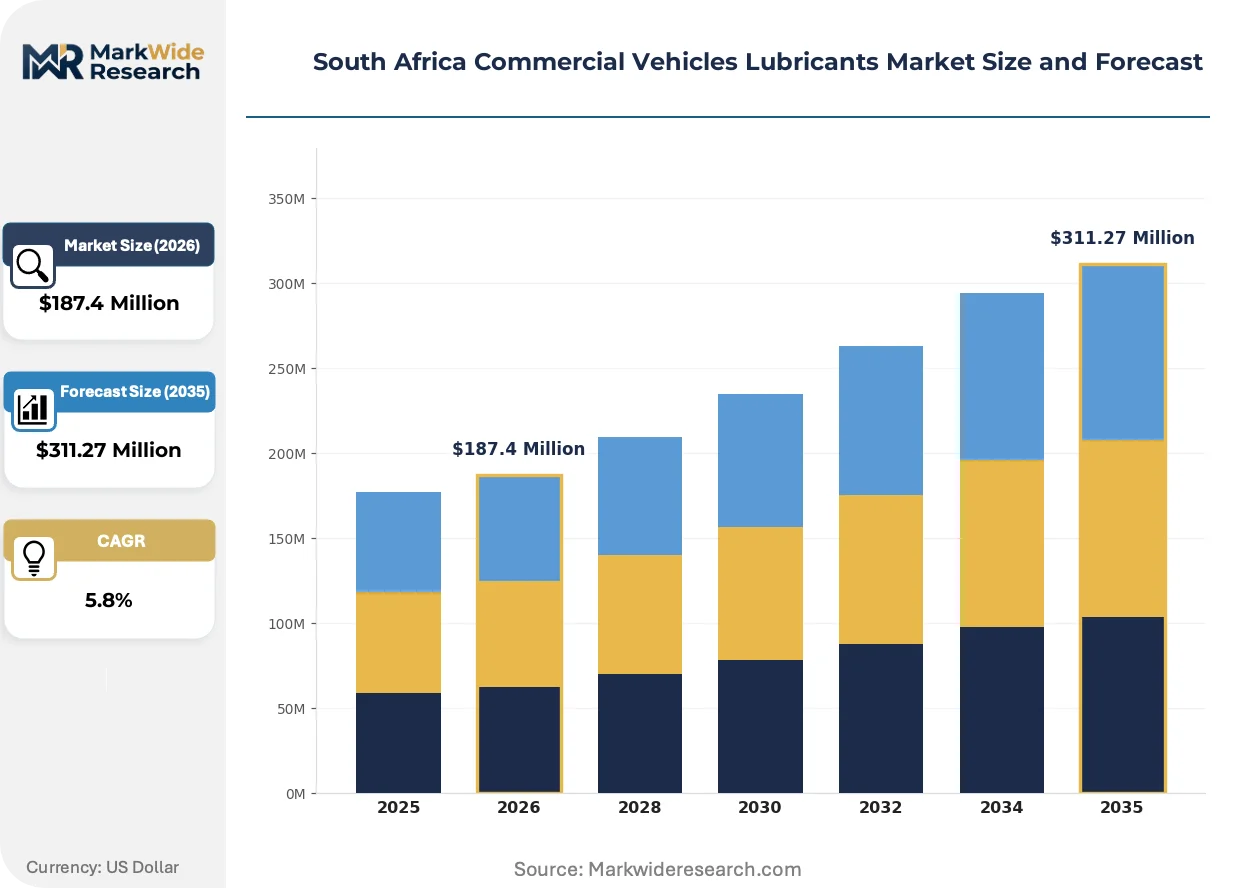
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Greases, Hydraulic Fluids End User: Fleet Owners, Logistics Companies, Construction Firms, Agricultural Businesses Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Wholesale Distributors Packaging Type: Barrels, Pails, Bottles, Bulk Containers |
| Companies Covered | Fuchs Lubricants, Sasol, Engen Petroleum, Shield Lubricants, Astron Energy, Shell plc, Total South Africa, African Group Lubricants, BP (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic base oil technology and emissions-driven additive reformulation are compressing traditional product lifecycles while reshaping how fleet buyers evaluate lubricant value beyond unit price metrics.
Polyalphaolefin and gas-to-liquid base stocks are displacing Group I mineral oils in heavy-duty diesel applications. Mining contractors at Anglo American and Kumba Iron Ore operations are specifying synthetic 5W-30 grades for cold-start protection in Highveld winter conditions. Conventional 15W-40 mineral formulations are rendering obsolete for equipment under warranty coverage requiring OEM-approved chemistry.
South Africa's Department of Transport is enforcing National Environmental Management Act amendments that align with Euro VI particulate limits. This regulatory pressure forces additive packagers to reformulate detergent systems toward magnesium and calcium salicylates away from traditional zinc dithiophosphates. Long-haul operators in the Durban-Johannesburg corridor face the steepest compliance costs as pre-2018 truck fleets require retrofit-compatible lubricant specifications.
Consolidated fleet procurement is displacing fragmented owner-operator purchasing across the logistics sector. Large transport groups with 500-plus vehicle counts are centralizing lubricant supply agreements through direct blender relationships, bypassing traditional distributor networks. This concentration is most visible in Gauteng, where Super Group and Barloworld Logistics have established captive technical service partnerships with formulators for condition monitoring and used oil analysis programs.
South Africa Commercial Vehicles Lubricants Market Segmentation
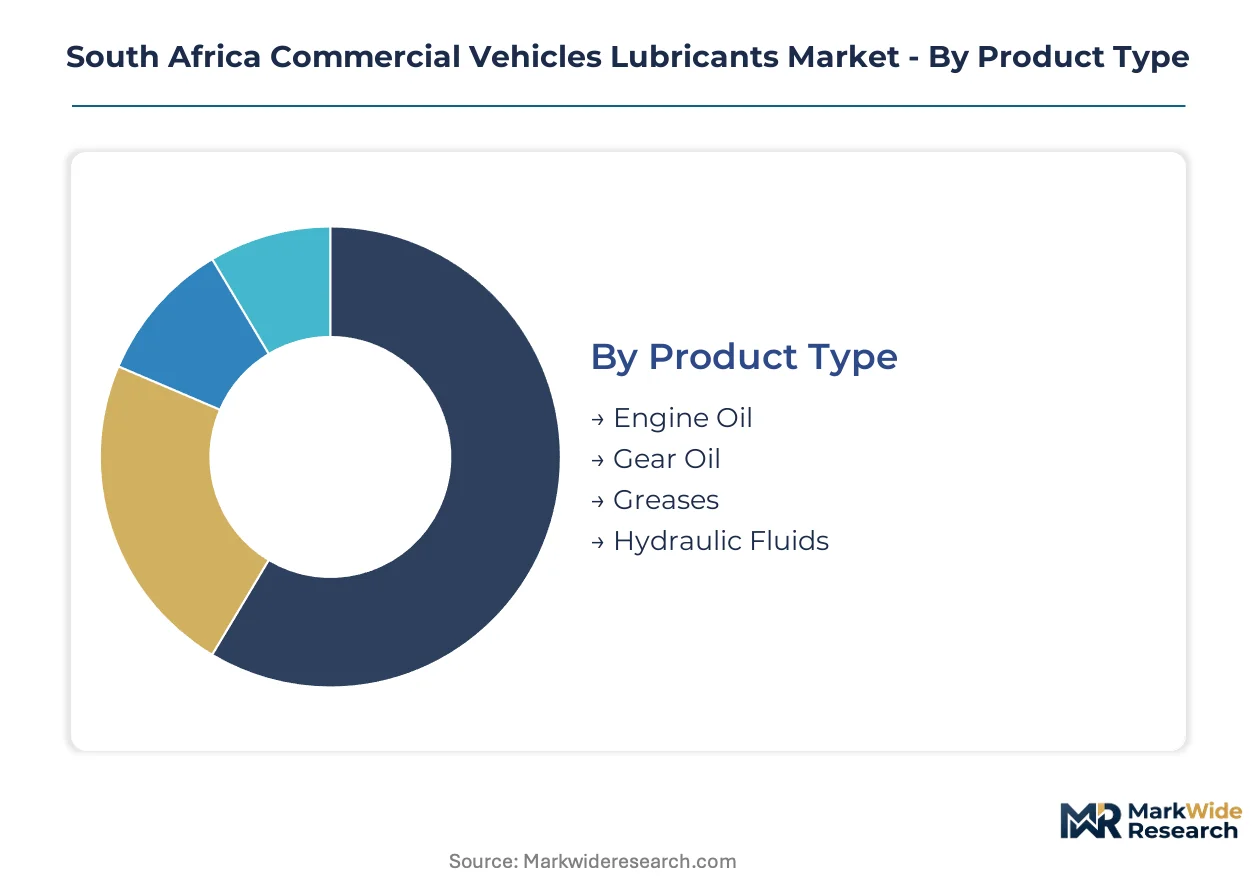
Fleet procurement centralization and drain interval extension are compressing product lifecycles unevenly across lubricant categories. Segmentation reveals which formulations command premium positioning versus commodity exposure in South Africa's logistics corridor.
Product Type:
Engine oil cycles through sump systems fastest at 15,000-45,000 kilometer intervals, while greases persist through annual or semi-annual service windows. Hydraulic fluids occupy intermediate replacement frequencies tied to construction seasonality.
- Engine Oil:Formulated hydrocarbon-based fluids spanning SAE 15W-40 to 5W-30 viscosity grades with detergent-dispersant and anti-wear additive packages. Long-haul freight operators along the Johannesburg-Durban-Cape Town axis consume disproportionate volumes as containerized cargo shifts from rail to road, though low-SAPS reformulation under the National Environmental Management Act is raising per-liter costs.
- Hydraulic Fluids:Anti-wear and rust-inhibited formulations transmitting power in precision construction and agricultural equipment. Mechanization trends in maize and platinum belt operations are expanding demand fastest, particularly where precision planting and harvesting equipment requires ISO 11158-specified viscosity stability.
- Gear Oil:Extreme-pressure lubricants protecting differentials and transmissions in mining haul trucks and long-haul tractors. Mining contractors at Mogalakwena and Sishen specify synthetic grades for extended service intervals.
- Greases:NLGI Grade 2 lithium complex formulations with extreme pressure and water washout resistance for chassis, wheel bearings, and mining equipment. Concentrated margin pools persist in platinum and coal mining applications where equipment downtime costs dwarf lubricant expenditure.
Engine oil anchors the volume base while hydraulic fluids gain share at the steepest rate.
End User:
Procurement scale separates stakeholders who negotiate direct blender relationships from those purchasing through distributor networks. Volume concentration determines technical service access and condition monitoring program availability.
- Fleet Owners:Vehicle operators with 50-plus unit counts centralizing lubricant supply agreements and bypassing traditional distributors. Gauteng-based Super Group and Barloworld Logistics have established captive technical service partnerships with formulators for used oil analysis programs.
- Logistics Companies:Third-party freight operators managing contracted fleet maintenance across the Durban-Johannesburg corridor. Pre-2018 truck fleets in this segment face steepest compliance costs for Euro VI-aligned lubricant specifications.
- Construction Firms:Equipment-intensive contractors consuming hydraulic fluids and greases through project-based procurement. Seasonal demand fluctuates with public infrastructure spending cycles.
- Agricultural Businesses:Mechanized farming operations in Free State and Mpumalanga requiring cold-start protection and dust-sealing formulations. Precision equipment deployment is expanding synthetic hydraulic fluid demand beyond traditional mineral-based purchases.
Fleet owners concentrate procurement volume while logistics companies drive fastest specification upgrading.
Distribution Channel:
Channel selection reflects customer scale and technical support requirements rather than price sensitivity alone. Direct relationships reward volume commitment with embedded laboratory services.
- Direct Sales:Blender-to-fleet supply agreements capturing consolidated procurement from 500-plus vehicle operators. Technical service partnerships include condition monitoring and used oil analysis programs.
- Wholesale Distributors:Regional stockists serving fragmented owner-operators and smaller fleet managers across Gauteng and KwaZulu-Natal. Inventory carrying costs and credit terms determine competitive positioning.
- Retail Stores:Forecourt and automotive parts outlets catering to emergency top-ups and owner-operator maintenance. Engen Petroleum competes through coastal terminal access and retail penetration.
- Online Platforms:Emerging procurement channel for standardized specifications with documented SANS 1099 compliance. Limited penetration for technical-grade formulations requiring application guidance.
Direct sales anchor volume concentration while online platforms expand most quickly among standardized product categories.
Packaging Type:
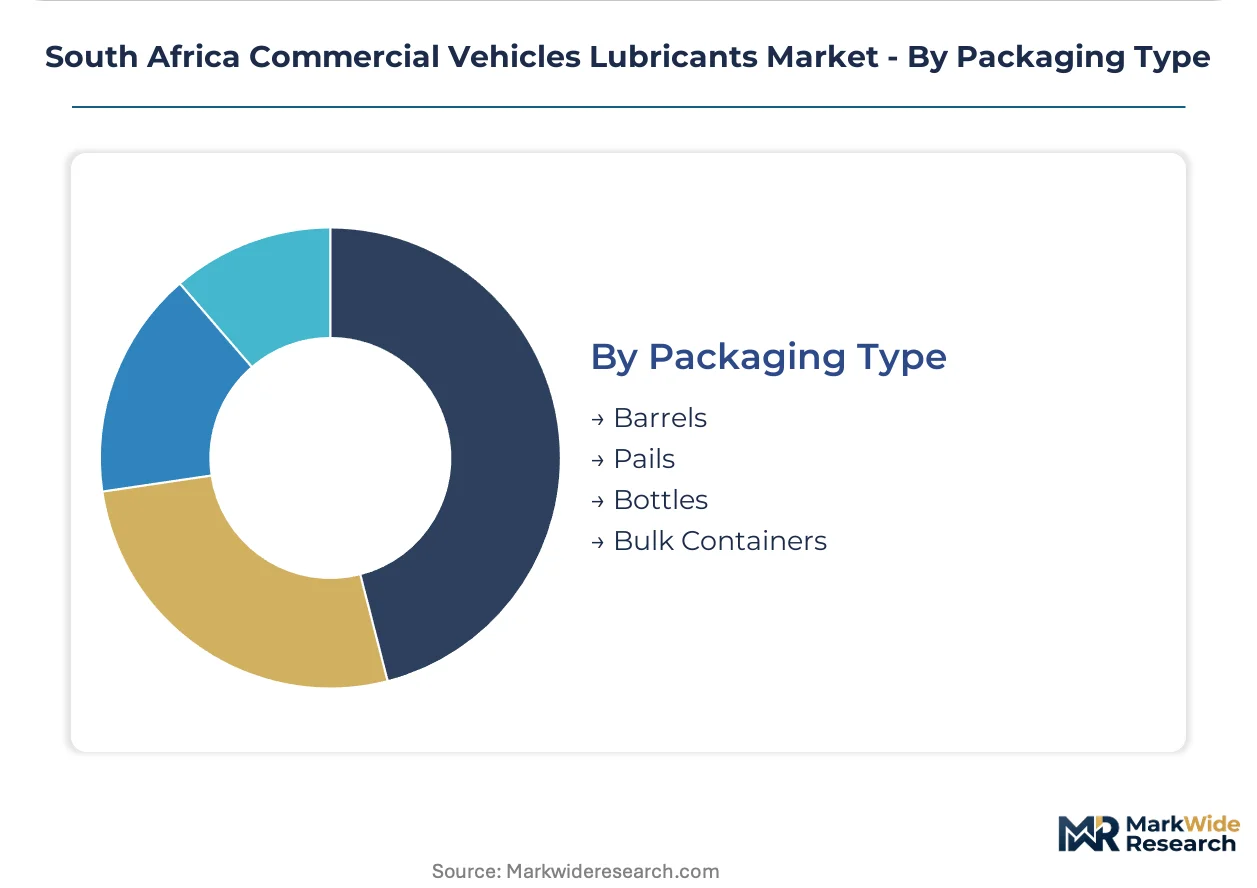
Packaging economics align with consumption velocity and storage infrastructure at customer sites. Bulk systems reward high-throughput operations with per-liter cost advantages.
- Bulk Containers:Tanker and intermediate bulk container deliveries to mining operations and large fleet depots with on-site storage. Sasol leverages Fischer-Tropsch base oil output to anchor supply security for domestic bulk formulators.
- Barrels:200-liter steel drums for medium fleet operators and construction contractors with secured storage. Standard logistics corridor packaging for Johannesburg-Durban-Cape Town freight movements.
- Pails:20-25 liter plastic containers for smaller workshops and agricultural operations. Balances portability with unit economics for customers lacking bulk storage infrastructure.
- Bottles:1-5 liter retail formats for emergency top-ups and light commercial vehicle owners. Lowest per-liter cost efficiency but highest accessibility for fragmented demand.
Bulk containers anchor industrial volume while pails gain fastest among mid-size fleet operators upgrading from bottle purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blending capacity clusters around Durban's port infrastructure, with Gauteng's inland demand pulling supply through the Johannesburg-Pretoria corridor. Provincial regulatory enforcement varies, creating specification compliance gaps between coastal and interior markets.
Gauteng
Fleet consolidation in Johannesburg and Pretoria concentrates procurement power among 500-plus vehicle operators. The National Environmental Management Act enforcement is strictest here, accelerating low-SAPS lubricant conversion. The Johannesburg-Durban logistics corridor anchors heavy-duty diesel consumption as containerized freight shifts from rail to road.
KwaZulu-Natal
Durban's blending plants and coastal terminal access position the province as South Africa's import gateway for Group II/III base stocks. The Department of Transport's emissions checkpoint density along the N3 highway enforces Euro VI-aligned specifications. Richards Bay mining logistics and Durban port operations sustain bulk lubricant demand.
Western Cape
Cape Town's container terminal and agricultural hinterland generate distinct demand profiles for long-haul and farm equipment lubricants. The provincial environmental regulator applies National Environmental Management Act standards with coastal-specific water protection provisions. The Cape Town-Johannesburg freight corridor supports mid-tier fleet operator procurement.
Eastern Cape
Port Elizabeth-Gqeberha's automotive manufacturing cluster and Coega IDZ logistics growth remain underpenetrated by technical service presence. The provincial government offers industrial incentives for localized blending investment. Mining contractors in the platinum belt generate grease and hydraulic fluid demand.
Mpumalanga
Coal mining operations around Witbank and Middelburg consume extreme-pressure greases and extended-drain engine oils. Agricultural mechanization in the maize belt expands synthetic hydraulic fluid requirements. Provincial enforcement of SANS 1099 compliance lags coastal provinces, creating specification arbitrage opportunities.
South Africa Commercial Vehicles Lubricants Market Competitive Landscape
Integrated refiners and independent packers split the market between supply security and formulation flexibility. Sasol anchors domestic base oil production through Fischer-Tropsch output, while coastal terminals enable import-dependent blenders to access Middle Eastern and Asian feedstocks. Three archetypes dominate: vertically integrated energy majors with captive base oil supply, independent packers leveraging toll blending relationships, and mining-focused specialists with technical service depth. Competitive moves center on direct fleet procurement partnerships and extended-drain synthetic portfolio expansion.
Among energy majors with integrated supply chains, Sasol and Shell plc occupy positions that exemplify divergent strategic foundations—Sasol through synthetic fuel-to-lubricant integration, Shell through global formulation technology transfer. Engen Petroleum represents the coastal-access archetype, leveraging terminal infrastructure for import flexibility. Independent packers including Fuchs Lubricants and Shield Lubricants sit within the formulation-specialist tier, competing on technical service rather than feedstock control.
| Leading Market Players |
|---|
| Fuchs Lubricants |
| Sasol |
| Engen Petroleum |
| Shield Lubricants |
| Astron Energy |
| Shell plc |
| Total South Africa |
| African Group Lubricants |
| BP (Castrol) |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Middle Eastern and Asian Group II/III base oil imports compresses both pricing tier spreads and supply chain resilience, forcing South African blenders to absorb freight volatility into margin structures while fleet buyers face escalating per-liter costs for SANS 1099-compliant formulations.
Pricing Analysis
SANS 1099 and SANS 1322 standards dictate the pricing tier structure across the South African commercial vehicles lubricants market. Three-tier pricing separates premium synthetic grades from mineral-based standards and economy imports lacking full certification. Price differentiation rests on additive chemistry sophistication and OEM approval status rather than base oil origin alone. Cost compression in the mid-tier is intensifying because independent packers challenge established refiners with toll-blended alternatives. Fragmented owner-operators exhibit highest price sensitivity, while consolidated fleet operators with 500-plus vehicle counts prioritize total cost of ownership metrics over unit pricing.
Supply Chain Analysis
Extended payment terms from Sasol and coastal terminal operators anchor working capital flexibility for domestic formulators facing import feedstock costs. Geographic supply concentration draws from Qatar, South Korea, and Singapore for hydrocracked Group II/III base stocks. Raw material dependencies include detergent-dispersant additive packages, viscosity index improvers, and pour point depressants. Single-source vulnerability persists in Fischer-Tropsch wax stream allocation, where Sasol's synthetic fuel operations divert feedstocks during diesel margin strength. Distribution runs through Durban's port infrastructure with inland pull through the Johannesburg-Pretoria corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of lubricant formulation specialists graduating from South African universities constrains product development velocity and technical service expansion, creating asymmetric advantage for stakeholders who secure tribology talent ahead of fuel and chemical sector competitors.
For Market Incumbents: Build captive technical service partnerships as a moat against independent packers eroding mid-tier share. Sasol should defend Fischer-Tropsch supply security through long-term offtake agreements with domestic blenders. Engen Petroleum must deepen coastal terminal control to offset import cost volatility. Investment in SANS 1322 testing capacity accelerates product registration timelines against new entrants. For New Entrants and Emerging Players: Establish a beachhead in Eastern Cape automotive manufacturing and Coega IDZ logistics growth where technical service presence remains underdeveloped. Target precision agriculture hydraulic fluid demand in Free State and Mpumalanga through ISO 11158-specified formulations. Leverage online platforms for standardized SANS 1099-compliant products requiring minimal application guidance. Partner with mining contractors at Mogalakwena and Sishen for extended-drain synthetic trials. For Investors and Strategic Acquirers: Euro VI alignment under the National Environmental Management Act reshapes the acquisition landscape toward low-SAPS formulation capability. Long-term viability favors blenders with backward integration into additive packaging or captive base oil supply. Acquisition target archetype: independent packers with SADC export certification and toll-blending relationships. Monitor SANS 1322 laboratory capacity expansion as signal for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Packaging | Secures detergent-chemistry supply independence from multinational additive houses. |
| SANS 1322 Laboratory Capacity Expansion | Reduces product registration bottlenecks for new formulation launches. |
| Eastern Cape Blending Facility Investment | Captures Port Elizabeth-Gqeberha automotive cluster demand with localized supply. |
| Extended-Drain Synthetic Portfolio Launch | Targets mining haul truck operators piloting 1,000-hour service intervals. |
| SADC Harmonization Certification Program | Enables Zimbabwe, Zambia, and Mozambique market access through BIS-equivalent alignment. |
Research Methodology
A standing panel of lubricant formulators, fleet maintenance directors, mining procurement managers, and SANS compliance officers provided ongoing calibration across the study period. Primary interviews with Sasol supply chain executives, Engen Petroleum terminal operators, and independent packer technical directors were cross-validated against secondary sources including South African customs records, Department of Mineral Resources and Energy fuel quality disclosures, and SADC trade protocol documentation. Bottom-up volume builds from end-use segment consumption rates were triangulated against top-down base oil import throughput data from Durban port authorities.
Scenario-bracketing around low-SAPS mandate enforcement timing and Fischer-Tropsch wax stream allocation volatility framed the projection horizon. Segmentation dimensions modeled include product type viscosity grade, end-user procurement scale, distribution channel technical intensity, and provincial regulatory enforcement variation. CAGRs were derived from elasticity-adjusted demand curves incorporating fleet consolidation rates and mechanization trends in construction and agriculture. Industry-specific inputs included mining haul truck population counts and containerized freight modal shift patterns along the Johannesburg-Durban-Cape Town corridor.
Stress conditions across base oil freight rates, rand-dollar exchange volatility, and Euro VI retrofit compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SANS 1099 enforcement consistency and SADC harmonization progress. Macroeconomic contraction, regulatory delay, or synthetic base oil technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market