
 Global Auto Parts and Accessories Market | 2026-2036
Global Auto Parts and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Auto Parts and Accessories Market Analysis
Fleet operators and EV-focused vehicle assemblers are rotating procurement budgets toward electrical systems and brake components as internal combustion architectures lose share. Robert Bosch GmbH leverages its R&D intensity in powertrain electronics to anchor long-term supply contracts with European OEMs. Continental AG competes through manufacturing scale in suspension and braking modules across multiple continents. Michelin differentiates via material science leadership in high-performance rubber compounds for electrified platforms.
Auto parts and accessories encompass engineered components and subsystems manufactured to OEM specifications or aftermarket interchange standards, typically requiring tolerances within micrometers and compliance with SAE or ISO functional test protocols for safety-critical assemblies. These products serve vehicle production, repair, and performance enhancement across passenger, commercial, and specialty vehicle categories. Engine components and electrical systems command the largest revenue pools, while brake systems represent the fastest-growing margin segment as regenerative braking architectures multiply part complexity. Aluminum and steel still dominate material tonnage, though plastic substitution is accelerating in non-structural electrical housings and underhood applications.
The EPA enforces emissions-linked material certifications that constrain steel and aluminum supplier qualification in the United States, while REACH and the EU Green Deal mandate chemical disclosure and recycled content thresholds for rubber and plastic components sold into Europe. China's MEE implements dual carbon goals that tighten smelter emissions standards for aluminum used in engine and suspension castings. Stakeholders must monitor how divergent carbon border mechanisms between the EU, United States, and China reshape sourcing economics for cross-shipped brake and electrical assemblies.
Market Dynamics
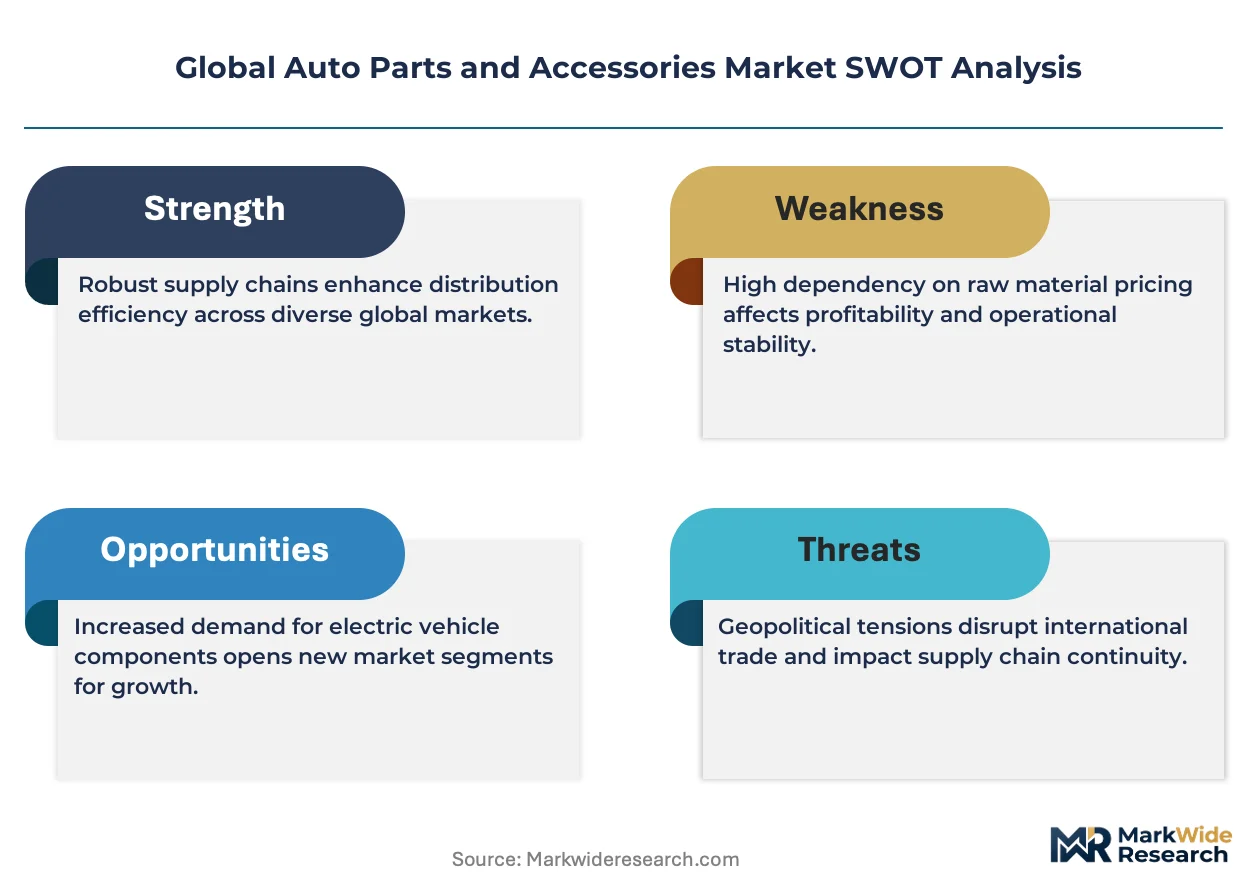
Powertrain electrification is redistributing engineering budgets away from traditional engine components toward electrical architectures and regenerative braking systems, compressing legacy supplier margins while opening new procurement categories.
Growth Catalysts
- EU F-Gas Regulation:Mandates on fluorinated gas containment in vehicle air conditioning systems are accelerating replacement cycles for HVAC components across European fleets.
- Aluminum smelter consolidation:China's MEE emissions standards are concentrating supply of low-carbon primary aluminum for suspension castings, advantaging qualified suppliers.
- Regenerative braking proliferation:Hybrid and battery-electric platforms require integrated brake-by-wire modules that combine friction and energy recovery functions in single assemblies.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings constrain electric motor and sensor actuator production economics.
- Single-source semiconductor dependency:Advanced driver-assistance system chips concentrate in Taiwan and South Korean foundries, creating supply vulnerability.
- REACH chemical disclosure burden:European rubber and plastic compounders face extended certification timelines for new material formulations.
Strategic Opportunities
- India aftermarket expansion:Vehicle parc growth and aging fleets in Maharashtra and Tamil Nadu create demand for brake pad and filter replacement networks.
- Brazil flex-fuel sensor retrofit:Existing ethanol-compatible vehicles require upgraded fuel system components to meet ANVISA quality standards.
- Direct-to-fleet digital procurement:Large commercial operators in Germany bypass traditional distribution tiers through integrated e-procurement platforms.
Industry Challenges
- Embedded software validation:Functional safety certification to ISO 26262 for brake and steering electronics extends development cycles by 18-24 months.
- Cross-border carbon accounting:Divergent EU CBAM and proposed US clean competition rules complicate sourcing decisions for aluminum-intensive components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Auto Parts and Accessories Market |
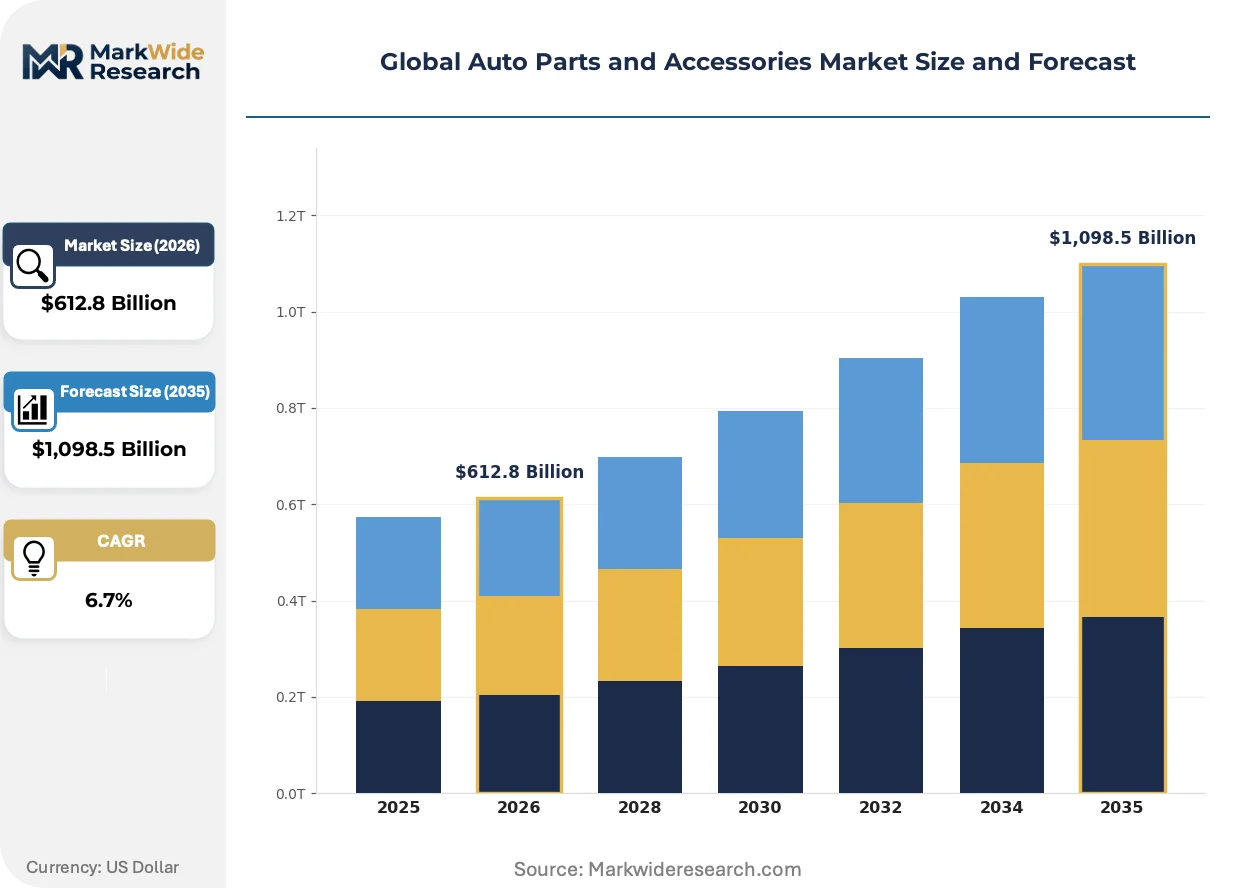
| Market Size in 2026 | $612.8 Billion |
| Market Size in 2035 | $1,098.5 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Electrical Systems, Suspension Parts, Brake Systems End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Distributors Material: Plastic, Aluminum, Steel, Rubber Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesalers, Direct Sales |
| Companies Covered | Fuyao Glass Industry Group, Robert Bosch GmbH, DENSO Corporation, ZF Friedrichshafen AG, Continental AG, Bridgestone Corporation, Michelin, Aptiv PLC, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Auto Parts and Accessories Market Emerging Trajectories
Material science advances and digital integration are compressing product lifecycles while expanding the boundary between mechanical and electronic subsystems in vehicle architectures.
Silicon carbide power semiconductors are replacing silicon IGBTs in inverter modules for electric drivetrains. Tier 1 suppliers in Japan and Germany are qualifying 800-volt architectures for premium platforms. This voltage transition is bifurcating the supplier base between legacy silicon players and compound semiconductor specialists.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of brake friction materials across European supply chains. Manufacturers in Italy and Poland are accelerating ceramic and copper-free compound development. The regulation most affects aftermarket brake pad producers serving passenger vehicle fleets.
Commercial fleet operators are consolidating maintenance spend through outcome-based contracts with component suppliers rather than part-by-part purchasing. Large logistics companies in the United States now specify total cost-per-mile agreements for brake and tire systems. This contracting shift is most advanced in long-haul trucking corridors between Texas and California.
Global Auto Parts and Accessories Market Segmentation
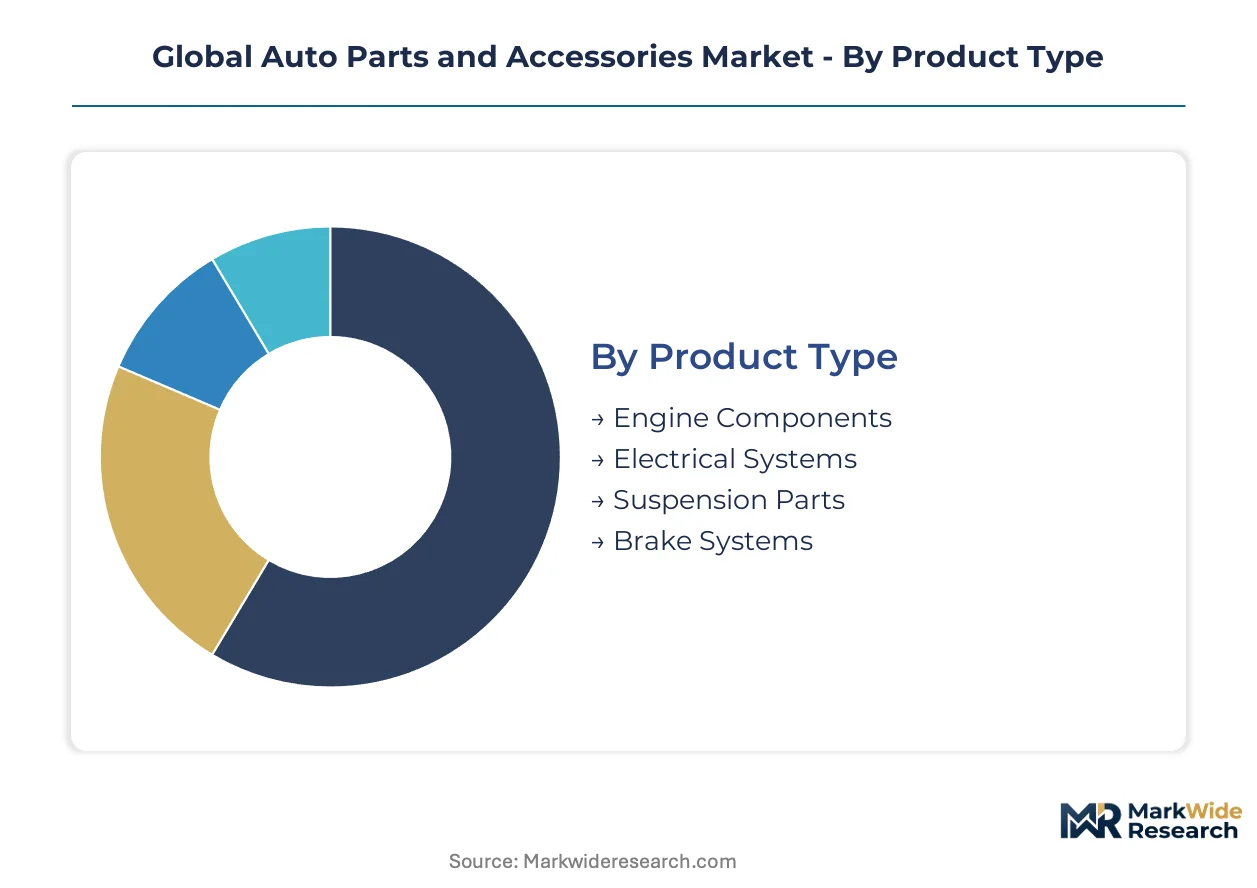
Segmentation in the Global Auto Parts and Accessories Market reveals distinct procurement patterns across electrified powertrains and legacy platforms. Understanding these divisions helps suppliers align R&D investment with channel-specific certification requirements and margin structures.
Product Type:
Engine components and brake systems flow through divergent channels, with electrification redistributing volume toward electrical-intensive categories while legacy engine parts concentrate in aftermarket rebuild networks.
- Engine Components:Precision-machined assemblies including cylinder heads, pistons, and crankshafts meeting SAE J1349 power density specifications. Demand concentrates in aftermarket remanufacturing hubs across Michigan and Guanajuato as internal combustion vehicle parc ages and fleet operators extend service intervals.
- Electrical Systems:Wiring harnesses, battery management modules, and power distribution units requiring ISO 26262 functional safety certification. Procurement from OEMs in Germany and Japan is accelerating as 800-volt architectures proliferate in premium battery-electric platforms.
- Suspension Parts:Control arms, shock absorbers, and steering linkages fabricated from forged aluminum and high-strength steel.
- Brake Systems:Friction materials, calipers, and integrated brake-by-wire modules combining hydraulic and regenerative functions.
By volume, engine components lead. By growth pace, electrical systems are climbing the fastest.
End User:
Cost tier stratification separates specification-heavy OEM contracts from price-sensitive aftermarket procurement, with vehicle assemblers occupying a hybrid position demanding both scale and customization.
- OEMs:Tier 1 suppliers delivering serialized components under long-term supply agreements with embedded quality gates and VDA 6.3 process audits. Volkswagen, Toyota, and Ford anchor demand in Stuttgart, Toyota City, and Dearborn.
- Aftermarket Providers:Independent distributors and service chains sourcing interchangeable parts meeting SAE or ISO interchange standards. Networks across São Paulo and Jakarta are expanding as vehicle parc density rises.
- Vehicle Assemblers:Contract manufacturers and specialty builders requiring flexible batch sizes with shortened lead times.
- Distributors:Regional warehousing operations consolidating inventory for secondary resale to repair shops and fleet maintenance depots.
OEMs command the highest per-unit margins. Aftermarket providers are expanding most quickly in emerging economies.
Material:
Application-specific requirements drive material selection, with structural loads dictating metal grades and electrical isolation favoring polymer formulations.
- Aluminum:Low-carbon primary and secondary alloys for suspension castings and engine blocks, with China's MEE emissions standards concentrating qualified smelter supply. German OEMs specify EN 1706 certified grades for structural applications.
- Steel:High-strength and advanced high-strength grades for chassis and powertrain components. US EPA emissions-linked certifications constrain supplier qualification for domestic OEM programs.
- Plastic:Engineering polymers for electrical housings and underhood applications substituting metal in non-structural roles.
- Rubber:EPDM and natural rubber compounds for seals, hoses, and vibration isolation meeting REACH substance restrictions.
Steel dominates by tonnage. Aluminum is gaining share fastest amid lightweighting mandates.
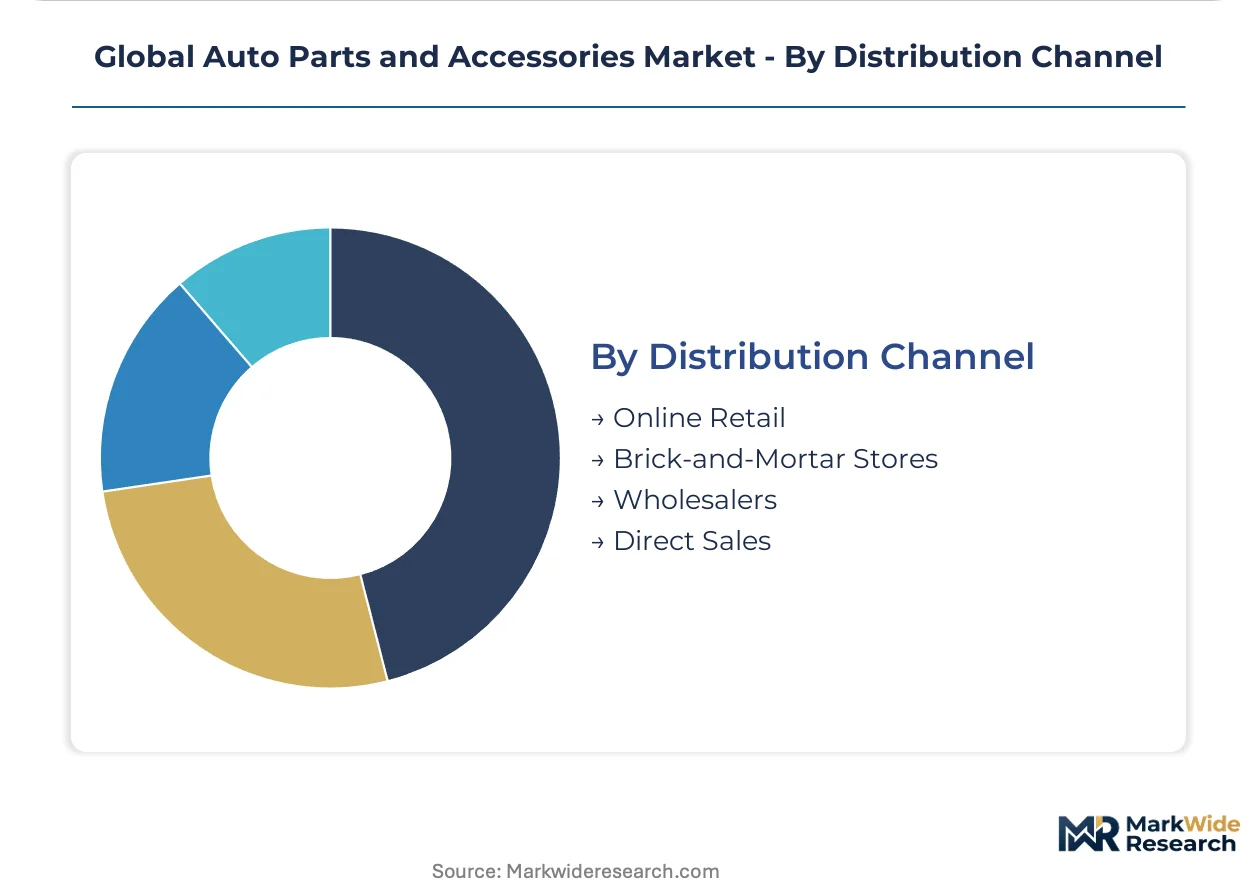
Distribution Channel:
Customer type and order scale determine channel selection, with large fleet operators bypassing traditional tiers while small repair shops rely on consolidated wholesaler networks.
- Wholesalers:Regional distributors maintaining buffer inventory for same-day or next-day fulfillment to independent repair networks. Concentration in Chicago, Düsseldorf, and Shanghai supports geographic coverage for routine maintenance parts.
- Direct Sales:Long-term contracts between Tier 1 suppliers and OEM assembly plants, with sequenced delivery matching production schedules. BMW and Mercedes-Benz procurement teams in Munich and Sindelfingen specify vendor-managed inventory arrangements.
- Online Retail:E-commerce platforms serving DIY consumers and small fleet operators with catalog-based ordering and dropship fulfillment.
- Brick-and-Mortar Stores:Physical retail locations providing immediate availability for emergency repairs and walk-in trade.
Wholesalers handle the greatest transaction volume. Direct sales are expanding most quickly as OEMs consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers export brake-by-wire modules and powertrain electronics to North American OEM assembly plants, while Chinese aluminum casters ship suspension components to European tier-one distributors under REACH-certified supply agreements.
United States
Domestic OEMs in Dearborn and Detroit are expanding procurement of 800-volt electrical architectures for battery-electric truck platforms. EPA emissions-linked material certifications constrain steel and aluminum supplier qualification for domestic programs. Michigan-based remanufacturing hubs concentrate aftermarket engine component rebuild capacity serving aging internal combustion vehicle parc.
Germany
Stuttgart and Munich anchor OEM demand for ISO 26262-certified brake and steering electronics as Volkswagen and BMW accelerate electrification roadmaps. EU F-Gas Regulation mandates accelerate HVAC component replacement cycles across European fleets. Baden-Württemberg suppliers leverage VDA 6.3 process audits to anchor long-term supply contracts with premium vehicle assemblers.
China
Shanghai and Yangtze River Delta clusters concentrate aluminum smelter capacity qualified under MEE dual carbon emissions standards for suspension castings. Domestic EV fleet operators are expanding procurement of brake and electrical components as powertrain architectures shift. MIIT implementation of GB standards for vehicle electronics is tightening certification timelines for wiring harness suppliers.
Japan
Tokyo and Toyota City anchor OEM demand for silicon carbide power semiconductors in 800-volt inverter modules. METI industrial policy supports qualification of compound semiconductor specialists for premium battery-electric platforms. Chubu region suppliers concentrate manufacturing scale for suspension and braking modules serving export markets.
India
Maharashtra and Tamil Nadu vehicle parc growth is creating aftermarket demand for brake pad and filter replacement networks. BIS quality standards are tightening certification requirements for electrical system components sold into domestic assembly plants. Pune-based distributors are expanding warehousing capacity to serve independent repair networks across western India.
Global Auto Parts and Accessories Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive R&D in powertrain electronics and braking systems. Tier-one suppliers anchor long-term contracts through embedded quality gates and vendor-managed inventory arrangements. Strategic archetypes include integrated system suppliers, material science specialists, and scale-driven component fabricators. Competitive moves concentrate on M&A for electrical architecture capabilities and geographic expansion into Indian and Brazilian aftermarket networks.
Among diversified system suppliers, Robert Bosch GmbH and Continental AG exemplify the integrated tier-one archetype through their positioning across braking, suspension, and powertrain electronics. DENSO Corporation occupies a parallel position among Japanese industrial groups with concentrated capability in thermal and electrical systems. Michelin represents the material science specialist archetype through its leadership in high-performance rubber compounds for electrified platforms.
| Leading Market Players |
|---|
| Fuyao Glass Industry Group |
| Robert Bosch GmbH |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| Bridgestone Corporation |
| Michelin |
| Aptiv PLC |
| Sumitomo Electric Industries |
| Others |
Supply Flow & Price Mechanics
EPA emissions-linked material certifications gate both supplier qualification and price differentiation across brake and electrical component procurement in the United States, compressing margins for uncertified producers while enabling premium positioning for qualified Tier 1 suppliers serving OEM assembly plants.
Pricing Analysis
800-volt electrical architectures command substantial premiums over legacy 400-volt systems, while silicon IGBT-based inverters face accelerating price erosion as silicon carbide power semiconductors displace them in premium battery-electric platforms. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 functional safety certification grade and volume scale, with OEM direct contracts showing least price sensitivity and aftermarket distributors facing intense cost compression from independent repair networks in Maharashtra and São Paulo.
Supply Chain Analysis
China and Germany anchor aluminum smelter and precision casting capacity for suspension components, while Taiwan and South Korea concentrate foundry output for advanced driver-assistance system semiconductors. The supply chain draws from neodymium and dysprosium rare earth deposits, low-carbon primary aluminum qualified under MEE emissions standards, and copper-free brake friction materials reformulated for REACH compliance. Single-source semiconductor dependency in Taiwanese foundries creates acute supply vulnerability. Distribution runs through vendor-managed inventory arrangements at BMW and Mercedes-Benz assembly plants, regional wholesaler networks in Chicago and Düsseldorf, and direct-to-fleet digital procurement platforms serving German commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through emissions-linked material certifications and ISO 26262 functional safety requirements creates formidable defensive moats for qualified suppliers, as switching costs lock OEMs into long-term supply agreements with audited Tier 1 partners.
For Market Incumbents: Fortify market position through backward integration into silicon carbide wafer supply and captive qualification of 800-volt electrical architectures, while expanding vendor-managed inventory arrangements with Volkswagen and BMW to deepen switching cost advantages against emerging compound semiconductor specialists. For New Entrants and Emerging Players: Lead with ceramic and copper-free brake friction materials targeting European aftermarket pad replacement cycles accelerated by REACH substance restrictions, deploying direct-to-fleet digital procurement platforms to bypass entrenched wholesaler tiers serving aging vehicle parc in India and Brazil. For Investors and Strategic Acquirers: EU F-Gas Regulation and China's dual carbon goals reshape the acquisition landscape toward suppliers with MEE-qualified aluminum smelter relationships and REACH-certified rubber compound formulations. Long-term viability centers on electrical architecture capabilities rather than legacy engine component exposure. Monitor MIIT implementation of GB standards for vehicle electronics as the critical inflection signal for wiring harness supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces part complexity for brake-by-wire modules across Volkswagen and BMW electrification roadmaps. |
| Battery Supply Agreement | Secures 800-volt architecture qualification for silicon carbide inverter modules in premium platforms. |
| Software-Defined Vehicle Investment | Accelerates ISO 26262 certification for integrated brake and steering electronics at Robert Bosch. |
| Geographic Manufacturing Footprint | Positions aluminum casting capacity near Yangtze River Delta EV assembly clusters under MEE standards. |
| Charging Infrastructure Partnership | Links electrical system procurement to fleet operator outcome-based contracts in Texas-California corridors. |
Methodological Framework
The analysis maps engine components, electrical systems, brake systems, and suspension parts, each validated through Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations heads, combining primary interviews with secondary sources including vehicle production databases, IHS Markit registration data, EPA emissions certifications, and REACH substance filings, with bottom-up and top-down triangulation across segmentation dimensions.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, modeling propulsion architecture, content per vehicle, OEM tier, and regional production cluster to derive growth trajectories, with CAGRs reflecting electric vehicle penetration curves, aluminum lightweighting adoption rates, and regulatory compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in EPA emissions-linked certifications, EU F-Gas Regulation, and China's MEE dual carbon standards; material policy shifts in carbon border mechanisms or REACH substance restrictions would require re-modeling. Recalibration cycles align with material shifts in powertrain electrification, rare earth magnet pricing, and semiconductor foundry capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Connecting Rods Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Nigeria Commercial Vehicles Lubricants Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Composite Leaf Springs Market