
 Brake Fluids Market | 2026-2036
Brake Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Fluids Market Outlook
Multi-source procurement among tier-one automotive suppliers is expanding as vehicle electrification strains legacy supply agreements. Exxon Mobil Corporation leverages its integrated base oil refining to secure cost-advantaged glycol ether feedstocks for DOT 4 production. Robert Bosch GmbH anchors its aftermarket position through captive distribution into European service centers. FUCHS competes on formulation specialization, particularly for racing and high-performance DOT 5.1 segments where thermal stability thresholds exceed standard commercial requirements.
Brake fluids are non-compressible hydraulic media formulated from glycol ethers, borate esters, or silicone bases, designed to transmit force from the master cylinder to wheel calipers across temperature extremes spanning minus forty to over two hundred degrees Celsius. Their primary industrial purpose centers on ensuring consistent friction transfer and corrosion inhibition within sealed braking systems subjected to thermal cycling and moisture ingress. DOT 4 formulations lead volume consumption owing to their compatibility with anti-lock braking systems and broader vehicle parc coverage, while synthetic sub-categories command margin premiums through extended service intervals. Racing cars represent the fastest-growing application niche as motorsport sanctioning bodies tighten minimum dry boiling point specifications.
DOT standards administered by the US NHTSA establish minimum wet and dry boiling point thresholds that shape product development roadmaps for North American suppliers. REACH compliance through ECHA governs glycol ether constituent disclosure across European formulations, directly influencing reformulation costs and import market access. China's SAMR enforces GB 12981 conformance for brake fluids sold into domestic OEM channels. Stakeholders must monitor divergence between regional boiling point specifications and emerging compatibility requirements for regenerative braking architectures.
Market Dynamics
Vehicle electrification is compressing brake fluid replacement intervals while simultaneously elevating thermal performance thresholds as regenerative braking systems expose hydraulic circuits to novel heat cycling patterns.
Growth Catalysts
- China's GB 12981 Standard Tightening:MIIT mandates elevated wet boiling point minimums for new energy vehicles, forcing formulation upgrades across domestic OEM supply chains.
- Commercial Fleet Replacement Acceleration:United States heavy-duty truck operators are compressing DOT 4 changeout cycles from 24 months to 12 months amid intensified DOT inspection enforcement.
- Racing Motorsport Specification Escalation:FIA and NASCAR sanctioning bodies are raising minimum dry boiling point thresholds above 260°C, creating premium synthetic sub-category demand.
Market Restraints
- Glycol Ether Feedstock Volatility:Ethylene oxide and propylene oxide price swings transmit directly to DOT 3 and DOT 4 production economics, squeezing blender margins.
- European REACH Compliance Burden:ECHA disclosure requirements for borate ester constituents add 8-14% to reformulation costs and delay new product introductions by 6-9 months.
- Silicone-Based DOT 5 Substitution Ceiling:Incompatibility with ABS modulator seals limits DOT 5 penetration to niche military and classic vehicle segments below 3% of volume.
Strategic Opportunities
- India Two-Wheeler Aftermarket White Space:BIS certification gaps in informal service channels create branded DOT 3 and DOT 4 penetration potential as scooter parc expands.
- Regenerative Braking Fluid Formulation Gap:Conventional glycol ethers degrade faster under hybrid brake blending cycles, opening specialized high-thermal-stability product development.
- Direct-to-Fleet Digital Distribution:Amazon Business and specialized B2B platforms are disintermediating traditional jobber networks for commercial vehicle maintenance procurement.
Industry Challenges
- Formulation Chemist Talent Scarcity:Expertise in borate ester synthesis and corrosion inhibitor balancing is concentrating at legacy suppliers, constraining new entrant R&D velocity.
- Multi-Regional Certification Parallel Tracking:Simultaneous NHTSA, ECE R90, and GB 12981 homologation requires duplicative testing protocols, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Fluids Market |
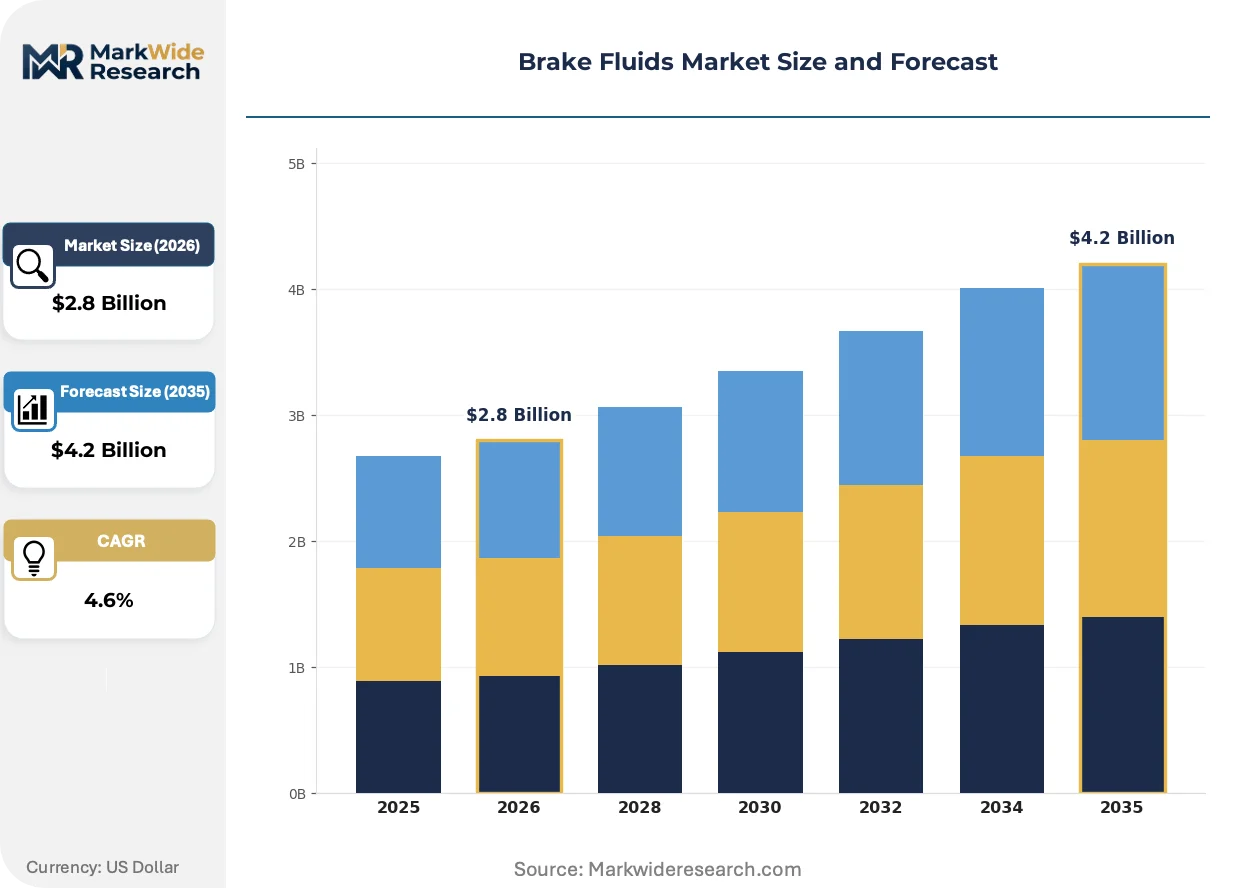
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DOT 3, DOT 4, DOT 5, DOT 5.1, Synthetic Application: Passenger Vehicles, Commercial Trucks, Motorcycles, Off-road Vehicles, Racing Cars End User: OEMs, Aftermarket Providers, Maintenance Workshops, Vehicle Assemblers Distribution Channel: Automotive Dealerships, Online Retailers, Auto Parts Stores, Service Centers |
| Companies Covered | Exxon Mobil Corporation, TotalEnergies, BP p.l.c (Castrol), FUCHS, Valvoline Inc., Chevron Corporation, Royal Dutch Shell plc, Robert Bosch GmbH, Liqui Moly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Fluids Market Strategic Shifts
Brake fluid technology is bifurcating between commodity DOT 3 and DOT 4 formulations serving legacy internal combustion parc and advanced synthetic chemistries engineered for electrified powertrain thermal regimes.
Low-conductivity DOT 4 LV formulations are electrifying brake system architecture design. These fluids reduce electrical conductivity below 50 μS/cm to prevent current leakage in integrated brake-by-wire systems. BMW and Tesla are specifying them for 48V mild-hybrid platforms. The technology is electrifying supplier R&D roadmaps away from conventional glycol ether bases toward silicate-enhanced borate ester hybrids.
REACH Annex XIV authorization processes are tightening glycol ether constituent oversight across European formulations. ECHA is evaluating boric acid and specific ethylene glycol ethers for potential restriction or authorization requirements. German and French aftermarket distributors are accelerating inventory turnover to avoid stranded stock, compressing pricing power for non-compliant legacy SKUs.
Commercial fleet maintenance departments are consolidating brake fluid procurement under national account structures. Large United States trucking operators are bypassing regional jobbers to negotiate direct supply agreements with blenders. The shift is most visible in the Southeast where Werner Enterprises and J.B. Hunt have established captive distribution hubs for DOT 4 bulk delivery.
Brake Fluids Market Segmentation
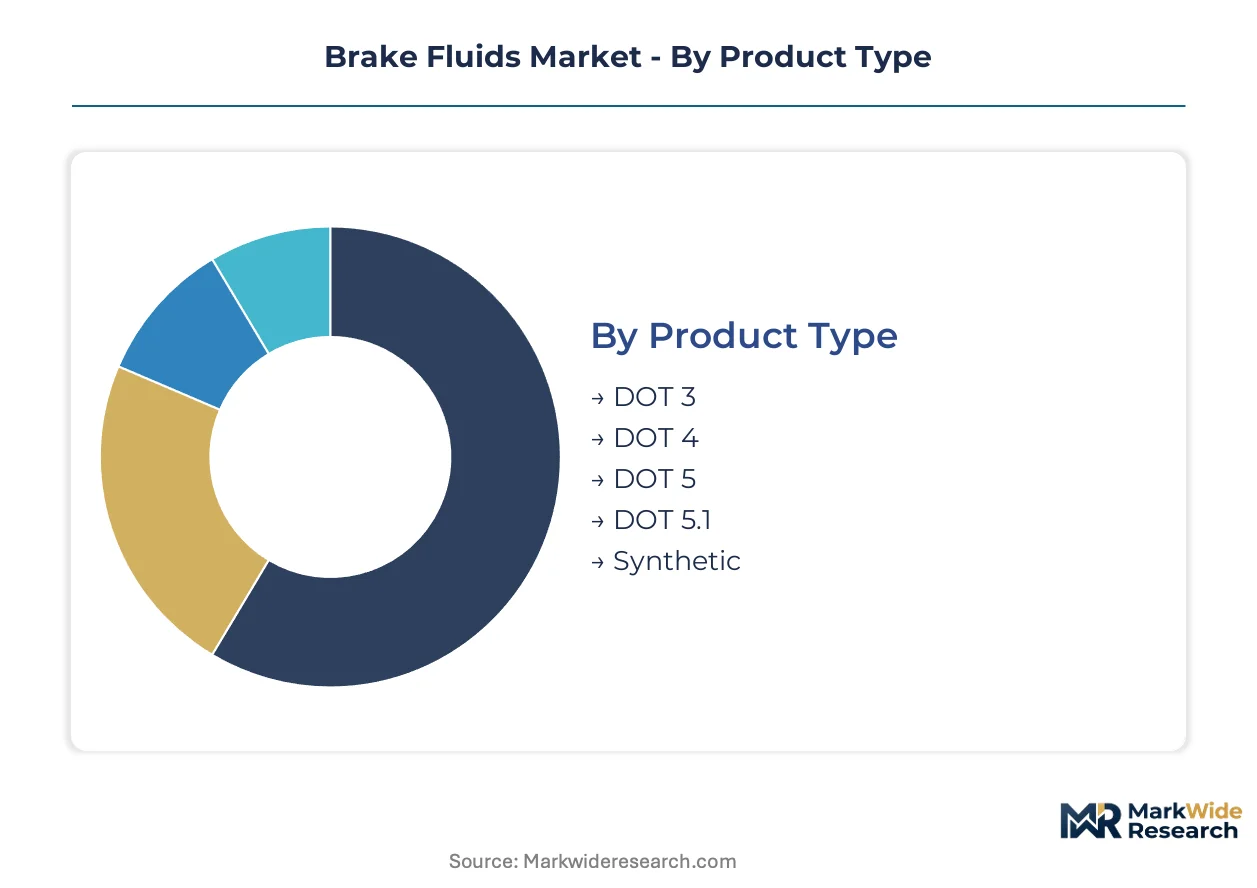
Brake fluid procurement patterns diverge sharply across specification grades and vehicle architectures. Electrification is fragmenting demand between legacy glycol-ether formulations and low-conductivity synthetic chemistries engineered for brake-by-wire systems.
Product Type:
Capital intensity escalates with boiling point thresholds and additive complexity, borate ester synthesis demanding specialized reactor infrastructure absent from commodity glycol ether blending.
- DOT 3:Glycol ether-based formulations with minimum dry boiling point of 205°C serve aging vehicle parc and price-sensitive aftermarket channels. Demand concentrates in India and Southeast Asia where two-wheeler density sustains volume despite specification obsolescence in developed markets.
- DOT 4:Borate ester-enhanced chemistry delivers 230°C dry boiling point minimums required for ABS-equipped passenger vehicles and commercial trucks. United States fleet operators are compressing replacement cycles amid intensified NHTSA inspection protocols, absorbing the bulk of North American blender capacity.
- DOT 5:Silicone-based formulations achieve hydrophobic stability for military and classic vehicle preservation segments. Incompatibility with ABS modulator seals constrains addressable market below three percent of global volume.
- DOT 5.1:Glycol ether chemistry meeting DOT 5 boiling point specifications bridges compatibility and performance for high-performance road vehicles.
- Synthetic:Proprietary low-conductivity and extended-service formulations command formulation premiums through specialized additive packages.
DOT 4 absorbs the bulk of installed capacity; synthetic grades are expanding most quickly as electrified architectures proliferate.
Application:
Vehicle architecture determines thermal cycling severity and fluid degradation rates, with regenerative braking systems exposing hydraulic circuits to novel heat management demands.
- Passenger Vehicles:Mass-market OEM specifications center on DOT 4 compatibility across ABS and ESC-equipped platforms. China's MIIT is tightening GB 12981 wet boiling point minimums for new energy vehicles, forcing formulation upgrades across domestic supply chains.
- Commercial Trucks:Heavy-duty hydraulic systems operating under sustained load cycles demand elevated wet boiling point retention. United States operators including Werner Enterprises and J.B. Hunt have established captive distribution hubs for bulk DOT 4 procurement.
- Motorcycles:Smaller reservoir volumes and exposed brake lines accelerate moisture ingress, shortening service intervals relative to enclosed automotive systems.
- Off-road Vehicles:Contaminated operating environments prioritize seal compatibility and corrosion inhibition over extended service intervals.
- Racing Cars:FIA and NASCAR sanctioning bodies are raising minimum dry boiling point thresholds above 260°C, creating premium synthetic sub-category demand with steepest expansion trajectory.
Passenger vehicles anchor volume consumption; racing applications command the highest per-liter pricing multiples.
End User:
Procurement sophistication varies with technical specification authority and inventory carrying capacity.
- OEMs:Long-term supply agreements with formulation lock-in and homologation testing requirements dominate passenger vehicle and commercial truck factory fill. German and Japanese automakers are specifying low-conductivity DOT 4 LV for 48V mild-hybrid platforms.
- Aftermarket Providers:Brand-agnostic distributors serving independent service channels compete on logistics coverage and price positioning.
- Maintenance Workshops:Quick-service operators prioritize inventory turnover and OEM approval certifications over formulation differentiation.
- Vehicle Assemblers:Contract manufacturers and kit builders source fluids under delegated procurement arrangements from tier-one system suppliers.
OEMs lock in the longest supply commitments; aftermarket providers are gaining share fastest through digital distribution platforms.
Distribution Channel:
Channel economics reflect customer acquisition costs and technical consultation requirements.
- Automotive Dealerships:Captive service bays leverage OEM approval status to command specification premiums on factory-recommended formulations.
- Online Retailers:Amazon Business and specialized B2B platforms are disintermediating traditional jobber networks for commercial fleet maintenance procurement.
- Auto Parts Stores:Retail-focused chains serving DIY enthusiasts and independent mechanics emphasize private-label DOT 3 and DOT 4 volume SKUs.
- Service Centers:European chains including Bosch Car Service anchor aftermarket position through captive distribution and technical training certification.
Service centers capture the highest-margin synthetic formulations; online retailers are expanding share fastest in commercial fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States commercial fleet operators are compressing DOT 4 replacement cycles amid intensified NHTSA inspection enforcement, while China's MIIT mandates elevated wet boiling point minimums for new energy vehicles. Germany and Japan anchor European and Asian formulation sophistication respectively.
United States
Heavy-duty truck operators including Werner Enterprises and J.B. Hunt have established captive distribution hubs for bulk DOT 4 procurement in the Southeast. NHTSA DOT standards shape product development roadmaps with minimum wet and dry boiling point thresholds. Detroit and the broader Midwest industrial corridor concentrate blender capacity serving domestic OEM factory fill requirements.
China
Domestic OEM supply chains are forcing formulation upgrades as new energy vehicle production scales. MIIT's GB 12981 standard tightening mandates elevated wet boiling point minimums specifically for electrified platforms. Shanghai and the Yangtze River Delta cluster hosts the majority of indigenous brake fluid blending capacity serving BYD and domestic EV manufacturers.
Germany
Aftermarket distribution anchors through Bosch Car Service chains with technical training certification requirements. ECHA REACH compliance governs glycol ether constituent disclosure, adding reformulation costs across European formulations. Stuttgart and Bavaria concentrate automotive chemical R&D facilities developing low-conductivity DOT 4 LV specifications for 48V mild-hybrid platforms.
Japan
Automotive OEMs specify extended-service synthetic formulations with specialized additive packages for hybrid architectures. METI oversees industrial chemical standards alignment with international DOT specifications. Nagoya and the Chubu region host precision chemical blending operations supplying Toyota and Honda factory fill programs.
India
Two-wheeler density sustains DOT 3 and DOT 4 volume in informal service channels despite specification obsolescence elsewhere. BIS certification gaps create branded penetration potential as scooter parc expands. Maharashtra and Gujarat industrial corridors concentrate indigenous blending capacity serving Maruti Suzuki and Hero MotoCorp supply chains.
Brake Fluids Market Competitive Environment
Capacity expansion dominates the current landscape as integrated refiners and independent blenders race to secure glycol ether feedstock positions. The vendor base stratifies across three tiers: multinational oil majors with backward integration into base oil refining, specialized automotive chemical formulators with homologation expertise, and regional blenders competing on logistics coverage. Strategic archetypes include feedstock-integrated volume players, formulation-specialist premium-positioned operators, and aftermarket-distribution-captive service networks. M&A activity and geographic expansion into India's two-wheeler aftermarket represent the dominant competitive moves.
Among feedstock-integrated majors, Exxon Mobil Corporation exemplifies the archetype leveraging integrated base oil refining to secure cost-advantaged glycol ether positions. Robert Bosch GmbH anchors the aftermarket-distribution-captive model through European service center networks. FUCHS occupies the formulation-specialist tier, with its GmbH structure signaling German engineering heritage and premium positioning in high-performance segments where thermal stability thresholds exceed standard commercial requirements.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| TotalEnergies |
| BP p.l.c (Castrol) |
| FUCHS |
| Valvoline Inc. |
| Chevron Corporation |
| Royal Dutch Shell plc |
| Robert Bosch GmbH |
| Liqui Moly |
| Others |
Value Chain & Pricing Dynamics
Specification-grade bifurcation between DOT 4 commodity formulations and low-conductivity synthetic grades manifests in divergent margin structures and supply chain footprints across the brake fluids market. Premium synthetic chemistries command formulation premiums through specialized borate ester additive packages while commodity glycol ether blending concentrates in high-volume, low-margin regional operations serving price-sensitive aftermarket channels.
Pricing Analysis
Volume absorption concentrates in DOT 4 borate ester formulations where wet boiling point retention drives specification compliance, while margin capture clusters in synthetic low-conductivity grades for electrified architectures. Price differentiation hinges on GB 12981 certification tier for China OEM supply and NHTSA DOT boiling point thresholds for United States commercial fleet procurement. Pricing pressure stems from ethylene oxide and propylene oxide feedstock volatility transmitting directly to blender cost structures. Commercial fleet operators exhibit highest price sensitivity through national account consolidation, while racing motorsport channels absorb premium multiples with minimal elasticity.
Supply Chain Analysis
Freight cost escalation from glycol ether feedstock origins in the United States Gulf Coast and Middle East petrochemical complexes shapes regional blender location decisions. Manufacturing concentrates in China, Germany, and the United States where integrated refiners secure backward positions in ethylene oxide supply. Raw material dependencies rest on borate ester intermediates, corrosion inhibitor packages, and silicate enhancement chemistries. Supply chain risk centers on REACH Annex XIV authorization timelines for glycol ether constituents creating stranded inventory exposure. Distribution runs through captive OEM supply agreements for factory fill and Bosch Car Service networks for European aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock volatility and multi-regulatory homologation burdens are compressing margins for non-integrated blenders, forcing consolidation toward refiners with captive glycol ether positions and formulators with established certification expertise.
For Market Incumbents: Anticipate margin compression from Chinese domestic blender capacity expansion by locking in long-term ethylene oxide supply contracts and accelerating low-conductivity DOT 4 LV certification for 48V mild-hybrid platforms. Prioritize homologation investment to compress ECHA REACH compliance timelines and defend aftermarket share against Amazon Business fleet disintermediation. For New Entrants and Emerging Players: GB 12981 tightening in China opens a window for formulation-specialist positioning in domestic NEV supply chains where indigenous blending capacity lags specification requirements. Target India's two-wheeler aftermarket through BIS certification investment in informal service channels, leveraging direct digital distribution to bypass entrenched jobber networks. For Investors and Strategic Acquirers: Re-rating potential sits with borate ester synthesis specialists given MIIT mandate acceleration and regenerative braking thermal stability demand. Long-term viability favors targets with dual NHTSA-ECE R90 homologation capabilities and established OEM technical service relationships. Monitor ethylene oxide contract price spreads as inflection indicator for integrated versus non-integrated blender margin divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Secures cost-advantaged feedstock positions against propylene oxide price volatility. |
| Low-Conductivity Formulation Certification | Unlocks BMW and Tesla 48V mild-hybrid platform specifications ahead of competitor homologation. |
| Direct-to-Fleet Digital Distribution | Disintermediates traditional jobber networks serving Werner Enterprises and J.B. Hunt procurement. |
| Multi-Regional Homologation Parallel Tracking | Compresses NHTSA, ECE R90, and GB 12981 launch timelines for electrified vehicle platforms. |
| Racing Motorsport Specification Development | Captures FIA and NASCAR dry boiling point premiums above 260°C threshold requirements. |
Study Parameters
Independent corroboration across formulation chemists at tier-one automotive suppliers, procurement directors at commercial fleet operators, and technical directors at brake system OEMs underwrites the qualitative findings. Secondary validation draws from NHTSA DOT standard filings, ECHA REACH authorization databases, MIIT GB standard publications, and customs trade data for glycol ether and borate ester import flows. Bottom-up segment sizing triangulates against top-down OEM factory fill and aftermarket replacement cycle estimates.
Comparable-period anchoring to historical vehicle production and brake fluid consumption patterns establishes the forecast baseline across the projection horizon. The analytical framework models product type segmentation by DOT grade and boiling point specification, application segmentation by vehicle architecture thermal cycling severity, and end-user segmentation by procurement sophistication and inventory carrying capacity. CAGRs derive from vehicle parc growth, electrification penetration rates, and replacement interval compression factors.
The model assumes a particular technology adoption path; alternative pathways for brake-by-wire system penetration or solid-state brake architecture displacement would alter the outlook. Forecasts reflect assumptions regarding GB 12981 enforcement timelines, REACH authorization outcomes, and commercial fleet inspection protocol intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Brass Synchronizer Ring Market
Automotive Parts
Motor Bearings Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Hydraulic Lash Adjuster Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market