
 Automotive Pinion Gear Market | 2026-2036
Automotive Pinion Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pinion Gear Market Analysis
China's Jiangsu province is reconfiguring automotive component supply chains through dedicated gear-machining industrial parks. GKN PLC leverages backward integration into powder-forging operations to control alloy-grade consistency across differential pinion lines. Robert Bosch GmbH sustains R&D intensity in electromechanical steering pinions, anchoring its position in rack-and-pinion architectures for electric vehicles. ZF Friedrichshafen AG competes through modular gear-set platforms that span multiple torque ratings without retooling.
An automotive pinion gear is a small-diameter cylindrical gear with precision-cut teeth that meshes with a larger ring or rack gear to transmit torque and motion, typically manufactured through hobbing, shaping, or grinding processes with surface hardness reaching 58-64 HRC after case hardening. Its primary purpose sits within drivetrain and steering subsystems, converting rotational input from driveshafts or steering columns into directional force with minimal backlash. Helical pinion variants command the largest share among product types due to their smoother engagement profiles and higher load-bearing capacity in passenger vehicle transmissions. Steel dominates the material category through forged alloy compositions that withstand cyclic contact stresses, though composite experimentation is accelerating in lightweighting-focused EV programs.
NHTSA Federal Motor Vehicle Safety Standards govern steering-system integrity requirements that directly shape pinion fatigue-test protocols for US-bound production. EPA Corporate Average Fuel Economy mandates push OEMs toward lower-friction gear designs, tightening tolerances on tooth surface finish and lubrication retention. The EU Green Deal's embedded carbon tracking extends through automotive supply tiers, pressuring European gear producers to document smelting-source emissions for alloy steel inputs. Stakeholders must monitor how battery-electric platform architectures eliminate traditional multi-speed transmissions while creating new precision-steering and e-axle reduction gear requirements.
Market Dynamics
Electric vehicle platform architectures are compressing traditional multi-speed transmission volumes while simultaneously expanding precision-steering and e-axle reduction gear specifications, forcing suppliers to retool capability portfolios around torque-dense helical geometries.
Growth Catalysts
- EPA fuel-efficiency mandates:OEMs source lower-friction tooth profiles with tighter surface-finish tolerances to meet Corporate Average Fuel Economy thresholds.
- Powder-forging process adoption:Alloy-grade consistency improvements enable higher contact-stress durability in differential pinion applications.
- Baden-Württemberg supplier cluster:Germany's transmission engineering concentration accelerates precision-machining capability diffusion to tier-two gear producers.
Market Restraints
- Alloy steel input volatility:Smelting-source emission documentation requirements under EU Green Deal carbon tracking increase raw material qualification costs.
- Single-source hobbing equipment dependency:Precision gear-grinding machine supply concentrates among German and Japanese capital equipment builders.
- Case-hardening depth limitations:Surface hardness specifications of 58-64 HRC create processing bottlenecks for high-volume EV pinion runs.
Strategic Opportunities
- Jiangsu province industrial parks:Dedicated gear-machining zones in China offer integrated forging-to-finishing capacity for export-oriented suppliers.
- Rack-and-pinion electromechanical steering:EV steering architecture transitions create demand for noise-optimized pinion geometries.
- NHTSA noise-emission standards:Federal Motor Vehicle Safety Standards testing protocols favor suppliers with in-house acoustic validation laboratories.
Industry Challenges
- CNC gear-grinding programmer scarcity:Tooth-profile correction algorithms require specialized metrology expertise that outpaces vocational training output.
- Heat-treatment furnace certification timelines:Automotive IATF 16949 audit cycles delay new alloy qualification by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pinion Gear Market |
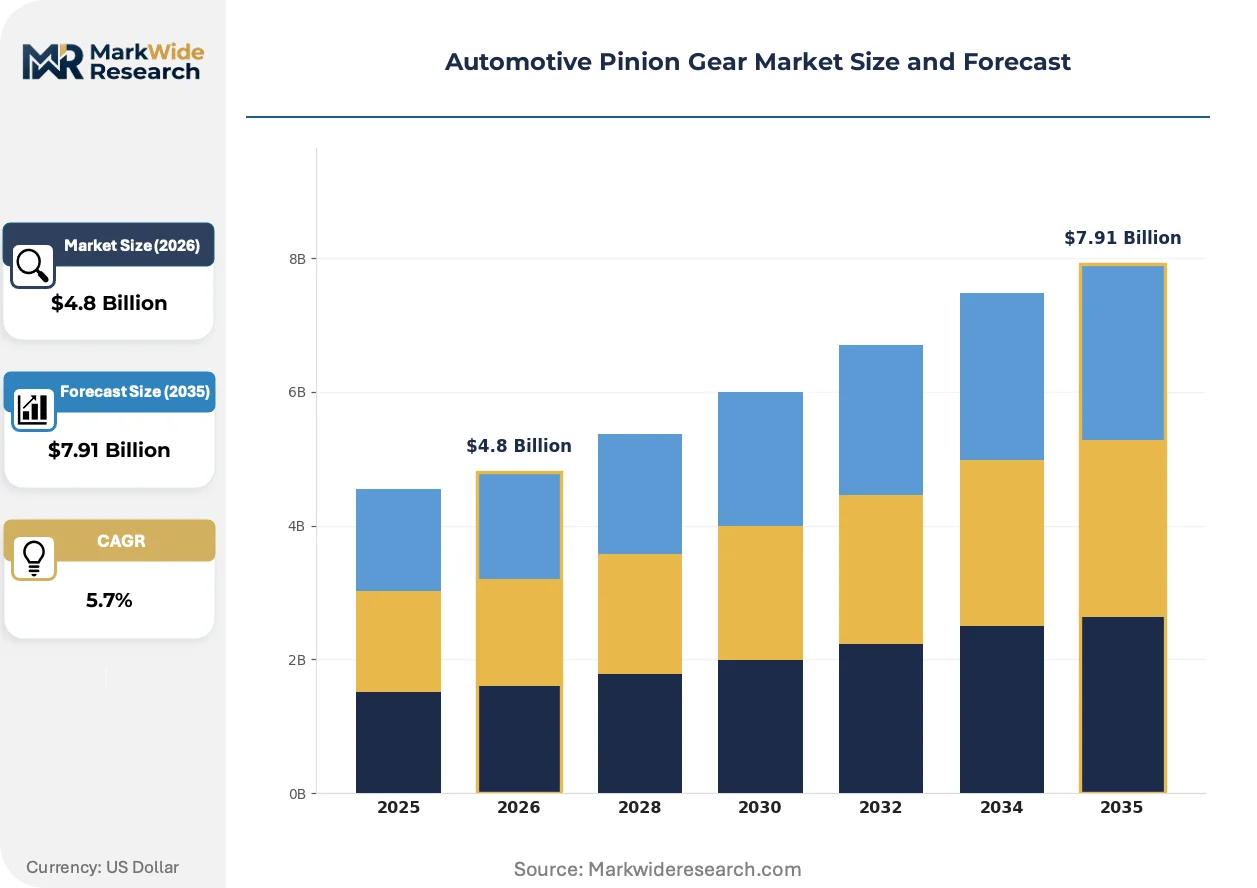
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Pinion, Helical Pinion, Bevel Pinion, Worm Pinion Material: Steel, Aluminum, Plastic, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Repair Shops Gear Ratio: High Ratio, Low Ratio, Medium Ratio, Variable Ratio |
| Companies Covered | GKN PLC, Robert Bosch GmbH, SHOWA Corporation, ZF Friedrichshafen AG, Dana Incorporated, Bharat Gears Ltd., American Axle & Manufacturing Holdings Inc., JTEKT Corporation, Eaton Corporation plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pinion Gear Market Emerging Trajectories
Manufacturing process convergence and regulatory tightening are compressing traditional gear-making timelines while elevating precision requirements beyond legacy equipment capabilities.
Hybrid composite-steel pinion construction is hybridizing forged alloy cores with carbon-fiber-reinforced polymer webs to reduce rotating mass in e-axle reduction stages. Tier-one suppliers in Stuttgart and Shanghai are piloting these geometries for 2026 platform launches. The approach is hybridizing material science with traditional metalworking, forcing gear shops to add polymer processing cleanrooms alongside CNC floors.
REACH embedded carbon disclosure rules are extending through automotive supply tiers to document alloy steel smelting emissions from European mills. Gear producers in Germany and Italy now face quarterly sustainability audits from OEM customers. Differential pinion lines serving EU-bound vehicles carry the heaviest documentation burden, with some suppliers shifting forging operations to electric-arc furnace sources.
Consolidated procurement through platform engineering teams is displacing traditional component-sourcing relationships as OEMs specify complete e-axle modules rather than discrete gears. Tier-one integrators like ZF Friedrichshafen and GKN now control pinion specification authority that previously sat with transmission specialists. This concentration is most visible in Germany's OEM engineering centers, where modular gear-set platforms span multiple torque ratings without supplier retooling.
Automotive Pinion Gear Market Segmentation
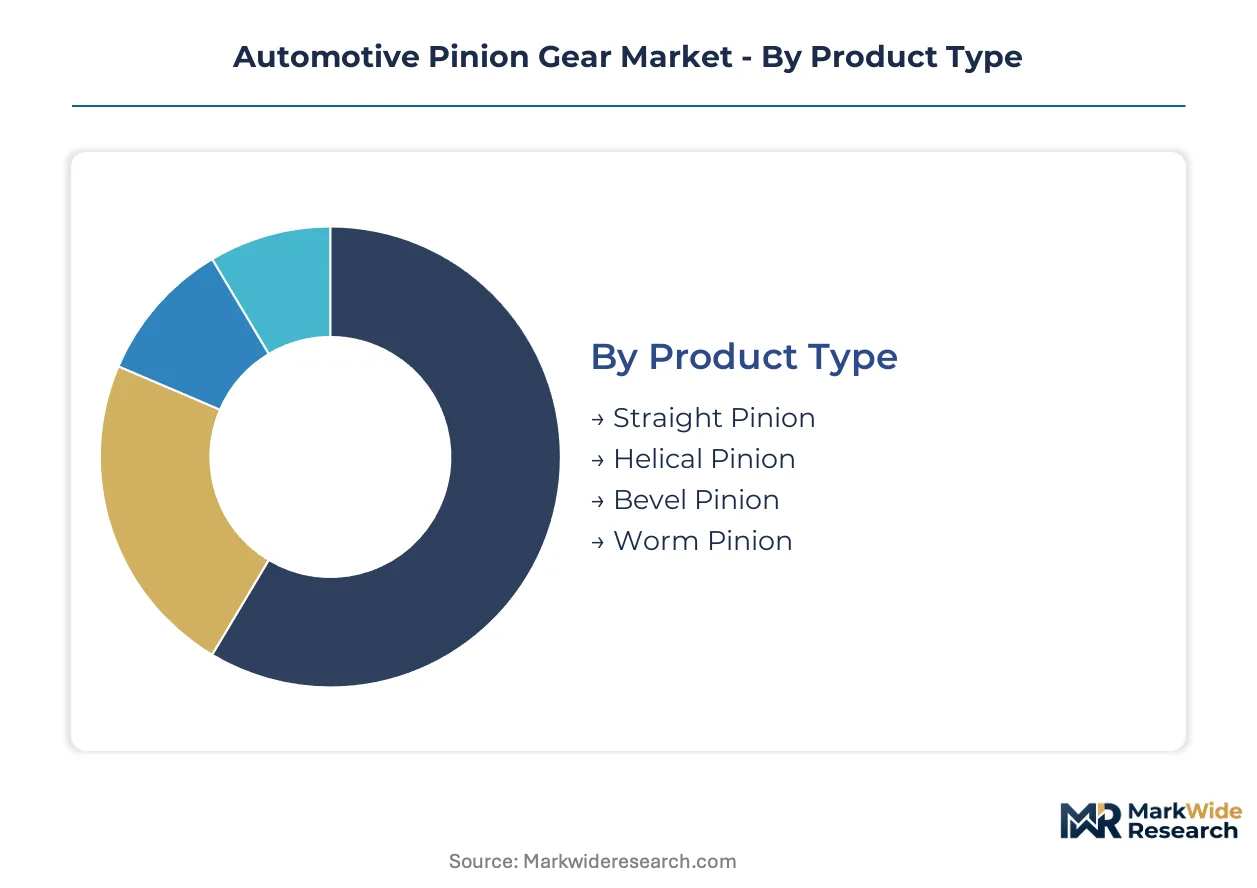
Automotive pinion gear segmentation reveals how torque density requirements, weight reduction mandates, and powertrain electrification are fragmenting demand across geometries and material systems. Each dimension carries distinct certification burdens and capital intensity profiles that reshape supplier competitive position.
Product Type:
Cost tier differentiation separates precision-machined helical geometries from conventional straight-cut alternatives in transmission and steering applications.
- Straight Pinion:Spur-tooth geometry with parallel-axis engagement suits manual transmission reverse gears and low-cost steering racks. Demand concentrates in India's commercial vehicle hub around Pune, where cost-sensitive axle manufacturers prioritize tool-life economy over noise optimization.
- Helical Pinion:Angled tooth profiles enable gradual mesh engagement that reduces NVH in passenger vehicle automatic transmissions. Stuttgart's OEM engineering centers specify these for torque-dense e-axle reduction stages where surface finish tolerances below 0.4 micrometers Ra satisfy NHTSA noise-emission protocols.
- Bevel Pinion:Conical tooth geometry transmits torque between intersecting shafts in differential assemblies.
- Worm Pinion:Screw-thread engagement delivers high reduction ratios in heavy-duty steering columns and winch mechanisms.
Helical pinion holds installed capacity. Bevel pinion is rotating up the share rankings.
Material:
Application severity dictates alloy selection, with contact stress cycles and thermal loading separating forged steel from lightweight alternatives.
- Steel:Case-hardened alloy compositions reaching 58-64 HRC surface hardness withstand 10^7 contact stress cycles in differential pinions. Baden-Württemberg forging clusters supply BMW and Mercedes-Benz programs with vacuum-degassed 8620H and 20MnCr5 grades certified to IATF 16949.
- Aluminum:Silicon-modified A356-T6 castings reduce rotating mass in steering pinions where inertia damping matters more than absolute strength. Chinese suppliers in Jiangsu province industrial parks dominate volume production for domestic EV steering rack programs.
- Plastic:Glass-reinforced polyamide serves non-structural auxiliary drives and HVAC blend-door actuators.
- Composite:Hybrid carbon-fiber webs bonded to steel cores pilot in e-axle reduction stages for 2026 platform launches.
Steel dominates revenue contribution. Composite is climbing the fastest among emerging material classes.
End User:
Customer type determines specification authority, with platform engineering teams displacing traditional component procurement relationships.
- OEMs:Volkswagen Group and Toyota Motor Corporation retain direct sourcing for steering pinions in rack-and-pinion architectures, specifying tooth-profile tolerances and acoustic validation protocols that tier suppliers must replicate.
- Aftermarket Providers:Distributors like Dorman Products and SKF Automotive serve collision repair and wear-item replacement, stocking pinion sets matched to VIN-specific axle ratios.
- Tier-1 Suppliers:ZF Friedrichshafen and GKN integrate pinion production into complete e-axle modules, controlling specification authority previously held by transmission specialists.
- Repair Shops:Independent service centers source remanufactured pinions through wholesale distributors, prioritizing interchangeability over OEM pedigree.
Tier-1 suppliers concentrate specification authority. Aftermarket providers are expanding fastest in aging-vehicle regions.
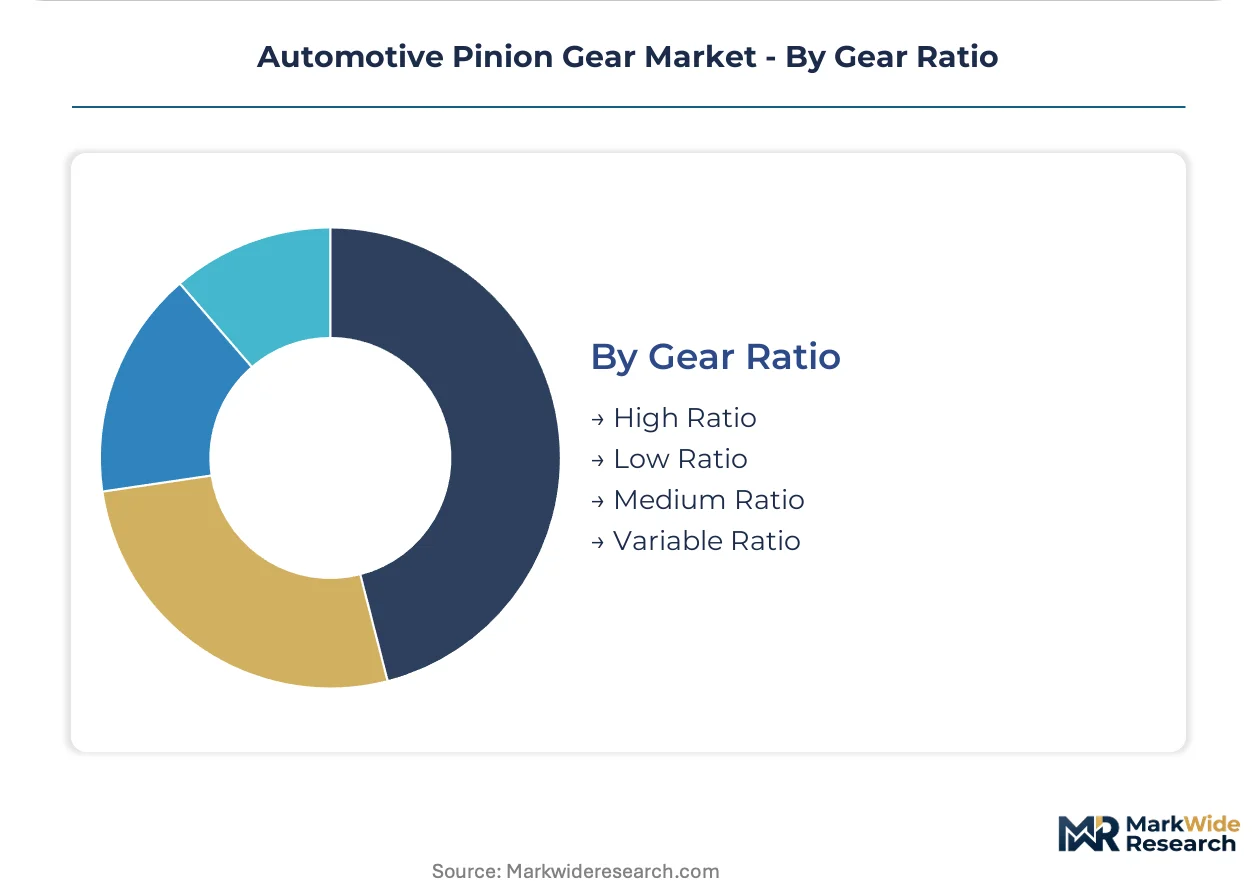
Gear Ratio:
Volume distribution follows powertrain architecture, with fixed-ratio designs yielding to variable geometries in multi-mode hybrid systems.
- High Ratio:Reduction exceeds 4:1 in steering pinions where torque multiplication amplifies driver input with minimal backlash. Bosch's electromechanical steering programs for European OEMs specify these ratios with position-sensor integration.
- Low Ratio:Direct-drive geometries below 2:1 suit high-speed transmission applications where efficiency losses from excessive reduction outweigh torque benefits.
- Medium Ratio:2.5-3.5:1 spans conventional differential pinions in rear-wheel-drive passenger vehicles.
- Variable Ratio:Continuously adjustable tooth engagement enables speed-sensitive steering feel and multi-mode hybrid powertrains.
Medium ratio holds production volume leadership. Variable ratio is gaining share fastest in electrified platform architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German transmission engineering clusters and Chinese machining parks concentrate precision gear capacity, while regulatory divergence across EPA, EU Green Deal, and MIIT frameworks fragments compliance pathways for multinational suppliers.
Germany
Baden-Württemberg's supplier density drives helical pinion demand for torque-dense e-axle applications. EU Green Deal embedded carbon tracking mandates smelting-source documentation for alloy steel inputs. Stuttgart's OEM engineering centers specify complete modular gear-set platforms that compress supplier qualification cycles.
China
Jiangsu province industrial parks integrate forging-to-finishing capacity for export-oriented EV steering programs. MIIT dual carbon goals accelerate electric-arc furnace adoption for low-emission steel qualification. Shanghai-based tier-one suppliers pilot hybrid composite-steel pinion geometries for 2026 platform launches.
United States
EPA Corporate Average Fuel Economy thresholds push OEMs toward lower-friction tooth profiles with sub-0.4 micrometer Ra surface finishes. NHTSA Federal Motor Vehicle Safety Standards govern steering-system integrity protocols that shape pinion fatigue-test requirements. Michigan's automotive corridor anchors differential pinion sourcing for Detroit Three transmission programs.
Japan
METI industrial policy supports precision gear-grinding equipment domestication to reduce German and Japanese capital equipment dependency. JIS standards govern case-hardening depth specifications for high-volume EV production runs. Nagoya-area suppliers concentrate on electromechanical steering pinion architectures for hybrid platform integration.
India
PLI scheme incentives attract gear-machining investment for domestic EV component localization. BIS certification timelines extend heat-treatment furnace qualification cycles by 18-24 months. Pune's commercial vehicle hub sustains straight-cut pinion demand for cost-sensitive axle manufacturers prioritizing tool-life economy.
Automotive Pinion Gear Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure consolidating around e-axle module specification authority. Tier-one transmission and driveline integrators now control pinion geometry decisions previously held by discrete gear suppliers. Three archetypes dominate: diversified automotive conglomerates with captive gear production, specialized powertrain engineering houses, and regional forging-to-finishing machining specialists. Competitive moves concentrate on backward integration into powder-forging operations and modular platform scaling across torque ratings.
Among European-based diversified conglomerates, ZF Friedrichshafen AG and GKN PLC exemplify platform integrators that have absorbed specification authority through complete e-axle module offerings. Robert Bosch GmbH anchors the electromechanical steering tier, representing specialists that have maintained direct OEM relationships in rack-and-pinion architectures despite broader consolidation pressures. These three entities occupy positions that illustrate how competitive advantage now flows from system-level integration rather than discrete component excellence.
| Leading Market Players |
|---|
| GKN PLC |
| Robert Bosch GmbH |
| SHOWA Corporation |
| ZF Friedrichshafen AG |
| Dana Incorporated |
| Bharat Gears Ltd. |
| American Axle & Manufacturing Holdings Inc. |
| JTEKT Corporation |
| Eaton Corporation plc |
| Others |
Supply Flow & Price Mechanics
Single-source hobbing equipment dependency among German and Japanese capital equipment builders compresses pricing tier spreads while simultaneously dictating supply chain geography. This concentration forces tier-two gear producers to absorb alloy steel volatility or surrender margin, while OEM platform engineering teams exploit consolidated procurement leverage.
Pricing Analysis
NHTSA Federal Motor Vehicle Safety Standards dictate the pricing tier structure across steering pinion categories, separating premium IATF 16949-certified suppliers from standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with OEM direct sourcing commanding highest tier and aftermarket remanufacturers occupying lowest. Cost compression in economy tiers is intensifying because Indian and Chinese machining parks compete on tool-life efficiency rather than surface finish precision. Aftermarket providers exhibit highest price sensitivity, while OEM platform engineering teams prioritize acoustic validation over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Baden-Württemberg forging clusters, Jiangsu province industrial parks, and Nagoya-area precision machining networks. Raw material flows draw from vacuum-degassed alloy steel mills in Germany, electric-arc furnace sources qualifying under EU Green Deal carbon tracking, and silicon-modified aluminum casters in China. Single-source vulnerability concentrates in precision gear-grinding equipment, where German and Japanese builders control spindle technology. Distribution runs through tier-one integrators like ZF Friedrichshafen and GKN, which now specify complete e-axle modules rather than discrete pinion components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering consolidation has fragmented specification authority, creating white-space opportunities for specialized suppliers that can navigate modular gear-set requirements without tier-one integration.
For Market Incumbents: Build certification moats around IATF 16949 audit depth and in-house acoustic validation laboratories. Secure backward integration into powder-forging operations to control alloy-grade consistency against raw material volatility. Expand heat-treatment furnace capacity in Baden-Württemberg to capture EU Green Deal-compliant smelting-source documentation demand. For New Entrants and Emerging Players: Build out electromechanical steering pinion capabilities for EV rack-and-pinion architectures, where noise-optimized geometries remain undersupplied relative to transmission gear demand. Target Jiangsu province industrial parks for integrated forging-to-finishing capacity that serves export-oriented EV steering programs. Pursue OEM qualification through modular gear-set platforms that span multiple torque ratings without retooling investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized powertrain engineering houses with captive gear production. Long-term viability hinges on electromechanical steering and e-axle reduction gear exposure as battery-electric platforms eliminate traditional multi-speed transmissions. Monitor tier-one integrator procurement shifts toward complete module sourcing as the inflection signal for component supplier margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Forging | GKN PLC controls alloy-grade consistency across differential pinion lines through captive powder operations. |
| Modular Gear-Set Platform Development | ZF Friedrichshafen spans multiple torque ratings without supplier retooling through standardized architectures. |
| Electromechanical Steering Pinion Investment | Robert Bosch GmbH anchors rack-and-pinion positions for electric vehicle steering column transitions. |
| Hybrid Composite-Steel Pilot Production | Shanghai and Stuttgart tier-one suppliers bond carbon-fiber webs to steel cores for 2026 e-axle launches. |
| Electric-Arc Furnace Steel Qualification | European gear producers shift forging sources to meet EU Green Deal embedded carbon disclosure rules. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and heat-treatment furnace operators converged on the working assumptions. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and EU Green Deal compliance documentation. Bottom-up segment sizing triangulated against top-down powertrain production forecasts.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled include product type, material system, end-user category, and gear ratio specification. CAGRs derived from production volume trajectories weighted by content-per-vehicle assumptions for electric and hybrid architectures. Forecast inputs incorporated NHTSA noise-emission protocol evolution and EPA Corporate Average Fuel Economy threshold adjustments.
Sensitivities concentrate around battery-electric platform adoption rates, alloy steel smelting-source emission documentation costs, and precision gear-grinding equipment delivery timelines. Forecasts reflect assumptions about modular gear-set platform penetration and tier-one integrator procurement consolidation. Quarterly review of OEM e-axle module sourcing decisions and EU Green Deal audit enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Timing Gear Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Automotive Bellows Market