
 Large Volume Injector Market | 2026-2036
Large Volume Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Large Volume Injector Market Insights
Connected device architecture is fragmenting the traditional large volume injector landscape into modular, software-integrated platforms. Becton Dickinson and Company leverages its vertical manufacturing scale to dominate prefilled syringe-to-injector ecosystems. Medtronic anchors its position through deep R&D intensity in closed-loop delivery algorithms. Enable Injections specializes in fully disposable wearable designs that eliminate drug transfer steps.
Large volume injectors are electromechanical or spring-driven drug delivery systems engineered to administer viscous biologic formulations—typically 2–20 mL—subcutaneously over extended durations via prefilled, patient-worn devices. Spring-driven injectors retain cost leadership in emerging markets where reimbursement pressure constrains capital outlay. Electrically-driven injectors and connected devices capture the fastest expansion as programmable dose tracking and remote monitoring become standard requirements in oncology and autoimmune therapy protocols.
FDA premarket notification pathways and EMA MDR conformity assessments shape device design cycles and market access timelines for all commercial entrants. ISO 11608 needle-based injection system standards govern dose accuracy validation, while HIPAA and GDPR data frameworks constrain how connected injectors transmit patient adherence metrics to healthcare providers. Stakeholders must weigh regulatory compliance costs against the pricing power that certified connectivity features command in integrated care contracts.
Market Dynamics
Connected device mandates from FDA and EMA are compressing development timelines while forcing hardware-software integration investments that reshape competitive economics across the large volume injector value chain.
Growth Catalysts
- Homecare biologic delivery:Patient preference for subcutaneous self-administration outside clinical settings pulls device demand toward wearable platforms with simplified interfaces.
- EMA MDR conformity requirements:Stricter post-market surveillance obligations for connected injectors accelerate replacement cycles for legacy non-connected devices.
- Spring-driven cost engineering:Manufacturing advances in precision metal forming reduce per-unit costs for mechanical injectors serving price-sensitive reimbursement environments.
Market Restraints
- Polymer resin cost volatility:Device housings depend on medical-grade polycarbonate and cyclic olefin polymer supply chains exposed to petrochemical feedstock fluctuations.
- Single-source sensor concentration:Force-sensing resistors and MEMS pressure transducers for dose verification concentrate among East Asian component suppliers.
- Biologic viscosity ceiling:Current subcutaneous delivery mechanisms face physical limits around 50 cP formulations, constraining monoclonal antibody pipeline compatibility.
Strategic Opportunities
- India outpatient expansion:Government hospital modernization programs create procurement windows for cost-optimized large volume injectors in oncology and diabetes care.
- Closed-loop algorithm integration:Convergence of continuous glucose monitoring data streams with insulin delivery wearables enables adaptive dosing platforms.
- Direct-to-patient pharmacy channels:Specialty pharmacy networks bypass traditional hospital purchasing committees for chronic therapy device distribution.
Industry Challenges
- ISO 11608-1 validation timelines:Dose accuracy testing protocols for variable-volume wearable devices extend certification cycles by 8-14 months versus fixed-dose syringes.
- Legacy EHR integration friction:Connected injector data formats require custom API development for compatibility with entrenched hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Volume Injector Market |
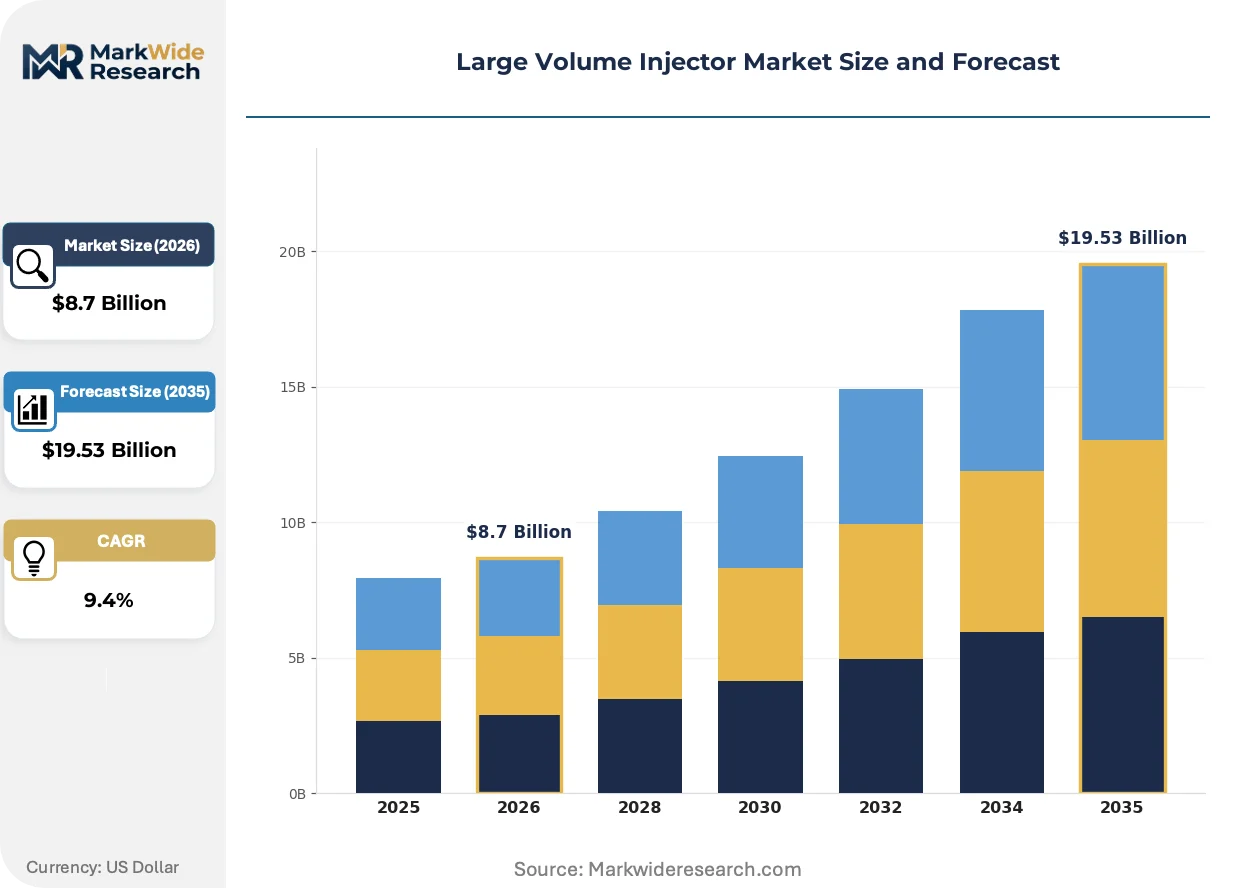
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring-Driven Injectors, Electrically-Driven Injectors, Pneumatically-Driven Injectors, Handheld Injectors End User: Hospitals, Clinics, Homecare Settings, Research Institutions Application: Immunization, Hormonal Treatments, Pain Management, Chemotherapy Technology: Smart Injectors, Manual Injectors, Connected Devices, Programmable Systems |
| Companies Covered | Becton Dickinson and Company, Medtronic, Insulet Corporation, West Pharmaceutical Services, Amgen Inc., Ypsomed Holding AG, Enable Injections, Johnson & Johnson Services, Inc., Tandem Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Volume Injector Market Trends and Innovations
Digital twin architectures and embedded sensor networks are transforming device validation from physical prototyping to simulated performance modeling, compressing iteration cycles and reducing capital intensity for new platform launches.
Cloud-based device simulation software is virtualizing the traditional mold-and-test development pathway for wearable injector mechanics. Medtech engineering teams in Germany and the United States now validate spring-force profiles and plunger kinematics through finite element modeling before cutting steel. This shift collapses prototype iteration timelines from months to weeks while reducing scrap rates for complex multi-component housings.
EMA's Medical Device Regulation Article 10 post-market clinical follow-up requirements are mandating real-world evidence collection from connected injectors in European markets. Manufacturers must embed cellular or Wi-Fi transmission modules to capture adherence and adverse event data across patient populations. This regulatory architecture favors platforms with pre-integrated telemetry over retrofitted connectivity solutions.
Hospital procurement committees in Japan and the United States are unbundling device acquisition from drug supply contracts that historically locked injectors to specific biologic portfolios. Buyers now evaluate hardware on standalone total cost-of-ownership metrics including training burden and disposal logistics. This pattern elevates modular, multi-drug-compatible platforms over legacy single-product designs in competitive tenders.
Large Volume Injector Market Segmentation
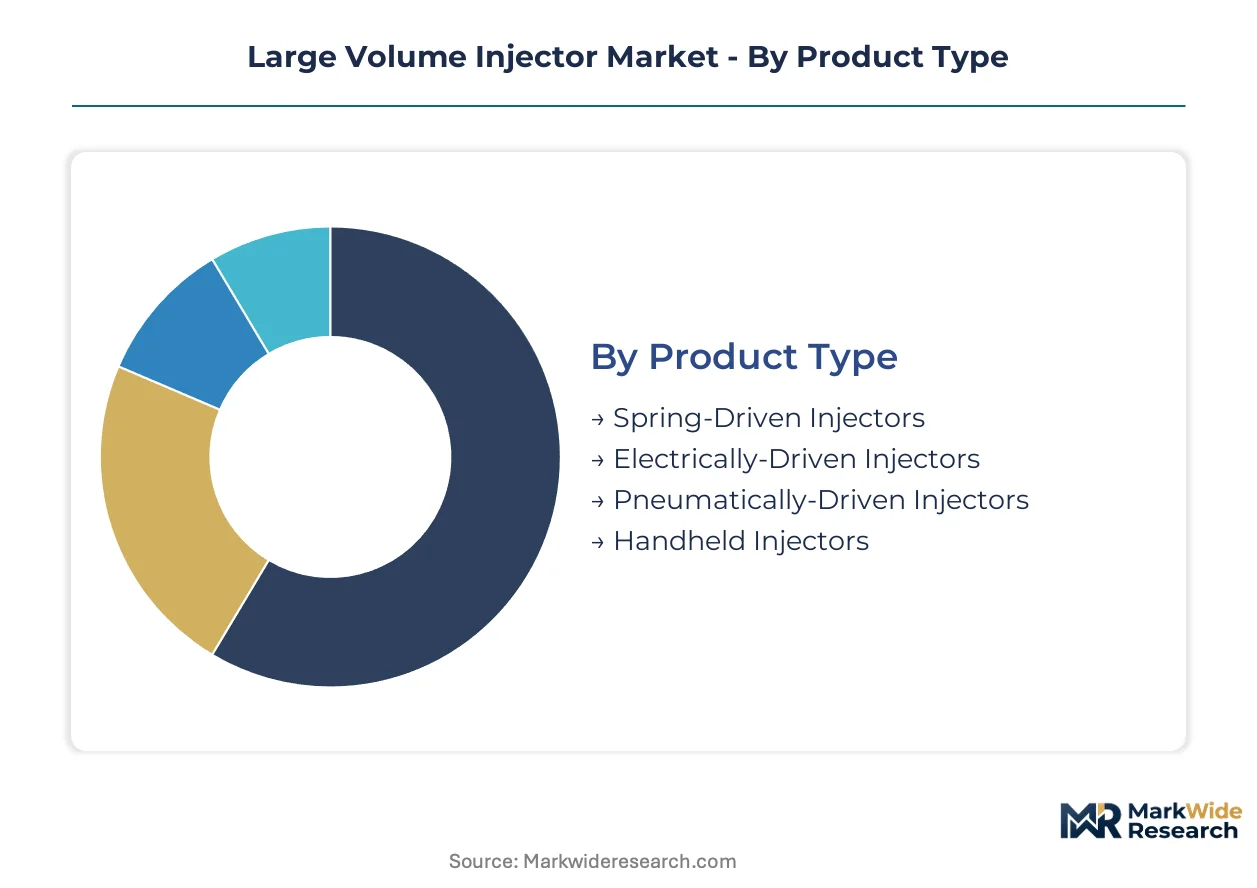
Large volume injector segmentation reveals how device architecture, care setting, therapeutic application, and digital capability create distinct commercial battlegrounds. Each dimension carries unique regulatory, reimbursement, and technical requirements that shape vendor positioning and procurement decisions.
Product Type:
Mature mechanical platforms coexist alongside emerging electromechanical systems, with cost sensitivity and connectivity requirements determining adoption patterns across care environments.
- Spring-Driven Injectors:Coiled metal spring mechanisms deliver stored mechanical energy to drive plunger advancement through viscous drug formulations. These devices dominate procurement tenders in India and Brazil where hospital budgets constrain capital expenditure, with single-use disposability eliminating sterilization infrastructure requirements.
- Electrically-Driven Injectors:Stepper motor and lead-screw assemblies enable programmable flow-rate modulation and dose completion feedback. Demand concentrates in German and Japanese oncology centers where EMA MDR and PMDA connected-device mandates require electronic dose verification for biologic therapies.
- Pneumatically-Driven Injectors:Compressed gas cartridges power drug delivery in specialized research and veterinary applications requiring rapid bolus administration.
- Handheld Injectors:Manual trigger-actuated devices serve emergency medicine and military field deployment scenarios where power independence outweighs precision dosing requirements.
Spring-driven platforms handle the majority of throughput across price-sensitive markets; electrically-driven systems are climbing the fastest on share as connectivity mandates expand.
End User:
Care setting migration from institutional to ambulatory environments is redistributing device requirements toward patient-operated interfaces and remote monitoring compatibility.
- Hospitals:Acute care facilities administer high-volume biologics through tethered infusion pumps and supervised injection protocols. German university hospitals and US academic medical centers drive demand for EHR-integrated systems with barcode medication administration verification.
- Homecare Settings:Patients self-administer chronic therapies through wearable platforms with simplified one-button activation. Japanese aging demographics and US specialty pharmacy expansion accelerate procurement of disposable wearables with telemedicine connectivity.
- Clinics:Outpatient infusion centers balance throughput efficiency against capital equipment costs in community oncology networks.
- Research Institutions:Clinical trial sponsors require programmable devices with precise dosing flexibility for investigational biologics.
Hospitals retain the largest installed base; homecare settings are expanding most quickly as biologic patent expirations enable biosimilar self-administration.
Application:
Therapeutic area requirements span acute intervention through chronic maintenance, with dosing frequency and viscosity profiles dictating device selection.
- Chemotherapy:Cytotoxic and supportive-care biologics demand precise volume delivery with spill-protection engineering. US oncology practices and European day-clinics specify closed-system transfer devices for hazardous drug handling compliance.
- Immunization:Mass vaccination campaigns and routine pediatric schedules favor prefilled autodisabling syringes for cold-chain-stable formulations.
- Hormonal Treatments:Fertility protocols and endocrine replacement therapies require patient-adjustable dosing with injection-depth control.
- Pain Management:Post-operative and chronic pain protocols utilize patient-controlled analgesia pumps with lockout intervals for safety.
Chemotherapy applications command premium pricing through safety-engineered requirements; immunization represents the highest-volume deployment channel.
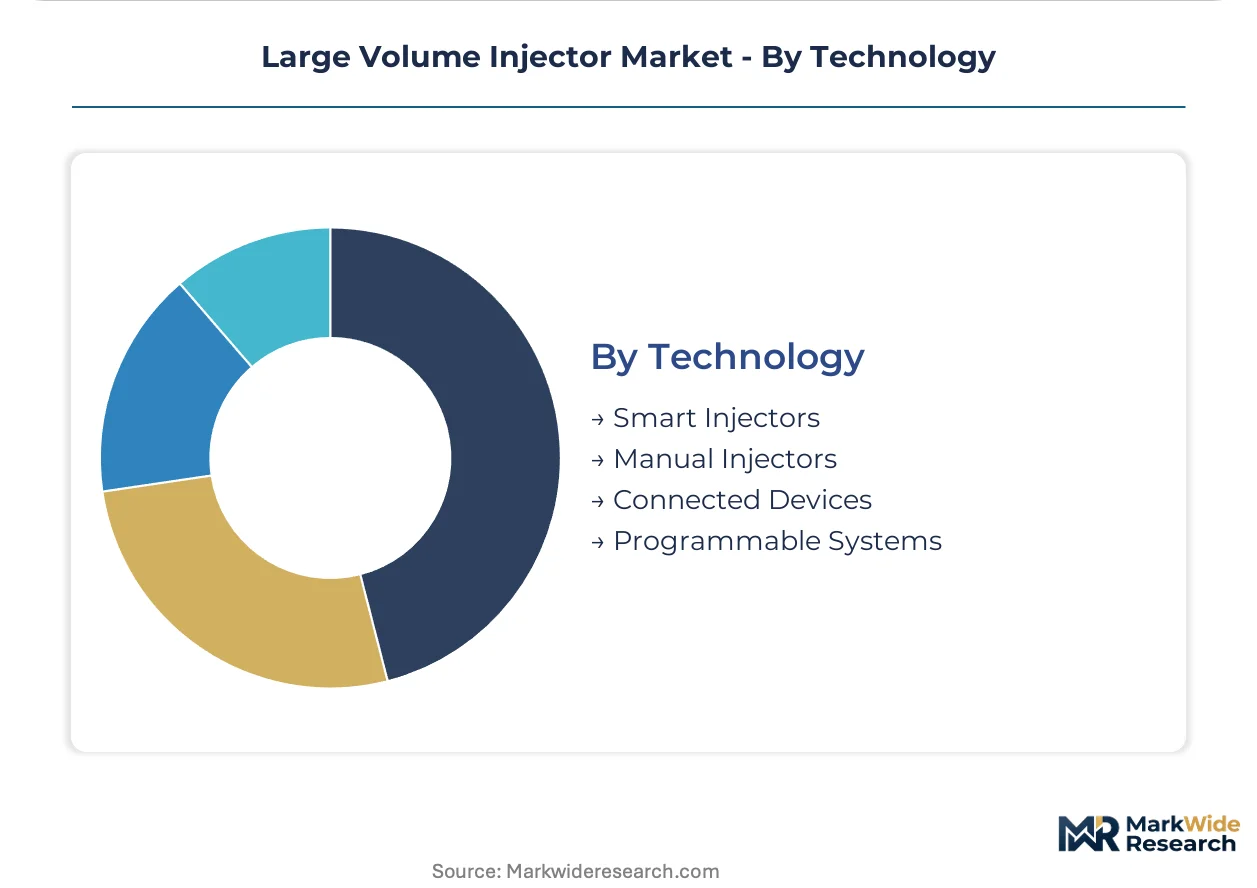
Technology:
Digital capability tiers separate commodity hardware from value-capturing platforms, with data transmission architecture becoming the primary competitive differentiator.
- Connected Devices:Cellular and Bluetooth-enabled injectors transmit adherence timestamps and adverse events to cloud dashboards. EMA Article 10 post-market surveillance requirements and FDA digital health guidance accelerate replacement of legacy non-connected inventory in European and US markets.
- Smart Injectors:Sensor-equipped platforms detect skin contact, needle insertion depth, and flow obstruction with real-time user feedback. Japanese device manufacturers integrate MEMS accelerometers for injection-angle guidance in insulin delivery.
- Programmable Systems:Clinician-configurable dose parameters serve complex titration protocols in academic medical center settings.
- Manual Injectors:Basic mechanical devices without electronic components serve cost-constrained markets and backup power-independent scenarios.
Connected devices capture the steepest expansion trajectory as regulatory surveillance mandates harden; manual injectors persist where electrification costs exceed reimbursement returns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for large volume injectors, while specialty pharmacy networks in these markets pull device demand toward homecare-compatible platforms.
United States
FDA digital health guidance and HIPAA data frameworks accelerate replacement of legacy injectors with connected platforms in oncology and autoimmune therapy protocols. The 21st Century Cures Act mandates interoperability standards that reshape how device data integrates with hospital EHR systems. Boston's medical device cluster anchors development of closed-loop delivery algorithms for insulin and biologic administration.
Germany
EMA Medical Device Regulation Article 10 post-market surveillance requirements compress certification timelines for wearable injector platforms. German university hospitals drive demand for EHR-integrated systems with barcode medication administration verification. The Baden-Württemberg precision engineering corridor supplies precision metal forming components for spring-driven mechanical injectors serving price-sensitive European tenders.
Japan
PMDA connected-device mandates and aging demographics accelerate procurement of disposable wearables with telemedicine connectivity for chronic therapy self-administration. METI industrial policy supports domestic manufacturing of MEMS sensors for injection-angle guidance in insulin delivery. The Kanto region around Tokyo concentrates headquarters of device manufacturers integrating accelerometer-based user feedback systems.
India
Government hospital modernization programs under the Ayushman Bharat scheme create procurement windows for cost-optimized large volume injectors in oncology and diabetes care. CDSCO medical device rules tighten quality standards for imported electromechanical systems while streamlining domestic manufacturing registrations. The Maharashtra pharmaceutical manufacturing belt near Mumbai hosts contract manufacturers producing spring-driven disposable injectors for emerging market export.
United Kingdom
NHS long-term plan targets for hospital-at-home services shift biologic delivery toward patient-operated wearable platforms with remote monitoring compatibility. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR standards while accelerating approval pathways for innovative connected devices. The Cambridge life sciences cluster advances digital twin architectures for virtual validation of injector mechanics before physical prototyping.
Large Volume Injector Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions shaped by vertical manufacturing scale versus focused R&D intensity. The vendor base organizes around three strategic archetypes: diversified medtech conglomerates with prefilled syringe-to-injector ecosystems, diabetes-focused pump manufacturers extending into large-volume biologic delivery, and pure-play wearable specialists engineering fully disposable designs. Dominant competitive moves include strategic partnerships between device manufacturers and biopharma sponsors for co-developed drug-device combinations, plus capacity expansion in precision metal forming for cost-engineered mechanical platforms.
Among diversified medtech conglomerates, Becton Dickinson and Company and Johnson & Johnson Services, Inc. occupy positions spanning hospital procurement channels and specialty pharmacy networks. Enable Injections exemplifies the pure-play wearable specialist archetype, while Medtronic represents the diabetes pump manufacturer extending platform expertise into broader biologic delivery applications.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Medtronic |
| Insulet Corporation |
| West Pharmaceutical Services |
| Amgen Inc. |
| Ypsomed Holding AG |
| Enable Injections |
| Johnson & Johnson Services, Inc. |
| Tandem Diabetes Care |
| Others |
Pricing and Supply Chain Analysis
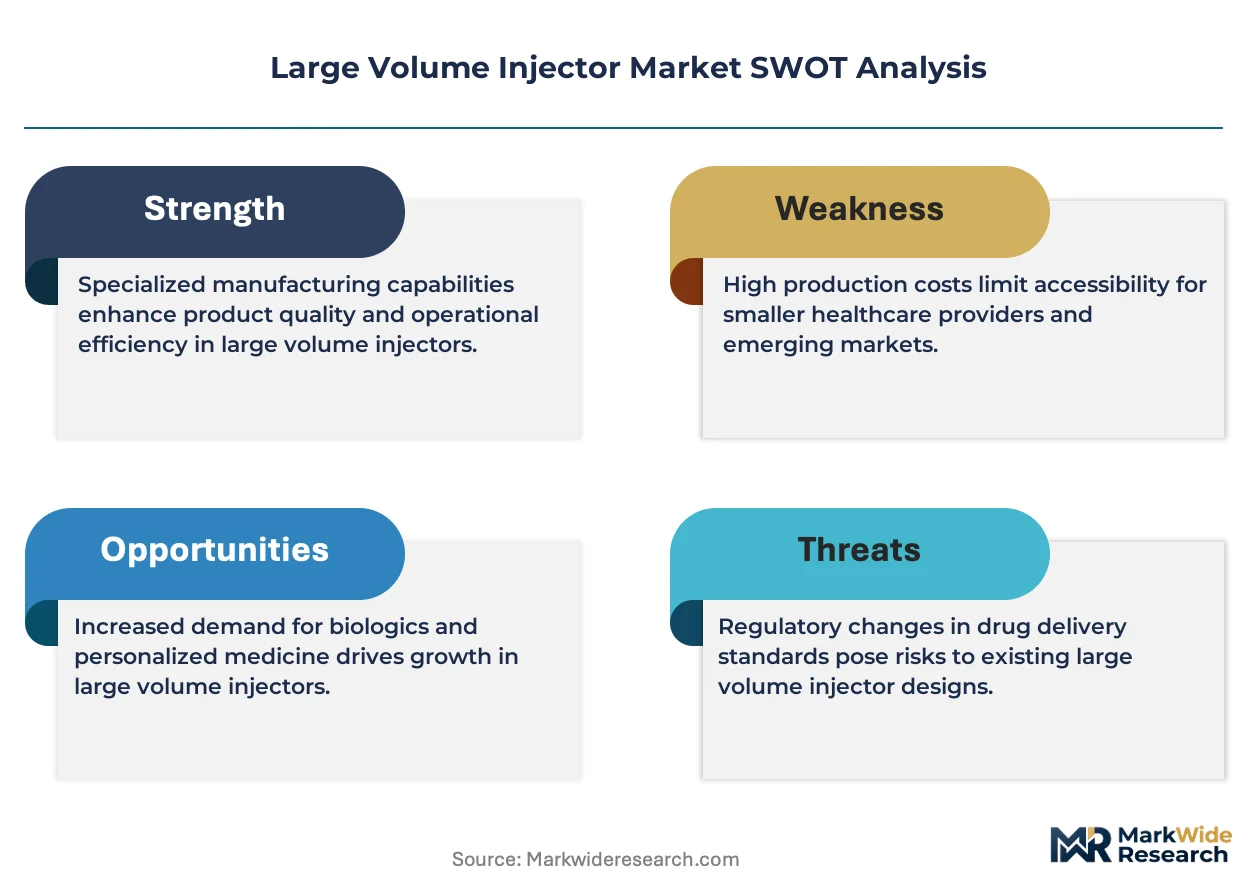
East Asian concentration in MEMS pressure transducers and force-sensing resistors anchors margin pools in the connected device tier, where FDA and EMA telemetry mandates concentrate pricing power among suppliers with pre-integrated sensor modules.
Pricing Analysis
Cost-plus contracts with medical-grade polycarbonate indexation dominate procurement for spring-driven mechanical injectors serving Indian and Brazilian hospital tenders. Pricing stratifies across premium, standard, and economy tiers based on connectivity certification grade and EMA MDR conformity level. Pricing pressure stems from polymer resin feedstock volatility and reimbursement compression in outpatient oncology settings. Price sensitivity concentrates among government procurement committees in emerging markets, while US specialty pharmacy networks prioritize total cost-of-ownership over unit price.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended terms have become standard for East Asian sensor vendors serving German and Japanese device manufacturers. Precision metal forming for spring mechanisms draws from Baden-Württemberg and the US Midwest, while medical-grade polymer compounding rests on German and Japanese chemical suppliers. Single-source vulnerability in MEMS fabrication creates exposure to regional logistics chokepoints. Distribution runs through hospital GPO contracts in the United States and direct specialty pharmacy channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The large volume injector market sits at a platform-economics inflection where FDA interoperability mandates and EMA post-market surveillance requirements are collapsing standalone hardware margins into software-integrated ecosystem value.
For Market Incumbents: Entrench position through backward integration into precision metal forming for cost-engineered spring platforms and captive supply of medical-grade polymer compounding. Biopharma co-development partnerships for drug-device combinations represent the critical defensive lever against pure-play wearable specialists. EMA MDR certification investment creates switching costs that protect installed base in European oncology centers. For New Entrants and Emerging Players: India's outpatient oncology expansion under Ayushman Bharat offers the most penetrable geographic entry point for cost-optimized mechanical injectors. Closed-loop algorithm development for insulin-biologic convergence represents the highest-value white-space target. Direct-to-patient pharmacy channel partnerships bypass entrenched hospital procurement gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play wearable specialists with FDA breakthrough device designation and embedded telemetry architectures. Long-term viability in this market hinges on software companion development capability and EHR integration depth. Watch for FDA digital health guidance expansion as the inflection signal for connected platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review timelines compress competitive entry windows for connected injectors in oncology protocols. |
| EMA MDR Conformity Assessment | Post-market surveillance mandates force hardware-software integration investments that reshape vendor economics. |
| Biopharma Co-Development Partnership | Drug-device combination locks secure procurement preference in integrated care contracts. |
| Precision Metal Forming Capacity Expansion | Baden-Württemberg engineering corridor supplies cost-engineered spring components for price-sensitive tenders. |
| Specialty Pharmacy Distribution Agreement | Direct-to-patient channels bypass hospital purchasing committees for chronic therapy device placement. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads anchored the qualitative base. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up device shipment modeling and top-down biologic therapy volume analysis provided triangulation across the analysis window.
Scenario-bracketing around regulatory implementation timing and reimbursement policy shifts framed the analytical approach. Segmentation dimensions modeled include product architecture, care setting migration, therapeutic application, and digital capability tier. CAGRs were derived from installed base replacement cycles and connected device penetration curves. Forecast inputs incorporated EMA Article 10 surveillance requirements and FDA digital health guidance evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diabetes pump manufacturers into large-volume biologic delivery would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Automotive Adaptive Engine Mounts Market