
 Passenger Vehicle Market | 2026-2036
Passenger Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Vehicle Market Outlook
Fleet operators and ride-hailing services is restructuring procurement priorities toward electrified and hybrid powertrains. Toyota Motor Corporation leverages its hybrid technology leadership across multiple continents. Volkswagen Group anchors its position through dedicated battery-electric platforms and scale manufacturing. Tesla dominates direct-to-consumer distribution and over-the-air software monetization.
A passenger vehicle is a motorized road vehicle designed primarily for transporting up to nine occupants, constructed on a unibody or body-on-frame architecture with independent suspension systems, internal combustion or electric propulsion, and crash structures engineered to meet specific occupant-protection standards. Its commercial purpose centers on personal mobility, fleet transportation, and status-oriented consumption across diverse demographic segments. The SUV and crossover size category commands the largest revenue pool as consumers prioritize cabin versatility and elevated driving positions across mainstream and premium market segments. Electric powertrains represent the fastest-expanding structural segment as battery costs decline and charging infrastructure densifies, while sedan vehicle types face contraction in mature markets where hatchbacks and coupes retain niche positioning.
The US EPA, the EU Green Deal framework with its F-Gas Regulation, and China's MIIT govern emissions benchmarks, refrigerant transitions, and new-energy vehicle production quotas that directly shape product development cycles and factory certification requirements. NHTSA crash-test protocols and EMA-equivalent standards in Europe further constrain design freedom while creating compliance barriers for new entrants. Stakeholders must monitor battery raw material supply agreements and regulatory credit trading mechanics as these mechanisms increasingly determine which powertrain configurations achieve production viability.
Market Dynamics
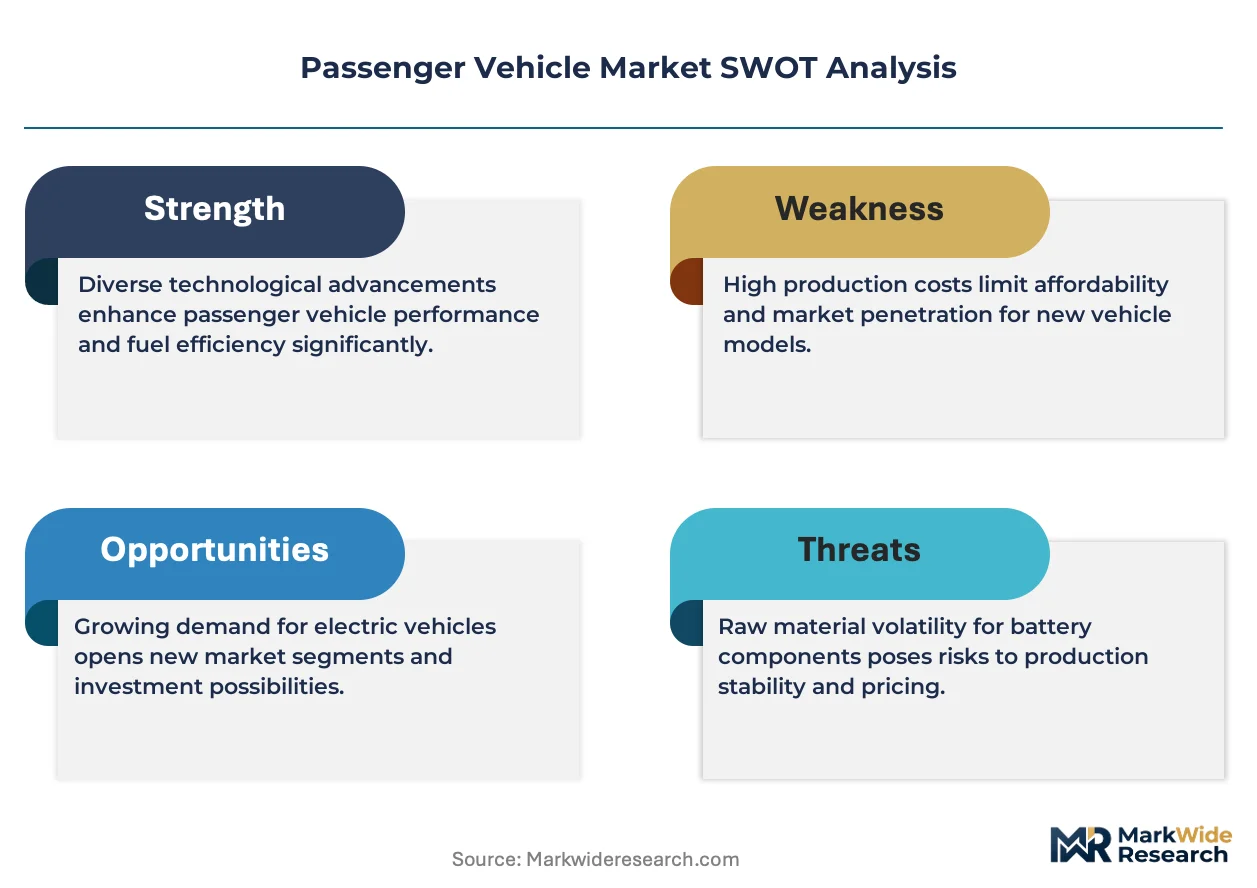
Battery platform standardization and solid-state cell development are redirecting engineering budgets across OEMs, compressing development timelines while forcing supplier consolidation around cell chemistry roadmaps.
Growth Catalysts
- Zero-emission zone mandates:Municipal zero-emission zones in Germany and China are compelling ride-hailing fleet operators to expand electrified model procurement.
- Battery cost decline:Falling lithium-ion cell prices are enabling mass-market EV parity with internal combustion powertrains in key volume segments.
- Charging infrastructure densification:Public and private capital deployment across highway corridors and urban centers is reducing range anxiety barriers.
Market Restraints
- Raw material supply concentration:Cobalt and lithium processing capacity concentrates in the Democratic Republic of Congo and Chile, creating geopolitical vulnerability.
- Technical limitation of solid-state cells:Manufacturing yield challenges and interface stability problems delay commercialization timelines.
- Regulatory friction from F-Gas Regulation:EU refrigerant transition requirements impose retooling costs on HVAC system suppliers.
Strategic Opportunities
- Underpenetrated fleet electrification:Corporate and government fleet operators in India present untapped demand for purpose-built electric commercial vehicles.
- Regulatory tailwind from IRA clean vehicle credits:US tax incentives for domestic battery and vehicle assembly are reshaping investment location decisions.
- Software-defined vehicle convergence:Over-the-air update capability combined with subscription revenue models creates new monetization pathways.
Industry Challenges
- Electrification talent scarcity:Battery engineering and power electronics expertise shortages constrain product development velocity at multiple OEMs.
- Certification timeline compression:UN ECE R100 and FMVSS 305 testing protocols for high-voltage systems extend homologation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Vehicle Market |
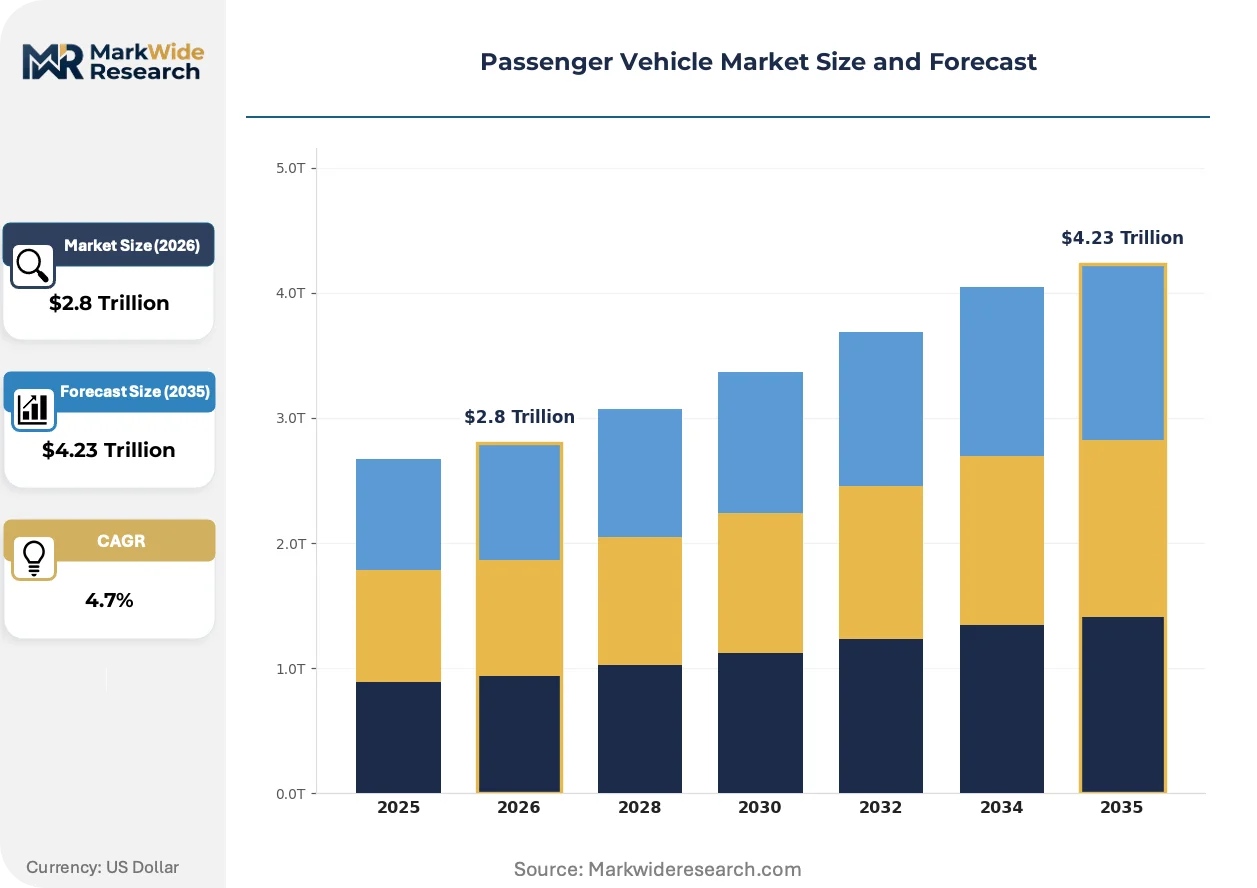
| Market Size in 2026 | $2.8 Trillion |
| Market Size in 2035 | $4.23 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Powertrain: Petrol, Diesel, Electric, Hybrid Size Category: Compact, Midsize, Full-Size, Luxury Market Segment: Mainstream, Premium, Budget, Performance |
| Companies Covered | Toyota Motor Corporation, Volkswagen Group, Hyundai Motor Company, General Motors, Ford Motor Company, Stellantis, Honda Motor Co., Ltd., Nissan Motor Co., Ltd., Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Vehicle Market Strategic Shifts
Powertrain architecture decisions now precede platform engineering, reversing decades of mechanical-first development. Software monetization and energy management systems are becoming primary differentiation vectors.
Cell-to-pack battery architecture eliminates module housings and reduces mass. Premium and mass-market OEMs are adopting this approach simultaneously. The technology is electrifying vehicle packaging efficiency and compressing floor pan height requirements.
China's MIIT new-energy vehicle production quotas mandate escalating zero-emission sales percentages. OEMs face credit deficit penalties or surplus trading mechanics. Foreign joint ventures and domestic brands alike are accelerating dedicated BEV platform launches to comply.
Fleet procurement departments now specify total cost of ownership over sticker price, including residual value guarantees and charging infrastructure bundling. Direct-to-fleet sales channels are displacing traditional dealer networks for volume contracts. This pattern is most visible in Germany and California where municipal fleet electrification targets are binding.
Passenger Vehicle Market Segmentation
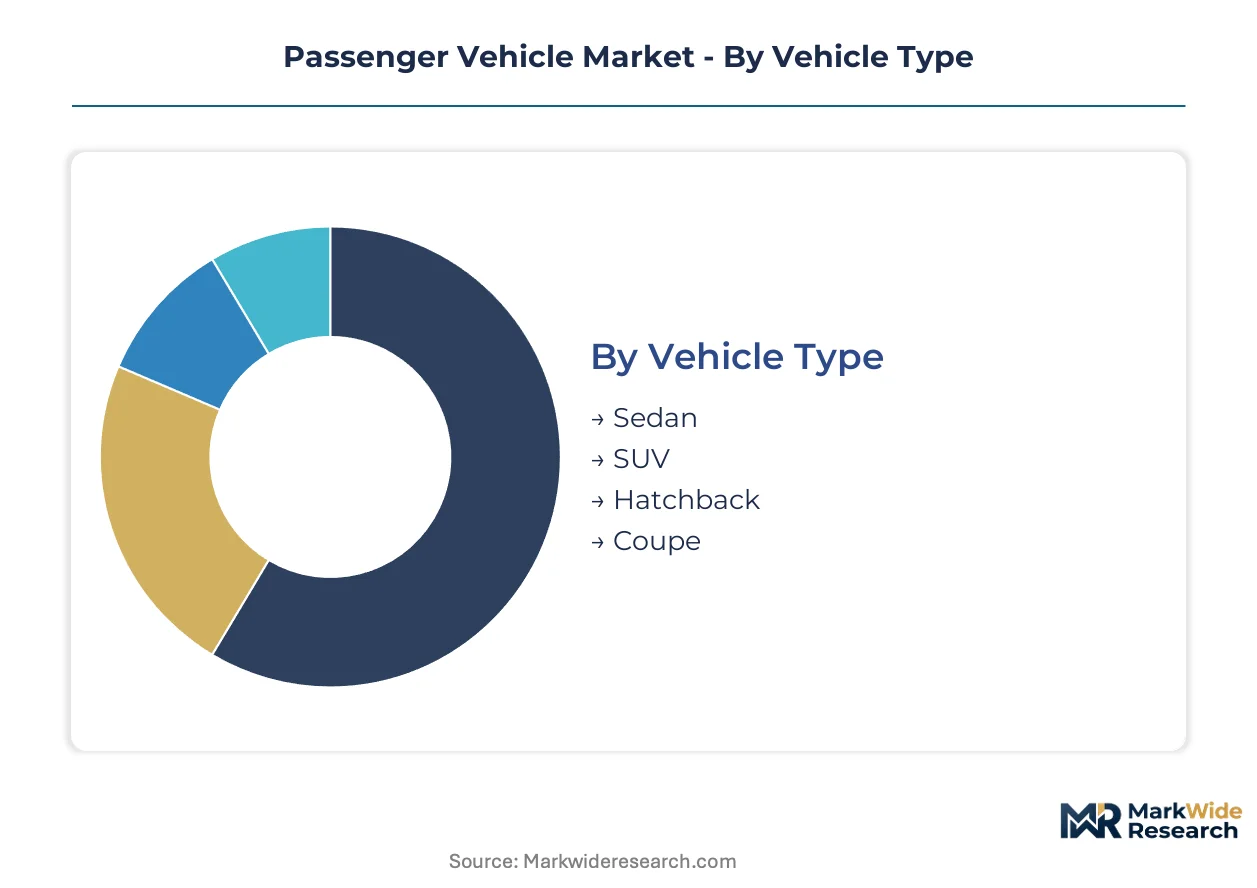
Segmentation in passenger vehicles determines factory tooling allocation, powertrain engineering priorities, and distribution channel design. Each dimension—vehicle architecture, propulsion system, dimensional class, and price positioning—creates distinct competitive arenas with separate margin profiles and regulatory exposure.
Vehicle Type:
Integration depth varies sharply: SUVs function as standalone platform decisions with dedicated unibody or body-on-frame architectures, while coupes embed as derivatives sharing underpinnings with sedans or hatchbacks.
- SUV:Elevated seating position and expanded cargo volume define the unibody architecture. Demand clusters in China's Yangtze River Delta manufacturing corridor where domestic brands and joint ventures compete on electrified platform variants. Municipal fleet procurement in Germany's zero-emission zones accelerates electrified SUV adoption.
- Sedan:Three-box profile with fixed roofline and separate trunk compartment. Volume concentrates in corporate fleet channels across India and Southeast Asia where total cost of ownership calculations dominate procurement. The segment faces structural contraction in mature Western markets as consumers migrate to crossovers.
- Hatchback:Two-box design with integrated cargo access via rear liftgate. European urban centers and Japanese kei-car regulations sustain demand for subcompact variants with tight turning radii.
- Coupe:Two-door fixed-roof body style typically riding on shortened sedan platforms. Niche positioning in premium segments emphasizes styling differentiation over utility.
Volume placements concentrate in SUV; the faster expansion belongs to hatchback electrification in dense Asian urban cores.
Powertrain:
Cost tier stratification separates mass-market internal combustion from emerging electric parity, with hybrid systems bridging the price gap during transition.
- Electric:Battery-electric architecture with motor-driven axles and high-voltage pack integration. China's MIIT production quotas and US IRA clean vehicle credits reshape investment location decisions for cell and assembly capacity. Solid-state cell development delays are compressing engineering timelines around lithium-ion platform standardization.
- Hybrid:Combined internal combustion and electric motor propulsion with regenerative braking. Toyota's multi-continent hybrid technology leadership demonstrates the segment's margin sustainability during electrification transition.
- Petrol:Spark-ignition internal combustion with port or direct fuel injection. Retains volume dominance in emerging markets with limited charging infrastructure and lower fuel taxation.
- Diesel:Compression-ignition engines with higher thermal efficiency for highway cruising. EU Green Deal emissions benchmarks and municipal access restrictions accelerate decline in European passenger applications.
Petrol retains the largest installed base; electric powertrains are climbing the fastest as battery costs approach mass-market parity thresholds.
Size Category:
Application context drives dimensional segmentation: compact vehicles serve urban congestion constraints while full-size architectures prioritize highway comfort and fleet executive transport.
- Compact:Sub-4.5 meter length with transverse engine packaging and space-efficient suspension. European city centers and Japanese regulatory dimensions sustain demand for parking-optimized footprints.
- Midsize:4.5-4.9 meter length accommodating five occupants with moderate cargo capacity. Fleet procurement departments in California specify this dimensional class for corporate pool vehicle programs.
- Full-Size:Exceeding 4.9 meters with longitudinal engine options and expanded rear legroom. North American highway cruising preferences and Chinese rear-seat executive transport sustain premium pricing.
- Luxury:Dimensional flexibility with priority on material specification, acoustic isolation, and advanced driver assistance integration. Customization programs and coachbuilt variants extend margins through bespoke commissioning.
Compact dimensions dominate unit volume; luxury size categories command the steepest expansion trajectory in electrified powertrain configurations.
Market Segment:
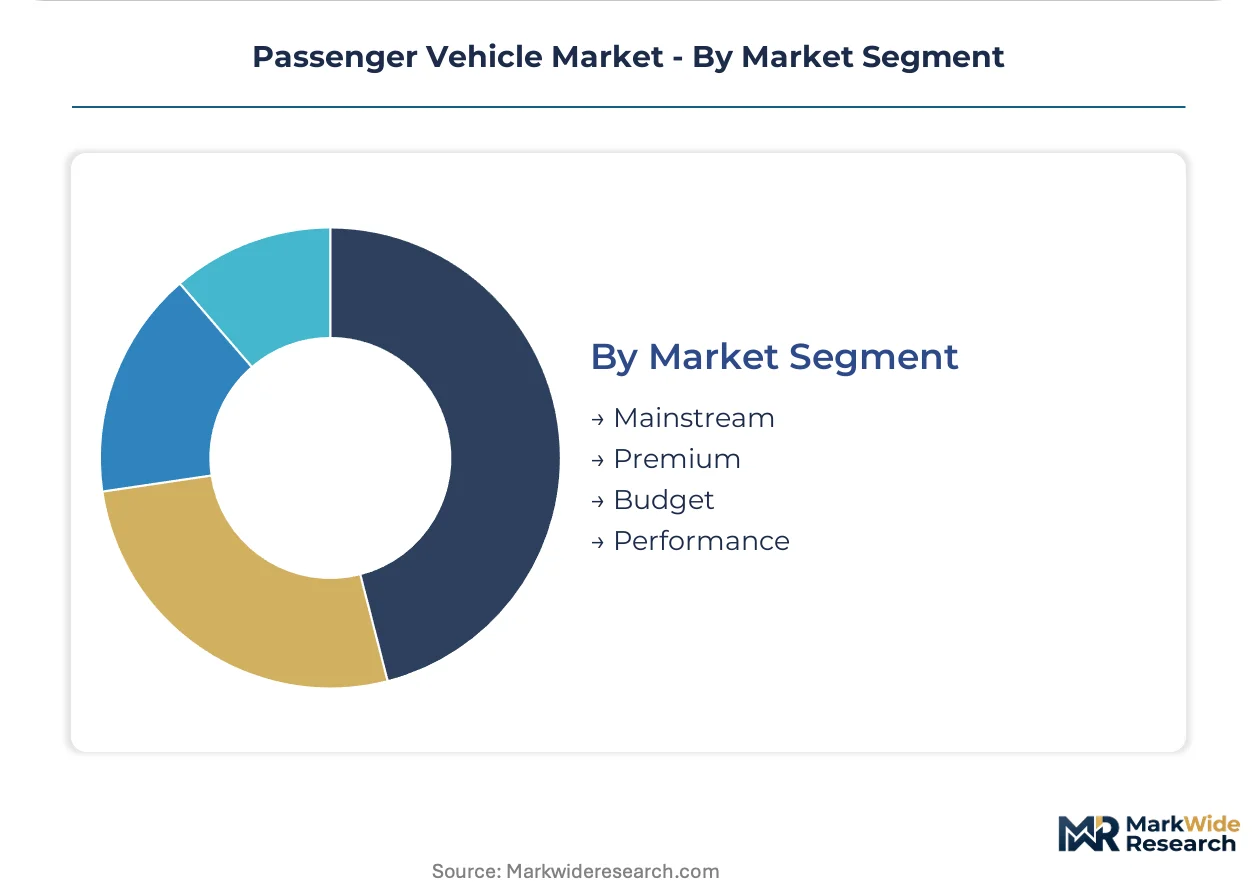
Customer type and margin structure separate budget positioning with stripped feature content from performance variants engineering chassis dynamics and powertrain calibration for enthusiast demand.
- Mainstream:Volume-focused specification balancing feature content against price accessibility. China's domestic brands and joint ventures compete aggressively on connected service integration and warranty terms.
- Premium:Elevated material quality, brand heritage positioning, and advanced technology availability. Direct-to-consumer distribution models and over-the-air monetization reshape revenue architecture in this tier.
- Budget:Essential transportation with minimized feature content and standardized powertrains. Emerging market growth in India and Southeast Asia sustains demand for entry-price positioning.
- Performance:Chassis and powertrain calibration prioritizing dynamic response over comfort optimization. Limited production volumes and motorsport heritage associations support pricing premiums.
Mainstream placement captures the volume concentration; premium segment electrification is gaining share fastest as battery costs enable technology transfer from luxury tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate battery and vehicle assembly capacity, drawing component suppliers into clustered logistics corridors that compress procurement lead times for electrified platforms.
China
MIIT production quotas mandate escalating zero-emission sales percentages, compelling joint ventures and domestic brands to accelerate dedicated BEV platform launches. The Yangtze River Delta manufacturing cluster hosts the densest concentration of cell-to-pack battery assembly operations. Municipal fleet procurement in Shanghai and Hangzhou specifies total cost of ownership calculations over sticker price.
Germany
Municipal zero-emission zones in Berlin, Hamburg, and Munich compel ride-hailing fleet operators to expand electrified model procurement. The EU Green Deal F-Gas Regulation imposes retooling costs on HVAC system suppliers while accelerating refrigerant transitions. Volkswagen Group anchors production in Lower Saxony and Bavaria through dedicated battery-electric platforms.
United States
IRA clean vehicle credits reshape investment location decisions for domestic battery and vehicle assembly capacity. NHTSA crash-test protocols and FMVSS 305 testing for high-voltage systems extend homologation cycles. California's corporate fleet pool vehicle programs specify midsize dimensional classes with charging infrastructure bundling.
Japan
METI industrial policy sustains hybrid technology leadership across multiple continents through multi-generational powertrain development. JIS standards govern component interoperability while kei-car regulations sustain subcompact hatchback demand in dense urban cores. Toyota Motor Corporation leverages this regulatory framework across Kanto and Chubu manufacturing regions.
India
PLI scheme incentives for advanced chemistry cell manufacturing attract battery supplier investments into Gujarat and Tamil Nadu. Corporate and government fleet operators present untapped demand for purpose-built electric commercial vehicles. BIS certification requirements for high-voltage systems create compliance barriers that favor established joint venture partnerships.
Passenger Vehicle Market Competitive Environment
Top-tier vendors anchor platform-scale electrification, while mid-tier specialists concentrate on regional powertrain variants and fleet customization. The market structure reflects tiered consolidation around three strategic archetypes: legacy OEMs with hybrid technology depth, dedicated electric-native manufacturers with software monetization models, and conglomerate groups with multi-brand platform sharing. Competitive moves center on battery supply agreements and over-the-air capability deployment.
Among established conglomerates, Toyota Motor Corporation and Volkswagen Group exemplify divergent electrification pathways—one leveraging multi-continent hybrid technology depth, the other anchoring position through dedicated battery-electric platforms and scale manufacturing. Tesla occupies a position representing direct-to-consumer distribution and software-defined vehicle convergence.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Volkswagen Group |
| Hyundai Motor Company |
| General Motors |
| Ford Motor Company |
| Stellantis |
| Honda Motor Co., Ltd. |
| Nissan Motor Co., Ltd. |
| Tesla |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement departments in Germany and California concentrate demand volume, forcing contract-based pricing with total cost of ownership guarantees rather than transactional sticker-price negotiations. This buyer concentration compresses margins for OEMs while elevating pricing power for battery suppliers with secured cathode material offtake.
Pricing Analysis
Short lead-time premiums apply to cell-to-pack battery architectures where OEMs pay 8-12% above contract rates for spot capacity releases. Three-tier pricing structure across premium, standard, and economy levels separates luxury EV configurations with solid-state pre-orders from mass-market lithium-ion platforms and entry fleet hatchbacks. Cost compression in mainstream segments is intensifying because China's domestic brands are absorbing warranty and charging infrastructure bundling into base pricing. Corporate fleet operators in India exhibit highest price sensitivity, while luxury buyers in China's Yangtze River Delta show least elasticity to powertrain premiums.
Supply Chain Analysis
US IRA clean vehicle credits and China's MIIT domestic-content mandates are reshaping sourcing, compelling OEMs to relocate cell assembly and cathode processing within tariff-advantaged zones. Battery supply concentrates in China, South Korea, and Japan, with lithium hydroxide processing anchored in Chile and Australia's spodumene mines. The chain rests on cobalt concentrate from the Democratic Republic of Congo, high-purity nickel from Indonesia, and separator films from Japanese chemical specialists. Single-source vulnerability in cathode active material creates exposure to export licensing shifts. Distribution runs through dedicated EV platform engineering centers in Lower Saxony, Bavaria, and Michigan before final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-scale electrification, with solid-state cell development delays and battery engineering talent scarcity forcing weaker OEMs into joint venture dependence or exit.
For Market Incumbents: Hedge technology risk by securing dual-source cathode supply agreements with both Chinese and South Korean suppliers before capacity allocation tightens. Accelerate backward integration into lithium hydroxide processing in Australia and Chile to insulate against export restriction scenarios. Toyota's multi-continent hybrid depth and Volkswagen's dedicated BEV platform scale represent divergent defensive templates. For New Entrants and Emerging Players: US IRA clean vehicle credits in Michigan and Tennessee open a window for fleet-focused electric commercial vehicle specialists to bypass retail channel establishment costs entirely. Target corporate pool vehicle programs in California and municipal procurement in Germany's zero-emission zones where total cost of ownership specifications displace brand loyalty. Direct-to-fleet sales channels with charging infrastructure bundling offer the most penetrable go-to-market angle against entrenched dealer networks. For Investors and Strategic Acquirers: The window for entry favors mid-tier battery engineering specialists with captive cell chemistry roadmaps and OEM validation contracts. Long-term viability hinges on 5-10 year platform standardization cycles where acquisition targets must demonstrate homologation completion for UN ECE R100 and FMVSS 305 protocols. Watch solid-state manufacturing yield breakthroughs at pilot-scale facilities as the inflection signal for chemistry roadmap obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode active material allocation from South Korean suppliers for dedicated BEV platforms. |
| Platform Standardization | Reduces engineering overhead across Volkswagen Group's MEB architecture variants in Lower Saxony. |
| Software-Defined Vehicle Investment | Enables over-the-air monetization through Tesla's direct-to-consumer distribution model. |
| Geographic Manufacturing Footprint | Positions IRA credit eligibility through domestic battery assembly in Michigan and Tennessee. |
| Charging Infrastructure Partnership | Bundles fleet procurement contracts with municipal electrification targets in Berlin and Shanghai. |
Study Parameters
Document review covered vehicle production databases, IHS Markit registration data, and SEC OEM filings, complemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations heads. Primary fieldwork validated battery cost trajectory assumptions and charging infrastructure deployment timelines. Secondary sources included MIIT production quota disclosures, EPA emissions certification records, and EU Green Deal implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Unit volume and value projections across the analysis window applied powertrain transition curves, platform sharing coefficients, and regional regulatory compliance costs. Segmentation dimensions encompassed vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from logistic diffusion modeling of electric powertrain penetration rates, with specific inputs for lithium-ion cell price decline elasticity and solid-state commercialization timeline risk.
The model assumes a particular technology adoption path; alternative pathways for solid-state cell manufacturing yield breakthroughs would alter the outlook for lithium-ion platform investment recovery. Forecasts reflect documented assumptions regarding MIIT quota enforcement, IRA credit continuity, and cobalt supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Electric Passenger Car MRO Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
South America Passenger Cars Market
Passenger Vehicles
Medium Cars Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Large Suvs Market
Passenger Vehicles
India Passenger Car Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
India Luxury Car Market