
 Russia Automotive Airfilters Market | 2026-2036
Russia Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Airfilters Market Analytics
ECE R24 type-approval certification is unwinding competitive access for non-compliant suppliers across the Russia automotive airfilters landscape. Mann+Hummel leverages its captive manufacturing footprint to dominate cabin and engine filter supply chains serving domestic assemblers. K&N Engineering differentiates through high-performance cotton gauze designs targeting enthusiast segments with extended service intervals. Purolator Filters LLC anchors its position via synthetic fiber technology leadership and established distribution through regional aftermarket distributors.
Automotive airfilters are engineered filtration media—typically pleated cellulose paper, synthetic nonwoven blends, or oiled cotton gauze—designed to remove particulate contaminants from intake air streams before combustion or cabin circulation, with efficiency ratings commonly tested to ISO 5011 protocols for gravimetric dust capacity and airflow restriction. Engine air intake systems demand higher dust-holding capacity and thermal stability, while cabin filtration emphasizes multi-layer synthetic fiber constructions for pollen, PM2.5, and activated carbon adsorption of volatile organic compounds. Panel filters retain the largest installed base across passenger vehicle parc volumes, though cartridge formats are gaining traction in newer European-platform models assembled domestically; cotton media occupies a premium niche among performance-oriented aftermarket consumers willing to accept higher initial cost for reusable lifecycles.
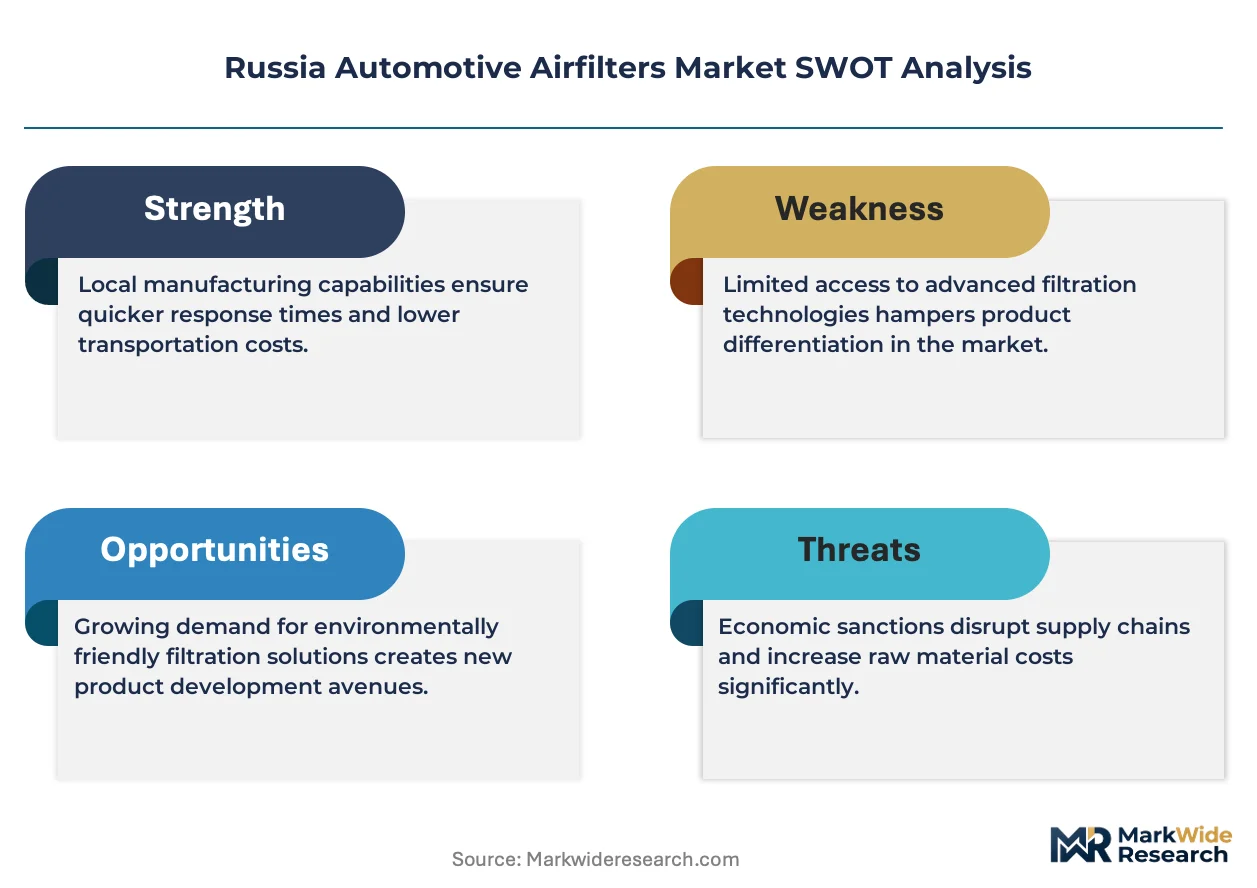
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) administers GOST R conformity assessment alongside EAEU harmonized technical regulations, while the Ministry of Industry and Trade oversees automotive component localization requirements that influence supplier qualification. These frameworks compel foreign filter manufacturers to establish domestic production or joint ventures to maintain OEM eligibility, particularly for vehicles participating in state procurement programs. Stakeholders must monitor evolving EAEU technical regulation amendments and localization thresholds to calibrate capital deployment between imported premium media and domestic assembly investments.
Market Dynamics
TR CU 018/2011 certification mandates are compressing supplier eligibility while Mann+Hummel's captive production footprint locks in OEM supply relationships across Moscow and St. Petersburg corridors.
Growth Catalysts
- Localization mandates:Russia's Ministry of Industry and Trade enforces component localization thresholds that compel foreign filter manufacturers to establish domestic joint ventures for state procurement eligibility.
- Light commercial vehicle fleet expansion:Central Federal District logistics operators are extending replacement schedules, driving aftermarket volume through service corridors radiating from Moscow.
- Synthetic fiber media:Multi-layer nonwoven constructions with PM2.5 and activated carbon adsorption layers are displacing basic cellulose in cabin filtration for premium vehicle segments.
Market Restraints
- ECE R24 type-approval barriers:Non-compliant suppliers face systematic exclusion from OEM supply chains as Rosstandart tightens conformity assessment protocols.
- Cellulose paper input volatility:Raw material costs for pleated paper media fluctuate with pulp supply chain disruptions affecting domestic filter converters.
- Supply concentration risk:Captive manufacturing by integrated system suppliers limits independent aftermarket access to OEM-grade filtration media.
Strategic Opportunities
- Reusable cotton gauze niche:Performance-oriented enthusiasts in St. Petersburg and Moscow accept premium pricing for oiled cotton designs with extended service intervals.
- Cartridge format migration:European-platform vehicles assembled domestically are adopting cartridge filters, creating upgrade pathways from panel filter installed base.
- EAEU harmonization tailwinds:Technical regulation amendments across the customs union may streamline cross-border certification for compliant suppliers.
Industry Challenges
- GOST R certification timelines:Rosstandart conformity assessment procedures create extended qualification periods for new filter media formulations.
- Legacy system integration:Aftermarket distributors face complexity bridging inventory systems between Soviet-era vehicle parc and modern European-platform service requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Airfilters Market |
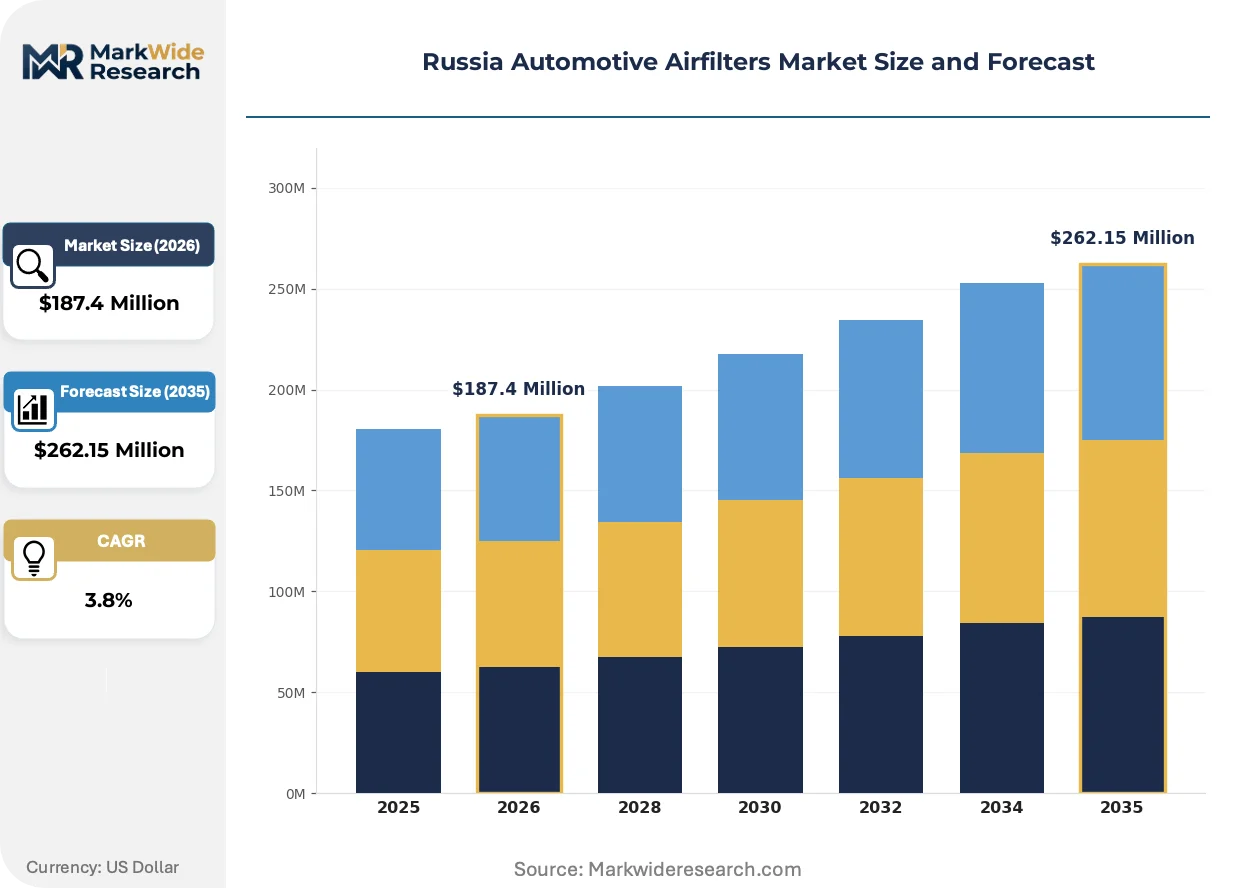
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Filters, Cabin Filters, Cartridge Filters, Engine Filters End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealerships Material: Paper, Synthetic Fiber, Foam, Cotton Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Recreational Vehicles |
| Companies Covered | Mann+Hummel, K&N Engineering, Purolator Filters LLC, A.L. Group, Allena Auto Industries Pvt. Ltd., JS Automobiles, AL Filters, Wsmridhi Manufacturing Co Pvt Ltd, Advanced Flow Engineering Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Airfilters Market Evolving Landscape
Synthetic fiber engineering and regulatory certification compression are restructuring competitive access while procurement patterns fragment across OEM captive supply and independent aftermarket channels.
Electrospun nanofiber surface layers are enhancing sub-micron particulate capture without airflow restriction penalties. Domestic assemblers in St. Petersburg's OEM zones are adopting these media for next-generation cabin filtration. The technology is miniaturizing multilayer constructions into thinner pleat packs that fit legacy housing dimensions.
Rosstandart's administration of EAEU harmonized technical regulations is tightening filter certification cycles under TR CU 018/2011 amendments. Foreign manufacturers must recalibrate testing protocols to maintain OEM eligibility for state procurement programs. Aftermarket suppliers serving Moscow's service corridors face documentation burdens that favor established domestic producers.
Fleet operators are compressing supplier relationships toward single-source agreements with integrated service providers. Independent distributors in the Central Federal District are losing share to authorized service networks with captive parts supply. This concentration is most visible among light commercial vehicle operators managing TCO across extended replacement intervals.
Russia Automotive Airfilters Market Segmentation
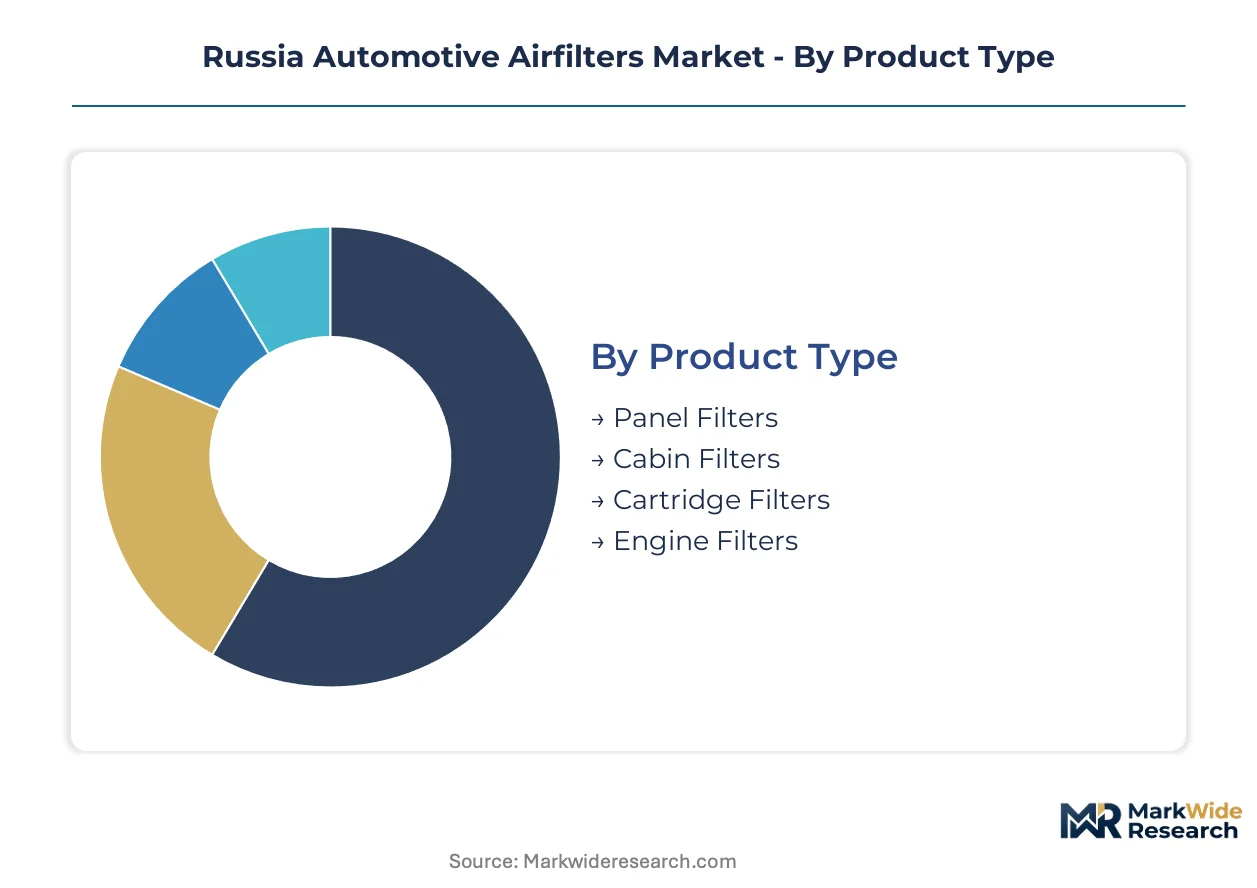
Filter format migration and material substitution are fragmenting procurement patterns across Russia's automotive supply base. Segment boundaries blur as synthetic media displaces cellulose in cabin applications and cartridge designs penetrate European-platform assemblies.
Product Type:
Cartridge formats face the most acute substitution pressure as legacy panel housings dominate Soviet-era vehicle parc maintenance while new European-platform models mandate cylindrical designs.
- Panel Filters:Pleated cellulose or synthetic media in rectangular housings retain the largest installed base across Russia's aging passenger vehicle fleet. Demand concentrates in Moscow's aftermarket service corridors where independent workshops service Lada and GAZ platforms with standardized replacement schedules.
- Cabin Filters:Multi-layer synthetic fiber constructions with PM2.5 and activated carbon adsorption layers are displacing basic cellulose in premium vehicle segments. St. Petersburg's OEM supply zones drive specification upgrades as domestic assemblers adopt ECE R24-compliant filtration for export-market vehicles.
- Cartridge Filters:Cylindrical media packs with axial airflow paths are gaining traction in newer European-platform models assembled domestically.
- Engine Filters:High-dust-capacity designs with thermal-stable media serve heavy-duty intake applications across commercial vehicle fleets.
Panel filters retain volume leadership; cabin filters hold the steepest expansion curve.
End User:
Procurement authority clusters differently across cost tiers, with state procurement programs favoring OEM-captive supply while independent aftermarket channels compete on price.
- OEMs:Domestic assemblers in St. Petersburg and Moscow regions specify ECE R24 type-approved filters under TR CU 018/2011 mandates. Localization thresholds enforced by the Ministry of Industry and Trade compel joint venture structures for state fleet eligibility.
- Aftermarket Providers:Independent distributors serving Central Federal District logistics operators face margin compression as fleet customers consolidate toward single-source agreements with integrated service networks.
- Vehicle Assemblers:Contract manufacturers for European brands prioritize synthetic fiber media with nanofiber surface layers for cabin filtration.
- Dealerships:Authorized service networks in Moscow's premium corridors capture replacement demand through captive parts supply tied to extended warranty programs.
OEMs command specification authority; aftermarket providers face the most aggressive consolidation pressure.
Material:
Margin structures diverge sharply between commodity cellulose converters and specialty media suppliers with electrospun nanofiber capabilities.
- Paper:Pleated cellulose media remains the cost baseline for economy-tier replacements across Soviet-era vehicle parc. Raw material volatility in pulp supply chains affects domestic converter margins.
- Synthetic Fiber:Multi-layer nonwoven constructions dominate cabin filtration for PM2.5 and VOC adsorption applications. St. Petersburg OEM zones specify these media for next-generation vehicle platforms.
- Foam:Open-cell polyurethane structures serve niche applications in pre-cleaner stages and recreational vehicle intake systems.
- Cotton:Oiled gauze designs target enthusiast segments in Moscow and St. Petersburg with reusable lifecycles and extended service intervals.
Paper retains volume leadership; synthetic fiber climbs the fastest on cabin filtration upgrades.
Application:
Vehicle class determines duty cycle severity and replacement frequency, with commercial operators optimizing total cost of ownership through extended service intervals.
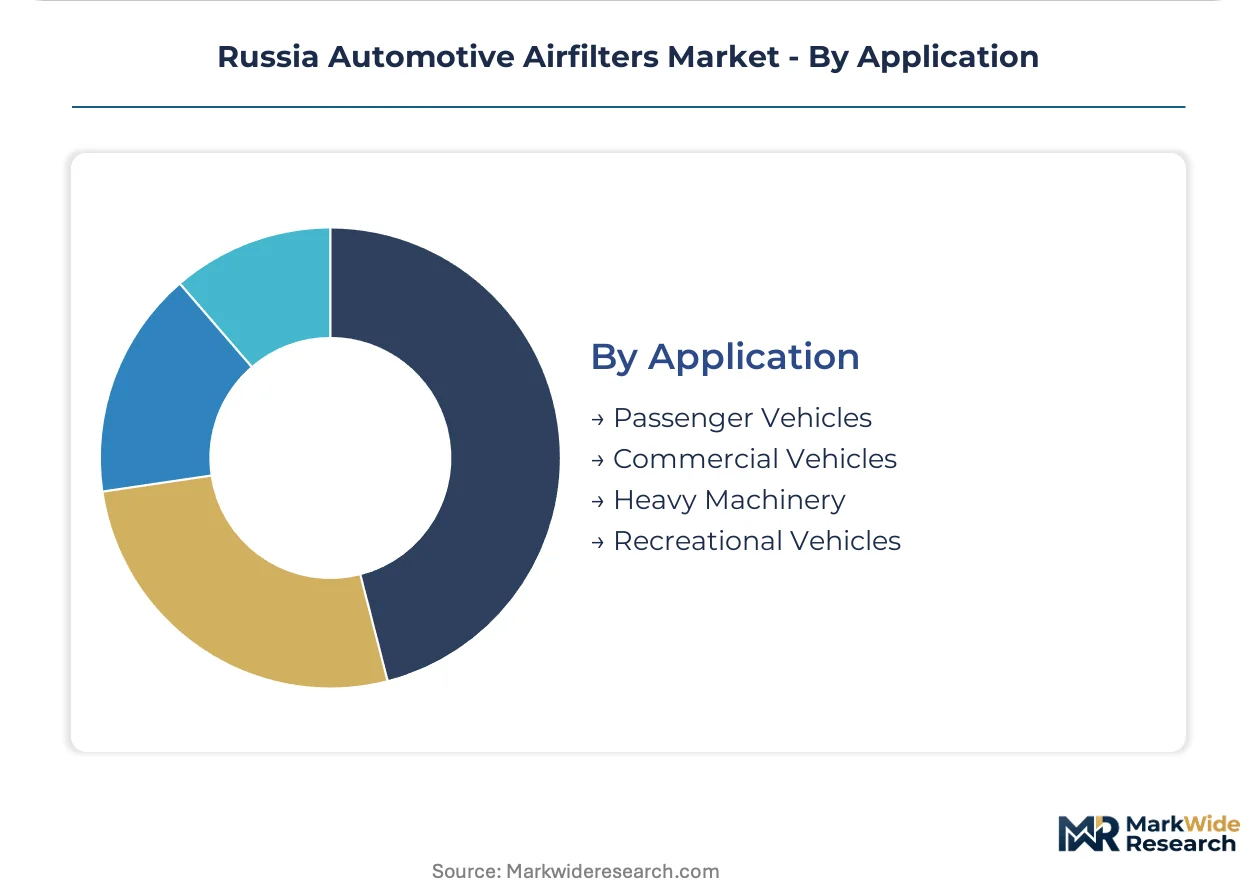
- Passenger Vehicles:Light-duty applications split between basic cellulose replacements for legacy domestic models and synthetic cabin media for European-platform imports. Moscow's dense vehicle parc sustains aftermarket volume through service corridor density.
- Commercial Vehicles:Light commercial fleets in the Central Federal District extend replacement schedules, driving demand for high-dust-capacity engine filters. Fleet operators compress supplier relationships toward integrated service providers with captive parts supply.
- Heavy Machinery:Severe-duty intake applications in construction and agricultural sectors require thermal-stable media with enhanced gravimetric dust capacity ratings.
- Recreational Vehicles:Niche demand for washable cotton gauze and foam pre-cleaners serves off-road enthusiast segments.
Passenger vehicles retain volume leadership; commercial vehicles gain share fastest on fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rosstandart's administration of EAEU harmonized technical regulations is redistributing manufacturing investments across Russia's federal districts. Filter producers must align domestic assembly footprints with TR CU 018/2011 certification corridors to retain state procurement eligibility.
Central Federal District
Moscow's aftermarket service corridors sustain the highest replacement volume density across Russia's automotive parc. The Ministry of Industry and Trade enforces localization thresholds that compel joint venture structures for state fleet contracts. Light commercial vehicle operators in the district compress supplier relationships toward integrated service networks with captive parts supply.
Northwestern Federal District
St. Petersburg's OEM supply zones drive specification upgrades as domestic assemblers adopt ECE R24-compliant filtration for export-market vehicles. Rosstandart's conformity assessment procedures create extended qualification periods for new filter media formulations entering this corridor. Contract manufacturers for European brands in the district prioritize synthetic fiber media with nanofiber surface layers.
Volga Federal District
Tolyatti's vehicle assembly cluster generates captive demand for engine and cabin filtration serving AvtoVAZ production lines. The district's converter base processes cellulose media for economy-tier replacements across Soviet-era vehicle parc maintenance. Pulp supply chain disruptions affecting domestic filter converters create margin volatility for paper-based producers.
Southern Federal District
Rostov-on-Don's logistics hub extends replacement schedules for commercial vehicle fleets operating across Black Sea trade corridors. Fleet operators in the district optimize total cost of ownership through high-dust-capacity engine filter specifications. Aftermarket distributors face complexity bridging inventory systems between legacy domestic platforms and modern European-platform service requirements.
Ural Federal District
Yekaterinburg's industrial machinery base sustains severe-duty intake applications in construction and agricultural sectors. The district's mining equipment operators demand thermal-stable media with enhanced gravimetric dust capacity ratings. Regional distributors serve niche demand for washable cotton gauze among off-road enthusiast segments.
Russia Automotive Airfilters Market Competitive Landscape
Listed filtration conglomerates compete with private specialists across certification access and manufacturing footprint dimensions. The supplier base concentrates around integrated system providers with captive OEM relationships and independent aftermarket converters serving price-sensitive replacement demand. Three archetypes dominate: multinational component suppliers with domestic assembly plants, regional media converters serving legacy vehicle parc, and performance-oriented specialists targeting enthusiast segments. Competitive dynamics center on ECE R24 type-approval acquisition and joint venture formation to satisfy localization mandates.
Within the multinational tier, Mann+Hummel represents the integrated system supplier archetype with established domestic manufacturing presence. K&N Engineering exemplifies the performance specialist positioning through its cotton gauze technology focus. Purolator Filters LLC anchors the synthetic fiber technology leadership segment among aftermarket distributors. These three entities collectively illustrate how certification compliance and material specialization stratify competitive access across Russia's bifurcated supply chains.
| Leading Market Players |
|---|
| Mann+Hummel |
| K&N Engineering |
| Purolator Filters LLC |
| A.L. Group |
| Allena Auto Industries Pvt. Ltd. |
| JS Automobiles |
| AL Filters |
| Wsmridhi Manufacturing Co Pvt Ltd |
| Advanced Flow Engineering Inc |
| Others |
Value Network & Pricing Analysis
TR CU 018/2011 certification gates both supply qualification and price differentiation simultaneously, compressing supplier eligibility while stratifying procurement tiers across Moscow's aftermarket corridors and St. Petersburg's OEM zones. Foreign manufacturers face joint venture mandates to access state fleet contracts, embedding compliance costs into pricing structures that separate ECE R24-approved suppliers from non-compliant converters serving economy segments.
Pricing Analysis
Certification level creates the primary spread between premium ECE R24-compliant filters and basic GOST R economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, with synthetic fiber nanofiber constructions commanding premiums over cellulose paper. Pricing pressure stems from pulp supply chain volatility affecting domestic converter margins. Fleet operators in the Central Federal District exhibit lowest price sensitivity due to TCO optimization, while independent workshops serving Soviet-era parc remain highly cost-conscious.
Supply Chain Analysis
Strategic stockpiling of cellulose pulp and synthetic fiber media dominates inventory strategy as Rosstandart certification timelines extend qualification periods. Manufacturing concentrates in Germany, China, and domestic Russian joint ventures serving OEM supply zones. Raw material dependencies span Nordic pulp suppliers, South Korean synthetic fiber producers, and German specialty chemical providers. Single-source vulnerability runs through integrated system suppliers like Mann+Hummel with captive OEM relationships. Distribution runs through regional aftermarket distributors in Moscow and authorized service networks with captive parts supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation toward single-source agreements shifts buyer power toward integrated service providers, fragmenting independent aftermarket channels across Russia's federal districts.
For Market Incumbents: Fortify ECE R24 certification portfolios to defend OEM eligibility as Rosstandart tightens conformity assessment protocols. Deepen backward integration into synthetic fiber media production to offset pulp supply volatility. Prioritize joint venture structures in St. Petersburg and Moscow regions to satisfy Ministry of Industry and Trade localization thresholds for state procurement access. For New Entrants and Emerging Players: Anchor in the reusable cotton gauze enthusiast segment where K&N Engineering's premium positioning leaves room for specialized competitors in Moscow and St. Petersburg corridors. Target cartridge format migration pathways as European-platform vehicles displace legacy panel filter installed base. Pursue direct-to-enthusiast digital channels bypassing consolidated distributor networks. For Investors and Strategic Acquirers: EAEU technical regulation amendments reshaping the acquisition landscape favor compliant suppliers with established domestic assembly footprints. Long-term viability centers on electrospun nanofiber capability and OEM-captive relationships rather than commodity cellulose conversion. Monitor Rosstandart certification queue lengths as inflection indicator for competitive access compression.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Satisfies Ministry of Industry and Trade localization mandates for state fleet eligibility. |
| Electrospun Nanofiber Investment | Captures cabin filtration upgrade demand from St. Petersburg OEM assemblers. |
| ECE R24 Certification Expansion | Locks in OEM supply relationships as Rosstandart tightens conformity protocols. |
| Cartridge Format Product Line | Aligns with European-platform vehicle assembly trends in domestic OEM zones. |
| Fleet Service Network Partnership | Secures volume offtake as Central Federal District operators consolidate suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, EAEU regulatory filings, and vehicle production databases. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads informed demand-side validation. Secondary sources span Rosstandart certification registries, Ministry of Industry and Trade localization reports, and IHS Markit vehicle registration data. Bottom-up filter volume estimates triangulate against top-down automotive parc modeling.
Segmentation dimensions modeled span filter format, material composition, end-user category, and application across vehicle classes over the projection horizon. CAGRs derive from replacement rate analysis tied to fleet expansion patterns and regulatory compliance cycles. Industry-specific inputs incorporate TR CU 018/2011 amendment trajectories and electrospun nanofiber adoption curves in cabin filtration specifications.
Underlying assumptions cover EAEU regulatory harmonization continuity and pulp supply chain stability, with deviation risk concentrated in Rosstandart certification timeline extensions and localization threshold adjustments. Revision becomes warranted when ECE R24 type-approval backlogs exceed historical clearance rates or joint venture formation pace diverges from Ministry of Industry and Trade enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Automotive Coolant Aftermarket Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Springs and Damper Market