
 Apheresis Market | 2026-2036
Apheresis Market Size, Share, and Industry Trends Forecast 2026-2036
Apheresis Market Intelligence
Therapeutic apheresis in autoimmune disorders is expanding faster than traditional transfusion medicine applications, reshaping how hospitals allocate capital equipment budgets. Fresenius SE & Co. KGaA leverages its dialysis infrastructure to cross-sell apheresis platforms into nephrology departments. Haemonetics Corporation anchors the North American blood collection segment with automated red cell exchange systems. Terumo BCT differentiates through integrated software that tracks patient treatment protocols across multiple sessions.
Apheresis denotes an extracorporeal blood processing technique that separates whole blood into components using centrifugal force or semipermeable membranes, typically operating at flow rates of 50-120 mL/min depending on vascular access and patient tolerance. The procedure enables selective removal, collection, or exchange of plasma, platelets, leukocytes, or erythrocytes for therapeutic or donor purposes. Plasma separation and membrane separation technologies command the largest installed base, while leukapheresis applications in oncology exhibit the steepest growth trajectory as cell therapy manufacturing scales. Photopheresis remains a niche margin pool concentrated in cutaneous T-cell lymphoma protocols at specialty clinics.
FDA device classification under 21 CFR 876.5880 governs therapeutic apheresis instruments and disposables, requiring premarket notification or approval based on intended use indications. EU MDR and ISO 13485 quality management standards shape design controls and post-market surveillance obligations for manufacturers selling into European markets. The EU F-Gas Regulation also constrains refrigerant choices in centrifugation equipment cooling systems. Stakeholders must monitor evolving reimbursement codes for outpatient therapeutic apheresis as health systems shift procedures away from inpatient settings.
Market Dynamics
Membrane separation technology is displacing centrifugation in outpatient therapeutic settings, compressing capital equipment cycles and forcing disposable kit manufacturers to redesign fluid pathways for lower flow rates.
Growth Catalysts
- EU MDR device classification:Tighter quality benchmarks for disposable kits are accelerating hospital consolidation around single-vendor platforms to simplify compliance audits.
- Leukapheresis in CAR-T manufacturing:Cell therapy contract development organizations are scaling collection capacity to feed autologous therapy pipelines.
- Japan's outpatient reimbursement framework:METI-aligned health ministry codes now cover photopheresis procedures outside inpatient wards, expanding addressable treatment volume.
Market Restraints
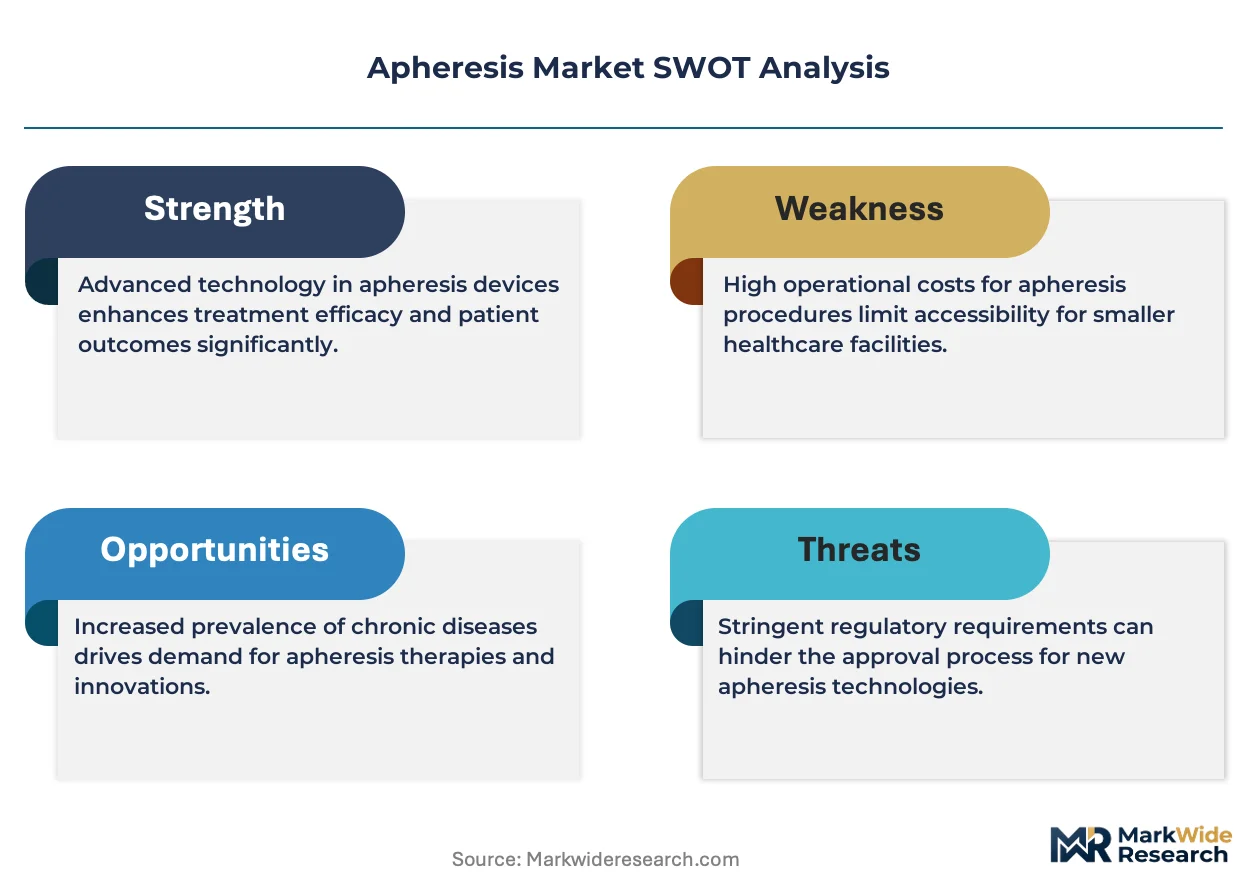
- Specialized polymer supply concentration:Medical-grade membrane substrates depend on German and Japanese chemical suppliers, exposing kit manufacturers to input bottlenecks.
- FDA 21 CFR 876.5880 clearance timelines:Premarket notification requirements for new therapeutic indications extend product launch windows by 18-24 months.
- Technical limitation in vascular access:Peripheral vein flow rate constraints cap procedure efficiency in patients with compromised vasculature.
Strategic Opportunities
- Home-based therapeutic apheresis:Portable membrane systems are opening chronic neurological indication markets previously confined to hospital settings.
- India's PLI scheme for medical devices:Domestic manufacturing incentives for critical care equipment are attracting component suppliers to establish local membrane production.
- Software-protocol convergence:Integration of patient treatment tracking with hospital information systems is creating platform stickiness and recurring revenue streams.
Industry Challenges
- Perfusionist and specialized nursing shortages:Therapeutic apheresis procedures require operators trained in extracorporeal circuit management, constraining procedure volume expansion.
- ISO 13485 certification complexity:Design control documentation for combination device-drug products is extending quality system implementation timelines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apheresis Market |
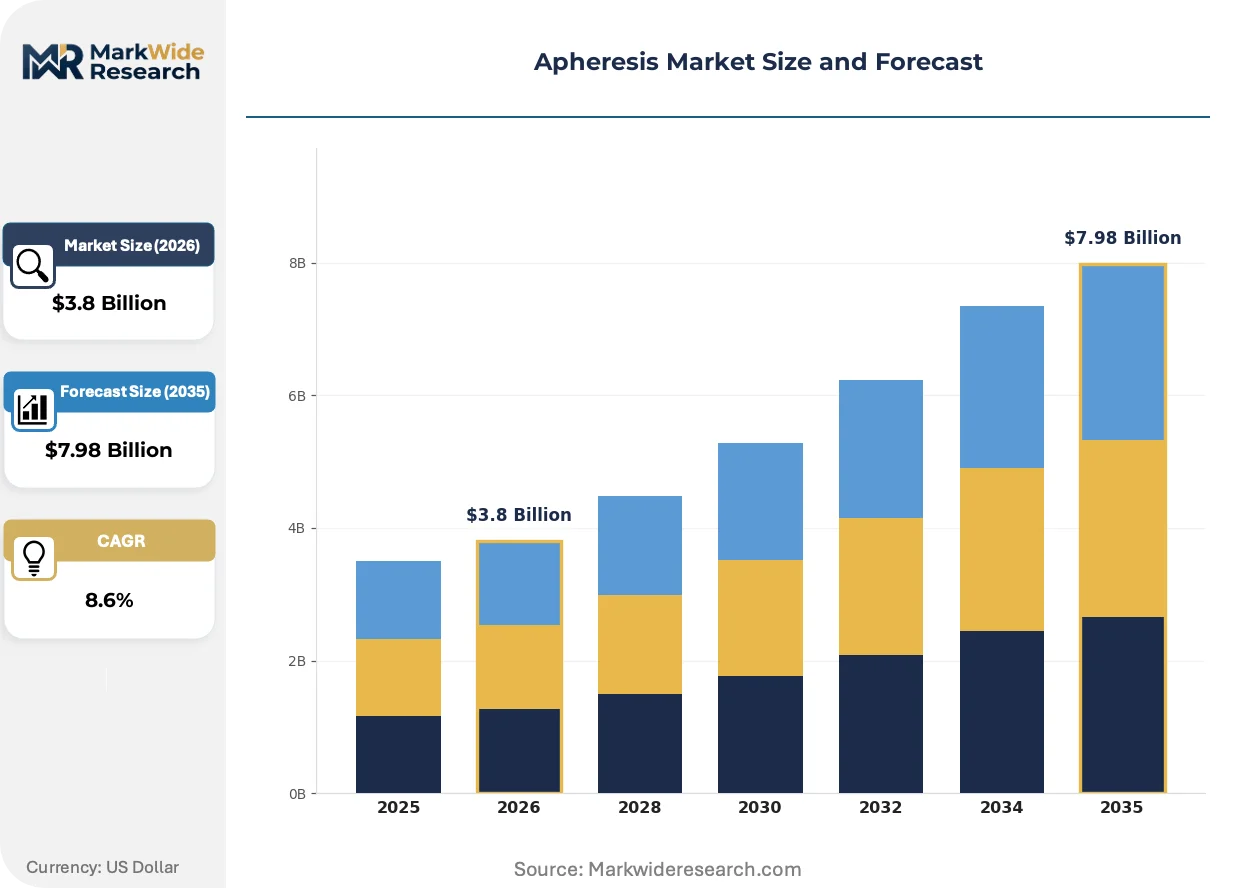
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Separation, Leukapheresis, Plateletpheresis, Red Cell Exchange, Photopheresis Application: Autoimmune Disorders, Hematology, Transfusion Medicine, Oncology, Infectious Diseases End User: Blood Banks, Therapeutic Centers, Research Institutes, Specialty Clinics, Academic Hospitals Technology: Centrifugation, Membrane Separation, Filtration, Adsorption, Continuous Flow |
| Companies Covered | Asahi Kasei Medical Co. Ltd., B. Braun Melsungen AG, Terumo BCT, Nikkiso Co. Ltd., Kaneka Corporation, Fresenius SE & Co. KGaA, Baxter International Inc., Miltenyi Biotec, Haemonetics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apheresis Market Strategic Shifts & Innovations
Automation, regulatory harmonization pressures, and site-of-care migration are compressing traditional boundaries between donor collection and therapeutic delivery platforms.
Continuous-flow membrane separation technology is automating plasma exchange procedures that previously required manual operator intervention for anticoagulant dosing and fluid balance monitoring. Academic medical centers in Germany and the United States are deploying these systems in satellite dialysis clinics to extend therapeutic apheresis access without perfusionist staffing. The technology is automating labor-intensive steps and enabling procedure volume growth without proportional headcount expansion.
EU F-Gas Regulation constraints on hydrofluorocarbon refrigerants are forcing centrifugation equipment manufacturers to redesign cooling systems using natural refrigerants or closed-loop architectures. This industrial consequence is compressing equipment refresh cycles as hospitals face retrofit-or-replace decisions for installed base units. Germany and France show the most visible response, with university hospitals accelerating procurement of compliant platforms ahead of 2030 phase-down deadlines.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, treating preventive maintenance and software updates as separately negotiable line items. This buying-pattern change is disrupting traditional vendor lock-in strategies and compressing service margin pools. The shift is most visible in United States health systems pursuing standardized fleet management across multiple hospital sites.
Apheresis Market Segmentation
Apheresis equipment purchasing cycles diverge sharply across clinical settings, with blood banks prioritizing throughput volume while therapeutic centers emphasize procedure flexibility. Hospital procurement committees weigh disposable kit economics against capital depreciation schedules when segmenting vendor proposals.
Product Type:
Upgrade cycles in this category track the shift from centrifugation-heavy platforms to membrane-based systems that reduce floor space and staffing requirements.
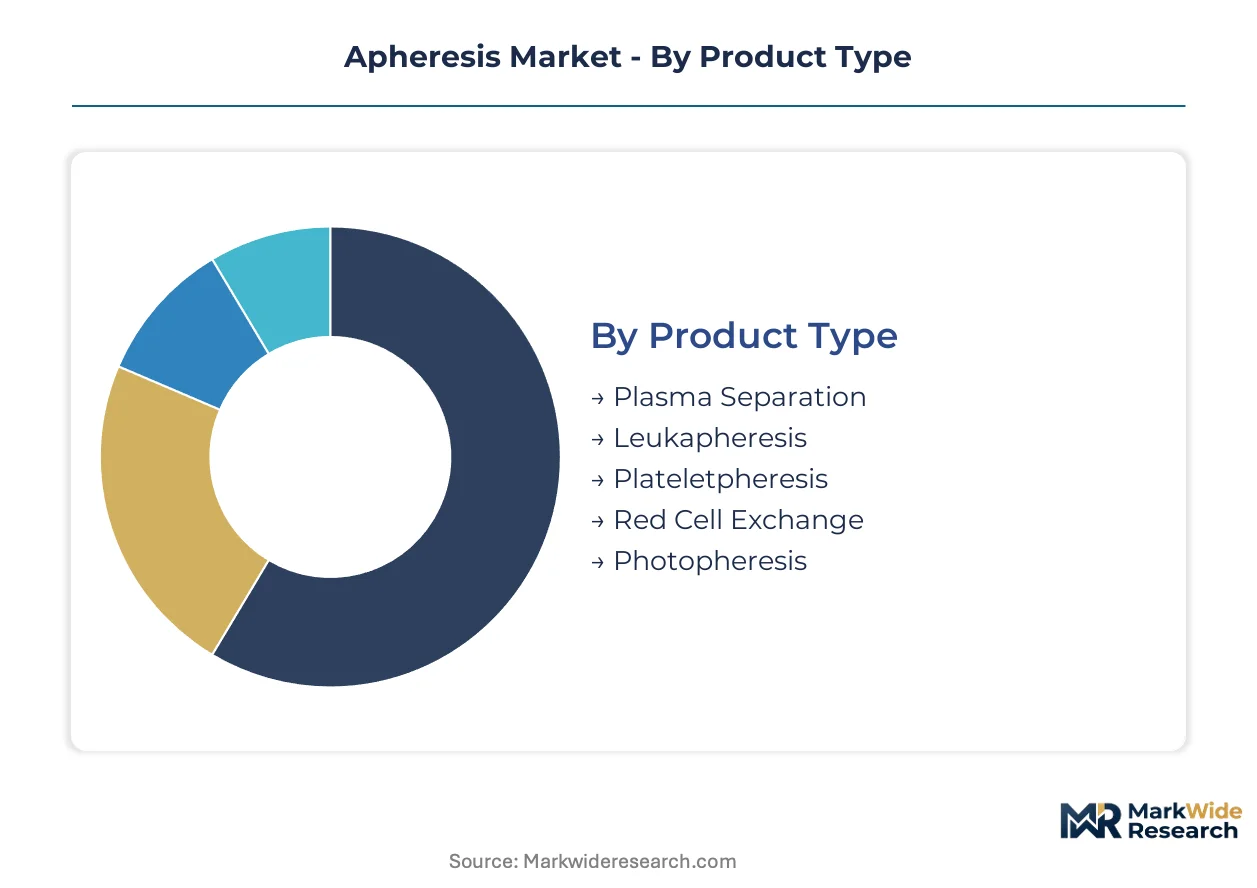
- Plasma Separation:Membrane-based plasma separators operate at 50-120 mL/min flow rates with hollow-fiber polysulfone cartridges. Demand concentrates in German and United States outpatient therapeutic centers where reimbursement codes favor ambulatory plasma exchange for neurological indications.
- Leukapheresis:Continuous-flow centrifugation systems collect mononuclear cells for CAR-T manufacturing pipelines. Academic hospitals in Boston and Heidelberg are expanding collection capacity to feed autologous cell therapy contract development organizations.
- Plateletpheresis:Automated collection platforms use intermittent-flow centrifugation with sterile disposable sets. Blood banks in Japan deploy these for single-donor platelet inventory.
- Red Cell Exchange:Erythrocytapheresis systems exchange patient red cells for donor units in sickle cell protocols. Therapeutic centers in metropolitan United States clusters utilize these for chronic transfusion programs.
- Photopheresis:Extracorporeal photoimmunotherapy combines leukapheresis with UVA irradiation and psoralen. Specialty clinics in France and Italy maintain installed bases for cutaneous T-cell lymphoma.
Volume placements concentrate in Plasma Separation; the faster expansion belongs to Leukapheresis.
Application:
Cost tier differentiation separates high-acuity inpatient indications from reimbursable outpatient procedures that sustain equipment utilization rates.
- Autoimmune Disorders:Therapeutic plasma exchange removes pathogenic antibodies in Guillain-Barré syndrome and myasthenia gravis. German university hospitals are shifting these procedures to satellite dialysis clinics to reduce inpatient bed days.
- Hematology:Red cell exchange and platelet reduction manage sickle cell disease and thrombocytosis. United States academic medical centers in Baltimore and Philadelphia anchor procedure volume for these indications.
- Transfusion Medicine:Donor apheresis collection supplies blood components for transfusion services. Blood banks in Tokyo and Osaka maintain the densest installed base of automated collection platforms.
- Oncology:Leukapheresis harvests peripheral blood stem cells for autologous transplantation. Cell therapy manufacturing facilities in North Carolina and Basel are scaling collection capacity to meet pipeline demand.
- Infectious Diseases:Plasmapheresis removes circulating cytokines in sepsis protocols. Research institutes in Paris and Milan evaluate these applications in controlled trials.
Transfusion Medicine sustains the largest installed equipment base; Oncology is climbing the fastest as cell therapy manufacturing scales.
End User:
Customer type determines service contract structures, with blood banks favoring comprehensive maintenance agreements while research institutes negotiate per-procedure consumable pricing.
- Blood Banks:High-volume donor collection facilities operate centrifugation platforms with automated component separation. Japanese Red Cross blood centers in Tokyo, Osaka, and Nagoya run the most intensive collection schedules.
- Therapeutic Centers:Outpatient facilities perform plasma exchange and red cell exchange on chronic patients. German dialysis chains are cross-training staff to operate apheresis platforms in existing vascular access centers.
- Research Institutes:Cell therapy development labs use leukapheresis for clinical trial material production. Boston and San Francisco clusters house the most concentrated collection infrastructure.
- Specialty Clinics:Photopheresis centers treat cutaneous T-cell lymphoma and graft-versus-host disease. Italian dermatology clinics in Milan and Rome maintain dedicated treatment capacity.
- Academic Hospitals:Full-service institutions combine donor collection, therapeutic procedures, and research applications. University hospitals in Heidelberg, Baltimore, and Tokyo integrate apheresis across multiple departments.
Equipment density peaks in Academic Hospitals; Specialty Clinics are gaining share fastest as site-of-care migration accelerates.
Technology:
Supply concentration in membrane substrate manufacturing is compressing margins for centrifugation-dependent platform vendors.
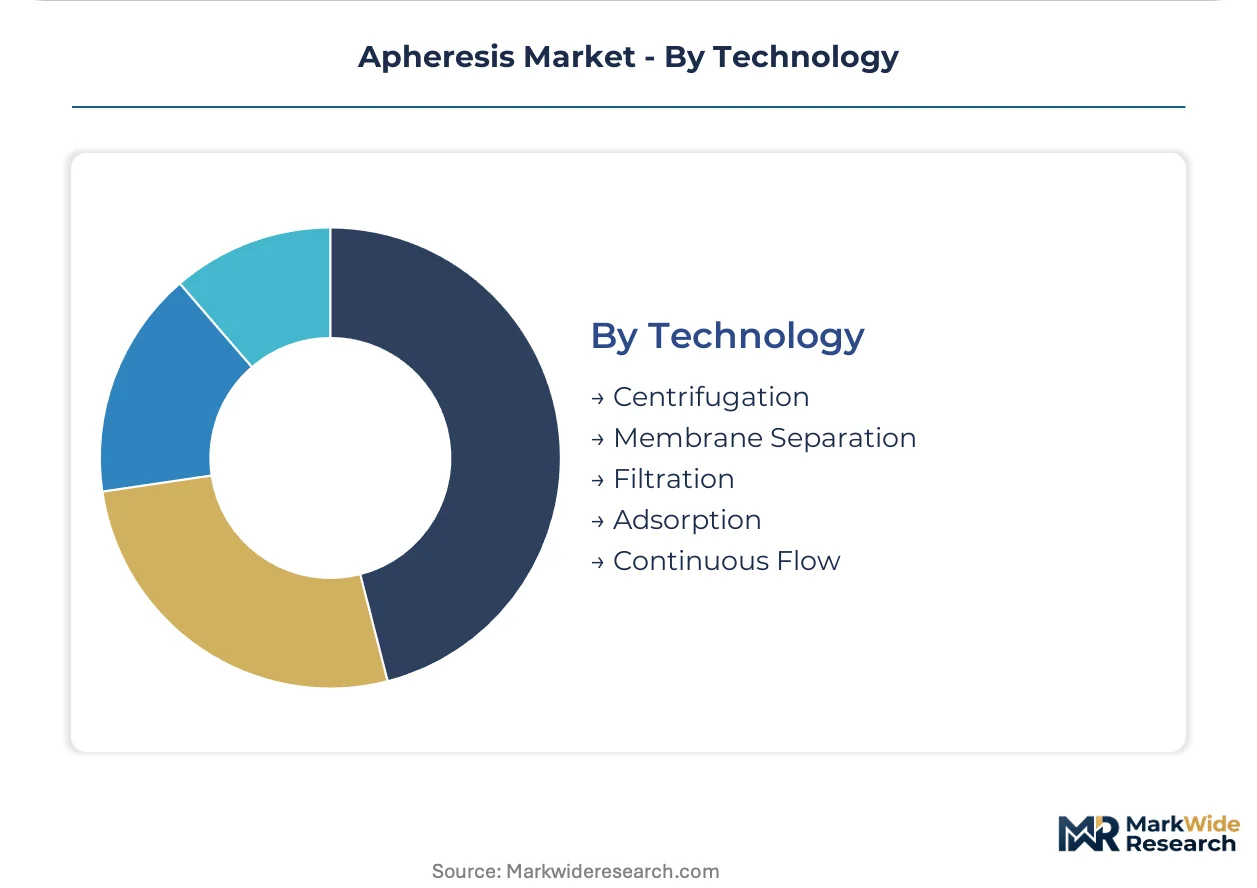
- Centrifugation:Density-gradient separation using intermittent or continuous flow at 3000-5000 rpm. Blood banks in Japan and Germany retain the largest installed base of these mature platforms.
- Membrane Separation:Hollow-fiber or flat-sheet membranes separate plasma based on molecular weight cutoffs. Outpatient therapeutic centers in the United States are displacing centrifugation with these compact systems.
- Filtration:Selective adsorption columns remove specific pathogenic substances from separated plasma. French and Italian clinics deploy these for lipid disorders and autoimmune conditions.
- Adsorption:Immunoaffinity columns bind targeted antibodies or immune complexes. Research applications in Basel and Boston evaluate these for refractory autoimmune diseases.
- Continuous Flow:Automated systems integrate separation, anticoagulation, and fluid balance without operator intervention. German dialysis clinic networks are deploying these to extend therapeutic apheresis access.
Centrifugation retains the deepest installed base; Membrane Separation is expanding most quickly as outpatient reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in Germany and Japan, while therapeutic procedure volume and cell therapy demand pull consumable consumption toward the United States. This geographic split shapes capital investment flows and disposable kit logistics differently across major markets.
United States
Academic medical centers in Boston and Baltimore drive leukapheresis collection for CAR-T manufacturing pipelines. FDA 21 CFR 876.5880 clearance pathways govern therapeutic device approvals, extending launch timelines for new indications. The Research Triangle Park corridor in North Carolina anchors cell therapy contract manufacturing infrastructure.
Germany
University hospitals in Heidelberg and Munich operate the densest installed base of therapeutic apheresis platforms in Europe. EU MDR device classification and F-Gas Regulation constraints are accelerating equipment refresh cycles ahead of 2030 refrigerant phase-down deadlines. Dialysis clinic networks in Baden-Württemberg are cross-training staff for outpatient plasma exchange procedures.
Japan
Tokyo and Osaka blood centers maintain intensive automated donor collection schedules for single-donor platelet inventory. METI-aligned health ministry reimbursement codes now cover photopheresis in outpatient settings, expanding addressable treatment volume. The Nagoya medical device cluster supplies membrane substrates for regional kit manufacturers.
France
Specialty dermatology clinics in Paris and Milan maintain dedicated photopheresis capacity for cutaneous T-cell lymphoma protocols. ANSM oversees device vigilance for therapeutic apheresis instruments under EU MDR harmonized standards. Research institutes in the Paris-Saclay cluster evaluate selective adsorption columns for refractory autoimmune conditions.
India
Maharashtra and Karnataka are attracting component suppliers establishing local membrane production under the PLI scheme for critical care equipment. CDSCO medical device rules govern import and manufacturing licensing for apheresis platforms. Hyderabad's pharmaceutical corridor is developing cell therapy collection infrastructure to serve domestic clinical trial pipelines.
Apheresis Market Key Industry Players
Top-tier vendors anchor the premium equipment tier, while mid-scale specialists and regional fabricators occupy differentiated positions in consumables and service networks. The market structure reflects consolidation around integrated platform providers alongside persistent fragmentation in membrane substrate supply. Three archetypes dominate: diversified medical technology conglomerates with dialysis cross-selling capabilities, blood management specialists with automated collection expertise, and cell therapy-focused equipment providers. Competitive moves center on M&A for membrane technology access and strategic partnerships with cell therapy contract manufacturers.
Among Germany-based diversified health care groups, Fresenius SE & Co. KGaA and B. Braun Melsungen AG exemplify the cross-selling archetype that leverages dialysis infrastructure for apheresis platform placement. Japanese manufacturers Asahi Kasei Medical Co. Ltd. and Terumo BCT occupy positions within the membrane technology and blood component processing tiers respectively. Haemonetics Corporation represents the North American blood management specialist archetype focused on automated collection systems.
| Leading Market Players |
|---|
| Asahi Kasei Medical Co. Ltd. |
| B. Braun Melsungen AG |
| Terumo BCT |
| Nikkiso Co. Ltd. |
| Kaneka Corporation |
| Fresenius SE & Co. KGaA |
| Baxter International Inc. |
| Miltenyi Biotec |
| Haemonetics Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up membrane substrate specialists in Germany and Japan exercise outsized influence on kit economics, translating concentrated polymer supply into pricing discipline that disposable manufacturers pass to hospital procurement committees through multi-year volume commitments.
Pricing Analysis
Cost-down pressure on standard-grade centrifugation platforms accelerates because outpatient therapeutic centers in the United States and Germany are unbundling service contracts from capital purchases. Three-tier pricing structure across premium membrane systems, standard centrifugation equipment, and economy-grade donor collection platforms dominates equipment transactions, with FDA 510(k) clearance tier and ISO 13485 certification level driving spreads between tiers. Pricing pressure stems from blood bank consolidation around single-vendor platforms to simplify EU MDR compliance audits. Research institutes and cell therapy contract manufacturers show lowest price sensitivity due to protocol-specific technical requirements.
Supply Chain Analysis
Refurbishment flows for centrifugation equipment concentrate in Germany and Japan, where original manufacturers recapture installed base units for cooling system retrofits ahead of EU F-Gas Regulation deadlines. Hollow-fiber polysulfone membranes and medical-grade polymer substrates draw from German chemical suppliers and Japanese material science clusters, with Nagoya and Heidelberg anchoring regional fabrication. Single-source vulnerability in specialized membrane substrates exposes kit manufacturers to input bottlenecks when pharmaceutical-grade polymer allocation tightens. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, direct tender contracts with university hospital networks in Germany, and Japanese Red Cross centralized procurement in Tokyo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The apheresis market represents a consolidation play as EU MDR quality benchmarks and FDA clearance timelines force sub-scale disposable kit manufacturers toward strategic exits or acquisition.
For Market Incumbents: Extend membrane technology leadership through captive supply arrangements with German and Japanese polymer substrate specialists, insulating against input bottlenecks that disrupt smaller competitors. Acquire regional service networks in United States dialysis clinic chains to lock in outpatient therapeutic apheresis volume before hospital procurement committees complete vendor consolidation. Prioritize CE marking investment for continuous-flow membrane platforms ahead of 2030 F-Gas equipment refresh cycles. For New Entrants and Emerging Players: Mid-tier therapeutic centers in India's Maharashtra and Karnataka states present addressable white space as PLI scheme incentives attract local membrane production and CDSCO licensing pathways mature. Home-based therapeutic apheresis for chronic neurological indications offers penetrable entry point with portable membrane systems that bypass perfusionist staffing constraints. Pursue software-protocol convergence partnerships with hospital information system vendors to create platform stickiness without competing on capital equipment price. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane substrate specialists with ISO 13485 certification and existing supplier relationships to Fresenius or Terumo BCT manufacturing networks in Germany and Japan. Five-to-ten year viability hinges on positioning for cell therapy manufacturing scale rather than traditional transfusion medicine replacement demand. Monitor leukapheresis collection capacity announcements from Boston and Research Triangle Park cell therapy contract development organizations as inflection indicator for consumable kit volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German and French hospital procurement tenders ahead of competitors. |
| Hospital System Partnership | United States academic medical center alliances secure leukapheresis volume for CAR-T manufacturing pipelines. |
| Software Companion Development | Patient treatment tracking integration with Epic or Cerner creates recurring revenue and platform stickiness. |
| Backward Integration into Membranes | Captive hollow-fiber polysulfone production insulates against German and Japanese polymer supply bottlenecks. |
| Reimbursement Strategy | METI-aligned outpatient procedure codes in Japan expand photopheresis addressable market beyond inpatient wards. |
Research Approach
FDA 510(k) filings, EU MDR technical documentation databases, and Japanese PMDA device registrations formed the secondary backbone for equipment and disposable kit market sizing. Primary interviews with hospital procurement committee chairs, biomedical engineers managing apheresis platforms, perfusionist department heads, and cell therapy manufacturing supply chain directors validated installed base estimates and replacement cycle assumptions. Bottom-up enumeration of academic hospital and blood center equipment placements triangulated against top-down disposable kit revenue flows reported in SEC filings and trade registry extracts.
Bottom-up modeling tracked individual procedure volumes across autoimmune disorder, hematology, and oncology applications, while top-down analysis calibrated aggregate market evolution against dialysis infrastructure expansion and cell therapy clinical trial pipelines. Segmentation dimensions included product type, application, end user, and technology platform, with geographic regulatory clusters capturing FDA, EU MDR, and PMDA pathway differences. CAGRs derived from equipment replacement cycles, reimbursement code expansion trajectories, and cell therapy manufacturing capacity buildouts across the projection horizon.
Revisions become necessary when EU F-Gas Regulation enforcement accelerates equipment refresh timelines, when Japanese METI expands outpatient reimbursement codes beyond current photopheresis coverage, or when cell therapy contract manufacturers consolidate collection capacity around captive leukapheresis infrastructure. Practitioners should monitor FDA 21 CFR 876.5880 clearance timelines for new therapeutic indications and German university hospital satellite clinic deployment schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Febrile Neutropenia Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Haematocrit Centrifuge Market
Hematology
Aplastic Anemia Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Bone Marrow Transplant Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Single Blood Drop Analysis Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Global Hemoglobin Meter Market
Hematology
Acute Myeloid Leukemia Treatment Market