
 Haematocrit Centrifuge Market | 2026-2036
Haematocrit Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Haematocrit Centrifuge Market Foresight
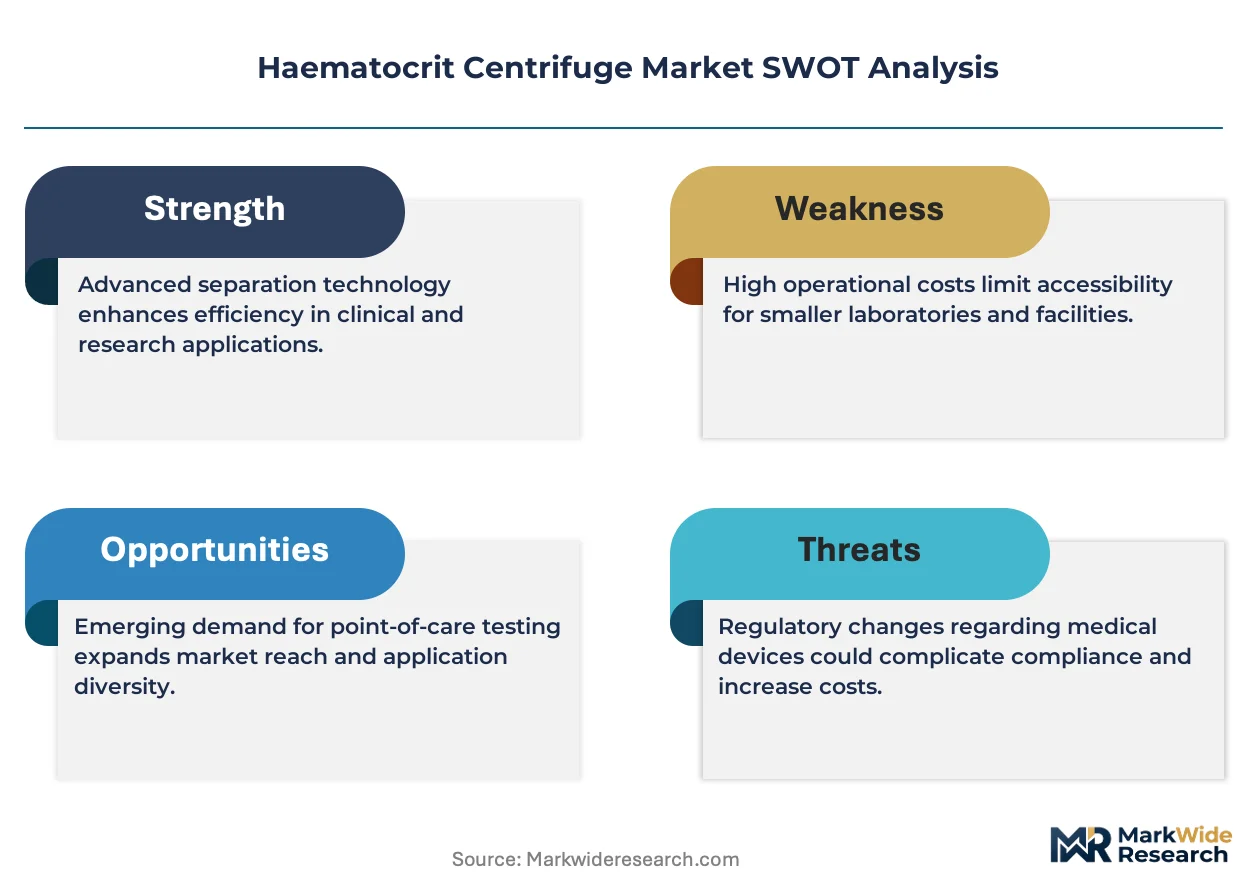
Diagnostic laboratories is reorganizing demand away from hospital-centric purchasing, pulling haematocrit centrifuge procurement toward decentralized testing networks. Thermo Fisher Scientific leverages its clinical diagnostics infrastructure to anchor high-volume supply agreements with reference labs across North America. Hettich GmbH & Co.KG sustains German engineering credibility through precision-manufactured benchtop units that dominate European laboratory specifications.
A haematocrit centrifuge is a laboratory instrument that spins blood samples at controlled rotational speeds, typically generating relative centrifugal force measured in g-force to separate red blood cells from plasma for volume fraction analysis. The device employs fixed-angle or swing-bucket rotors with precise timer and speed controls to ensure reproducible haematocrit readings essential for anaemia screening and blood disorder diagnostics. Digital centrifuges command premium positioning through programmable protocols and touchscreen interfaces that reduce operator error in high-throughput settings. Benchtop centrifuges retain volume leadership in blood bank applications where space constraints and batch processing requirements favor compact footprint designs. Microcentrifuges represent the fastest-expanding category as molecular diagnostics and microsample workflows penetrate point-of-care environments.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape haematocrit centrifuge market access by mandating biocompatibility testing and electromagnetic compatibility validation for clinical deployment. ISO 13485 quality management systems and IEC 61010-1 safety standards further constrain supplier participation by demanding documented design controls and risk management files. Stakeholders must monitor evolving harmonization between FDA and EU regulatory frameworks to anticipate compliance cost shifts that will redistribute competitive advantage among manufacturers with established quality infrastructures.
Market Dynamics
Point-of-care blood testing protocols are pulling procurement away from centralized hospital laboratories toward decentralized diagnostic networks, restructuring how haematocrit centrifuge vendors configure distribution and service models.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter device classification requirements in Europe are filtering out low-quality manufacturers and consolidating demand around certified suppliers with established quality management systems.
- Microsample workflow penetration:Molecular diagnostics laboratories are adopting compact microcentrifuge formats for capillary blood analysis, expanding addressable use cases beyond traditional haematology.
- Heidelberg-Berlin equipment cluster:German precision engineering concentration around these cities sustains regional supply chain density and accelerates R&D feedback loops for benchtop unit manufacturers.
Market Restraints
- Rotor material cost volatility:Aerospace-grade aluminum and carbon fiber composite prices fluctuate with energy markets, compressing margins for fixed-angle rotor production.
- Supply concentration in German precision manufacturing:Dependence on Mittelstand suppliers for spindle motors and vibration-dampening components creates single-source vulnerability.
- IEC 61010-1 electromagnetic compatibility validation:Clinical deployment requirements demand expensive third-party testing that extends product development timelines for new market entrants.
Strategic Opportunities
- Indian diagnostic laboratory expansion:CDSCO regulatory harmonization with ISO 13485 is lowering market access barriers for quality-certified centrifuge suppliers in tier-2 and tier-3 cities.
- Blood bank automation integration:Convergence between haematocrit centrifuges and automated sample handling systems creates specification pull from transfusion medicine facilities.
- Remote maintenance telemetry:IoT-enabled predictive service models allow manufacturers to unbundle after-sales support and capture recurring revenue from distributed point-of-care networks.
Industry Challenges
- ISO 13485 auditor scarcity:Limited pool of qualified quality management system assessors extends certification timelines and delays product launches.
- Legacy LIS integration complexity:Benchtop centrifuge data output formats often require middleware development to connect with established laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Haematocrit Centrifuge Market |
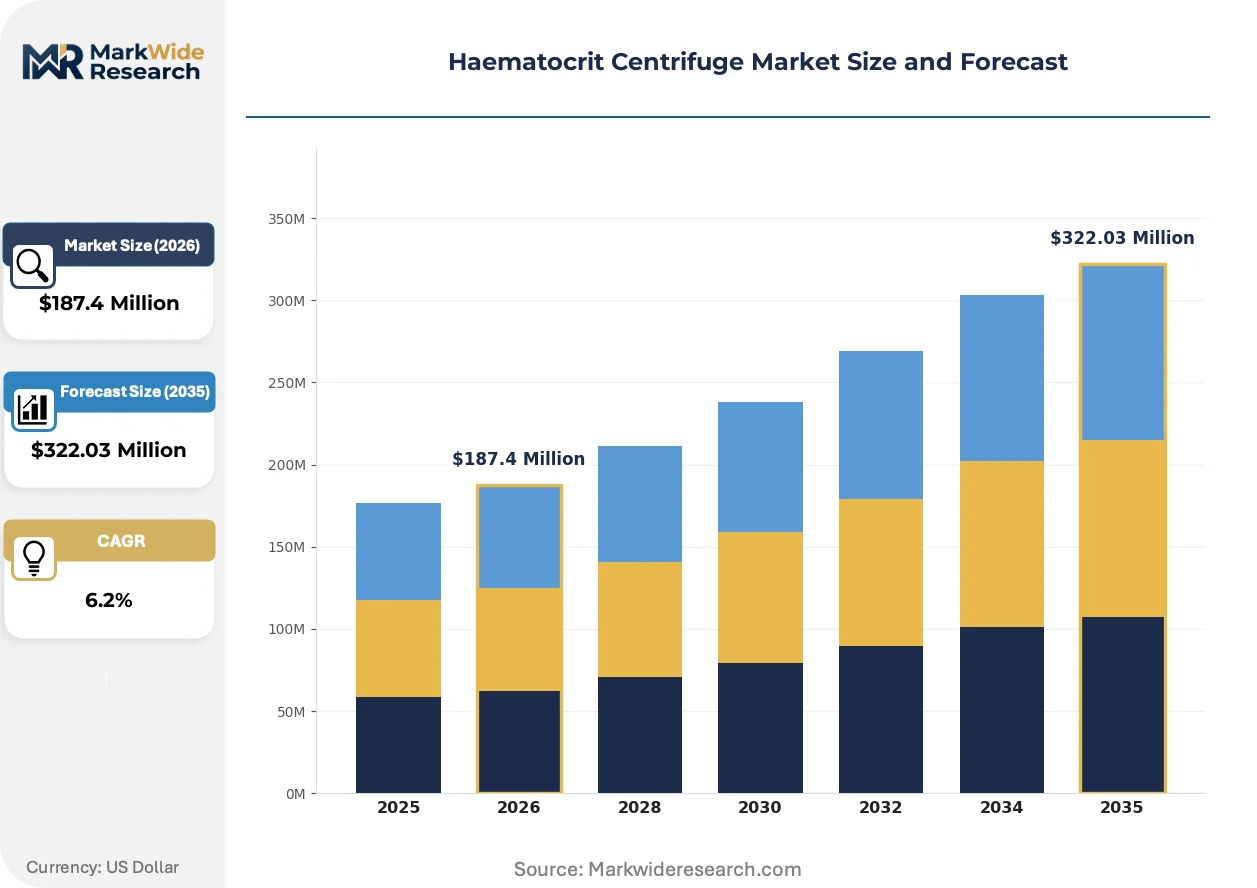
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $322.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Speed Centrifuges, High-Speed Centrifuges, Microcentrifuges, Benchtop Centrifuges End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Technology: Analog Centrifuges, Digital Centrifuges, Refrigerated Centrifuges, Universal Centrifuges Distribution Channel: Direct Sales, Online Retail, Third-Party Distributors, Medical Equipment Suppliers |
| Companies Covered | Thermo Fisher Scientific, Beckman Coulter, Hettich GmbH & Co.KG, Eppendorf, Horiba, Scilogex, LW Scientific, AHN Biotechnologie, Daigger Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haematocrit Centrifuge Market Shifts & Advancements
Digital control architectures and connected service models are displacing mechanical timer-based systems as the default specification in clinical procurement, while regulatory harmonization efforts compress compliance cost differentials between major markets.
Brushless DC motor technology with integrated tachometer feedback is displacing universal AC motor designs in premium haematocrit centrifuge configurations. Reference laboratories in North America are specifying these units for high-throughput anaemia screening protocols. The shift is compressing maintenance intervals and enabling programmable acceleration curves that improve red cell packing consistency.
EU MDR post-market surveillance requirements are mandating systematic vigilance reporting for Class IIa medical devices including haematocrit centrifuges. Manufacturers must now maintain electronic systems for incident tracking and periodic safety update reporting. German and French notified bodies are experiencing application backlogs that delay certificate renewals for established product lines.
Diagnostic laboratory purchasing consortia are consolidating procurement authority across regional health networks. Group purchasing organizations are displacing individual hospital tender processes as the dominant transaction channel. This concentration is most visible in the United States, where integrated delivery networks negotiate multi-year supply agreements that lock out smaller centrifuge vendors lacking national service infrastructure.
Haematocrit Centrifuge Market Segmentation
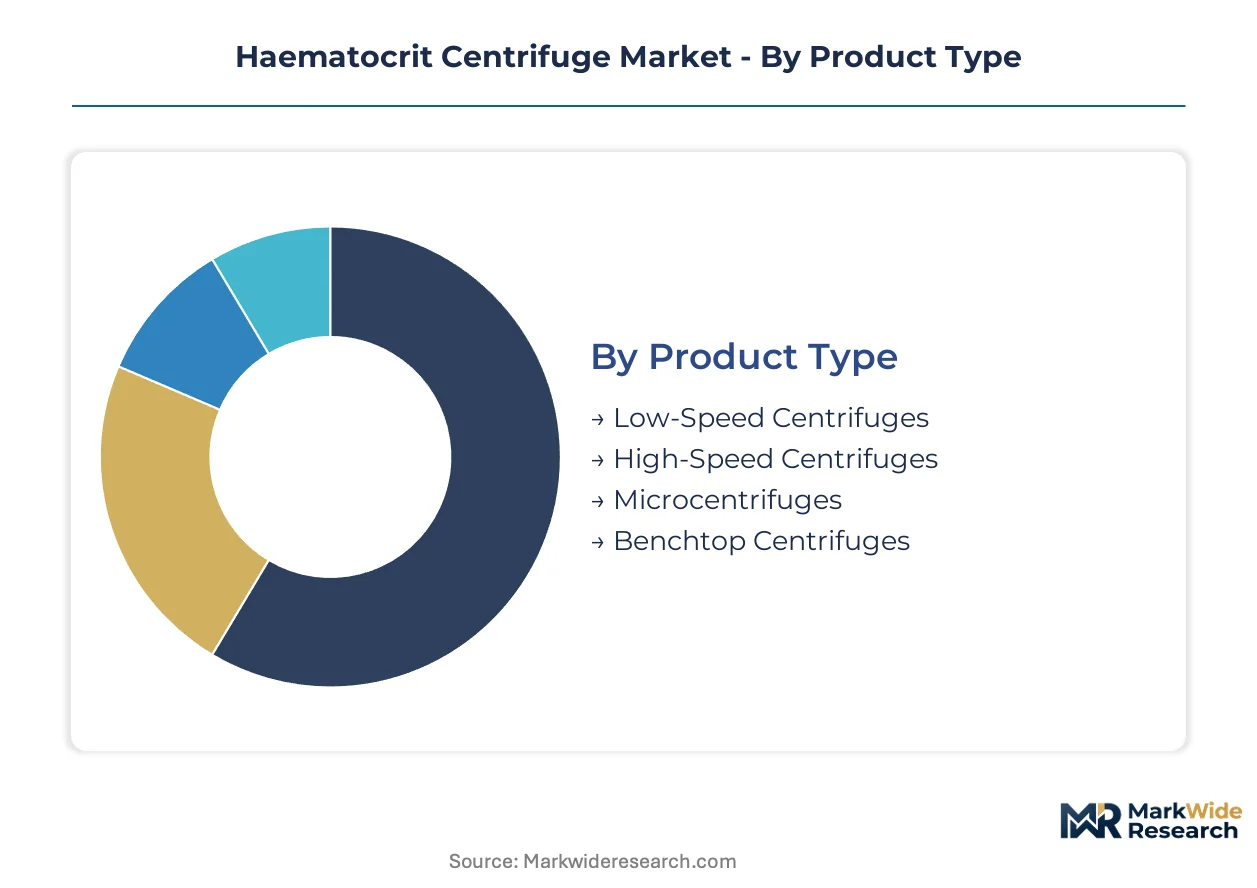
Haematocrit centrifuge procurement patterns diverge sharply across product formats, with regulatory classification tiers and end-use workflow requirements driving specification fragmentation. Understanding these segment boundaries clarifies how manufacturers configure rotor designs, control interfaces, and service architectures to match distinct buyer economics.
Product Type:
FDA 510(k) clearance pathways and EU MDR technical documentation requirements impose divergent compliance burdens across rotational speed categories, reshaping competitive entry barriers.
- Low-Speed Centrifuges:These units operate below 6,000 RPM for basic red cell packing in routine anaemia screening. Blood banks in Germany specify these for high-volume batch processing where gentle sedimentation preserves sample integrity.
- High-Speed Centrifuges:Capable of exceeding 15,000 RPM, these systems generate precise relative centrifugal force for coagulation studies and specialized haematology protocols. Research institutions in Heidelberg cluster demand these for reproducible acceleration curves in multi-site clinical trials.
- Microcentrifuges:Compact formats designed for capillary blood tubes and microsample workflows. Point-of-care networks in tier-2 Indian cities are adopting these for decentralized anaemia screening programs.
- Benchtop Centrifuges:Space-optimized designs with fixed-angle rotors dominate hospital laboratory footprints where batch throughput meets spatial constraints.
Benchtop centrifuges handle the majority of throughput; microcentrifuges are gaining share fastest as molecular diagnostics penetrates decentralized testing networks.
End User:
Procurement authority is migrating from hospital capital budgets toward diagnostic laboratory operating expenditure models, restructuring vendor pricing and service terms.
- Hospitals:Centralized haematology departments specify multi-purpose centrifuges with interchangeable rotors for diverse clinical protocols. German university hospitals anchor regional tender volumes through integrated device procurement.
- Diagnostic Laboratories:Reference labs in North America negotiate multi-year supply agreements with national service coverage requirements. These buyers prioritize programmable protocols and remote maintenance telemetry over capital cost minimization.
- Research Institutions:Academic medical centers demand validated reproducibility documentation for grant-funded multi-site studies. Precision engineering from Berlin-area manufacturers satisfies stringent protocol standardization requirements.
- Blood Banks:Transfusion medicine facilities require continuous-batch processing capability with minimal operator intervention. Automation integration specifications are pulling centrifuge design toward sample handling system compatibility.
Diagnostic laboratories command the steepest volume expansion; blood banks are driving the fastest specification evolution through automation convergence.
Technology:
Control architecture choices determine electromagnetic compatibility validation scope and IEC 61010-1 testing cost structures for clinical deployment.
- Analog Centrifuges:Mechanical timer-based systems with limited speed precision retain presence in price-sensitive procurement channels. These units face declining specification share as digital interfaces become default requirements in tier-1 laboratory tenders.
- Digital Centrifuges:Programmable touchscreen interfaces with stored protocol libraries reduce operator error in high-throughput settings. FDA-cleared digital units command premium positioning in US reference laboratory contracts.
- Refrigerated Centrifuges:Temperature-controlled chambers maintain sample integrity during extended centrifugation for sensitive coagulation assays. Blood processing centers in transfusion medicine specify these for plasma component preparation.
- Universal Centrifuges:Modular platforms accepting multiple rotor configurations serve laboratories with diverse testing menus. These systems minimize capital duplication across haematology, chemistry, and molecular diagnostics workflows.
Digital centrifuges dominate new procurement specifications; refrigerated units are climbing fastest as transfusion medicine quality standards tighten.
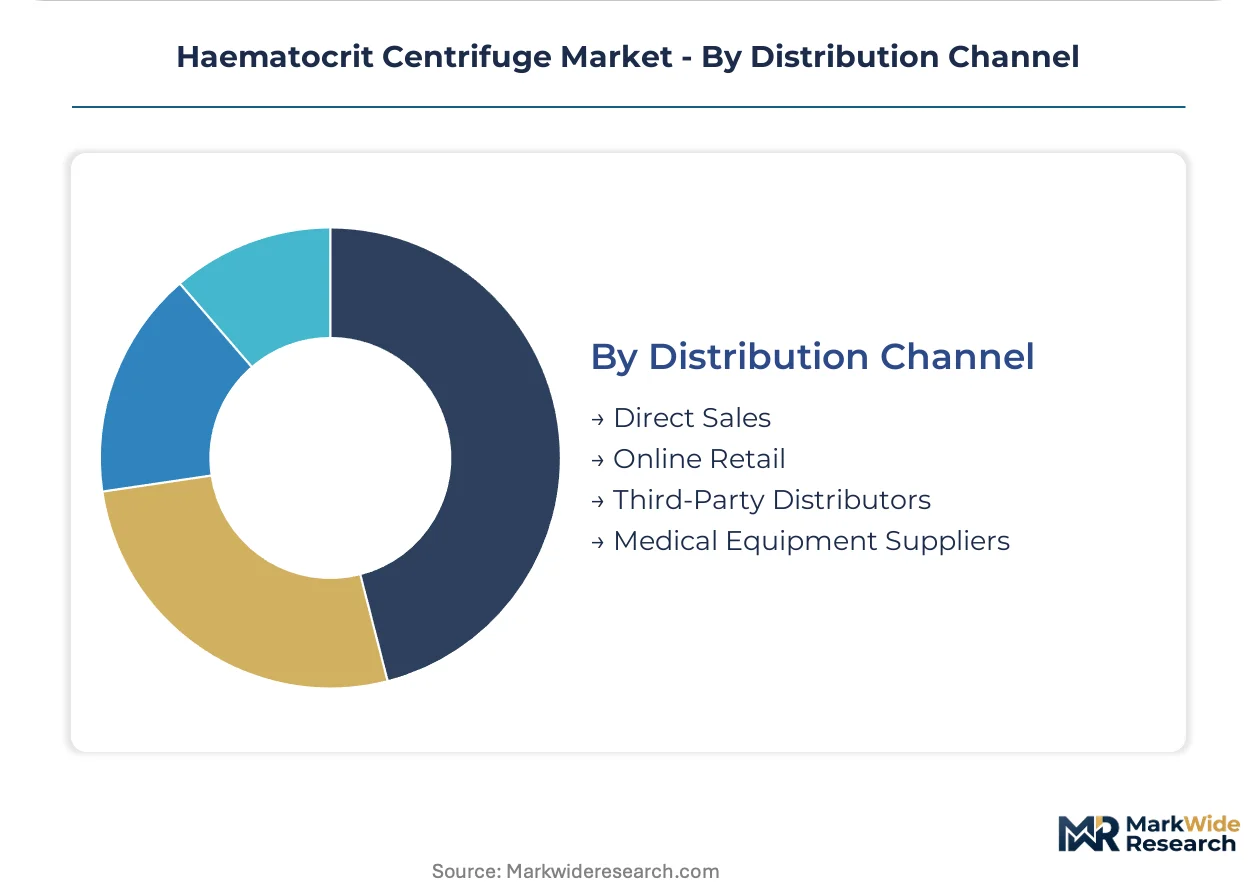
Distribution Channel:
Channel selection determines service response time commitments and spare parts inventory positioning across geographically dispersed laboratory networks.
- Direct Sales:Manufacturer field organizations negotiate enterprise agreements with integrated delivery networks. Thermo Fisher Scientific leverages this channel to anchor multi-year supply contracts with US reference laboratories.
- Online Retail:E-commerce platforms serve small diagnostic laboratories and physician office laboratories with standardized configurations and rapid delivery. CDSCO-harmonized Indian suppliers are penetrating tier-2 city procurement through this channel.
- Third-Party Distributors:Regional medical device distributors provide localized installation and preventive maintenance coverage. German Mittelstand manufacturers rely on these partners for European market penetration beyond direct sales reach.
- Medical Equipment Suppliers:Specialized laboratory equipment dealers bundle centrifuges with consumables and reagent contracts. Group purchasing organizations consolidate transactions through preferred supplier agreements.
Direct sales captures the largest transaction value; online retail is expanding most quickly as small laboratory procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European laboratory equipment distribution, handling precision instrument imports from Mittelstand manufacturers while serving as a transshipment node for Middle Eastern and African diagnostic networks.
Germany
Heidelberg university hospitals and Berlin-area research institutes drive demand for high-speed centrifuge systems with validated reproducibility documentation. EU MDR technical documentation requirements filter procurement toward ISO 13485-certified suppliers with established quality management systems. The Heidelberg-Berlin corridor concentrates precision engineering capabilities and accelerates R&D feedback loops for benchtop unit development.
United States
Integrated delivery networks and reference laboratories in Massachusetts and North Carolina negotiate multi-year supply agreements with national service coverage requirements. FDA 510(k) clearance pathways mandate biocompatibility testing and electromagnetic compatibility validation for clinical deployment. The Research Triangle Park cluster anchors contract research organization demand for protocol-standardized equipment in multi-site clinical trials.
India
Tier-2 and tier-3 city diagnostic laboratories in Maharashtra and Karnataka are expanding procurement as point-of-care blood testing protocols proliferate. CDSCO regulatory harmonization with ISO 13485 lowers market access barriers for quality-certified suppliers. Mumbai-Pune industrial corridor suppliers penetrate decentralized networks through digitized procurement channels and rapid delivery logistics.
China
Shanghai and Beijing hospital consortia specify digital centrifuge systems with programmable protocols for high-throughput anaemia screening. NMPA medical device registration requirements impose clinical trial documentation burdens on imported equipment. Yangtze River Delta manufacturing clusters are developing domestic brushless DC motor capabilities to reduce dependence on German spindle motor suppliers.
Japan
Tokyo and Osaka metropolitan area university hospitals demand precision-engineered units for grant-funded haematology research. PMDA quality management system inspections extend certification timelines for foreign manufacturers seeking market entry. Kansai region medical device distributors provide localized preventive maintenance coverage for imported European equipment.
Haematocrit Centrifuge Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification depth, creating a tiered structure where public company scale advantages clash with Mittelstand engineering precision. Thermo Fisher Scientific leverages clinical diagnostics infrastructure to anchor high-volume supply agreements, while Hettich GmbH sustains German engineering credibility through precision-manufactured benchtop units. Three archetypes dominate: diversified life science conglomerates with diagnostic divisions, family-owned precision engineering specialists, and emerging Asian fabricators with cost-optimized configurations. Competitive moves concentrate on M&A to secure service network density and strategic partnerships with group purchasing organizations.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Beckman Coulter exemplify scale-driven positioning through integrated supply agreements with North American reference laboratories. Hettich GmbH & Co.KG anchors the family-owned specialist archetype, occupying a position where precision manufacturing heritage commands specification pull in European tender processes. Eppendorf represents the mid-cap precision player segment, sitting within a competitive space where programmable digital interfaces differentiate against mechanical timer-based alternatives.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Beckman Coulter |
| Hettich GmbH & Co.KG |
| Eppendorf |
| Horiba |
| Scilogex |
| LW Scientific |
| AHN Biotechnologie |
| Daigger Scientific |
| Others |
Supply & Pricing Matrix
Ninety-day spindle motor lead times from Mittelstand suppliers compress inventory buffers for German manufacturers, concentrating pricing power with rotor fabricators who command premium positioning in ISO 13485-certified procurement channels. This inventory constraint feeds directly into tiered pricing stratification across the haematocrit centrifuge market.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared digital units with programmable protocols from CE-marked analog systems and uncertified economy configurations. Price differentiation hinges on electromagnetic compatibility validation depth and after-sales service bundling, with reference laboratories in North America least sensitive to capital cost and physician office laboratories in emerging markets most responsive to unit economics. Pricing pressure stems from carbon fiber rotor material cost volatility, which is squeezing margins for fixed-angle rotor production.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade aluminum and vibration-dampening components dominates procurement strategy among German precision manufacturers, insulating production schedules against raw material volatility. Supply concentrates in Germany for spindle motors and precision-machined rotors, with secondary sourcing from China for brushless DC motor assemblies and Taiwan for electronic control modules. Single-source vulnerability around Mittelstand component suppliers creates structural risk exposure. Distribution runs through specialized laboratory equipment dealers who bundle installation and preventive maintenance coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where ISO 13485 certification timelines and FDA 510(k) clearance pathways create switching costs that lock hospital systems into established supplier relationships.
For Market Incumbents: Compound service network density through predictive maintenance telemetry deployments that capture recurring revenue from distributed point-of-care networks. Deepen backward integration into brushless DC motor production to reduce exposure to German spindle motor supply concentration. Defend against emerging Asian fabricators by accelerating EU MDR certificate renewals before notified body backlogs extend.
For New Entrants and Emerging Players: Anchor in tier-2 Indian city diagnostic laboratories where CDSCO harmonization with ISO 13485 lowers market access barriers for quality-certified suppliers. Target microcentrifuge formats for capillary blood analysis workflows in decentralized anaemia screening programs. Penetrate through digitized procurement channels with rapid delivery logistics rather than direct sales infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU MDR and FDA clearance pathway divergence creates acquisition opportunities for quality-certified mid-cap specialists with underutilized notified body relationships. Monitor German notified body application backlogs as the signal to watch for certificate renewal delays that would compress valuations for established product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certificate Renewal Acceleration | Preemptive renewal secures market access before notified body backlogs extend timelines. |
| Brushless DC Motor Backward Integration | In-house motor production reduces dependence on German Mittelstand spindle suppliers. |
| Predictive Maintenance Telemetry Deployment | IoT-enabled service models unbundle after-sales support into recurring revenue streams. |
| CDSCO-Harmonized Quality Certification | ISO 13485 alignment opens tier-2 Indian city procurement channels for qualified entrants. |
| Microcentrifuge Format Development | Compact designs capture molecular diagnostics penetration in point-of-care environments. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads, then refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Bottom-up unit demand estimates triangulated with top-down market sizing across product type, end user, technology, and distribution channel segmentation dimensions.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segment. CAGRs were derived from modeled unit shipments and average selling price trajectories, incorporating brushless DC motor adoption curves and point-of-care network expansion rates as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU MDR implementation timelines and stable aerospace-grade aluminum pricing; material deviation would warrant model refresh. Revision becomes warranted when CDSCO regulatory harmonization progress or German notified body capacity crosses thresholds that alter market access economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Screening Market
Hematology
Hemoglobin Analyzer Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Single Blood Drop Analysis Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
At-Home Hematology Testing Market
Hematology
Myelofibrosis Treatment Market
Hematology
Hemostatic Spray Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Transfusion Dependent Thalassaemia Management Market