
 Bone Marrow Transplant Market | 2026-2036
Bone Marrow Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Marrow Transplant Market Analysis
Academic medical centers is collapsing the historical dominance of community oncology practices as the primary referral source for bone marrow transplant services. Novartis AG anchors the cellular therapy landscape through its sustained investment in CAR-T manufacturing infrastructure. Bristol Myers Squibb competes aggressively in the allogeneic transplant support segment with broad immunosuppressive portfolios. Merck Millipore Corporation controls critical consumable supply chains that underpin sterile cell processing workflows across transplant programs.
Bone marrow transplant encompasses the infusion of hematopoietic stem cells derived from bone marrow, peripheral blood, or umbilical cord blood into patients after myeloablative or reduced-intensity conditioning regimens, requiring CD34+ cell doses exceeding 2.0 × 10^6 cells per kilogram for engraftment. The procedure restores hematopoietic function following high-dose chemotherapy or radiation used to treat hematologic malignancies and certain genetic disorders. Allogeneic procedures command the highest procedural complexity and reimbursement tiers due to graft-versus-host disease management requirements, while autologous transplants sustain the largest procedure volumes across hospital-based transplant centers. Leukemia indications occupy the deepest clinical trial pipelines, whereas lymphoma applications are expanding fastest into outpatient and ambulatory surgery center settings where cost structures favor same-day discharge protocols.
FDA and EMA oversight of cellular therapy manufacturing through current Good Manufacturing Practice frameworks shapes facility capital requirements and limits market entry to well-capitalized hospital systems and dedicated contract manufacturers. The EU AI Act and HIPAA compliance obligations in the United States add data governance layers to transplant registries and patient-matching algorithms that international programs must navigate. Stakeholders should monitor how CMS and national health technology assessment bodies recalibrate reimbursement for outpatient transplant delivery models.
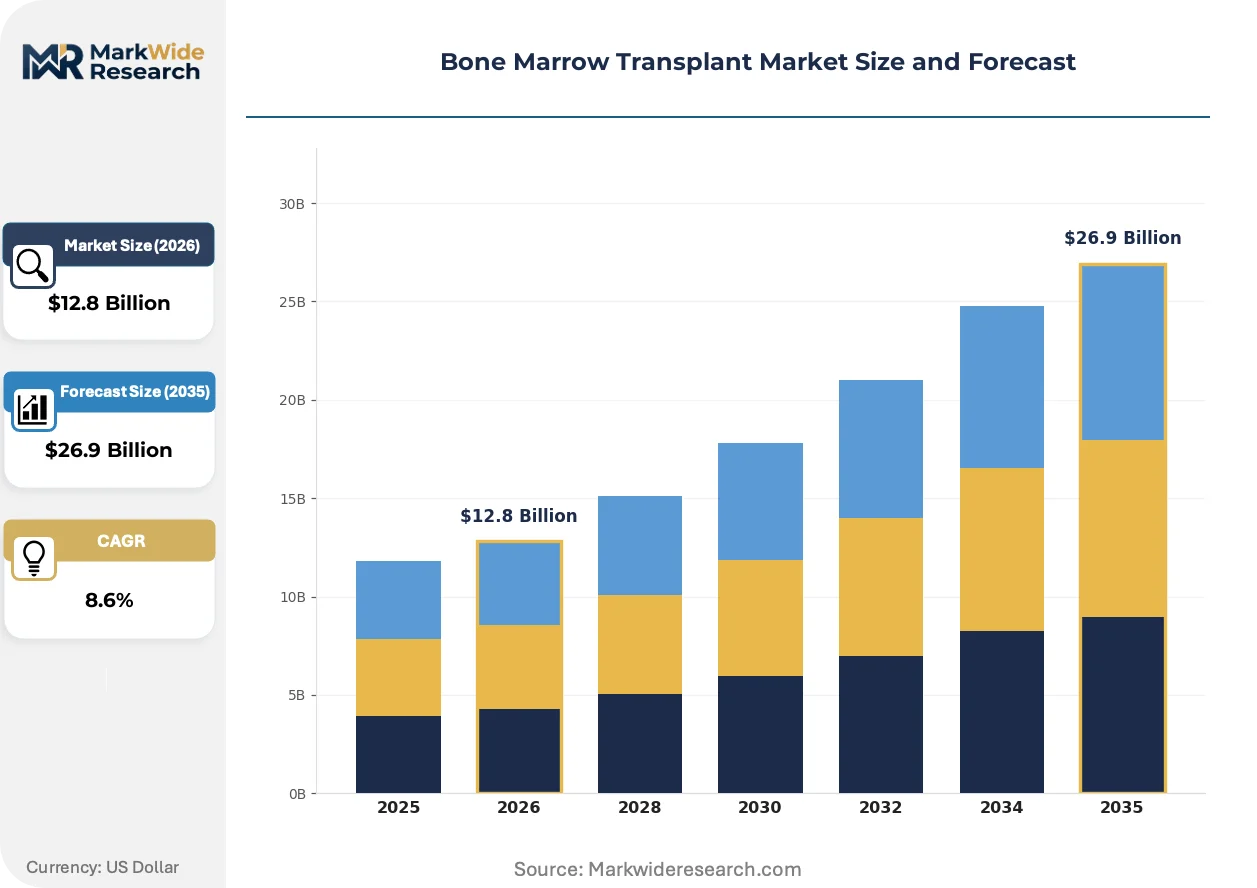
Market Dynamics
CAR-T cell therapy protocols are consolidating referral pathways toward academic medical centers, collapsing the historical distribution of bone marrow transplant services across community oncology networks and reshaping capital allocation for cellular therapy infrastructure.
Growth Catalysts
- FDA and EMA CAR-T Approvals:Regulatory clearances for CD19-directed therapies are creating standardized referral protocols that channel patients into certified transplant centers with manufacturing partnerships.
- Peripheral Blood Stem Cell Harvesting:Apheresis-based collection methods are displacing invasive bone marrow aspiration, reducing donor morbidity and expanding eligible donor pools for allogeneic procedures.
- Tertiary Care Network Consolidation:Hospital systems in the United States, Germany, and Japan are integrating cellular therapy services into centralized hubs that capture complex case referrals.
Market Restraints
- CD34+ Cell Dose Volatility:Donor-to-donor variation in stem cell yields creates engraftment failure risk that limits procedure scheduling predictability and inventory management.
- Graft-versus-Host Disease Burden:Allogeneic transplant complexity requires dedicated immunosuppression protocols that consume 40-60% of total procedural costs and extend length-of-stay metrics.
- Current Good Manufacturing Practice Capital Requirements:FDA and EMA facility standards impose sterile processing infrastructure costs that exclude smaller hospital systems from CAR-T program entry.
Strategic Opportunities
- Outpatient Transplant Models:Ambulatory surgery centers in the United States are piloting same-day discharge protocols for autologous lymphoma cases that reduce reimbursement pressure from inpatient DRG rates.
- Reduced-Intensity Conditioning Regimens:Lower-toxicity preparative protocols are expanding transplant eligibility to older patients and those with comorbidities previously excluded from myeloablative approaches.
- HIPAA-Compliant Registry Analytics:Patient-matching algorithms leveraging longitudinal outcome data are optimizing donor selection and graft-versus-tumor effect prediction.
Industry Challenges
- Cell Processing Technician Scarcity:Qualified personnel for aseptic manipulation of cellular products under current Good Manufacturing Practice protocols are concentrated in select metropolitan transplant hubs.
- Cryopreservation Supply Chain Fragility:Liquid nitrogen logistics and vapor-phase storage redundancy requirements create single-point-of-failure exposure for graft viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Marrow Transplant Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: AUTOGENOUS, ALLOGENEIC, UMBILICAL CORD BLOOD, STUMMEL CELL TRANSPLANT Indication: LEUKEMIA, LYMPHOMA, APLASTIC ANEMIA, MYELODYSPLASTIC SYNDROME End User: HOSPITALS, CLINICS, AMBULATORY SURGERY CENTERS, RESEARCH INSTITUTES Product Type: CONSUMABLES, INSTRUMENTS, SOFTWARE, SERVICES |
| Companies Covered | Novartis AG, Bristol Myers Squibb, Merck Millipore Corporation, STEMCELL Technologies, Gilead Sciences, Amgen, Abbott Laboratories, Sanofi-Aventis, Bluebird Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Marrow Transplant Market Emerging Trajectories
Cellular therapy manufacturing is separating into distinct operational models that privilege scale economies in centralized facilities over distributed hospital-based production, with regulatory frameworks accelerating this structural division.
Next-generation CAR constructs incorporating dual-targeting domains and armored receptor designs are bifurcating the competitive landscape between academic centers with in-house vector production capabilities and contract manufacturers serving multi-site hospital networks. Pediatric leukemia programs at institutions like St. Jude Children's Research Hospital and Memorial Sloan Kettering Cancer Center are adopting these platforms fastest, compressing development timelines for salvage therapy indications while marginalizing first-generation CD19 monotherapies.
The EU AI Act classification of patient-matching algorithms as high-risk AI systems is imposing validation documentation burdens on transplant registries that operate across European Economic Area jurisdictions. German and French centers are responding by segregating algorithmic decision-support tools from automated donor-selection workflows, while Swiss programs leverage Swissmedic's bilateral recognition agreements to maintain operational continuity.
Hospital procurement departments are unbundling cell processing consumables from equipment vendor contracts, creating direct purchasing relationships with Merck Millipore Corporation and competing suppliers for sterile filtration and cell separation media. This disintermediation is most advanced in United States academic medical centers with dedicated cellular therapy supply chain managers, where volume commitments are replacing bundled service agreements.
Bone Marrow Transplant Market Segmentation
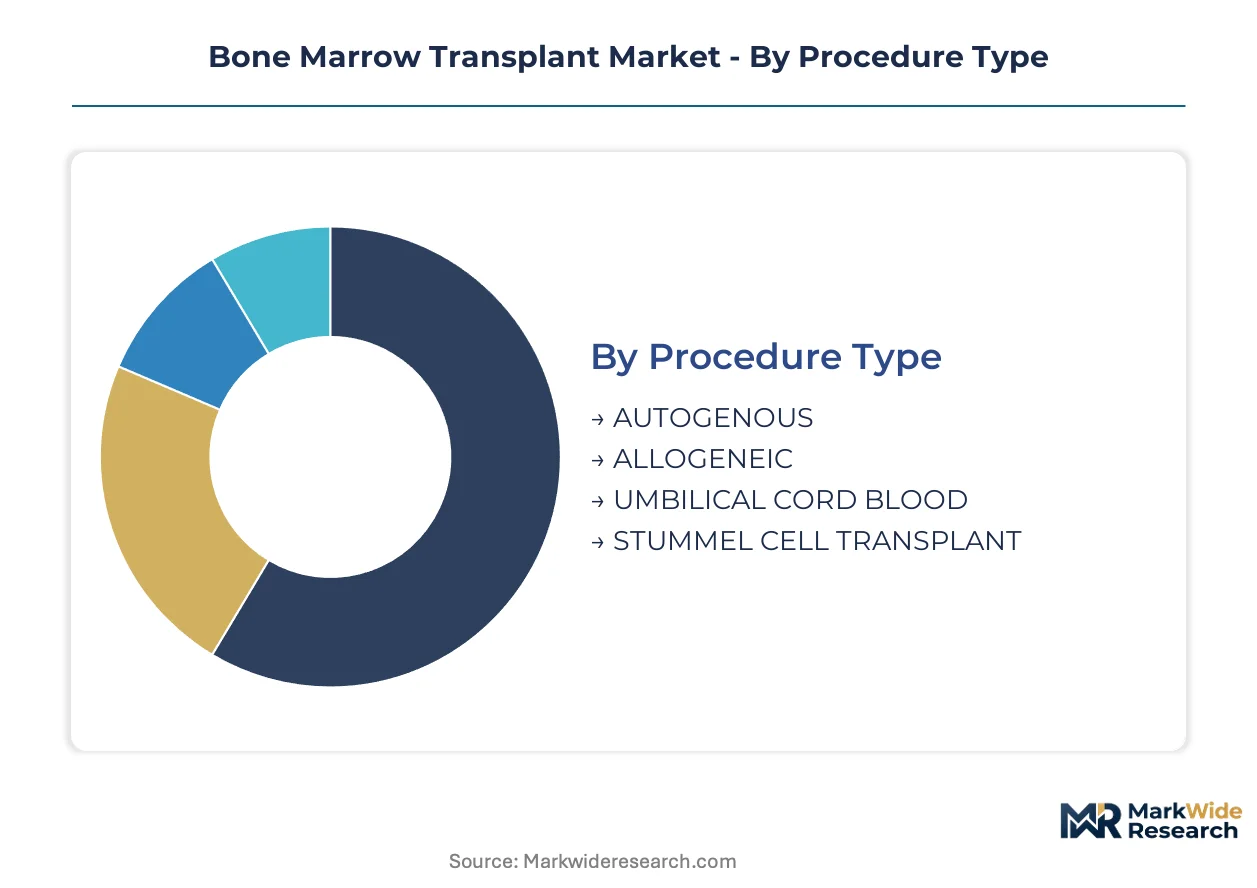
Segmentation in bone marrow transplant markets reveals how reimbursement tiers, facility certification requirements, and supply chain complexity concentrate margin pools across distinct operational models. Understanding these divisions helps stakeholders align capital deployment with the procedural volumes and regulatory burdens that define profitability in cellular therapy services.
Procedure Type:
Margin pools concentrate in allogeneic procedures where graft-versus-host disease management creates sustained pharmaceutical and monitoring revenue streams, while autologous volumes drive consumable throughput.
- Autologous:Patient-derived stem cells eliminate graft-versus-host disease risk and enable outpatient delivery models. Demand clusters in United States ambulatory surgery centers where same-day discharge protocols reduce inpatient DRG exposure and expand lymphoma case volumes.
- Allogeneic:Donor-sourced hematopoietic stem cells require HLA-matched registries and dedicated immunosuppression protocols. Complexity commands premium reimbursement tiers at tertiary care networks in Germany and Japan where graft-versus-tumor effect research deepens academic medical center concentration.
- Umbilical Cord Blood:Cryopreserved allografts from placental blood enable partial HLA mismatching with lower viral transmission risk. Inventory limitations constrain procedure scheduling at public cord blood banks.
- Stummel Cell Transplant:Emerging cellular platforms incorporate gene-modified stem cell populations for inherited disorder correction. Early-phase trials occupy pediatric centers with vector manufacturing partnerships.
Allogeneic holds installed capacity. Autologous is rotating up the share rankings.
Indication:
Clinical trial pipeline density varies sharply across hematologic malignancies, with leukemia commanding the deepest development resources and lymphoma expanding fastest into cost-sensitive delivery settings.
- Leukemia:Acute myeloid and lymphoblastic variants constitute the foundational indication for myeloablative transplant protocols. CAR-T salvage therapy approvals from FDA and EMA are redirecting relapsed pediatric cases toward cellular therapy centers with manufacturing capabilities.
- Lymphoma:Hodgkin and non-Hodgkin subtypes increasingly shift to reduced-intensity conditioning and outpatient autologous protocols. United States ambulatory surgery centers pilot same-day discharge for diffuse large B-cell cases, compressing reimbursement per procedure while expanding eligible patient pools.
- Aplastic Anemia:Bone marrow failure syndromes require allogeneic approaches with extended immunosuppression. Younger patient demographics concentrate demand at pediatric transplant centers.
- Myelodysplastic Syndrome:Clonal hematopoietic disorders in older populations drive reduced-intensity protocol adoption. Age-related comorbidity expansion is broadening transplant eligibility beyond historical cutoffs.
Lymphoma is climbing the fastest. Leukemia retains the deepest trial infrastructure.
End User:
Capital requirements and regulatory certification create tiered access to transplant service delivery, with hospital-based programs capturing complex cases and ambulatory settings absorbing standardized autologous volumes.
- Hospitals:Tertiary academic medical centers maintain FACT-JACIE accreditation for allogeneic and CAR-T services. CMS reimbursement structures and FDA manufacturing partnership requirements consolidate complex cases at United States hospital systems with dedicated cellular therapy units.
- Clinics:Community oncology practices historically referred transplant-eligible patients but now face referral pathway collapse toward academic hubs. Remaining clinic roles concentrate on pre-transplant evaluation and post-engraftment surveillance.
- Ambulatory Surgery Centers:United States sites pilot autologous lymphoma protocols with reduced-intensity conditioning. Cost structures favor same-day discharge but require proximity to hospital emergency infrastructure.
- Research Institutes:St. Jude Children's Research Hospital and similar institutions drive next-generation CAR construct development. Early-phase trial sponsorship depends on vector manufacturing capabilities and NIH funding access.
Hospitals hold accredited capacity. Ambulatory surgery centers are gaining share fastest.
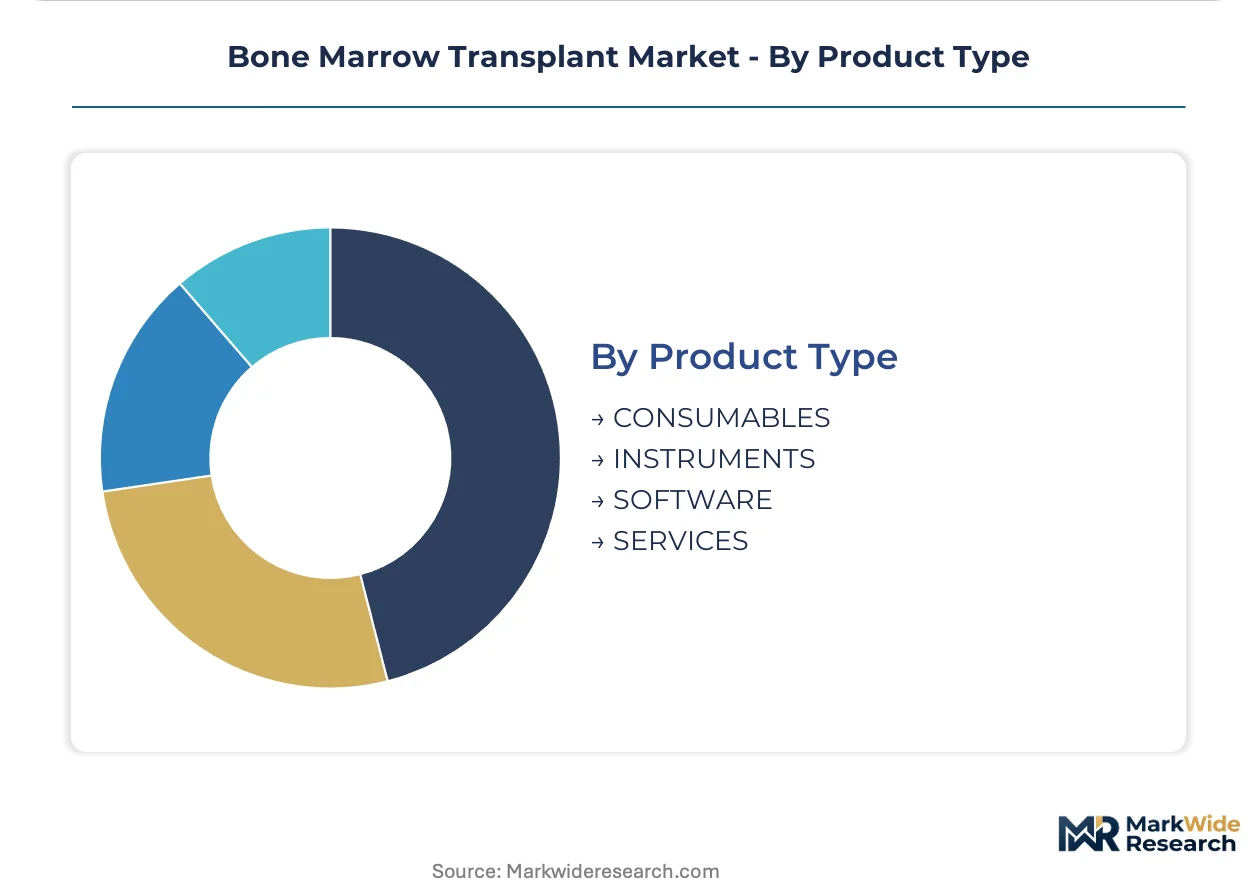
Product Type:
Supply chain configuration separates high-margin proprietary consumables from capital equipment with extended replacement cycles, while software and services capture recurring revenue through registry and data analytics subscriptions.
- Consumables:Sterile filtration media, cell separation reagents, and cryopreservation solutions constitute recurring procurement at transplant centers. Merck Millipore Corporation and competing suppliers are disintermediating equipment vendors through direct purchasing relationships with United States academic medical centers.
- Instruments:Apheresis machines, cell processing isolators, and vapor-phase cryostorage systems require cGMP-compliant infrastructure. Capital intensity limits replacement frequency to 7-10 year cycles.
- Software:Patient-matching algorithms and transplant registry platforms face EU AI Act compliance burdens for high-risk AI classification. German centers are segregating decision-support tools from automated workflows.
- Services:Contract manufacturing organizations and specialized logistics providers manage cryopreservation chain integrity. Liquid nitrogen logistics redundancy requirements create single-point-of-failure exposure.
Consumables dominate recurring procurement. Software is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The tertiary care networks of the United States, Germany, and Japan anchor bone marrow transplant service delivery through centralized cellular therapy hubs that consolidate complex case referrals and manufacturing partnerships.
United States
Academic medical centers in Boston, New York, and Houston drive autologous transplant volume expansion through CAR-T therapy protocols. FDA manufacturing partnership requirements channel patients into FACT-JACIE accredited facilities with sterile processing infrastructure. Memorial Sloan Kettering Cancer Center and St. Jude Children's Research Hospital anchor next-generation CAR construct development in pediatric leukemia.
Germany
Tertiary care consolidation across Bavaria and North Rhine-Westphalia concentrates allogeneic procedure complexity at university hospitals. EMA oversight of cellular therapy manufacturing through cGMP frameworks shapes facility capital requirements. German centers segregate algorithmic decision-support tools from automated donor-selection workflows to navigate EU AI Act compliance burdens.
Japan
PMDA regulatory clearances for CD19-directed therapies standardize referral protocols toward certified transplant centers. METI industrial policy supports domestic vector manufacturing capabilities. Tokyo and Osaka metropolitan hubs capture complex case volumes through dedicated cellular therapy units with cryopreservation logistics redundancy.
United Kingdom
NHS England specialized commissioning consolidates bone marrow transplant services at designated tertiary centers in London, Manchester, and Birmingham. MHRA alignment with EMA cGMP standards limits CAR-T program entry to well-capitalized hospital systems. London-based research institutes drive early-phase trial sponsorship for gene-modified stem cell platforms.
Switzerland
Swissmedic bilateral recognition agreements with EMA maintain operational continuity for transplant registries operating across European Economic Area jurisdictions. University Hospital Zurich and Geneva University Hospitals anchor reduced-intensity conditioning protocol development for older patient populations. Swiss programs leverage regulatory agility to pilot outpatient autologous delivery models.
Bone Marrow Transplant Market Vendor Landscape
Concentration sits with pharmaceutical conglomerates that control CAR-T manufacturing infrastructure and immunosuppressive portfolios. The market structure tiers between integrated cellular therapy developers, specialized consumable suppliers, and contract manufacturing organizations. Three archetypes dominate: vector production specialists, sterile processing consumable providers, and multi-site hospital network partners. Competitive moves center on manufacturing capacity expansion and direct purchasing relationship cultivation with academic medical center procurement departments.
Within the pharmaceutical conglomerate tier, Novartis AG and Bristol Myers Squibb occupy positions that exemplify divergent strategic emphases—one anchoring autologous CAR-T manufacturing scale, the other competing in allogeneic transplant support through broad immunosuppressive portfolios. Merck Millipore Corporation represents the consumable supply chain archetype, with direct purchasing relationships displacing bundled equipment vendor contracts at United States academic medical centers.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol Myers Squibb |
| Merck Millipore Corporation |
| STEMCELL Technologies |
| Gilead Sciences |
| Amgen |
| Abbott Laboratories |
| Sanofi-Aventis |
| Bluebird Bio |
| Others |
Supply Flow & Price Mechanics
Peripheral blood stem cell harvesting displacing bone marrow aspiration simultaneously redraws supply geography toward apheresis equipment clusters in the United States and Germany while compressing per-procedure procurement costs for transplant centers. This substitution dynamic concentrates sterile consumable demand at academic medical centers with dedicated cellular therapy supply chain managers who negotiate direct purchasing relationships.
Pricing Analysis
Volume-discount tiering structures separate FACT-JACIE accredited academic medical centers receiving preferential consumable rates from smaller hospital systems paying standard list prices for cell separation media and cryopreservation solutions. Price differentiation rests on cGMP certification status and annual procurement volume commitments to suppliers like Merck Millipore Corporation. Cost compression in autologous lymphoma protocols is intensifying because ambulatory surgery centers piloting same-day discharge models demand lower per-unit pricing. Community oncology practices exhibit highest price sensitivity due to collapsed referral pathways, while tertiary care networks with CAR-T manufacturing partnerships demonstrate lowest sensitivity given captive reimbursement tiers.
Supply Chain Analysis
Strategic-stockpile preferences dominate cryopreservation logistics where vapor-phase liquid nitrogen redundancy requirements mandate dual-sourced storage infrastructure rather than just-in-time delivery models. Geographic supply concentration centers on the United States, Germany, and Japan for apheresis equipment manufacturing and sterile processing consumables. Raw material dependencies encompass medical-grade liquid nitrogen, cell separation reagents, and gamma-sterilized filtration media. Single-source vulnerability pervades qualified cell processing technician pools concentrated in metropolitan transplant hubs. Distribution runs through direct purchasing relationships with academic medical center procurement departments displacing traditional equipment vendor bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as CAR-T therapy protocols splinter referral pathways away from community oncology networks toward specialized academic hubs, creating service gaps in post-engraftment surveillance and reduced-intensity conditioning patient management.
For Market Incumbents: Fortify manufacturing partnerships with FACT-JACIE accredited centers through exclusive consumable supply agreements that lock in multi-year procurement commitments. Expand sterile processing infrastructure in Germany and Japan to preempt EMA and PMDA capacity constraints. Vertical integration into vector production capabilities at pediatric leukemia centers counters contract manufacturer encroachment on next-generation CAR construct development. For New Entrants and Emerging Players: Post-engraftment remote monitoring services represent the most penetrable service-layer gap where incumbents under-serve ambulatory surgery center discharge protocols. Target United States autologous lymphoma cases shifting to outpatient settings by offering HIPAA-compliant registry analytics with automated graft-versus-host disease early warning algorithms. Go-to-market positioning emphasizes cost-per-procedure reduction through consumable bundle optimization rather than capital equipment sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors consumable supply chain specialists with direct academic medical center relationships over equipment manufacturers facing extended replacement cycles. Long-term viability hinges on regulatory certification durability across FDA, EMA, and PMDA jurisdictions. Acquisition target archetypes include contract manufacturing organizations with cGMP-compliant sterile processing infrastructure and established cryopreservation logistics redundancy. The signal to watch is CMS reimbursement recalibration for outpatient transplant delivery models crossing thresholds that validate ambulatory surgery center volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CAR-T cell therapy capacity expansion at FDA-certified facilities captures referral pathway consolidation. |
| Regulatory Approval Pathway | PMDA clearances for CD19-directed therapies standardize Japanese tertiary care network protocols. |
| Backward Integration | In-house vector production capabilities at pediatric centers compress next-generation construct development timelines. |
| Long-term Supply Agreement | Direct consumable purchasing relationships with Merck Millipore Corporation displace bundled equipment vendor contracts. |
| Reimbursement Strategy | CMS outpatient DRG recalibration for autologous lymphoma cases validates ambulatory surgery center expansion. |
Methodological Framework
Cross-validation between transplant center procurement managers and cellular therapy manufacturing executives anchors the qualitative findings on supply chain configuration shifts. Primary interviews encompassed apheresis unit directors, cell processing technicians, hospital supply chain managers, and GPO contract specialists across the United States, Germany, and Japan. Secondary validation drew from FDA BLA filings, EMA centralized procedure assessments, FACT-JACIE accreditation databases, and CMS Medicare cost report data. Bottom-up procedure volume modeling triangulated against top-down pharmaceutical revenue disclosures.
Sensitivity analysis tested forecast robustness across reduced-intensity conditioning adoption scenarios and outpatient transplant migration rates. Segmentation dimensions modeled encompassed procedure type, indication category, end-user facility tier, and regional regulatory cluster. CAGRs were derived from weighted least squares regression on historical procedure volumes with adjustments for CAR-T therapy cannibalization effects. Industry-specific inputs incorporated CD34+ cell dose yield distributions and graft-versus-host disease incidence rates by donor matching algorithm.
Material uncertainties — regulatory reimbursement recalibration, cryopreservation supply chain disruptions, and EU AI Act compliance burdens on patient-matching algorithms — sit outside the modeled envelope. Forecasts reflect assumptions on tertiary care network consolidation velocity and CAR-T manufacturing partnership stability. Revision becomes warranted when ambulatory surgery center same-day discharge protocols cross threshold adoption rates that materially shift inpatient-to-outpatient procedure mix.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hemoglobin Testing Systems Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Patient Blood Management Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Malignant Lymphoma Market
Hematology
Anemia Drugs Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
At-Home Hematology Testing Market
Hematology
Global Hematopoietic Stem Cell Transplantation Market
Hematology
Alpha Thalassemia Market
Hematology
Chronic Immune Thrombocytopenia Treatment Market
Hematology
Aplastic Anemia Treatment Market