
 Aplastic Anemia Treatment Market | 2026-2036
Aplastic Anemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Aplastic Anemia Treatment Market Outlook
Hospital end-user demand is restructuring as specialty clinics and home healthcare channels gain share for maintenance immunosuppression. Novartis AG leverages its transplant medicine portfolio to anchor positions in growth factor and immunosuppressant segments. Amgen Inc. sustains R&D intensity in biologic therapies for bone marrow failure syndromes. Pfizer Inc. competes through manufacturing scale across corticosteroid and supportive care formulations.
Aplastic anemia treatment encompasses therapeutic interventions targeting bone marrow failure characterized by pancytopenia, including immunosuppressive agents that modulate T-cell mediated hematopoietic destruction, growth factors that stimulate residual stem cell populations, and allogeneic bone marrow transplantation for severe or refractory cases. Immunosuppressants dominate current revenue pools as first-line therapy for non-severe patients ineligible for transplant, while bone marrow transplantation commands premium positioning for younger patients with matched donors. Injectable and intravenous delivery modes concentrate in hospital settings, whereas oral immunosuppressants extend into specialty clinic and home healthcare channels.
The FDA orphan drug program shapes developer incentives and exclusivity timelines for novel aplastic anemia therapies, while the EMA parallel track influences European market access and pediatric investigation requirements. ISO 14155 standards govern clinical trial conduct across jurisdictions, directly affecting evidence generation costs and approval timelines. Stakeholders must monitor evolving health technology assessment criteria for curative versus chronic therapy value propositions.
Market Dynamics
The FDA's orphan drug designation pathway is consolidating competitive incentives around novel immunosuppressive mechanisms and stem cell-based interventions, compressing development timelines for therapies targeting T-cell mediated bone marrow destruction.
Growth Catalysts
- EMA pediatric investigation mandates:The European Medicines Agency's pediatric investigation plan requirements for hematology products are accelerating clinical trial enrollment across pediatric aplastic anemia cohorts, expanding addressable patient populations.
- Home healthcare channel expansion:Oral immunosuppressant formulations are migrating into specialty clinic and home infusion settings, reducing hospital bed-day utilization while extending therapy adherence monitoring.
- Tertiary care center clustering:The United States exhibits concentrated treatment volume at academic medical centers with transplant capabilities, creating referral network density that streamlines patient access to curative interventions.
Market Restraints
- Matched donor scarcity:Allogeneic bone marrow transplantation remains constrained by human leukocyte antigen typing limitations, with sibling-matched donor availability falling below thirty percent in most populations.
- Biologic input cost volatility:Recombinant growth factor production depends on mammalian cell culture capacity, where contract manufacturing organization concentration in specific bioregions creates supply vulnerability.
- Immunosuppressant resistance mechanisms:Relapse rates following standard anti-thymocyte globulin and cyclosporine regimens limit durable remission achievement, compressing long-term therapy value propositions.
Strategic Opportunities
- Japan's regenerative medicine framework:The Pharmaceuticals and Medical Devices Agency's conditional approval pathway for stem cell products creates accelerated market access for novel hematopoietic stem cell gene therapies.
- Real-world evidence integration:Post-market surveillance databases capturing long-term immunosuppressant outcomes are enabling label expansion submissions without prospective trial requirements.
- Companion diagnostic co-development:Biomarker assays predicting immunosuppressant response are creating partnership opportunities between therapy developers and in vitro diagnostic manufacturers.
Industry Challenges
- Cell therapy manufacturing scale-up:Autologous stem cell product expansion requires specialized cleanroom infrastructure and trained apheresis coordination, limiting production throughput at existing transplant centers.
- Cross-border trial harmonization:Divergent ISO 14155 implementation across national competent authorities generates protocol amendment burdens, delaying multi-regional study initiation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aplastic Anemia Treatment Market |
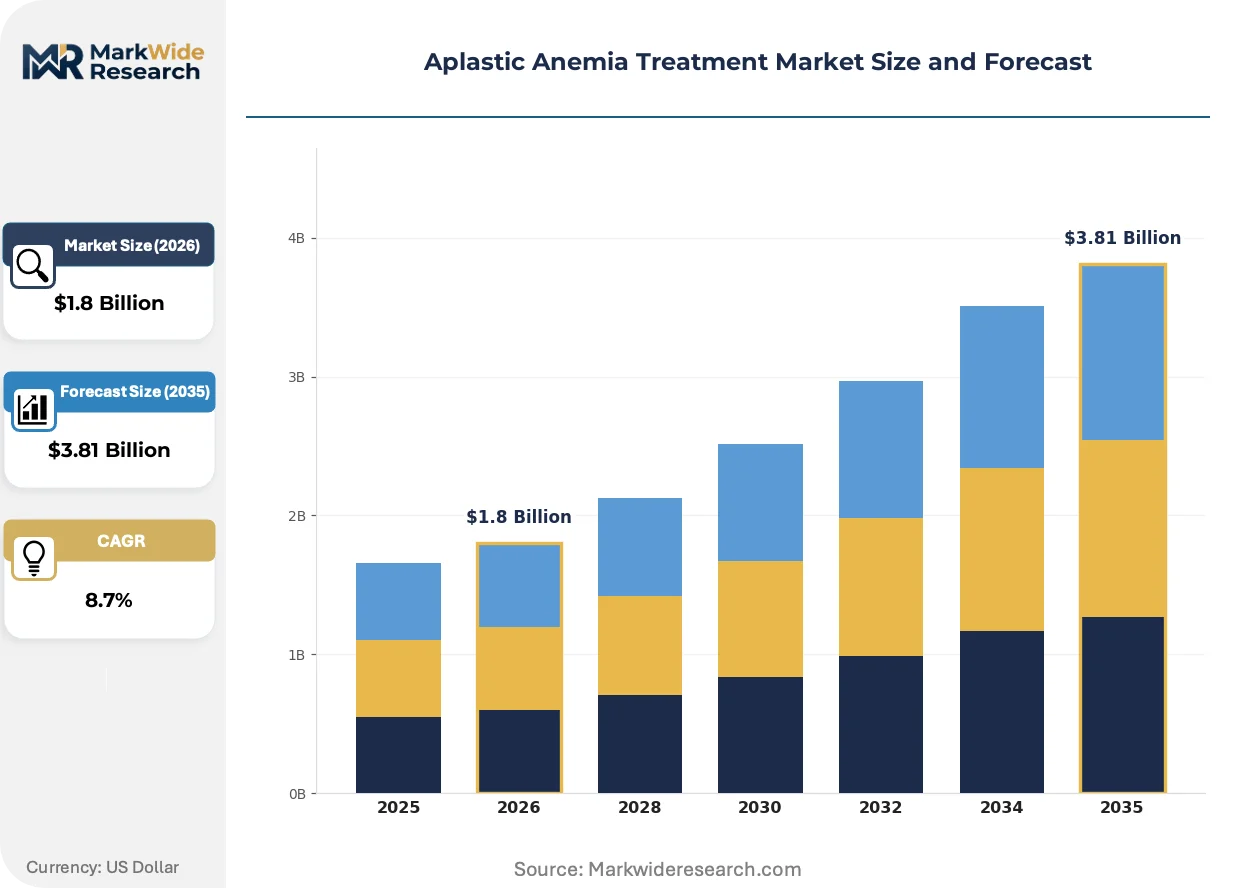
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Corticosteroids, Growth Factors, Bone Marrow Transplantation End User: Hospitals, Specialty Clinics, Home Healthcare, Research Laboratories Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous Therapy Area: Hematology, Oncology, Immunology, Palliative Care |
| Companies Covered | Novartis AG, Pfizer Inc., GlaxoSmithKline Plc., Amgen Inc., Kyowa Kirin Co., Ltd., Teva Pharmaceutical Industries Ltd., Sanofi S.A., F. Hoffmann-La Roche Ltd., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aplastic Anemia Treatment Market Strategic Shifts
Next-generation sequencing platforms are reshaping clonal evolution monitoring in aplastic anemia, enabling earlier detection of malignant transformation that alters therapeutic trajectories. These molecular surveillance capabilities intersect with evolving regulatory frameworks and shifting site-of-care preferences.
Chimeric antigen receptor T-cell engineering is consolidating around hematopoietic stem cell targets, with academic medical centers in the United States and Germany establishing dedicated manufacturing facilities for patient-specific cellular products. Hospital-based cell therapy units are absorbing capital allocation previously directed toward pharmaceutical inventory, compressing traditional drug distribution margins while creating captive supply chains for transplant centers.
The European Union's Medical Device Regulation is tightening in vitro diagnostic performance requirements for hematopoietic stem cell enumeration assays, forcing manufacturers to generate additional clinical validation data. German and French notified bodies are prioritizing review resources toward companion diagnostic submissions linked to orphan drug approvals, compressing timeline advantages previously held by standalone therapy applications.
Patient advocacy organizations are demanding expanded access programs for pre-approval therapies, pressuring manufacturers to establish managed access protocols outside formal clinical trial structures. United States-based tertiary care centers are negotiating direct-to-manufacturer agreements that bypass wholesale distribution for high-cost immunosuppressants, with similar patterns emerging at NHS England-designated specialized commissioning centers.
Aplastic Anemia Treatment Market Segmentation
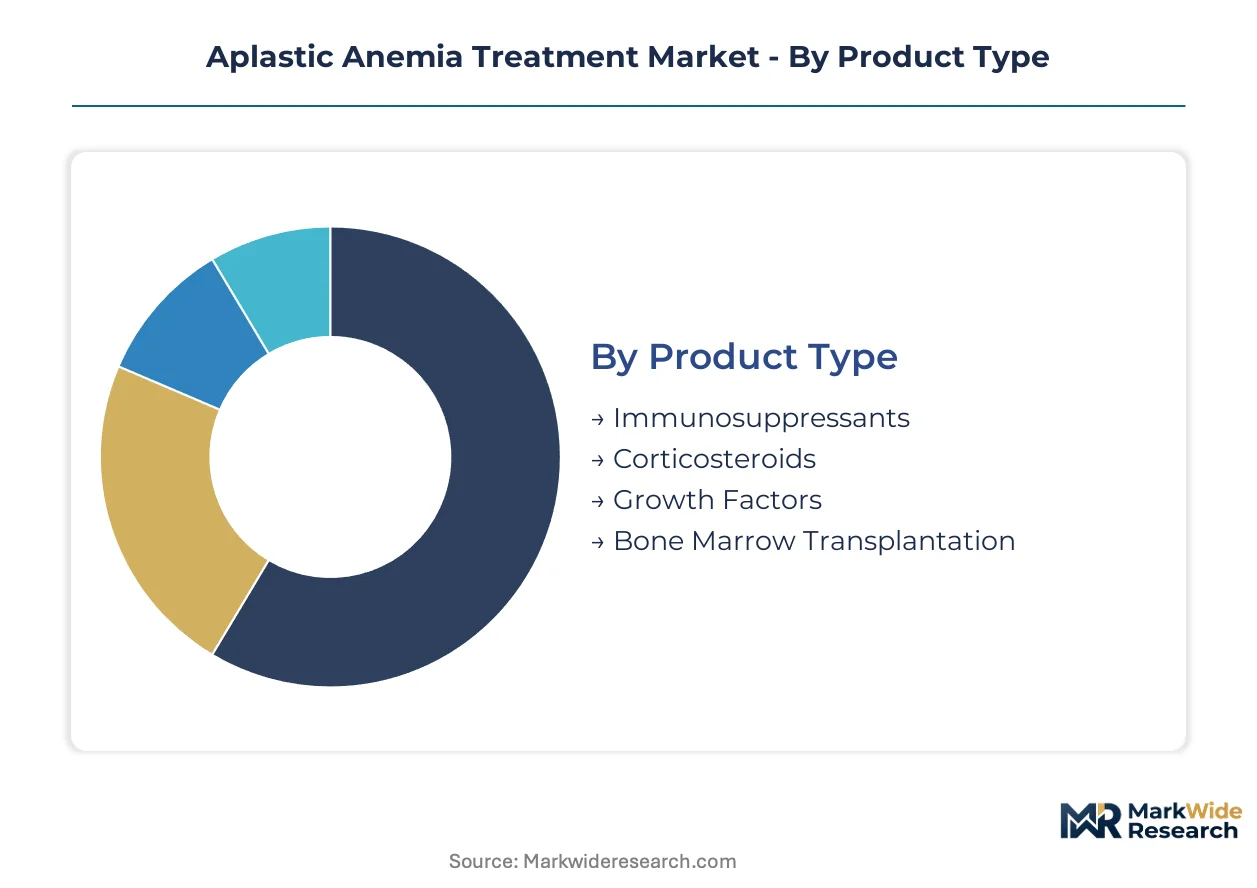
Treatment modality selection in aplastic anemia hinges on disease severity, patient age, and donor availability, with each segment demanding distinct manufacturing capabilities and distribution infrastructure. Segmentation reveals where capital deployment concentrates and which channels are capturing patient volume shifts.
Product Type:
Capital intensity varies sharply across mechanisms, with cellular therapies requiring specialized cleanroom investment while small-molecule manufacturing leverages existing chemical synthesis capacity.
- Immunosuppressants:Anti-thymocyte globulin and cyclosporine formulations constitute first-line intervention for transplant-ineligible patients. Demand clusters at tertiary hematology centers in the United States and Germany, where standardized protocols enable volume purchasing. Manufacturing scale advantages favor established pharmaceutical producers with mammalian cell culture infrastructure.
- Growth Factors:Recombinant erythropoietin and granulocyte colony-stimulating factor stimulate residual stem cell populations in moderate disease. Subcutaneous delivery compatibility positions this segment for home healthcare channel expansion, though cold chain requirements limit distributor options.
- Corticosteroids:Adjunctive therapy for immune modulation, manufactured through conventional chemical synthesis with lower barrier to entry.
- Bone Marrow Transplantation:Curative intervention requiring HLA-matched donors and specialized apheresis coordination at academic medical centers.
Immunosuppressants absorb the bulk of installed capacity; growth factors are expanding most quickly.
End User:
Site-of-care migration is redistributing revenue capture, with hospital dominance eroding as oral therapies enable outpatient management.
- Hospitals:Tertiary care centers anchor acute intervention delivery, housing transplant units and apheresis facilities. The United States maintains concentrated treatment volume at academic medical centers with FACT accreditation, where bundled payment structures incentivize protocol standardization.
- Specialty Clinics:Hematology-focused ambulatory settings capture maintenance immunosuppression administration. German and French networks are consolidating referral pathways to designated centers of excellence, compressing community hospital hematology service lines.
- Home Healthcare:Subcutaneous growth factor self-administration and oral cyclosporine regimens shift monitoring burden to telemedicine platforms.
- Research Laboratories:Academic and contract research organizations conduct biomarker validation and cell therapy process development.
Hospitals retain the highest revenue per patient episode; specialty clinics are gaining share fastest.
Delivery Mode:
Formulation technology determines distribution complexity and patient adherence profiles across the treatment continuum.
- Injectable:Parenteral immunosuppressant administration requires clinical supervision, anchoring hospital and infusion center utilization.
- Intravenous:High-dose regimens and stem cell products demand specialized nursing and monitoring infrastructure.
- Oral:Cyclosporine and eltrombopag tablets enable patient-managed chronic therapy with pharmacy benefit management integration.
- Subcutaneous:Growth factor pen devices support home administration with cold chain logistics managed through specialty pharmacy networks.
Intravenous delivery commands premium pricing; oral formulations are climbing the fastest.
Therapy Area:
Clinical positioning spans curative intent, disease modification, and supportive care, with reimbursement pathways diverging accordingly.
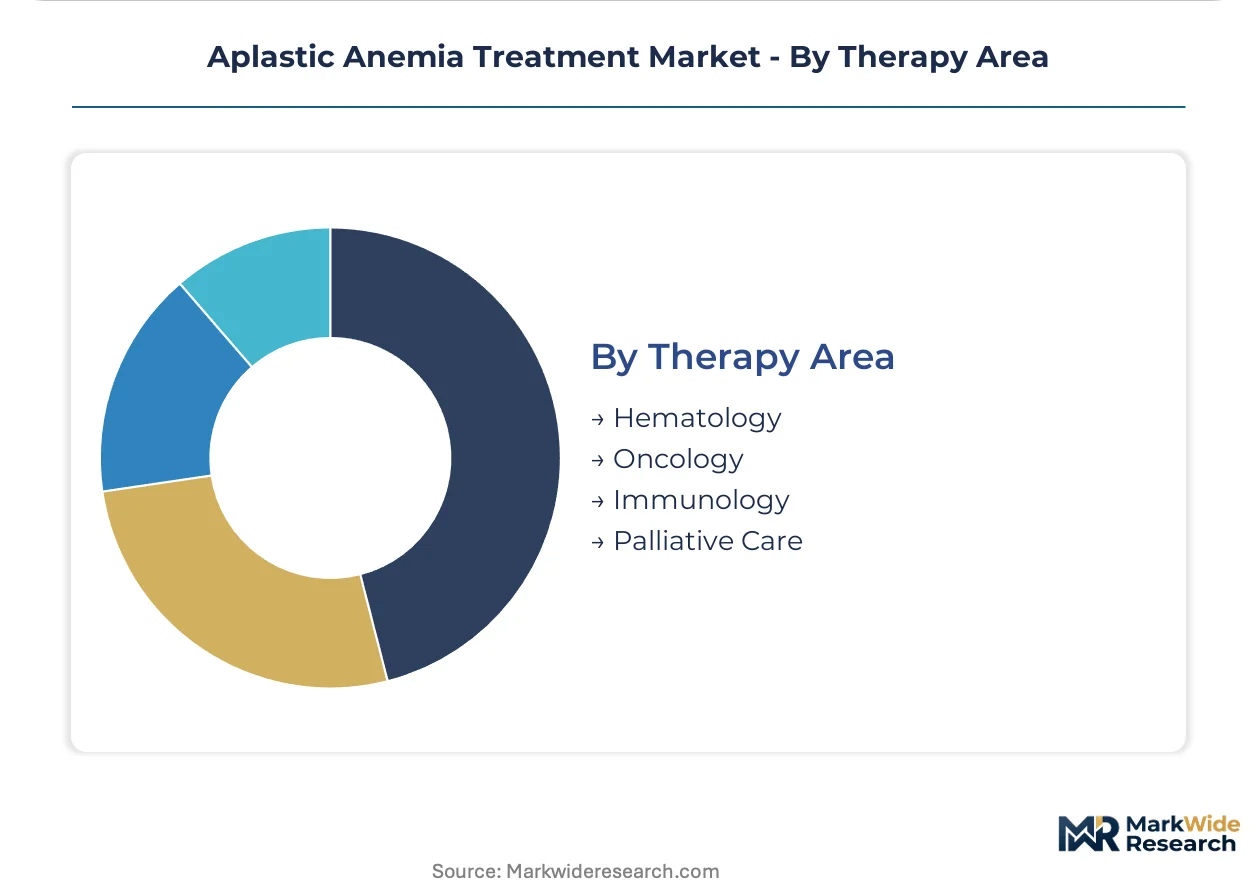
- Hematology:Core specialty managing bone marrow failure syndromes with integrated transplant and medical therapy protocols.
- Oncology:Overlap in clonal evolution monitoring and malignant transformation risk assessment.
- Immunology:T-cell mediated pathophysiology research drives novel mechanism investigation.
- Palliative Care:Symptom management for refractory cases and transplant-ineligible elderly populations.
Hematology coordinates the majority of treatment decisions; immunology is deepening its research investment most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for biomedical innovation in Singapore and Massachusetts concentrate cell therapy manufacturing infrastructure, attracting venture capital flows and regulatory fast-track designations that reshape competitive geography.
United States
Tertiary care centers at Johns Hopkins and Mayo Clinic anchor transplant volumes, with the FDA orphan drug designation compressing approval timelines for novel immunosuppressants. The 21st Century Cures Act provisions accelerate regenerative medicine pathways. Boston's Kendall Square biocluster houses contract manufacturing organizations serving apheresis-dependent therapies.
Germany
University hospitals in Heidelberg and Munich coordinate European reference networks for bone marrow failure syndromes, with the EMA centralized procedure streamlining pan-European market access. Germany's Hospital Structure Act reforms concentrate hematology services at designated centers of excellence. The Rhine-Main biotech corridor specializes in mammalian cell culture capacity for growth factor production.
Japan
PMDA's conditional approval pathway for regenerative medicine products accelerates stem cell therapy commercialization, with Tokyo and Osaka academic medical centers pioneering manufacturing protocols. The Act on Regenerative Medicine Safety establishes manufacturing quality standards. Kobe's biomedical innovation cluster hosts dedicated cleanroom facilities for autologous cell processing.
United Kingdom
NHS England's specialized commissioning framework concentrates aplastic anemia treatment at designated tertiary centers in London and Manchester, with NICE technology appraisals determining reimbursement for immunosuppressive regimens. The UK Rare Diseases Framework mandates coordinated care pathways. Cambridge's biotech cluster advances next-generation sequencing platforms for clonal evolution monitoring.
Switzerland
Swissmedic's parallel scientific advice procedures align with EMA timelines, while Basel's pharmaceutical corridor anchors European headquarters for immunosuppressant manufacturers. The country's bilateral agreements with the EU maintain market access continuity. Zurich's university hospital network maintains FACT-accredited transplant units serving cross-border patient flows.
Aplastic Anemia Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in biologic growth factors contrasting fragmented generic immunosuppressant supply. The vendor base organizes around three archetypes: integrated pharmaceutical conglomerates with transplant medicine portfolios, biologic-focused innovators with mammalian cell culture capabilities, and regional generic manufacturers serving cost-sensitive maintenance therapy. Capacity expansion and strategic partnerships dominate competitive moves, with academic medical centers negotiating direct supply agreements that bypass traditional wholesale channels.
Within the integrated pharmaceutical tier, Novartis AG and Pfizer Inc. occupy positions exemplifying scale-driven manufacturing advantages across immunosuppressant and supportive care formulations. Amgen Inc. represents the biologic innovation archetype, with its naming convention signaling mammalian cell culture specialization. These three entities anchor the competitive structure, with their geographic distribution across Swiss, American, and California-based headquarters reflecting the industry's regulatory and capital access patterns.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| GlaxoSmithKline Plc. |
| Amgen Inc. |
| Kyowa Kirin Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Captive biologics manufacturing by Novartis AG and Amgen Inc. anchors supply positions and pricing power in the aplastic anemia treatment market, with in-house mammalian cell culture capacity insulating against contract manufacturing organization volatility while supporting premium positioning for growth factor and immunosuppressant portfolios.
Pricing Analysis
Short lead-time premiums for apheresis-coordinated stem cell products contrast with spot inventory discounts for oral immunosuppressants in chronic maintenance settings. Three-tier pricing structure across premium, standard, and economy levels reflects FACT accreditation status and cold chain reliability rather than molecule differentiation alone. Cost compression in generic cyclosporine is intensifying because Indian and Chinese API manufacturers are expanding fermentation capacity. Hospital procurement committees exhibit highest price sensitivity for supportive care corticosteroids, while transplant centers accept premium pricing for matched-donor logistics coordination.
Supply Chain Analysis
Domestic-content mandates in Japan's Act on Regenerative Medicine Safety are reshaping sourcing patterns for autologous cell therapy processing equipment. Manufacturing concentrates in Switzerland, the United States, and Japan for immunosuppressant active pharmaceutical ingredients and growth factor bioreactor capacity. Recombinant protein production rests on Chinese hamster ovary cell lines, specialized filtration membranes, and single-use bioreactor bags. Single-source vulnerability permeates the apheresis device segment, where Fresenius Kabi and Haemonetics control global installed base. Distribution runs through hospital-owned specialty pharmacies and integrated delivery networks with direct manufacturer agreements bypassing wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aplastic anemia treatment market sits in a technology-transition phase as chimeric antigen receptor T-cell engineering displaces standard immunosuppressive regimens for relapsed cases.
For Market Incumbents: To counter biosimilar erosion in erythropoietin markets, Novartis AG and Amgen Inc. should deepen backward integration into plasmid DNA supply and expand cleanroom capacity at Singapore and Massachusetts bioclusters. Securing companion diagnostic partnerships for eltrombopag response prediction creates formulary stickiness against generic cyclosporine substitution. For New Entrants and Emerging Players: Gene-edited hematopoietic stem cell platforms offer the most penetrable wedge for specialty biotechnology firms, with Japan's PMDA conditional approval pathway providing accelerated market access for academic spinouts. Targeting home healthcare channels for subcutaneous growth factor formulations bypasses entrenched hospital formulary control. Go-to-market execution should prioritize direct-to-transplant-center contracting with telemedicine adherence monitoring bundles. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisition by integrated pharmaceutical conglomerates seeking transplant medicine verticals, with cell therapy manufacturing capabilities commanding valuation premiums. Long-term viability over the coming decade hinges on successful commercialization of allogeneic off-the-shelf products eliminating donor-matching constraints. The signal to watch is FDA breakthrough therapy designation frequency for T-cell engagers in bone marrow failure syndromes.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA's seven-year exclusivity accelerates novel immunosuppressant development timelines and reimbursement negotiations. |
| Companion Diagnostic Co-Development | Biomarker partnerships with Roche and Abbott Laboratories enable precision positioning for eltrombopag responders. |
| Cell Therapy Manufacturing Scale-Up | Specialized cleanroom investment at academic medical centers creates captive supply chains for transplant volumes. |
| Real-World Evidence Infrastructure | Post-market surveillance databases support label expansion without prospective trial costs for maintenance indications. |
| Home Healthcare Channel Integration | Specialty pharmacy partnerships for oral cyclosporine reduce hospital bed-day utilization while extending adherence capture. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hematology department heads, transplant center procurement managers, regulatory affairs leads at biologics manufacturers, and payer access specialists at Medicare Advantage plans. FDA orphan drug designations, EMA centralized procedure submissions, ClinicalTrials.gov enrollment data, and hospital formulary databases provided validation triangulation against bottom-up patient volume estimates and top-down pharmaceutical revenue segmentation.
Data-stream reconciliation across the projection horizon applied patient-flow modeling by disease severity tier, treatment line positioning, and regional regulatory cluster. Segmentation dimensions included immunosuppressant mechanism class, delivery mode, end-user site-of-care, and curative versus chronic intent. CAGRs derived from log-linear trend fitting to historical procedure volumes and therapy pricing indices, with sensitivity analysis around matched-donor availability assumptions and biosimilar entry timing for growth factor markets.
Several conditions sit outside the modeled scope, including gene therapy reimbursement determination by CMS and NICE, clonal evolution to myelodysplastic syndrome altering therapeutic trajectories, and unforeseen manufacturing contamination events at single-source bioreactor facilities. Forecasts reflect documented assumptions regarding immunosuppressant resistance rates and stem cell graft success benchmarks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hematopoietic Agents Market
Hematology
Blood Plasma Market
Hematology
Apheresis Market
Hematology
Venous Blood Collection Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Sickle Cell Treatment Market
Hematology
Anemia Drugs Market
Hematology
Hematology Analyzers Market
Hematology
Haematocrit Centrifuge Market
Hematology
Alpha Thalassemia Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market