
 Blood Disorder Therapeutics Market | 2026-2036
Blood Disorder Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Disorder Therapeutics Market Outlook
A capital-intensity divergence between plasma fractionation specialists and recombinant biologic developers is reorganizing competitive hierarchy in blood disorder therapeutics. Pfizer Inc leverages its global manufacturing footprint to sustain immunoglobulin supply security across multiple hemophilia markets. Novo Nordisk A/S anchors its position through recombinant factor VIII and IX leadership, while CSL Ltd competes via vertically integrated plasma collection networks spanning North America and Europe.
Blood disorder therapeutics encompass pharmaceutical and biological interventions targeting coagulation deficiencies, hemoglobinopathies, and bone marrow failure syndromes, typically requiring cold-chain distribution and parenteral administration with precise dosing calibrated to patient weight and factor levels. These therapies prevent hemorrhagic events, reduce transfusion dependence, and modify disease progression in inherited and acquired hematologic conditions. Monoclonal antibodies directed against platelet destruction pathways command premium positioning in immune thrombocytopenia, while intravenous immunoglobulin maintains mature volume leadership across neurologic and hematologic indications. Subcutaneous delivery modes are gaining fastest traction among hemophilia patients seeking prophylaxis independence from infusion center schedules.
FDA orphan drug designations and EMA PRIME eligibility criteria shape clinical trial investment and market exclusivity timelines for novel hemophilia gene therapies. REACH compliance and EU MDR requirements govern plasma-derived product traceability and viral safety documentation across European distribution channels. Stakeholders must monitor emerging biosimilar competition in factor replacement therapy and evolving payer evidence requirements for curative versus chronic treatment paradigms.
Market Dynamics
Plasma collection capacity constraints and recombinant biologic manufacturing scale-up are creating a bifurcated supply architecture in blood disorder therapeutics, with fractionation specialists competing against cell-culture producers for hospital formulary placement.
Growth Catalysts
- FDA orphan drug designation:Accelerated approval timelines for hemophilia gene therapies compress development cycles and extend market exclusivity periods for novel biologics.
- Subcutaneous prophylaxis:Extended half-life factor concentrates enable home-based administration, reducing infusion center dependence among adolescent hemophilia patients.
- Japan's specialized bleeding disorder centers:Concentrated treatment infrastructure generates predictable demand volumes and supports real-world evidence collection for novel therapies.
Market Restraints
- Plasma supply volatility:Donor availability fluctuations and collection center capacity limits create raw material bottlenecks for immunoglobulin and albumin production.
- EMA MDR compliance costs:Enhanced viral safety documentation and traceability requirements impose substantial regulatory burden on plasma-derived product manufacturers.
- Gene therapy durability uncertainty:Long-term expression persistence remains unproven, constraining payer willingness to fund curative versus chronic treatment models.
Strategic Opportunities
- Germany's outpatient infusion networks:Underpenetrated community-based prophylaxis administration creates channel expansion potential beyond hospital-based hematology departments.
- Non-factor replacement modalities:Bispecific antibodies and siRNA therapeutics open addressable markets in patients with factor inhibitors.
- US IRA price negotiation provisions:Exclusion of orphan-designated biologics from Medicare price controls preserves pricing autonomy for rare disease developers.
Industry Challenges
- Cold-chain logistics certification:GDP compliance for temperature-sensitive biologics requires specialized warehousing infrastructure and validated distribution partnerships.
- Gene therapy manufacturing scale-up:Viral vector production capacity constraints limit batch sizes and create supply-demand mismatches for approved therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Disorder Therapeutics Market |
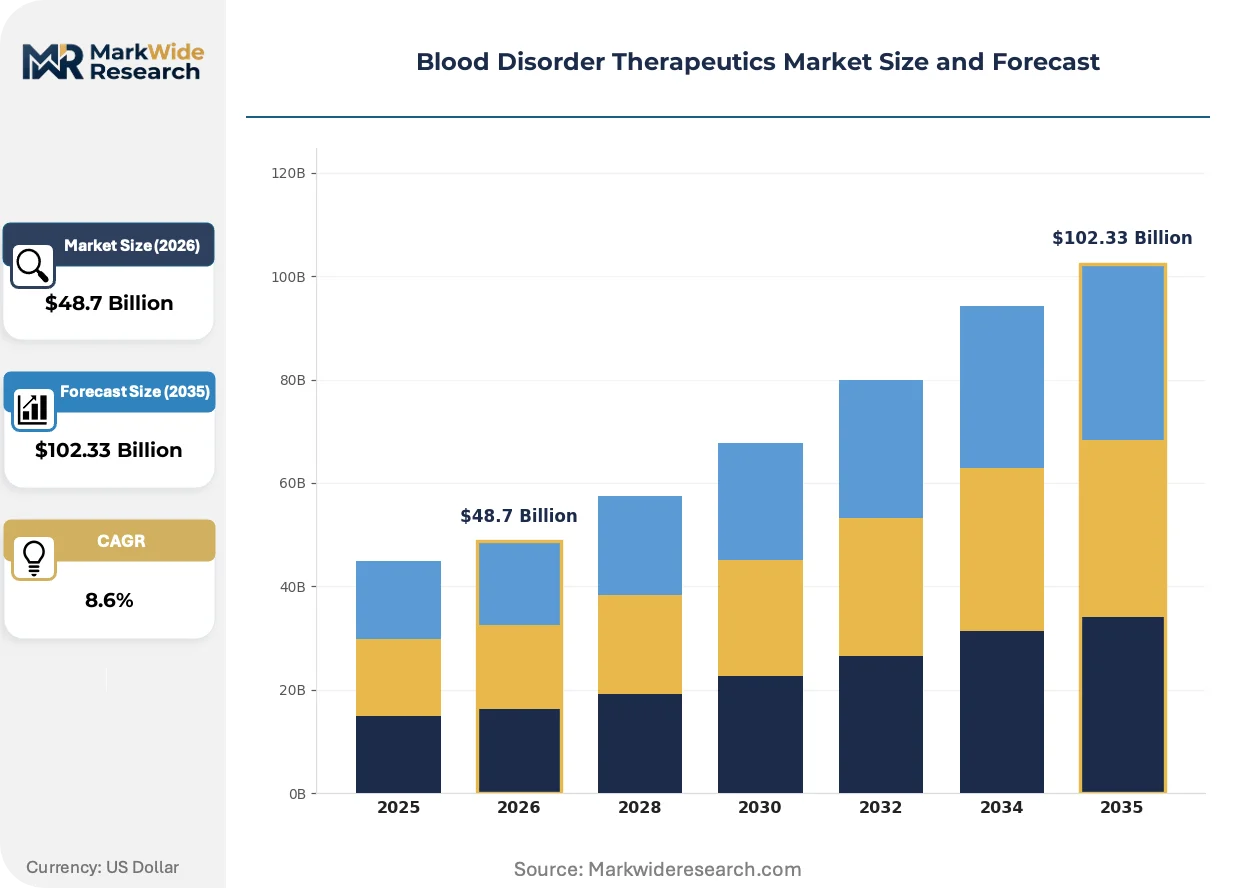
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Intravenous Immunoglobulin, Blood Transfusion, Platelet Growth Factors Therapy Area: Hemophilia, Sickle Cell Disease, Thalassemia, Aplastic Anemia Delivery Mode: Subcutaneous, Intravenous, Oral, Intramuscular End User: Hospitals, Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Pfizer Inc, CSL Ltd, Takeda Pharmaceutical Company Limited, Octapharma, Grifols S.A., Novo Nordisk A/S, Sanofi, Bristol-Myers Squibb Company, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Disorder Therapeutics Market Strategic Shifts
Digital therapeutic integration and patient-reported outcome capture are reconfiguring how hemophilia treatment centers measure prophylaxis effectiveness and justify therapy selection to payers.
Gene therapy delivery platforms are fragmenting traditional factor replacement market segments by offering single-administration alternatives to lifelong infusion regimens. Adult hemophilia patients with severe disease phenotypes are enrolling in gene transfer trials at accelerating rates. This adoption pattern is compressing addressable volumes for recombinant factor VIII and IX products in the United States and Western Europe.
EMA PRIME eligibility criteria are compressing clinical development timelines for breakthrough-designated hematologic therapies. Accelerated assessment pathways reduce regulatory review periods from twelve to seven months. Gene therapy developers targeting hemophilia A and B are prioritizing European market entry to leverage these procedural advantages.
Home infusion training programs are displacing hospital-based prophylaxis administration as the default care model for adolescent hemophilia patients. Specialty pharmacy networks and home health nursing services are capturing service revenue previously retained by hospital outpatient departments. This channel migration is most pronounced in the United States, where payer pressure to reduce site-of-care costs coincides with patient preference for treatment schedule autonomy.
Blood Disorder Therapeutics Market Segmentation
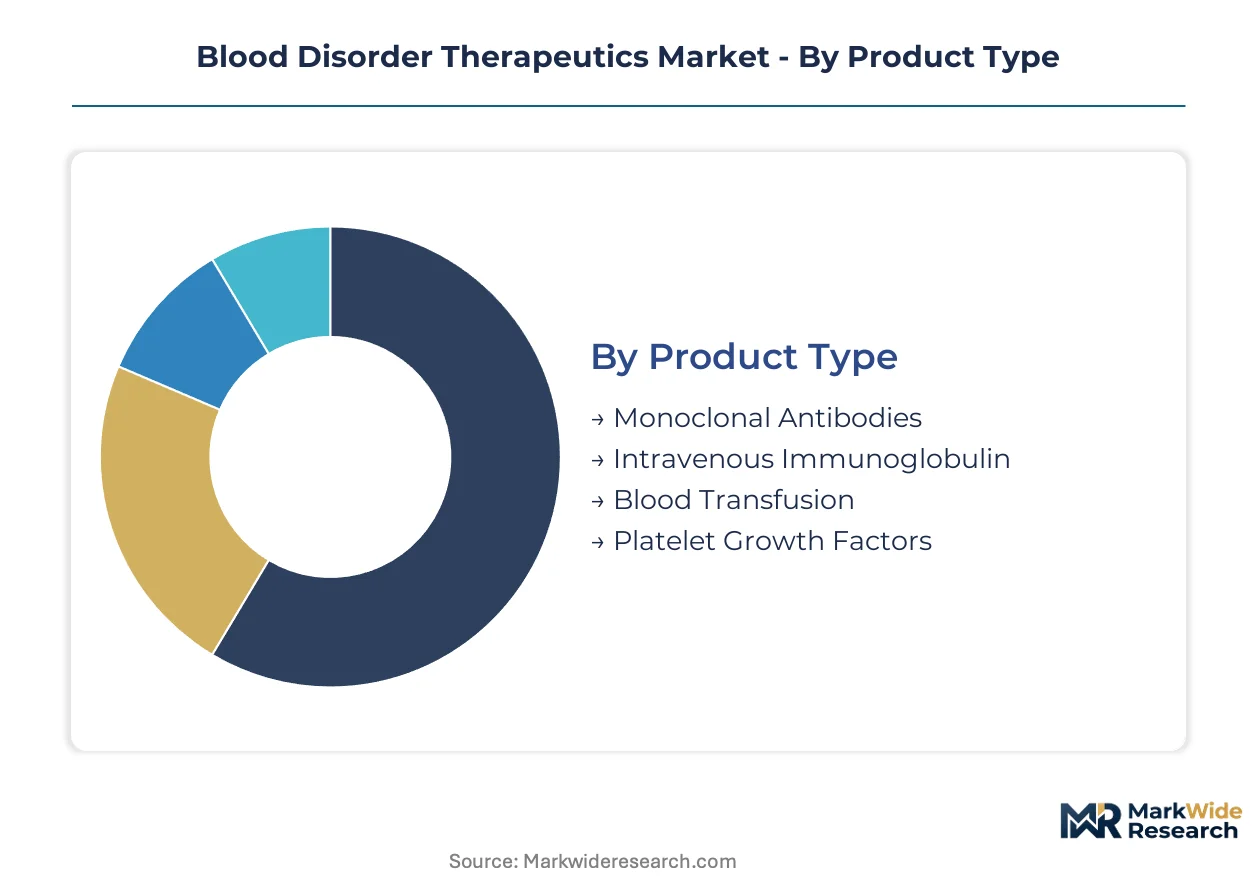
Blood disorder therapeutics flow through distinct channel architectures that reshape how manufacturers configure product portfolios. Segmentation reveals where formulation investments align with site-of-care economics and patient autonomy preferences.
Product Type:
Hospital formularies stock these products through divergent procurement channels — biologics via specialty pharmacy networks, plasma-derived therapies through blood bank contracts, and transfusion products via centralized hospital supply chains.
- Monoclonal Antibodies:Engineered immunoglobulins targeting platelet destruction pathways in immune thrombocytopenia. Demand concentrates in US academic medical centers where prior authorization requirements favor documented bleeding reduction metrics over cost minimization.
- Intravenous Immunoglobulin:Polyclonal antibody preparations fractionated from pooled human plasma for immunomodulation. Germany's outpatient infusion networks are expanding home-based administration, displacing hospital-based delivery for neurologic and hematologic indications.
- Blood Transfusion:Cellular and plasma components for acute hemorrhage management. Procurement runs through regional blood center consortia with FDA-mandated donor traceability.
- Platelet Growth Factors:Recombinant thrombopoietin receptor agonists stimulating megakaryocyte proliferation. Oncology supportive care units in Japan's specialized bleeding disorder centers generate predictable demand volumes.
Intravenous immunoglobulin dominates installed base. Monoclonal antibodies are where expansion concentrates.
Therapy Area:
Development pipelines and reimbursement pathways diverge sharply across these indications, with gene therapy investments clustering in hemophilia while small-molecule innovation targets hemoglobinopathies.
- Hemophilia:Coagulation factor replacement and gene transfer therapies for congenital factor VIII or IX deficiency. Subcutaneous prophylaxis adoption is climbing fastest among adolescent patients in US home care settings seeking schedule autonomy.
- Sickle Cell Disease:Disease-modifying agents targeting hemoglobin polymerization and vaso-occlusive crisis prevention. Medicaid-managed care plans in US southeastern states are expanding access to disease-modifying therapies with curative intent.
- Thalassemia:Iron chelation and transfusion support for hemoglobin synthesis disorders. Blood bank partnerships in Mediterranean-climate countries sustain chronic transfusion program infrastructure.
- Aplastic Anemia:Immunosuppressive regimens and stem cell transplantation for bone marrow failure. Tertiary referral centers in Japan concentrate diagnostic expertise and allogeneic donor matching capabilities.
Hemophilia commands development investment. Sickle cell disease is gaining share fastest.
Delivery Mode:
Route selection determines cold-chain complexity, nursing labor requirements, and patient adherence economics across reimbursement environments.
- Subcutaneous:Extended half-life factor concentrates and monoclonal antibodies enabling self-administration. US specialty pharmacy networks are capturing service revenue from hospital outpatient departments through home infusion training programs.
- Intravenous:Standard half-life factors, immunoglobulin, and cellular products requiring vascular access. EMA MDR compliance costs for viral safety documentation constrain European plasma-derived product distribution.
- Oral:Small-molecule iron chelators and anticoagulants for chronic outpatient management. Payer preference for site-of-care cost reduction favors oral alternatives where bioequivalence permits.
- Intramuscular:Emergency coagulation factor administration and hematinics in acute care settings. Hospital emergency departments retain this route for rapid reversal of hemorrhagic events.
Intravenous delivery dominates transaction volume. Subcutaneous administration shows steepest expansion trajectory.
End User:
Site-of-care migration is redistributing service revenue and inventory ownership across institutional and ambulatory channels.
- Hospitals:Acute bleeding management, surgical prophylaxis, and gene therapy administration. Hematology departments in US academic centers anchor regional referral networks for complex coagulation disorders.
- Clinics:Outpatient factor infusion and monitoring for stable chronic patients. Germany's community-based prophylaxis networks remain underpenetrated relative to hospital-based alternatives.
- Home Care:Self-administered prophylaxis with nursing support and remote monitoring. Payer pressure to reduce site-of-care costs coincides with patient preference for treatment schedule independence in US markets.
- Rehabilitation Centers:Post-hemorrhagic joint recovery and physical therapy for hemophilia patients. Long-term orthopedic outcomes data collection supports real-world evidence generation for novel therapies.
Hospitals retain acute intervention dominance. Home care is where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's outpatient infusion networks exhibit the highest price elasticity among developed markets, while Japan's specialized bleeding disorder centers demonstrate inelastic demand anchored by concentrated treatment infrastructure and predictable reimbursement.
United States
Medicaid-managed care plans in southeastern states are expanding access to disease-modifying therapies with curative intent. FDA orphan drug designation compresses development cycles and extends market exclusivity for novel hemophilia gene therapies. Academic medical centers in Boston and the Research Triangle anchor regional referral networks for complex coagulation disorders.
Germany
Community-based prophylaxis networks remain underpenetrated relative to hospital-based alternatives, creating channel expansion potential. EMA MDR compliance costs for viral safety documentation constrain plasma-derived product distribution. Outpatient infusion networks in Bavaria and North Rhine-Westphalia are displacing hospital-based delivery for neurologic and hematologic indications.
Japan
Specialized bleeding disorder centers generate predictable demand volumes and support real-world evidence collection for novel therapies. PMDA accelerated assessment pathways reduce regulatory review periods for breakthrough-designated hematologic therapies. Tertiary referral centers in Tokyo and Osaka concentrate diagnostic expertise and allogeneic donor matching capabilities for aplastic anemia.
United Kingdom
NHS England's specialized commissioning framework concentrates hemophilia treatment in designated hemophilia comprehensive care centers. MHRA recognition of EMA marketing authorizations streamlines post-Brexit regulatory pathways for plasma-derived products. London and Manchester anchor regional networks for gene therapy administration and patient monitoring.
India
CDSCO fast-track approvals for orphan biologics are shortening time-to-market for recombinant factor concentrates. Government hospital blood banks in Maharashtra and Gujarat sustain chronic transfusion program infrastructure for thalassemia patients. Mumbai and Ahmedabad cluster plasma collection operations and fractionation partnerships.
Blood Disorder Therapeutics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in blood disorder therapeutics. Recombinant biologic developers command premium positioning through extended half-life factor engineering, while plasma fractionation specialists compete on immunoglobulin supply security and viral safety documentation. The market structures around three archetypes: vertically integrated plasma collectors, recombinant factor specialists, and diversified pharmaceutical conglomerates with hematology franchises. Dominant competitive moves include M&A to secure plasma collection networks and strategic partnerships for gene therapy viral vector manufacturing.
Among the plasma-derived therapy specialists, CSL Ltd, Octapharma, and Grifols S.A. occupy positions defined by collection infrastructure scale and geographic reach. Within the recombinant biologic tier, Novo Nordisk A/S and Sanofi exemplify factor replacement leadership through half-life extension technologies. Pfizer Inc and Bayer AG sit within the diversified pharmaceutical archetype, leveraging global manufacturing footprints to sustain supply security across multiple hemophilia markets.
| Leading Market Players |
|---|
| Pfizer Inc |
| CSL Ltd |
| Takeda Pharmaceutical Company Limited |
| Octapharma |
| Grifols S.A. |
| Novo Nordisk A/S |
| Sanofi |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation scale economies in the United States and Germany anchor price floors for immunoglobulin and albumin products, while recombinant biologic manufacturing scale-up in Switzerland and Denmark compresses margins for factor replacement therapies through competing supply architectures.
Pricing Analysis
Home infusion training and nursing support contracts drive lifetime value capture for hemophilia prophylaxis providers. Three-tier pricing structure across premium, standard, and economy levels separates extended half-life recombinant factors from standard half-life alternatives and plasma-derived equivalents. Cost compression in plasma-derived immunoglobulin intensifies because donor availability constraints limit collection economics. Medicaid-managed care plans in US southeastern states exhibit highest price sensitivity; Japan's specialized bleeding disorder centers demonstrate lowest elasticity due to concentrated infrastructure and predictable reimbursement.
Supply Chain Analysis
Cold-chain GDP certification for temperature-sensitive biologics creates distribution chokepoints between fractionation facilities and hospital formularies. Plasma collection draws from the United States, Germany, and Austria; recombinant biologic production centers on Denmark, Switzerland, and Belgium. Viral vector manufacturing capacity for gene therapies rests on specialized contract development organizations in Massachusetts and North Carolina. Single-source vulnerability in plasma collection networks constrains immunoglobulin supply security. Distribution runs through specialty pharmacy networks for home-based administration and hospital blood bank contracts for acute care delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral vector manufacturing capability scarcity defines competitive positioning in gene therapy development, with batch size constraints limiting supply security for curative hemophilia treatments.
For Market Incumbents: Consolidate plasma collection network ownership in the United States and Central Europe to secure immunoglobulin raw material access against donor availability volatility. Lock in viral vector manufacturing partnerships with CDMOs in Massachusetts and North Carolina before capacity allocation tightens further. Gene therapy durability uncertainty threatens factor replacement volumes; backward integration into gene therapy manufacturing preserves optionality. For New Entrants and Emerging Players: Lead with bispecific antibody and siRNA modalities targeting inhibitor patients excluded from standard factor replacement therapy. Germany's community-based prophylaxis networks remain underpenetrated relative to hospital-based alternatives, offering channel expansion potential with lower competitive density. Partner with US specialty pharmacy networks for home infusion training revenue capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plasma fractionation specialists with captive collection networks and long-term hospital blood bank contracts. Five-to-ten year viability favors vertically integrated players with immunoglobulin supply security over pure-play gene therapy developers facing durability questions. Monitor EMA gene therapy approval velocity as inflection indicator for factor replacement market compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | CSL Ltd and Grifols S.A. secure donor base access in the United States and Germany against supply volatility. |
| Gene Therapy Viral Vector Partnership | Novo Nordisk A/S and Sanofi lock in CDMO capacity in Massachusetts for hemophilia A and B programs. |
| Subcutaneous Formulation Development | Extended half-life factor engineering enables home administration and displaces hospital-based prophylaxis. |
| Specialty Pharmacy Network Integration | Pfizer Inc captures service revenue from hospital outpatient departments through home infusion training. |
| EMA PRIME Eligibility Pursuit | Accelerated assessment pathways compress regulatory review from twelve to seven months for breakthrough therapies. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions for plasma-derived and recombinant biologic demand trajectories. Primary interviews combined with secondary validation from FDA orphan drug filings, EMA PRIME submissions, ClinicalTrials.gov enrollment data, and hospital formulary databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include therapy area, product type, delivery mode, and end-user channel across the analysis window. CAGRs derived from treatment penetration curves, pricing trajectory assumptions, and regulatory approval timing. Forecast inputs incorporated gene therapy durability uncertainty, plasma collection capacity constraints, and site-of-care migration from hospital to home administration.
The analysis sits within stated boundaries; outcomes outside FDA and EMA approval timelines, plasma donor availability trends, and gene therapy long-term expression data would require recalibration. Practitioners should keep alternative scenarios live as payer evidence requirements for curative versus chronic treatment models evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Follicular Lymphoma Treatment Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Sickle Cell Treatment Market
Hematology
Hematology Analyzers Market
Hematology
Rare Hematology Market
Hematology
Thalassemia Treatment Market
Hematology
Multiple Myeloma Treatment Market
Hematology
Alpha Thalassemia Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Sickle Cell Anemia Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Malignant Lymphoma Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Apheresis Market