
 Neutropenia Treatment Market | 2026-2036
Neutropenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neutropenia Treatment Market Outlook
Multi-source procurement of biologic active ingredients is restructuring supply economics across the neutropenia treatment landscape. Amgen Inc leverages decades of filgrastim manufacturing expertise to sustain dominance in originator molecule supply. Pfizer Inc competes through broad oncology portfolio integration, while Novartis AG anchors European distribution networks with pegfilgrastim and follow-on biologics.
Neutropenia treatment encompasses pharmacologic interventions that elevate absolute neutrophil counts, primarily recombinant human granulocyte colony-stimulating factors produced via E. coli or CHO cell fermentation with specific protein purity thresholds exceeding 95 percent. These agents prevent febrile neutropenia in chemotherapy patients and reduce hospitalization duration. Pegfilgrastim formulations command premium positioning due to reduced injection frequency, while homecare delivery modes represent the fastest-expanding channel as payors push for site-of-care migration. Prophylactic treatment type absorbs the dominant share of clinical protocols, though palliative applications in advanced oncology settings retain distinct margin pools.
FDA biosimilar approval frameworks and EMA extrapolation guidelines shape product substitution rates and pricing trajectories across regulated markets. The EPA governs environmental discharge standards from biologics manufacturing facilities, adding compliance cost layers. Japan's PMDA maintains distinct immunogenicity testing requirements that filter market entrants. Stakeholders must monitor evolving interchangeability designations and site-of-care reimbursement shifts to calibrate portfolio and channel investments.
Market Dynamics
Biosimilar substitution protocols are compressing originator pricing power while oncology clinics consolidate procurement volumes through group purchasing organizations. This structural pressure forces manufacturers to defend position through formulation differentiation and site-of-care service bundling.
Growth Catalysts
- EMA Extrapolation Guidelines:These frameworks accelerate biosimilar approval timelines across European oncology networks. Expanded therapeutic indications broaden addressable patient pools without duplicate clinical trials.
- Homecare Delivery Modes:Payer pressure for site-of-care migration drives demand for self-administered pegfilgrastim formulations. Reduced injection frequency improves patient compliance and lowers total cost of care.
- Prophylactic Protocol Standardization:Major cancer centers in the United States, Germany, and Japan now mandate colony-stimulating factor prophylaxis for intermediate-risk chemotherapy regimens. This clinical practice shift locks in baseline demand volume.
Market Restraints
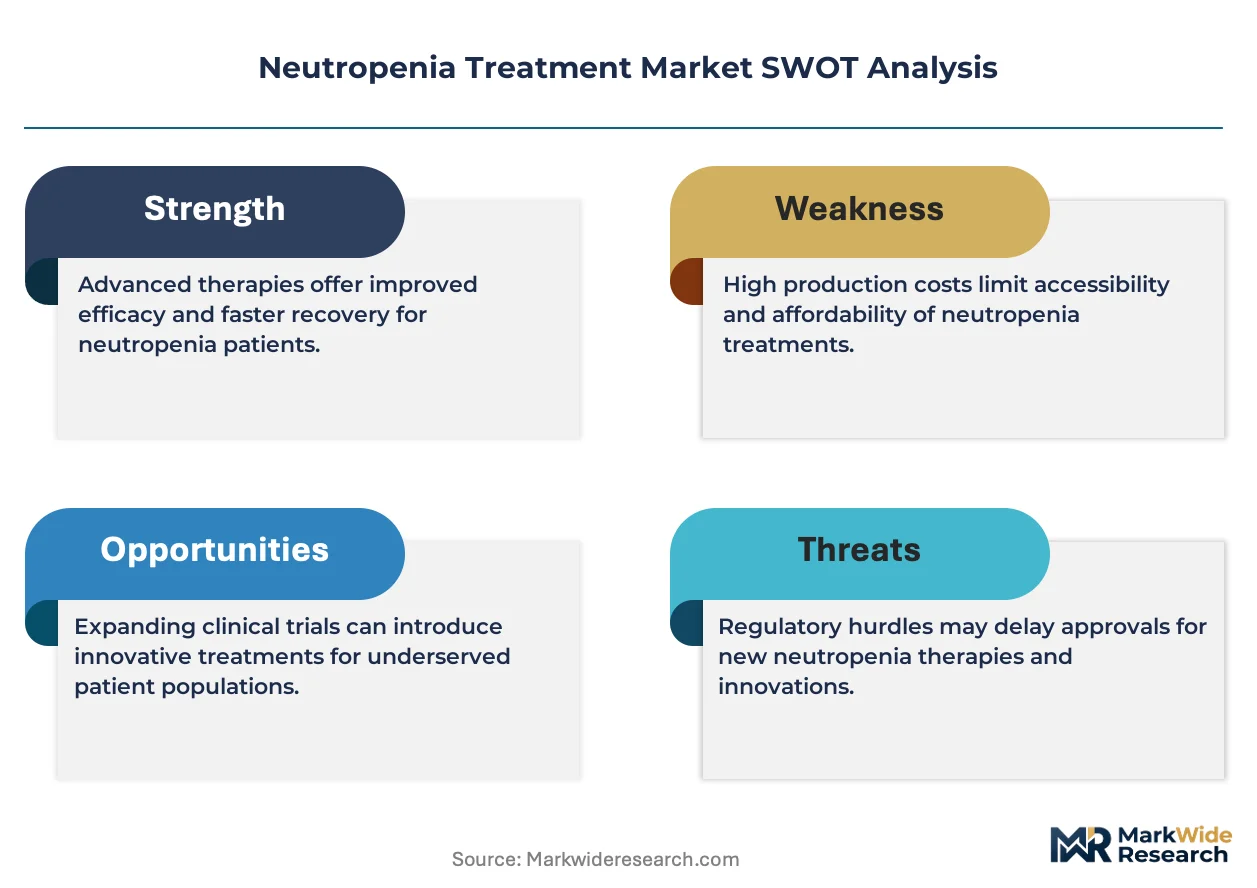
- CHO Cell Fermentation Input Concentration:Biologic active ingredient production depends on limited mammalian cell culture capacity. Supply bottlenecks in contract manufacturing organizations constrain rapid volume scaling.
- Immunogenicity Testing Burden:Japan's PMDA maintains distinct analytical requirements that filter market entrants. Extended development timelines delay product launch in high-value Asia-Pacific markets.
- Originator Pricing Collapse:Filgrastim reference products face severe price erosion from multi-source biosimilar competition. Margin compression threatens sustained investment in next-generation molecule development.
Strategic Opportunities
- Long-Acting Formulation Gaps:Extended-duration G-CSF products remain underpenetrated in palliative oncology settings. These applications retain distinct margin pools despite smaller patient volumes.
- IRA Price Negotiation Exclusions:Biologics with orphan designations fall outside Medicare price controls for specified periods. Strategic portfolio positioning around rare disease indications preserves pricing autonomy.
- Oncology Clinic Consolidation:Large integrated delivery networks in Texas and California centralize purchasing decisions. Direct contracting relationships with these systems bypass traditional wholesale markup structures.
Industry Challenges
- Cold Chain Integrity Requirements:Temperature-sensitive biologics demand specialized logistics infrastructure. Last-mile delivery failures trigger product spoilage and patient treatment delays.
- Interchangeability Designation Delays:FDA switching study requirements extend biosimilar substitution timelines. Pharmacy-level substitution without physician pre-approval remains restricted for most products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neutropenia Treatment Market |
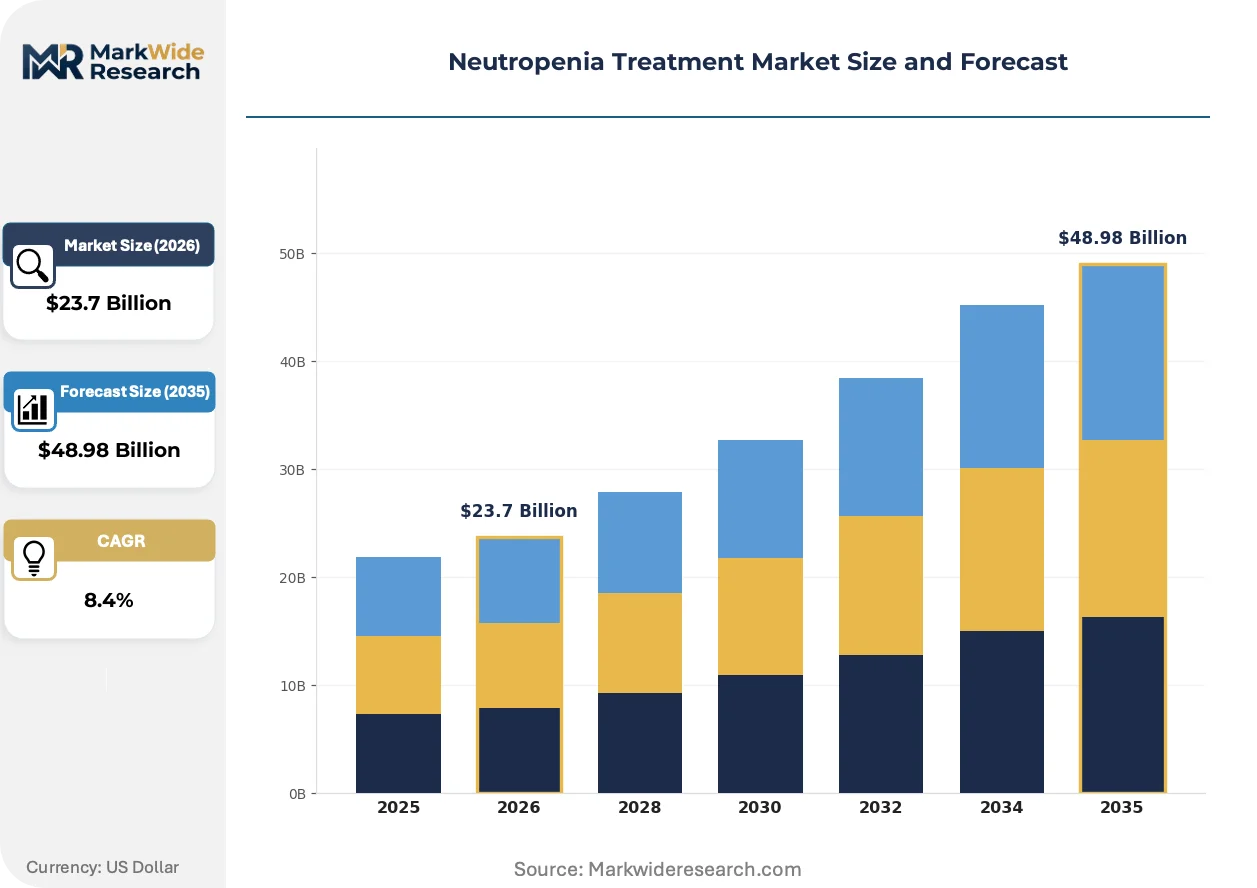
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filgrastim, Pegfilgrastim, Tadekinig alfa, Lipegfilgrastim End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Delivery Mode: Syringe, Auto-injector, Infusion, Oral Treatment Type: Prophylactic, Palliative, Curative, Supportive |
| Companies Covered | Amgen Inc, Pfizer Inc, Novartis AG, Teva Pharmaceutical Industries Ltd, Coherus BioSciences Inc, Biocon Biologics Inc, Kyowa Kirin Co Ltd, Sandoz Inc, G1 Therapeutics Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neutropenia Treatment Market Strategic Shifts
Next-generation delivery technologies and regulatory pathway refinements are compressing development cycles while payer cost-containment measures reshape commercialization strategies across neutropenia therapeutics.
On-body injector systems for pegfilgrastim administration are unifying drug delivery with real-world adherence monitoring. Major oncology clinics in the United States deploy these devices to reduce nursing burden and capture injection timing data. The technology is unifying clinical outcomes tracking with reimbursement documentation, creating integrated value demonstration platforms that manufacturers leverage in payer negotiations.
FDA interchangeability guidance updates are clarifying substitution standards for oncology supportive care. These regulatory refinements reduce prescriber uncertainty and accelerate pharmacy-level product switches. Biosimilar sponsors targeting the United States market now prioritize switching study designs that satisfy these evolving evidentiary thresholds.
Site-of-care economics now dominate procurement decisions for febrile neutropenia prophylaxis. Hospital outpatient departments face reimbursement compression under Medicare's 340B program modifications, pushing volume toward physician office settings. This channel rotation is most pronounced in competitive metropolitan markets where alternative infusion centers have achieved accreditation density.
Neutropenia Treatment Market Segmentation
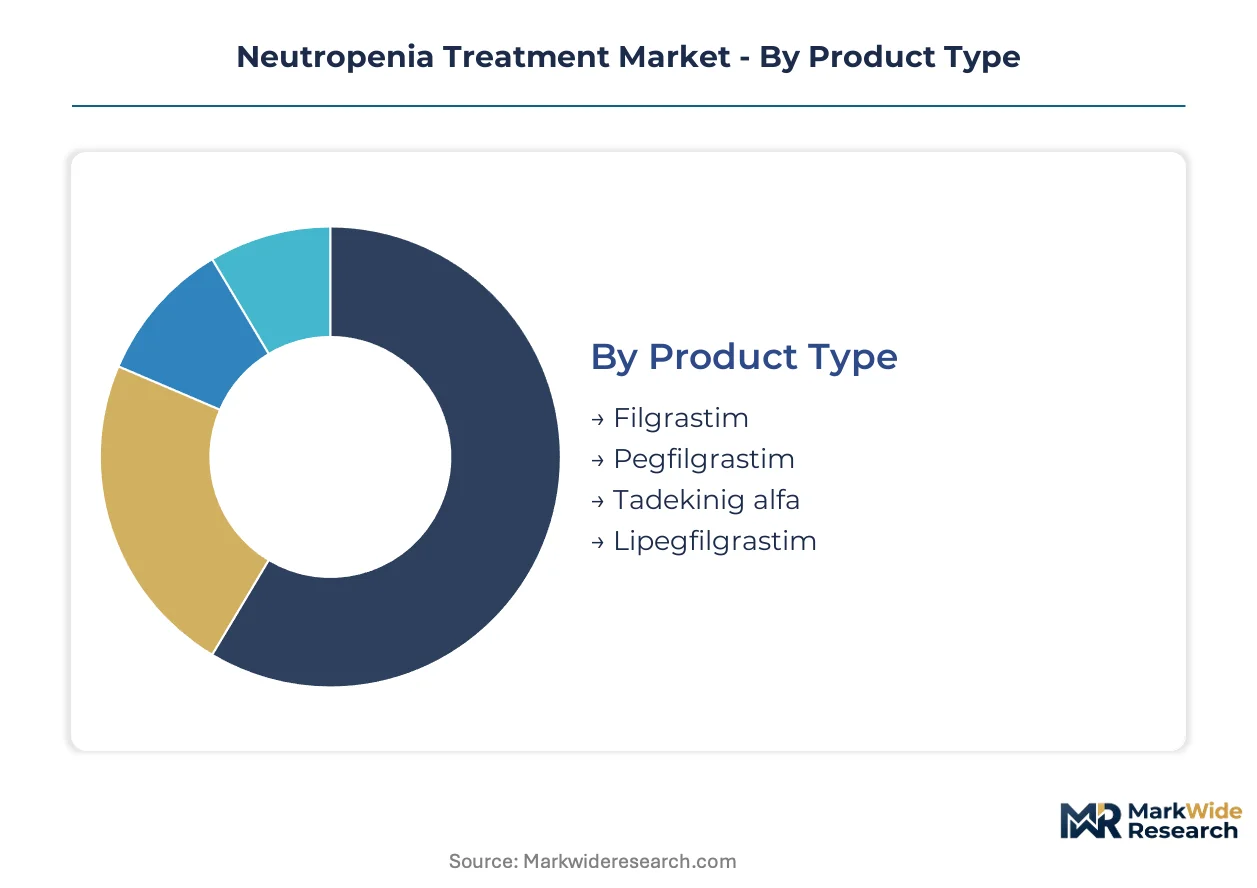
Neutropenia treatment segmentation reflects divergent manufacturing economics across molecule architectures and delivery technologies. Supply chain configuration varies sharply between fermentation-based biologics and synthetic peptide alternatives, while site-of-care migration reshapes channel economics for each delivery mode.
Product Type:
Manufacturing concentration for recombinant proteins dictates competitive positioning across this category, with mammalian cell culture capacity bottlenecks favoring incumbents with captive production assets.
- Pegfilgrastim:PEGylated filgrastim variant with extended half-life enabling single-dose per chemotherapy cycle. Demand concentrates in United States oncology clinics where reduced injection frequency aligns with Medicare reimbursement for physician-administered drugs. The formulation commands premium positioning due to compliance advantages in curative chemotherapy protocols.
- Filgrastim:First-generation recombinant human G-CSF produced via E. coli fermentation with established biosimilar competition. United States and German hospital systems drive volume through standardized prophylactic protocols, though price erosion from multi-source biosimilar entry compresses originator margins.
- Lipegfilgrastim:Glycopegylated G-CSF variant with distinct pharmacokinetic profile. European distribution networks anchor uptake following EMA approval pathways.
- Tadekinig alfa:IL-22 fusion protein targeting chemotherapy-induced neutropenia through alternative mechanism. Development-stage positioning limits commercial footprint to specialized academic medical centers.
Pegfilgrastim absorbs the bulk of installed capacity; tadekinig alfa is expanding most quickly from minimal base.
End User:
Site-of-care economics and reimbursement differentials create distinct procurement patterns across delivery settings, with channel migration accelerating toward lower-acuity environments.
- Hospitals:Inpatient and outpatient departments managing high-risk chemotherapy regimens with intensive monitoring requirements. United States 340B program modifications are compressing outpatient reimbursement and pushing volume toward alternative settings.
- Homecare:Self-administered pegfilgrastim via on-body injector systems. Payer pressure for site-of-care migration and patient preference for reduced clinic visits drive steepest expansion trajectory across all end-user categories.
- Clinics:Physician office-based infusion centers with accredited chemotherapy administration capabilities. Texas and California integrated delivery networks centralize procurement through direct manufacturer contracts.
- Long-term Care Facilities:Palliative neutropenia management in advanced oncology patients. Limited formulary access and nursing staff constraints restrict penetration to specialized hospice partnerships.
Hospitals retain dominant volume share; homecare is gaining share fastest as reimbursement shifts accelerate.
Delivery Mode:
Patient adherence requirements and nursing resource constraints shape technology adoption curves, with device-enabled delivery capturing investment priority from manufacturers and payers alike.
- Auto-injector:Pre-filled syringe systems with automated needle insertion and dose completion. On-body injector platforms for pegfilgrastim unify drug delivery with real-world adherence monitoring in United States oncology clinics.
- Syringe:Conventional manual injection requiring healthcare professional administration. Cost-sensitive markets and institutional procurement favor this mode despite compliance limitations.
- Infusion:Intravenous delivery for hospitalized patients with severe neutropenia or concurrent fluid requirements. Acute care settings in Japan and Germany maintain preference for this route in febrile episodes.
- Oral:Investigational small-molecule G-CSF mimetics with limited commercial availability. Development programs target patient convenience advantages in palliative settings.
Auto-injector platforms absorb the bulk of new product development investment; oral formulations are climbing the fastest from negligible base.
Treatment Type:
Clinical protocol standardization and reimbursement coding specificity determine addressable patient pools, with prophylactic applications commanding structured payment pathways.
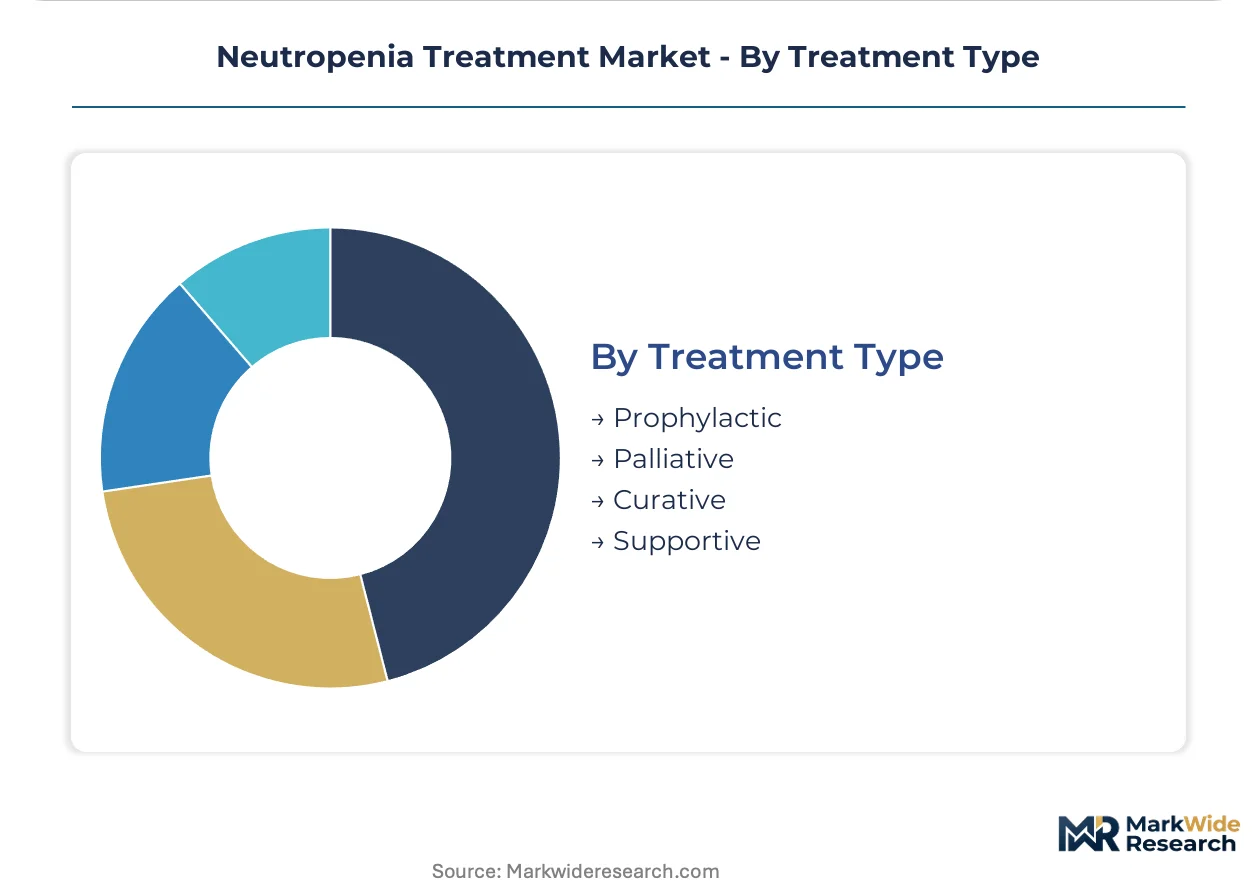
- Prophylactic:Primary prevention of febrile neutropenia in chemotherapy patients with intermediate-to-high risk profiles. United States, German, and Japanese cancer centers now mandate colony-stimulating factor prophylaxis for intermediate-risk regimens, locking in baseline demand volume.
- Supportive:Adjunctive management alongside antimicrobial therapy in established neutropenia. Hospital reimbursement bundles incorporate these agents as standard of care.
- Palliative:Symptom management in advanced malignancy with treatment-limiting cytopenias. Distinct margin pools persist despite smaller patient volumes due to limited price sensitivity in end-of-life care.
- Curative:Definitive resolution of neutropenia underlying etiology, rarely applicable in chemotherapy-induced cases. Limited to congenital or autoimmune neutropenia subtypes with specialized treatment algorithms.
Prophylactic treatment absorbs the bulk of clinical protocol adoption; supportive applications are expanding most quickly as reimbursement bundles mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where chemotherapy protocols are most standardized. Oncology clinics in these markets drive expanded uptake of prophylactic colony-stimulating factors. Regulatory pathway differences across FDA, EMA, and PMDA jurisdictions reshape competitive entry dynamics.
United States
Oncology clinic consolidation in Texas and California centralizes procurement through direct manufacturer contracts. Medicare's 340B program modifications compress hospital outpatient reimbursement, pushing volume toward physician office settings and homecare delivery. The FDA's interchangeability guidance updates clarify substitution standards, reducing prescriber uncertainty and accelerating pharmacy-level product switches.
Germany
Hospital systems drive filgrastim volume through standardized prophylactic protocols with established biosimilar competition. EMA extrapolation guidelines accelerate biosimilar approval timelines across European oncology networks, broadening addressable patient pools without duplicate clinical trials. Bavaria and North Rhine-Westphalia anchor distribution networks where pegfilgrastim and follow-on biologics penetrate integrated cancer centers.
Japan
PMDA maintains distinct immunogenicity testing requirements that filter market entrants and extend development timelines. Tokyo and Osaka metropolitan areas concentrate demand for febrile neutropenia prophylaxis in major academic medical centers. Extended regulatory review periods delay product launch in this high-value Asia-Pacific market despite strong clinical protocol adoption.
United Kingdom
NHS England's Cancer Drugs Fund shapes reimbursement access for colony-stimulating factors in curative chemotherapy protocols. London and the Southeast concentrate oncology service delivery where homecare delivery modes gain traction under payer pressure for site-of-care migration. EMA biosimilar pathways enable rapid formulary adoption once cost-effectiveness thresholds are demonstrated.
India
CDSCO regulatory frameworks govern biologics manufacturing with growing emphasis on biosimilar quality standards. Maharashtra and Gujarat host contract manufacturing organizations supplying active pharmaceutical ingredients to global markets. Domestic oncology networks expand prophylactic G-CSF use as chemotherapy protocol standardization advances in metropolitan hospital systems.
Neutropenia Treatment Market Competitive Environment
Formulation differentiation dominates the current landscape as originator manufacturers defend position against multi-source biosimilar entry. The market structure exhibits tiered consolidation with established biologics incumbents, biosimilar specialists, and emerging fusion protein developers occupying distinct competitive layers. Strategic archetypes include captive manufacturing incumbents, regulatory pathway specialists, and portfolio-integrated pharmaceutical conglomerates. Capacity expansion in mammalian cell culture and strategic partnerships for on-body injector technology represent the dominant competitive moves reshaping supply economics.
Among established biologics developers, Amgen Inc exemplifies the captive manufacturing archetype with decades of filgrastim production expertise. Pfizer Inc and Novartis AG occupy positions within the portfolio-integrated tier, leveraging broad oncology distribution networks and European market anchoring respectively. These three entities represent contrasting strategic postures: manufacturing depth, therapeutic portfolio breadth, and regional market specialization.
| Leading Market Players |
|---|
| Amgen Inc |
| Pfizer Inc |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Coherus BioSciences Inc |
| Biocon Biologics Inc |
| Kyowa Kirin Co Ltd |
| Sandoz Inc |
| G1 Therapeutics Inc |
| Others |
Value Chain & Pricing Dynamics
CHO cell fermentation capacity constraints in mammalian cell culture facilities propagate downstream through pegfilgrastim pricing tiers, with captive bioreactor assets commanding premium positioning against contract-manufactured alternatives.
Pricing Analysis
Volume concentration in prophylactic protocols absorbs margin compression while palliative applications retain pricing autonomy. Three-tier pricing structure across originator, interchangeable biosimilar, and non-interchangeable follow-on biologics segments buyers by formulary access and reimbursement coding. Price differentiation rests on immunogenicity testing documentation and cold chain certification levels. Cost compression in filgrastim originator tiers is intensifying because multi-source biosimilar entry has collapsed reference product premiums. Hospital procurement through 340B programs exhibits highest price sensitivity; homecare delivery channels with bundled device services show lowest.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised biologics require specialized cold chain recovery protocols that extend working capital cycles for distributors. Manufacturing concentration spans United States, Germany, and Japan where fermentation capacity anchors active pharmaceutical ingredient output. Raw material dependencies include fetal bovine serum, recombinant DNA vectors, and pharmaceutical-grade polyethylene glycol. Single-source vulnerability in CHO cell line licensing creates supply continuity exposure. Distribution runs through oncology-focused specialty distributors with direct-to-clinic delivery accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capacity scarcity in mammalian cell culture props pricing power for incumbents with captive bioreactor assets, while contract manufacturing organization bottlenecks constrain rapid volume scaling by challengers.
For Market Incumbents: Extend formulation differentiation through on-body injector platform integration that unifies drug delivery with adherence monitoring data. Deepen captive supply of CHO cell fermentation capacity to defend against biosimilar volume surges. Anchor procurement relationships with Texas and California integrated delivery networks before competitor direct contracting solidifies.
For New Entrants and Emerging Players: Begin with palliative oncology settings where limited formulary competition and reduced price sensitivity create viable margin pools. Target long-term care facility partnerships in hospice networks as the most penetrable channel bypassing hospital GPO consolidation. Pursue EMA extrapolation pathway approvals to accelerate European market entry without duplicate clinical trials.
For Investors and Strategic Acquirers: FDA interchangeability designation grants are the leading indicator that pharmacy-level substitution without physician pre-approval will accelerate, compressing originator valuations ahead of biosimilar volume capture. Long-term viability over the next decade hinges on portfolio positioning around orphan-designated biologics excluded from IRA price negotiation. Monitor Japan PMDA immunogenicity testing requirement modifications as the signal for accelerated Asia-Pacific market entry timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive CHO cell fermentation capacity insulates supply continuity against contract manufacturing organization bottlenecks. |
| Regulatory Approval Pathway | EMA extrapolation guidelines accelerate biosimilar timelines across European oncology networks without duplicate trials. |
| Reimbursement Strategy | Site-of-care economics alignment with Medicare 340B modifications redirects volume toward physician office settings. |
| Product Launch | On-body injector platforms for pegfilgrastim unify drug delivery with real-world adherence monitoring in United States clinics. |
| Strategic Partnership | Direct contracting with Texas and California integrated delivery networks bypasses traditional wholesale markup structures. |
Study Parameters
Independent corroboration across regulatory submission databases, hospital procurement records, and payer formulary filings underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data. Bottom-up patient volume modeling and top-down market sizing triangulate to segment-level estimates.
Rate-of-change decomposition across the projection horizon separates volume growth from price trajectory components in the analytical framework. Segmentation dimensions modeled include treatment type, delivery mode, end-user setting, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation with cross-validation against historical analogs. Forecast inputs incorporate biosimilar substitution protocol adoption curves and site-of-care reimbursement shift velocities.
Underlying measurement precision varies by segment; prophylactic treatment and auto-injector delivery mode carry tighter precision than palliative applications and oral formulations. Forecasts reflect assumptions about interchangeability designation timelines and CHO cell capacity expansion that could revise projections. Practitioners should monitor FDA switching study requirement modifications and Japan PMDA immunogenicity testing guideline updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Anemia Drugs Market
Hematology
Immune Thrombocytopenia (ITP) Market
Hematology
Hemocytometer Market
Hematology
Malignant Lymphoma Market
Hematology
Global Immunohematology Market
Hematology
Blood Plasma Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Polycythemia Vera Market
Hematology
Lymphoma Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Venous Blood Collection Market
Hematology
At-Home Hematology Testing Market