
 Lymphoproliferative Disorder Treatment Market | 2026-2036
Lymphoproliferative Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lymphoproliferative Disorder Treatment Market Foresight
Hospital systems is rotating toward outpatient infusion centers as the dominant buyer archetype for lymphoproliferative therapies, displacing traditional inpatient admissions. Bristol Myers Squibb Company anchors its position through deep manufacturing scale in biologics production. AbbVie Inc. differentiates via specialization in targeted therapy combinations for refractory patient populations. Novartis AG extends its reach through channel control across integrated delivery networks in North America.
Lymphoproliferative disorder treatment encompasses therapeutic interventions for conditions marked by abnormal lymphocyte proliferation, including monoclonal antibodies engineered to CD20 or CD30 surface markers, chemotherapy regimens, and cellular immunotherapies designed to restore immune surveillance. These interventions serve to induce remission, consolidate response, or maintain disease control across hematologic malignancies and autoimmune-driven lymphoproliferations. Monoclonal antibodies occupy the largest revenue pool given established reimbursement and infusion infrastructure, while immunotherapy segments attract the fastest development velocity as CAR-T platforms mature. Intravenous delivery dominates current volume, though subcutaneous formulations are gaining structural share through reduced administration burden and site-of-care economics.
The FDA accelerates oncology timelines through breakthrough therapy and accelerated approval designations, compressing development cycles for novel lymphoproliferative agents. EMA's MDR and EU pharmacovigilance frameworks enforce post-market safety monitoring that shapes commercialization strategies across European markets. Stakeholders must monitor evolving CMS reimbursement rules for cellular therapies and site-neutral payment policies that redistribute margin across infusion settings.
Market Dynamics
The transition from inpatient to outpatient infusion administration is compressing site-of-care economics and forcing manufacturers to reconfigure distribution networks around ambulatory settings rather than hospital pharmacy departments.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel lymphoproliferative agents, enabling earlier commercial entry for CAR-T platforms and bispecific antibodies targeting CD20 or CD30 markers.
- Academic Medical Center Expansion:United States-based university hospitals anchor clinical trial recruitment infrastructure, concentrating patient access to investigational cellular therapies and driving protocol standardization across referral networks.
- Subcutaneous Formulation Engineering:Reduced administration burden and elimination of infusion chair time are shifting prescriber preference toward self-administered biologics, expanding addressable patient populations beyond infusion-capable sites.
Market Restraints
- Plasma-Derived Raw Material Concentration:Dependency on specialized apheresis collection networks in the United States and Germany creates supply vulnerability for immunoglobulin and albumin-dependent manufacturing processes.
- EMA Post-Market Surveillance Burden:The MDR pharmacovigilance framework imposes ongoing safety monitoring costs that dilute commercial margins for therapies approved through conditional pathways in European markets.
- Allogeneic CAR-T Manufacturing Complexity:Batch-to-batch variability in cell expansion yields and cryopreservation logistics constrain production scalability relative to autologous platform economics.
Strategic Opportunities
- Site-Neutral Payment Arbitrage:CMS reimbursement parity between hospital outpatient departments and freestanding infusion centers creates margin redistribution opportunities for manufacturers with pharmacy benefit manager relationships.
- Refractory Population Targeting:Relapsed mantle cell lymphoma and post-transplant lymphoproliferative disorder segments remain underserved by existing CD20-directed regimens, opening positioning for next-generation antibody-drug conjugates.
- Integrated Delivery Network Channel Control:Direct contracting with United States health system formularies bypasses traditional wholesale distribution, capturing volume commitments through exclusive therapeutic class agreements.
Industry Challenges
- Cellular Therapy Workforce Scarcity:Shortage of apheresis nurses and cell processing technicians constrains expansion of CAR-T treatment capacity at certified treatment centers.
- Cold Chain Integrity Requirements:Cryogenic logistics for autologous products demand specialized courier networks and temperature-validated storage infrastructure that fragments distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lymphoproliferative Disorder Treatment Market |
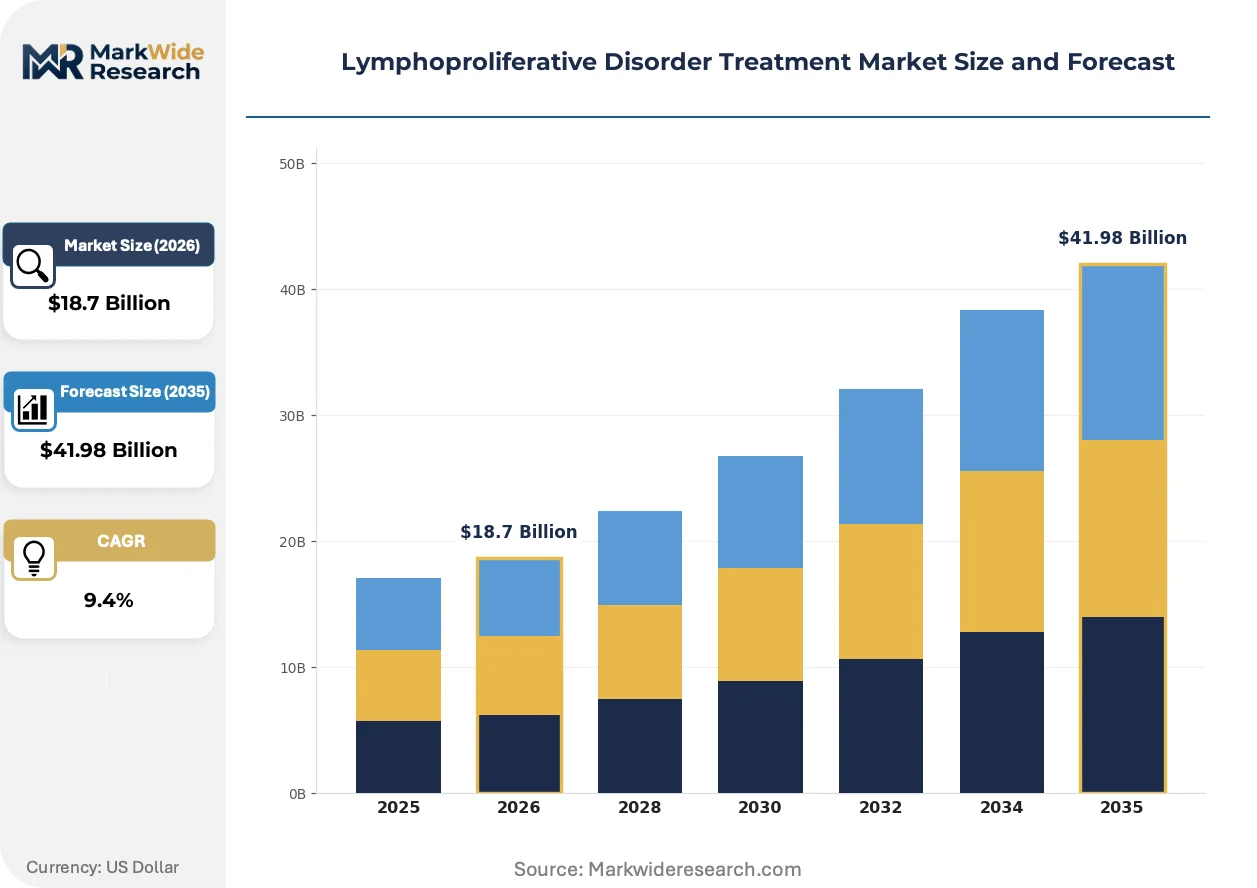
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy, Immunotherapy, Targeted Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Laboratories, Homecare Treatment Phase: Induction, Consolidation, Maintenance, Palliative |
| Companies Covered | Atara Biotherapeutics, Inc., Merck & Co., Inc., Bristol Myers Squibb Company, Genentech, Inc., ADC Therapeutics SA, AbbVie Inc., Novartis AG, Pfizer Inc., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lymphoproliferative Disorder Treatment Market Shifts & Advancements
Biologic delivery mechanisms and regulatory pathways are undergoing simultaneous transformation, with manufacturing scale and site-of-care flexibility emerging as the primary axes of competitive differentiation.
Subcutaneous rituximab and trastuzumab formulations are supplanting intravenous equivalents in lymphoproliferative indications where administration time reduction drives patient throughput economics. Community oncology practices and hospital outpatient departments are adopting these alternatives at accelerating velocity, compressing infusion center capacity requirements and reallocating nursing labor toward higher-acuity cellular therapy administration.
The FDA's accelerated approval pathway for oncology biologics continues to reshape development economics, permitting earlier revenue recognition based on surrogate endpoints rather than survival data. This regulatory compression favors well-capitalized developers capable of funding confirmatory trials, while EMA's parallel MDR enforcement imposes divergent post-market study obligations that fragment European launch sequencing.
Hospital systems are consolidating infusion service purchasing through centralized pharmacy and therapeutics committees, displacing individual physician preference as the dominant prescription determinant. This behavioral shift concentrates volume with manufacturers offering integrated patient support programs and outcomes guarantees, with the phenomenon most visible in United States integrated delivery networks where formulary exclusion clauses now govern biologic access.
Lymphoproliferative Disorder Treatment Market Segmentation
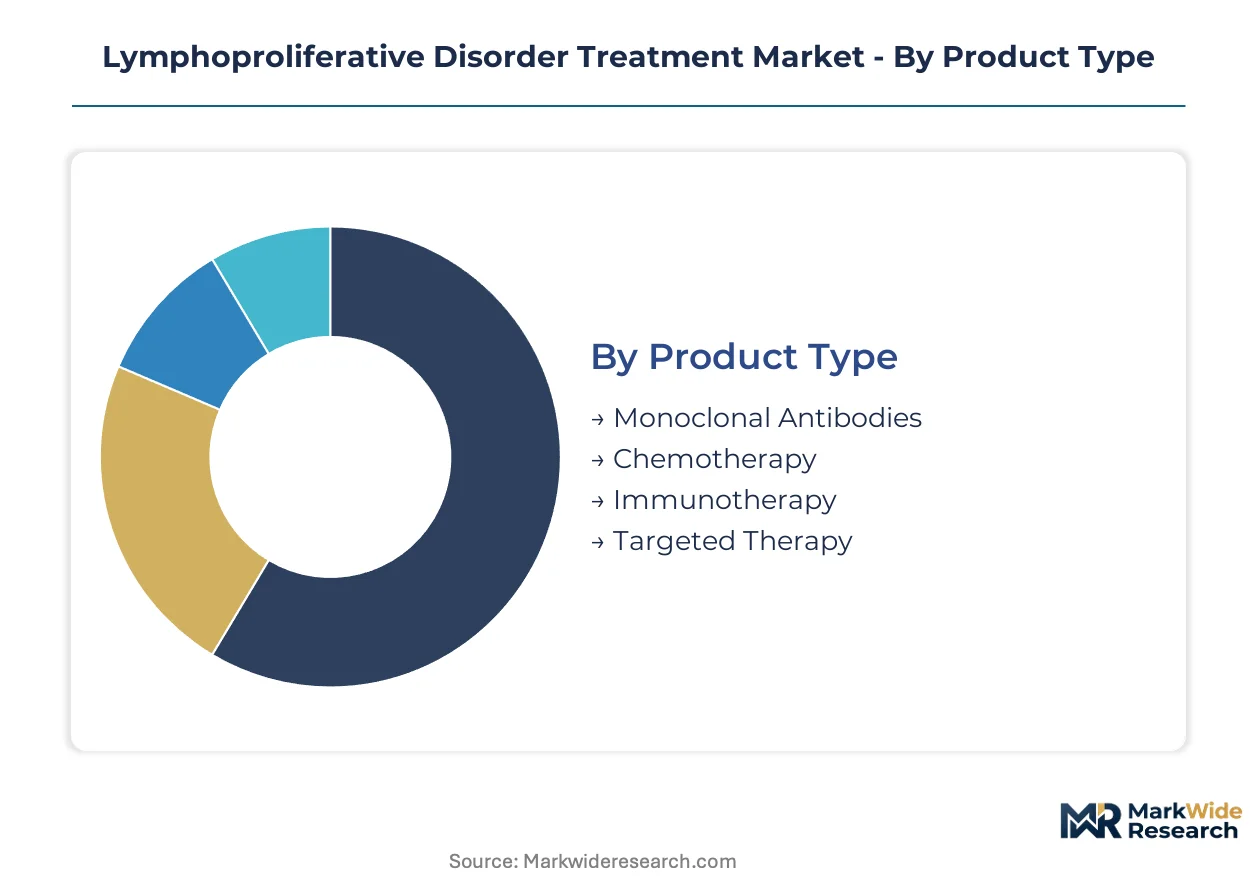
Treatment modality segmentation reveals divergent margin structures across lymphoproliferative therapies. Product engineering and site-of-care economics drive purchasing fragmentation that manufacturers must navigate through tailored channel strategies.
Product Type:
Monoclonal antibodies and immunotherapy platforms anchor domestic demand in the United States and Germany, while chemotherapy compounds retain export-led volume to emerging markets with constrained reimbursement.
- Monoclonal Antibodies:Engineered proteins bind CD20 or CD30 surface markers to induce antibody-dependent cellular cytotoxicity. Demand concentrates in United States academic medical centers where infusion infrastructure and premium reimbursement sustain biologic prescribing. Manufacturing scale and established pharmacovigilance databases reinforce incumbent positioning.
- Immunotherapy:CAR-T cell platforms and bispecific constructs reprogram patient-derived or donor lymphocytes to recognize malignant clones. Manufacturing complexity limits production to certified treatment centers in Boston, Seattle, and Philadelphia, constraining geographic accessibility despite clinical efficacy.
- Chemotherapy:Cytotoxic alkylating agents and antimetabolites remain standard-of-care backbone regimens across lower-resource settings.
- Targeted Therapy:Small-molecule inhibitors of BTK, PI3K, and BCL-2 pathways enable outpatient oral administration.
Monoclonal antibodies hold the largest share; momentum sits with immunotherapy platforms.
Delivery Mode:
Cost tier stratification separates high-touch intravenous administration from self-administered alternatives that reduce total cost of care.
- Intravenous:Infusion-dependent biologics require specialized nursing supervision and chair time allocation. Hospital outpatient departments in the United States capture margin through facility fees, while German ambulatory oncology practices manage comparable volume with lower overhead structures.
- Subcutaneous:Reformulated rituximab and trastuzumab variants eliminate infusion chair requirements and enable community practice administration. United States Medicare site-neutral payment policies accelerate adoption by compressing reimbursement differentials between hospital and freestanding settings.
- Oral:Targeted small molecules shift treatment burden to patient self-management and pharmacy benefit coverage.
- Topical:Cutaneous lymphoproliferative indications utilize localized corticosteroid or retinoid application.
Intravenous administration retains volume leadership; subcutaneous formulations are climbing the fastest.
End User:
Customer type determines procurement authority and formulary control mechanisms across divergent care settings.
- Hospitals:Integrated delivery networks consolidate purchasing through pharmacy and therapeutics committees, displacing individual physician autonomy. United States health systems in Texas, California, and New York anchor the highest CAR-T treatment volumes through captive referral networks and captive apheresis capacity.
- Clinics:Community oncology practices in Florida and Arizona adopt subcutaneous biologics to maximize patient throughput per nursing hour. Reimbursement compression under the Medicare Physician Fee Schedule constrains investment in cellular therapy infrastructure.
- Research Laboratories:Academic centers manage investigational therapy access through FDA-expanded access programs and sponsor-initiated trials.
- Homecare:Oral targeted therapies and subcutaneous formulations enable administration outside institutional settings.
Hospitals command the dominant share; homecare channels are gaining share fastest.
Treatment Phase:
Application timing across the care continuum segments pricing power and duration of therapy.
- Induction:Intensive initial regimens aim for complete remission in aggressive lymphoproliferative malignancies. United States oncology practices prioritize CD20-directed combinations with curative intent in diffuse large B-cell lymphoma, with treatment centers in Houston and Boston publishing the highest complete response rates.
- Consolidation:High-dose therapy with autologous stem cell rescue follows induction response in eligible patients. German university hospitals in Heidelberg and Munich maintain specialized transplant units with established European Bone Marrow Transplant accreditation.
- Maintenance:Extended rituximab or lenalidomide administration prolongs remission duration in follicular lymphoma.
- Palliative:Symptom-directed therapy prioritizes quality of life in refractory or elderly populations.
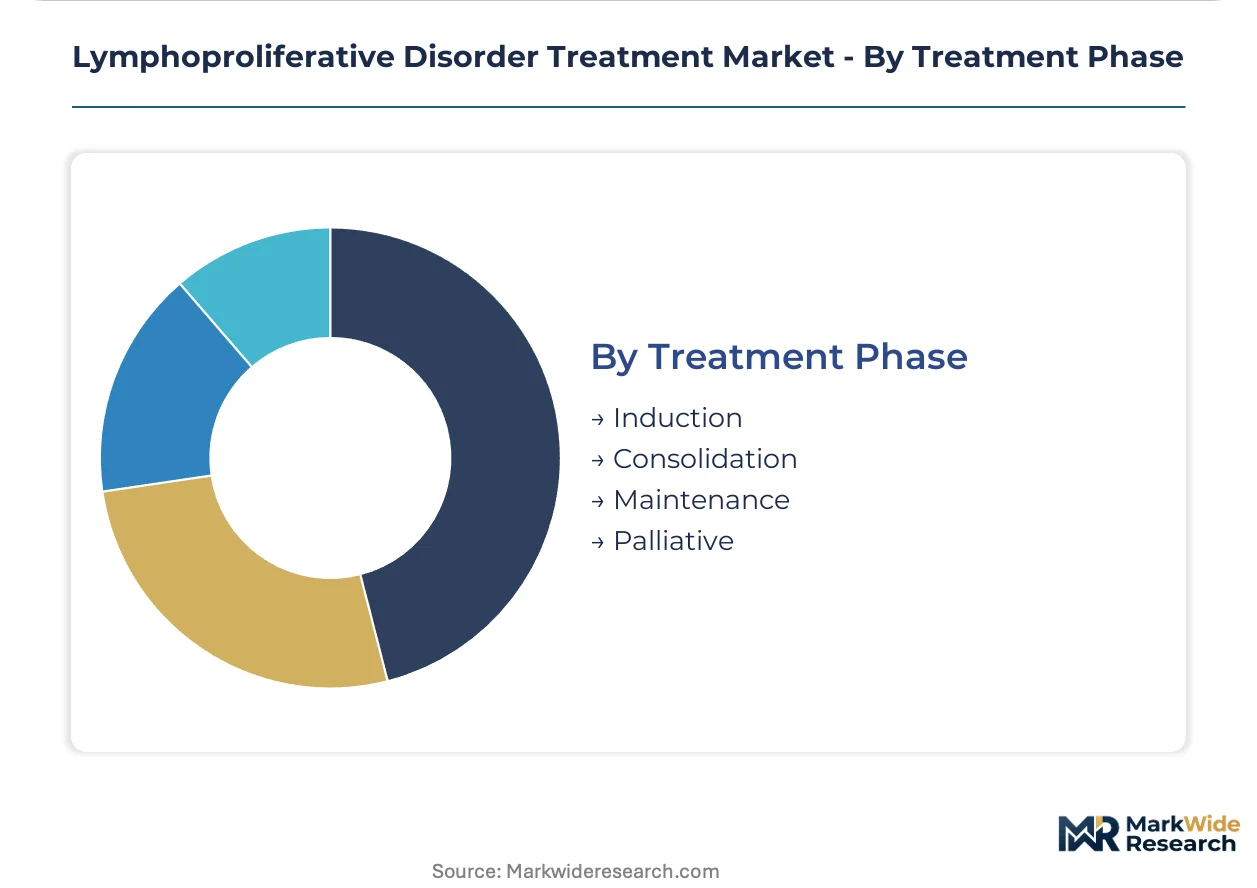
Induction therapy captures the largest share; maintenance protocols show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biologics manufacturers export CD20-directed monoclonal antibodies to United States academic medical centers, establishing the trans-Atlantic corridor as the dominant trade flow for lymphoproliferative therapies.
United States
Academic medical centers in Boston, Houston, and Seattle anchor CAR-T treatment capacity through captive apheresis infrastructure and FDA-certified manufacturing partnerships. CMS site-neutral payment policies redistribute reimbursement margin between hospital outpatient departments and freestanding infusion centers. The Texas Medical Center in Houston maintains the highest lymphoproliferative therapy volume through integrated referral networks spanning the Gulf Coast.
Germany
Heidelberg and Munich university hospitals specialize in consolidation-phase autologous stem cell transplant protocols with European Bone Marrow Transplant accreditation. EMA MDR pharmacovigilance frameworks impose post-market surveillance obligations that shape commercial launch sequencing. The Rhine-Main cluster around Frankfurt concentrates plasma-derived raw material processing for immunoglobulin manufacturing.
Japan
PMDA breakthrough therapy designations accelerate review timelines for bispecific antibodies targeting relapsed mantle cell lymphoma. METI industrial policy supports domestic cell processing infrastructure development. The Kansai region around Osaka hosts specialized cryopreservation logistics hubs serving Asia-Pacific cellular therapy distribution.
United Kingdom
NHS England specialized commissioning frameworks concentrate lymphoproliferative therapy access through designated cancer centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory autonomy enables divergence from EMA approval timelines. The Cambridge-London corridor anchors early-phase clinical trial recruitment for next-generation antibody-drug conjugates.
Switzerland
Swissmedic accelerated assessment pathways compress approval timelines for priority oncology medicines. Basel anchors biologics manufacturing scale through integrated chemical-pharmaceutical clusters. The Lake Geneva region concentrates precision medicine research infrastructure supporting biomarker-driven patient selection for targeted therapies.
Lymphoproliferative Disorder Treatment Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with biologics manufacturing scale, creating a consolidated structure around therapy-class leaders. Three archetypes dominate: CD20-directed monoclonal antibody incumbents with established infusion infrastructure, CAR-T platform specialists with certified treatment center networks, and targeted therapy developers with oral small-molecule portfolios. Competitive moves concentrate on site-of-care distribution partnerships and subcutaneous formulation engineering to capture outpatient volume.
Among United States-based biopharmaceutical conglomerates, Bristol Myers Squibb Company and AbbVie Inc. exemplify the integrated archetype with biologics manufacturing depth and formulary control capabilities. Novartis AG represents the European multinational tier with channel leverage across North American integrated delivery networks. ADC Therapeutics SA occupies a specialized position within the antibody-drug conjugate development segment.
| Leading Market Players |
|---|
| Atara Biotherapeutics, Inc. |
| Merck & Co., Inc. |
| Bristol Myers Squibb Company |
| Genentech, Inc. |
| ADC Therapeutics SA |
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Manufacturing scale at certified treatment centers anchors price floors for autologous cellular therapies, concentrating production economics in Boston, Seattle, and Philadelphia while compressing margins for smaller apheresis-dependent facilities. This scale concentration simultaneously shapes supply network topology, as cryogenic logistics capacity and batch-size minimums tether distribution to high-volume hospital systems.
Pricing Analysis
Next-generation CAR-T platforms command substantial premiums over established CD20-directed monoclonal antibodies, while prior-generation chemotherapy backbones face commoditization in lower-resource markets. The dominant pricing structure stratifies across premium cellular therapies, standard biologic infusions, and economy-tier cytotoxic regimens. Price differentiation hinges on manufacturing complexity and site-of-care administration requirements, with infusion-chair time and apheresis capacity as primary drivers. Pricing pressure intensifies in the standard biologic tier as subcutaneous formulations eliminate facility fee capture. Academic medical centers demonstrate lowest price sensitivity given captive reimbursement pathways, while community oncology practices in Florida and Arizona exhibit highest sensitivity to total cost of care.
Supply Chain Analysis
Strategic stockpiling of plasma-derived raw materials dominates manufacturer inventory strategy, contrasting with just-in-time preferences for small-molecule chemical inputs. Supply concentration centers on the United States and Germany for apheresis collection networks, with Switzerland anchoring biologics fill-finish capacity. Raw material dependencies encompass specialized cell culture media, cryopreservation dimethyl sulfoxide, and patient-matched leukapheresis kits. Single-source vulnerability in qualified viral vector production constrains CAR-T expansion timelines. Distribution runs through integrated delivery network pharmacy and therapeutics committees, displacing traditional wholesale channels for biologic therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Site-of-care fragmentation creates specialized entry points for differentiated delivery technologies and regional service models, as outpatient infusion migration splinters purchasing authority across hospital systems, community practices, and homecare channels.
For Market Incumbents: Fortify formulary control through exclusive therapeutic class agreements with United States integrated delivery networks, countering biosimilar erosion in CD20-directed monoclonal antibodies. Deepen backward integration into apheresis collection infrastructure to secure raw material supply against plasma-derived concentration risks. Prioritize subcutaneous formulation engineering to capture community oncology volume migrating away from hospital outpatient departments. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks commercial entry for bispecific antibodies targeting relapsed mantle cell lymphoma, the most penetrable segment given underserved refractory populations. White-space targets include post-transplant lymphoproliferative disorder protocols and German ambulatory oncology practices with lower overhead structures. Go-to-market positioning should emphasize site-neutral payment arbitrage through freestanding infusion center partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CAR-T platform specialists with certified treatment center networks and cryogenic logistics capabilities over small-molecule developers facing patent cliffs. Long-term viability over the next decade rests on manufacturing scalability and regulatory pathway execution rather than single-asset clinical data. Acquisition targets should demonstrate captive apheresis capacity and FDA-certified manufacturing partnerships. The signal to watch is CMS reimbursement rulemaking for cellular therapies, which would indicate inflection in site-of-care economics.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Eliminates infusion chair requirements and expands community practice addressable market. |
| Integrated Delivery Network Direct Contracting | Bypasses wholesale distribution through exclusive therapeutic class agreements with Texas and California health systems. |
| CAR-T Manufacturing Scale-Up | Certified treatment center expansion in Boston and Seattle anchors geographic capacity constraints. |
| Plasma Collection Network Integration | Captive apheresis capacity in the United States and Germany secures immunoglobulin-dependent supply chains. |
| Site-Neutral Payment Strategy | Pharmacy benefit manager relationships capture margin redistribution under CMS reimbursement parity rules. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, with input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Bottom-up patient-flow modeling triangulates against top-down revenue estimates across treatment modalities and administration settings. Primary interviews probed manufacturing capacity constraints, site-of-care migration patterns, and reimbursement pathway evolution.
Segmentation dimensions modeled encompass treatment modality, delivery mode, end-user channel, and treatment phase across the projection horizon. CAGRs derive from patient incidence projections, therapy penetration assumptions, and pricing trajectory analysis. Industry-specific forecast inputs include apheresis capacity expansion timelines and CMS site-neutral payment policy implementation pace. The analytical framework weights United States academic medical center volume concentration against German ambulatory oncology practice adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization or stable plasma collection network economics would require recalibration. Forecasts reflect documented assumptions regarding CAR-T manufacturing yield improvements and subcutaneous formulation substitution rates. Revision becomes warranted when CMS reimbursement rulemaking for cellular therapies crosses threshold implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Erythropoietic Protoporphyria (EPP) Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Apheresis Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Multiple Myeloma Market
Hematology
Global Disposable Hemoperfusion Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Venous Blood Collection Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Lymphoma Treatment Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Hemostatic Spray Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Hemoglobin Analyzer Market