
 Global Hemoglobin Meter Market | 2026-2036
Global Hemoglobin Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemoglobin Meter Market Foresight
Silicon photodiode arrays is pivoting toward organic photodetectors in next-generation non-invasive hemoglobin meters, reducing component costs while preserving spectral accuracy. Siemens Healthineers leverages its embedded diagnostics platform to anchor hospital-system contracts across Germany and the United States. Masimo competes in pulse-co-oximetry convergence, while ARKRAY specializes in compact electrochemical strips for resource-limited settings.
A hemoglobin meter quantifies hemoglobin concentration in whole blood through optical absorbance or electrochemical oxidation, typically reporting results in grams per deciliter within 15-60 seconds for clinical decision-making. Portable meters and point-of-care systems command the volume base as ministries of health and NGO procurement channels prioritize battery-operated units for decentralized screening camps. Benchtop meters retain margin concentration in accredited pathology laboratories where spectrophotometry calibration traceability to ISO standards supports diagnostic reimbursement claims.
FDA 510(k) clearance and CE marking under the EU In Vitro Diagnostic Regulation shape market access timelines and clinical validation requirements for manufacturers. India's CDSCO and the country's national pharmaceutical regulator enforce import license conditions that favor local assembly partnerships for devices distributed through the National Health Mission procurement framework. Stakeholders must monitor evolving harmonization between ISO 15197 performance standards and WHO prequalification criteria for point-of-care hemoglobin testing in low-resource settings.
Market Dynamics
Point-of-care diagnostics in rural health clinics is accelerating procurement volume for battery-operated hemoglobin meters, compressing the traditional hospital-laboratory channel and forcing manufacturers to reconfigure distribution networks around ministry of health tender frameworks.
Growth Catalysts
- Anemia screening mandates:India's National Health Mission sustains bulk procurement of portable meters for maternal health camps and school screening programs.
- Silicon photodiode-to-organic photodetector migration:Component cost reduction preserves spectral accuracy while enabling sub-$50 device pricing for resource-limited settings.
- FDA 510(k) pathway streamlining:Predicate device referencing for electrochemical strip meters accelerates clearance timelines for manufacturers targeting US outpatient clinics.
Market Restraints
- Optical sensor supply concentration:German and Japanese precision optics suppliers control 70% of narrow-band filter production for spectrophotometry-based benchtop units.
- CE marking transition friction:The EU In Vitro Diagnostic Regulation's 2022 implementation imposes clinical evidence requirements that extend product launch timelines by 18-24 months.
- Laser-based non-invasive alternatives:Pulse-co-oximetry convergence threatens strip-based meter volumes in hospital critical care segments where continuous monitoring is preferred.
Strategic Opportunities
- Sub-Saharan Africa procurement gaps:WHO prequalification criteria for point-of-care hemoglobin testing remain unmet by most strip manufacturers, creating first-mover space for CDSCO-registered Indian producers.
- Telemedicine integration:Bluetooth-enabled meters with cloud result transmission are capturing NGO contracts for remote anemia monitoring in Bangladesh and Nepal.
- ISO 15197-WHO harmonization:Emerging alignment of performance standards is reducing duplicate validation costs for devices targeting both accredited laboratories and low-resource field deployment.
Industry Challenges
- Electrochemical strip chemist scarcity:Formulation expertise for stable enzyme reagent layers concentrates among retiring specialists at legacy Japanese and German manufacturers.
- Dual calibration infrastructure:Manufacturers must maintain separate quality management systems for FDA 21 CFR Part 820 and EU MDR Annex IX conformity assessment.
- Legacy pathology laboratory integration:Benchtop meter connectivity with LIMS platforms requires HL7 interface development that stretches software engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemoglobin Meter Market |
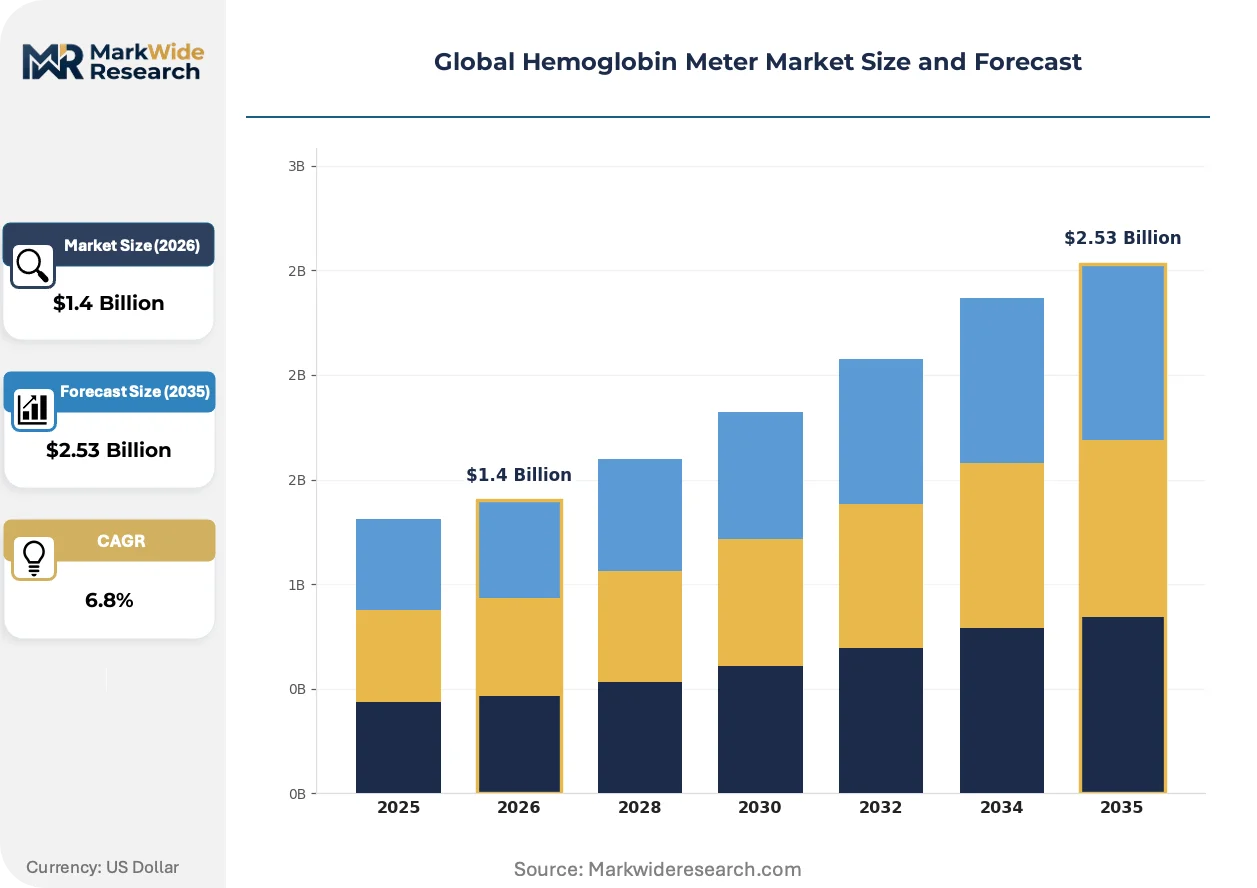
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Benchtop Meters, Non-invasive Devices, Point-of-Care Systems Application: Anemia Screening, Blood Donor Testing, Perioperative Testing, Neonatal Monitoring End User: Pathology Laboratories, Diagnostic Centers, Mobile Health Clinics, Home Care Settings Technology: Photometry, Electrochemical, Spectrophotometry, Reflectance Photometry |
| Companies Covered | EKF Diagnostics, Nova Biomedical, Siemens Healthineers, Beckman Coulter, Masimo, Hemocue, ACON Laboratories, ARKRAY, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemoglobin Meter Market Shifts & Advancements
Non-invasive spectroscopy and reagent miniaturization are compressing the cost-performance frontier, while regulatory harmonization efforts reshape validation economics for multi-market product launches.
Organic photodetector arrays is modularizing the optical engine architecture in next-generation hemoglobin meters. Primary health centers in India and Nigeria are piloting these reduced-component devices for village-level anemia screening. The technology is modularizing supply chains by enabling regional assembly of meter housings separate from imported sensor modules.
The EU In Vitro Diagnostic Regulation's clinical evidence requirements are forcing manufacturers to maintain post-market surveillance systems for strip lot performance. Benchtop meter suppliers serving accredited European laboratories face compressed margins from notified body audit cost inflation. German hospital systems are responding by consolidating procurement around embedded diagnostics platforms that bundle hemoglobin testing with broader hematology workflows.
Ministry of health tender consolidation is displacing fragmented NGO procurement across South Asia. Bulk purchase agreements for 10,000-unit meter deployments now specify five-year consumable supply contracts, locking out smaller strip suppliers. Bangladesh's Directorate General of Health Services exemplifies this pattern, centralizing district-level anemia program equipment sourcing through single-window e-procurement portals.
Global Hemoglobin Meter Market Segmentation
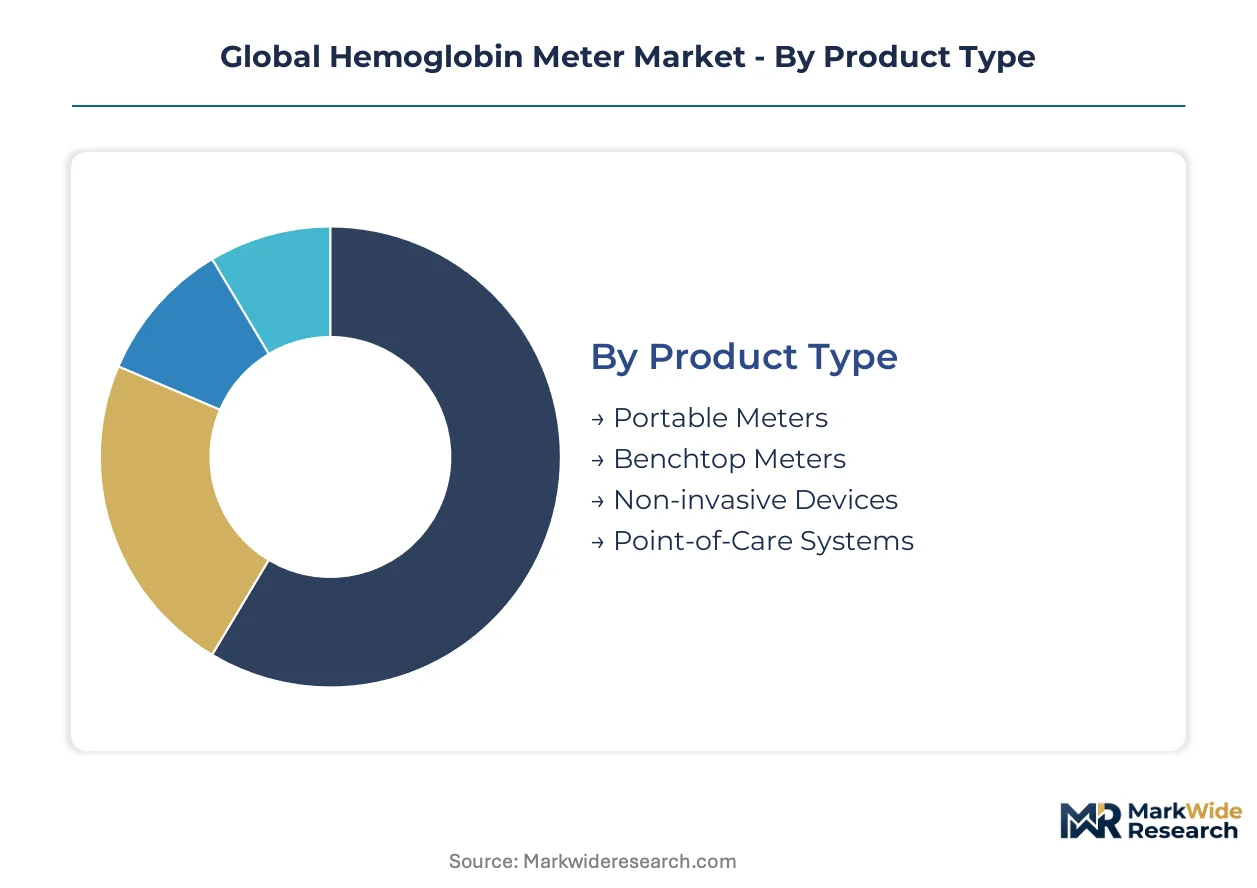
Segmentation in hemoglobin meters reveals divergent hardware requirements between centralized laboratory workflows and decentralized screening programs. Procurement patterns across ministries of health and private diagnostic chains favor different form factors, sensing technologies, and connectivity specifications.
Product Type:
Customization intensity varies sharply across this category, from standardized benchtop units for regulated laboratories to ruggedized portable designs engineered for field durability.
- Portable Meters:Battery-operated devices weighing under 500 grams utilize electrochemical strip chemistry or LED-photodiode optical engines. India's National Health Mission and Bangladesh's Directorate General of Health Services drive procurement through five-year consumable-locked tenders for maternal health camps.
- Benchtop Meters:Spectrophotometry-based systems with tungsten-halogen or xenon flash lamp sources achieve ISO 15197 traceability for accredited pathology reimbursement. German hospital systems consolidate procurement around embedded diagnostics platforms bundling hemoglobin with complete blood count workflows.
- Non-invasive Devices:Pulse-co-oximetry convergence devices from Masimo and similar manufacturers target critical care continuous monitoring.
- Point-of-Care Systems:Bluetooth-enabled units with cloud connectivity capture NGO contracts for remote anemia monitoring in Nepal and sub-Saharan Africa.
Leading the category by volume: Portable Meters. Expanding most quickly: Point-of-Care Systems.
Application:
Cost tiers separate mass screening programs from premium perioperative monitoring where reimbursement rates support higher device specifications.
- Anemia Screening:Population-scale programs in India and Nigeria mandate sub-$50 device pricing with 15-second turnaround. WHO prequalification criteria and CDSCO registration requirements filter supplier eligibility for national tender participation.
- Blood Donor Testing:Pre-donation hemoglobin thresholds require rapid finger-prick validation at collection centers. Red Cross and hospital blood bank networks in the United States and Germany specify FDA 510(k) or CE-marked devices with lot-level quality documentation.
- Perioperative Testing:Surgical workflows demand calibrated accuracy for transfusion decision support.
- Neonatal Monitoring:Low-birth-weight infant protocols require micro-volume sampling capability.
Highest procurement volume concentrates in Anemia Screening. Steepest expansion trajectory: Perioperative Testing.
End User:
Customer type determines connectivity requirements, calibration frequency, and regulatory documentation burdens.
- Pathology Laboratories:Accredited facilities in Germany and the United States require LIMS integration through HL7 interfaces and spectrophotometry calibration traceability to ISO standards. Benchtop meter suppliers face compressed margins from notified body audit cost inflation under EU MDR.
- Diagnostic Centers:Mid-scale urban facilities in Indian metropolitan areas balance throughput demands with space constraints, driving adoption of compact photometry-based systems.
- Mobile Health Clinics:Battery-operated portable meters with extended temperature stability serve village-level screening camps.
- Home Care Settings:Direct-to-consumer channels remain limited by prescription requirements and reimbursement gaps.
Pathology Laboratories anchor premium pricing. Mobile Health Clinics gain share fastest.
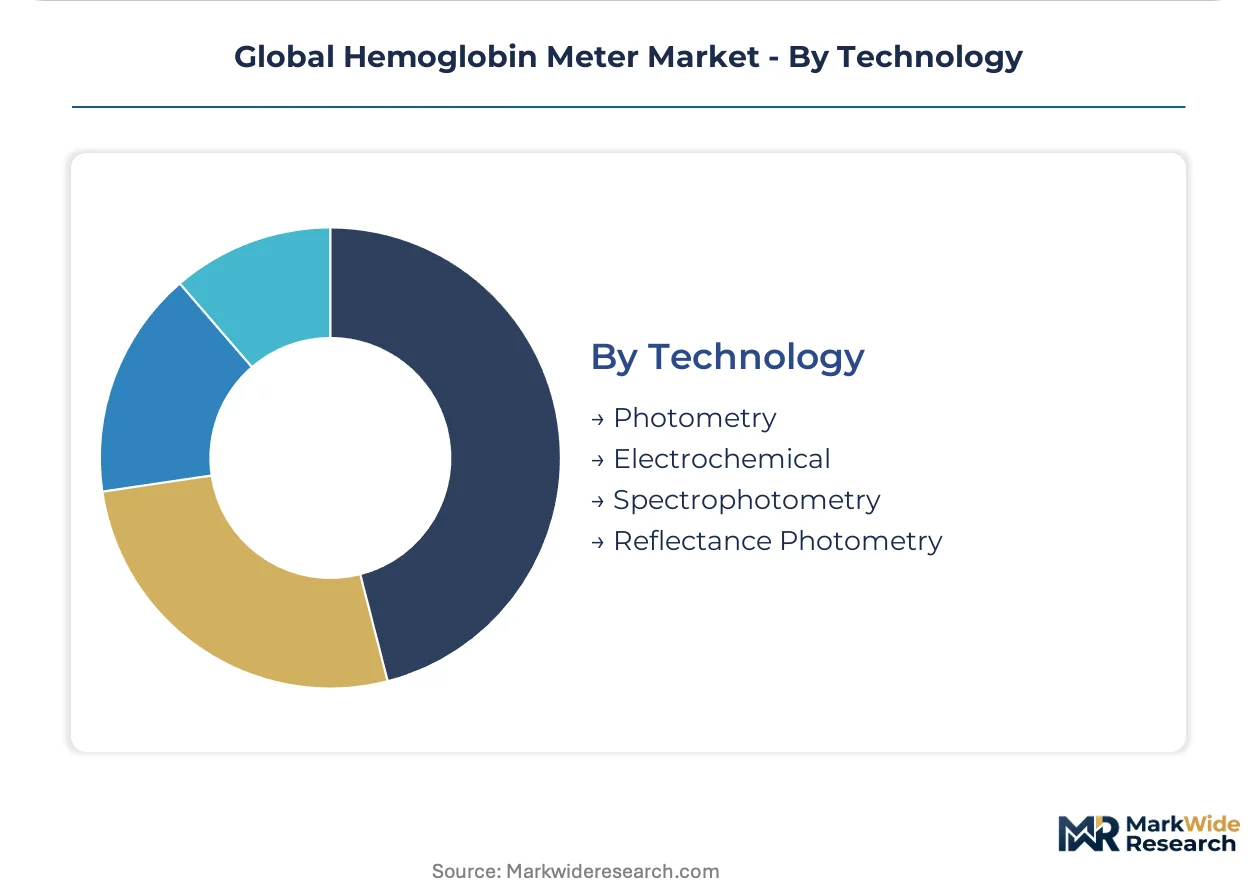
Technology:
Supply concentration in optical components creates margin pressure for photometry-dependent segments.
- Photometry:LED-photodiode architectures dominate portable meter production. Organic photodetector migration from silicon arrays reduces component costs while preserving spectral accuracy for next-generation devices.
- Electrochemical:Enzyme reagent strip formulations concentrate expertise among legacy Japanese and German manufacturers facing specialist retirement. CDSCO-registered Indian producers target WHO prequalification gaps in sub-Saharan Africa.
- Spectrophotometry:Tungsten-halogen and xenon flash sources with narrow-band filters supply benchtop laboratory accuracy.
- Reflectance Photometry:Strip-based colorimetric detection serves cost-sensitive point-of-care deployment.
Photometry leads by installed base. Electrochemical climbs the fastest on strip miniaturization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Health Mission procurement corridors and special economic zones for medical device assembly concentrate manufacturing partnerships around Chennai and Hyderabad. These zones attract CDSCO-registered producers seeking duty advantages on imported sensor modules.
United States
Hospital outpatient clinics and blood bank networks sustain demand for FDA 510(k)-cleared devices. The FDA's streamlined predicate device pathway accelerates clearance timelines for electrochemical strip meters. Texas and California house the largest concentrations of diagnostic distributors serving the Red Cross and regional hospital systems.
Germany
Accredited pathology laboratories in Bavaria and North Rhine-Westphalia drive benchtop meter procurement with stringent ISO 15197 traceability requirements. The EU MDR's clinical evidence mandates extend product launch timelines by 18-24 months. Siemens Healthineers anchors hospital-system contracts through embedded diagnostics platforms in Munich and Berlin clusters.
India
Maternal health camps and school screening programs under the National Health Mission sustain bulk procurement of sub-$50 portable meters. CDSCO import license conditions favor local assembly partnerships for devices distributed through central tender frameworks. Manufacturing concentrates in Maharashtra and Karnataka medical device parks.
China
Domestic producers supply township health centers with cost-optimized photometry-based units under NMPA Class II medical device registration. The country's dual carbon goals accelerate organic photodetector adoption in next-generation meter designs. Production clusters in Shenzhen and Suzhou integrate sensor module assembly with regional housing fabrication.
Brazil
ANVISA registration requirements filter supplier eligibility for Ministry of Health anemia screening tenders in the Northeast and Amazon regions. Blood bank networks in São Paulo and Rio de Janeiro specify lot-level quality documentation for pre-donation testing. Local distributors consolidate procurement around five-year consumable supply contracts.
Global Hemoglobin Meter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital-system contracts consolidating around embedded diagnostics platforms while resource-limited settings fragment across regional strip suppliers. The vendor base organizes into three archetypes: multinational platform integrators, regional consumable specialists, and emerging non-invasive technology developers. Competitive positioning hardens through strategic partnerships with ministry of health tender frameworks and backward integration into optical sensor production.
Within the multinational platform tier, Siemens Healthineers and Abbott Laboratories anchor hospital-system relationships across Germany and the United States. ARKRAY occupies a position among Japanese specialists focused on compact electrochemical formats. EKF Diagnostics exemplifies the European diagnostic fabricator archetype with emphasis on point-of-care validation standards.
| Leading Market Players |
|---|
| EKF Diagnostics |
| Nova Biomedical |
| Siemens Healthineers |
| Beckman Coulter |
| Masimo |
| Hemocue |
| ACON Laboratories |
| ARKRAY |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Backward integration into optical sensor production anchors pricing power for German and Japanese precision optics suppliers who control narrow-band filter manufacturing for spectrophotometry-based benchtop units. This captive supply structure enables premium pricing for accredited laboratory equipment while forcing portable meter assemblers to absorb component cost volatility through volume commitments.
Pricing Analysis
Volume concentrates in sub-$50 portable meters for ministry of health tenders while margins pool in ISO 15197-traceable benchtop systems for accredited pathology laboratories. Pricing stratifies across premium spectrophotometry calibration tiers, standard LED-photodiode portable units, and economy electrochemical strip devices. Cost compression in the portable tier intensifies because organic photodetector migration reduces component expenses. Mobile health clinics and rural screening programs exhibit the highest price sensitivity, whereas German hospital systems show lowest sensitivity due to bundled embedded diagnostics platform procurement.
Supply Chain Analysis
Dual-sourcing requirements for FDA 510(k) and CE marking compliance force manufacturers to qualify multiple precision optics suppliers across Germany, Japan, and South Korea. Narrow-band filters, silicon photodiode arrays, and enzyme reagent chemistries draw from concentrated specialist producers. Single-source vulnerability in retiring electrochemical formulation expertise threatens strip stability consistency. Distribution runs through ministry of health tender portals in India and Bangladesh, consolidated distributor networks in the United States, and embedded diagnostics platform contracts in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU In Vitro Diagnostic Regulation's clinical evidence requirements and post-market surveillance mandates erect a cost-of-compliance barrier that favors incumbents with established notified body relationships and penalizes undercapitalized entrants lacking validation infrastructure.
For Market Incumbents: Lock in hospital-system contracts through embedded diagnostics platform bundling that integrates hemoglobin testing with complete blood count workflows. Deepen backward integration into optical sensor production to defend against supply concentration risks from German and Japanese filter suppliers. Prioritize CDSCO registration and WHO prequalification to secure National Health Mission tender access in India before emerging competitors establish local assembly partnerships. For New Entrants and Emerging Players: Launch via telemedicine-integrated distribution models targeting NGO contracts for remote anemia monitoring in Nepal and Bangladesh where Bluetooth-enabled cloud connectivity remains underpenetrated. Exploit the sub-Saharan Africa procurement gap by pursuing WHO prequalification for point-of-care hemoglobin testing before established strip manufacturers adapt their validation portfolios. Anchor initial volume through five-year consumable-locked tender structures that mirror Bangladesh's single-window e-procurement consolidation. For Investors and Strategic Acquirers: Exit pathways concentrate in platform integrators with embedded diagnostics capabilities and regional consumable specialists holding CDSCO-registered manufacturing in Indian medical device parks. Long-term viability hinges on regulatory harmonization between ISO 15197 and WHO criteria reducing duplicate validation costs for multi-market deployment. Watch for FDA 510(k) pathway streamlining announcements as an inflection indicator for accelerated clearance timelines benefiting electrochemical strip meter portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend product launch timelines for European market access. |
| Hospital System Partnership | Siemens Healthineers anchors German contracts through embedded diagnostics platform bundling strategies. |
| Backward Integration | In-house production of optical sensors reduces dependency on German and Japanese precision optics suppliers. |
| Software Companion Development | Bluetooth-enabled cloud connectivity captures NGO contracts for remote anemia monitoring in South Asia. |
| Reimbursement Strategy | ISO 15197 traceability supports diagnostic reimbursement claims in accredited US and German laboratories. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation, and WHO prequalification assessment reports formed the secondary backbone for regulatory pathway mapping. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ministry of health procurement officers combined with secondary validation across customs records and tender databases. Bottom-up triangulation of device shipment data and top-down reconciliation against national anemia program budgets anchored volume estimates.
Historical trendline analysis of National Health Mission procurement volumes, Red Cross blood bank equipment refresh cycles, and German hospital system consolidation patterns informed the projection framework. Segmentation modeling spanned product type, application, end user, technology, and regional regulatory cluster dimensions. CAGRs derived from curve-fitting across the analysis window incorporated organic photodetector adoption curves and electrochemical strip miniaturization trajectories.
Regulatory harmonization delays, optical sensor supply disruptions, and tender framework consolidation shifts are the dominant revision risks to the outlook. Deviation in EU MDR implementation enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Thrombocytopenia Treatment Market
Hematology
Anemia Drugs Market
Hematology
Single Blood Drop Analysis Market
Hematology
At-Home Hematology Testing Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Hemoglobin Analyzer Market
Hematology
Hematologic Malignancies Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Neutropenia Treatment Market
Hematology
Alpha Thalassemia Market
Hematology
Haematocrit Centrifuge Market
Hematology
Multiple Myeloma Market