
 Hemoglobin Testing Systems Market | 2026-2036
Hemoglobin Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobin Testing Systems Market Analytics
Asian medical device manufacturers is pivoting toward compact, battery-operated hemoglobin meters for rural clinics. Siemens Healthineers leverages its diagnostic automation platform to sustain installed-base loyalty across European hospital networks. Abbott Laboratories anchors its position through integrated consumable-analyzer ecosystems in emerging markets. Danaher competes on regulatory breadth, maintaining FDA, EMA, and NMPA clearances simultaneously across its hematology portfolio.
Hemoglobin testing systems quantify blood hemoglobin concentration through photometric, chromatographic, or electrophoretic methods, typically reporting results in grams per deciliter with precision thresholds of ±0.5 g/dL for clinical-grade devices. These instruments serve anemia diagnostics, transfusion medicine, and chronic disease monitoring across inpatient, outpatient, and field-deployed settings. Point-of-care devices command expanding share as decentralized screening programs replace laboratory-dependent workflows, while laboratory analyzers retain margin concentration in reference settings demanding HPLC-based hemoglobin variant identification. Spectrophotometry leads technology adoption for routine screening, though electrophoresis and HPLC dominate thalassemia and sickle cell disease testing where variant resolution matters.
The US FDA's 510(k) and CLIA waiver pathways shape product development priorities, pushing manufacturers toward simplified operation protocols for waived-complexity classification. India's CDSCO and the EMA's In Vitro Diagnostic Regulation impose divergent clinical evidence requirements, fragmenting registration timelines and constraining single-SKU global strategies. Stakeholders must monitor evolving anemia screening mandates from WHO member states and calibrate distribution investments toward countries formalizing universal hemoglobin screening in maternal health programs.
Market Dynamics
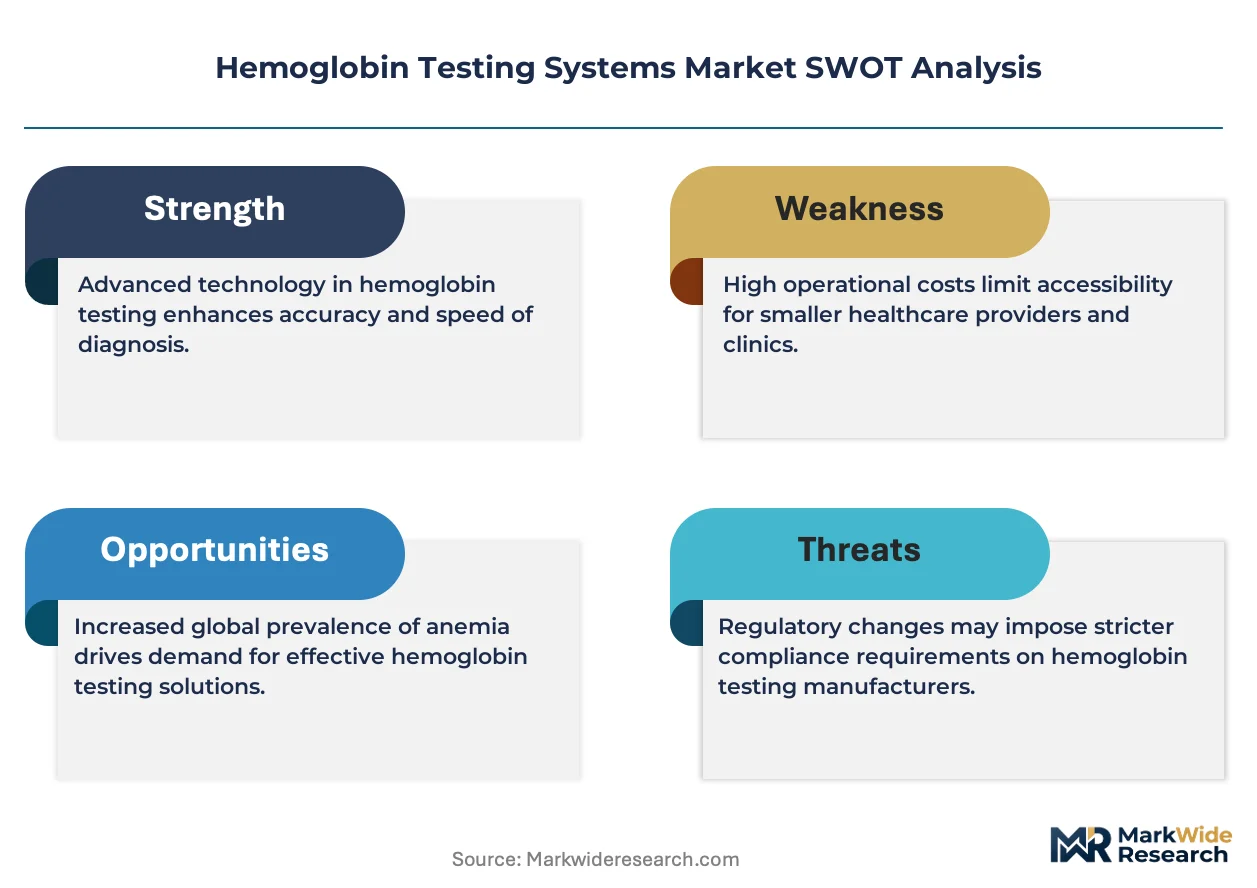
Point-of-care hemoglobin testing is absorbing screening volume from centralized laboratories as national anemia programs mandate decentralized diagnostics. The US FDA's CLIA waiver pathway accelerates this shift by lowering operational barriers for non-laboratory settings.
Growth Catalysts
- India's National Anemia Mukt Bharat Strategy:The program mandates hemoglobin screening for adolescents and pregnant women, driving procurement of portable battery-operated analyzers into 600,000+ sub-health centers.
- HPLC technology:Thalassemia and sickle cell disease screening programs in Mediterranean and Southeast Asian countries require variant resolution that photometric methods cannot deliver.
- WHO hemoglobin thresholds:Standardized diagnostic cutoffs for anemia classification enable interoperability between devices and simplify procurement specifications for ministries of health.
Market Restraints
- Reagent supply concentration:Lyophilized hemoglobin controls and calibrators depend on a narrow supplier base in Germany and the United States, creating vulnerability to batch shortages.
- EMA's In Vitro Diagnostic Regulation:The 2022 classification rules reclassify many hemoglobin meters as Class C devices, extending conformity assessment timelines and freezing some product registrations.
- Optical interference limitations:Spectrophotometric methods face accuracy degradation in high-lipidemia or hemolysis samples, limiting deployment in emergency settings without sample quality controls.
Strategic Opportunities
- Sub-Saharan Africa primary care networks:Less than 15% of rural clinics maintain cold-chain logistics for laboratory reagents, creating white space for ambient-temperature-stable cartridge systems.
- Telemedicine-integrated devices:Bluetooth-enabled meters that stream results to national health information systems satisfy emerging data requirements for conditional cash transfer programs in Latin America.
- Japan's metabolic syndrome screening expansion:Revised health checkup guidelines now include hemoglobin assessment for working-age adults, opening institutional volume previously concentrated in anemia-focused markets.
Industry Challenges
- CLIA waiver operational validation:Manufacturers must demonstrate that untrained operators achieve equivalent precision to laboratory technicians, requiring extensive usability studies that extend development timelines.
- Legacy LIS integration:Hospital information systems in emerging markets often lack HL7 FHIR compatibility, forcing custom middleware development for each deployment.
- Biomarker multiplexing complexity:Combined glucose-hemoglobin devices face conflicting regulatory pathways—blood glucose meters follow ISO 15197 while hemoglobin analyzers fall under IVD directive—creating certification friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobin Testing Systems Market |
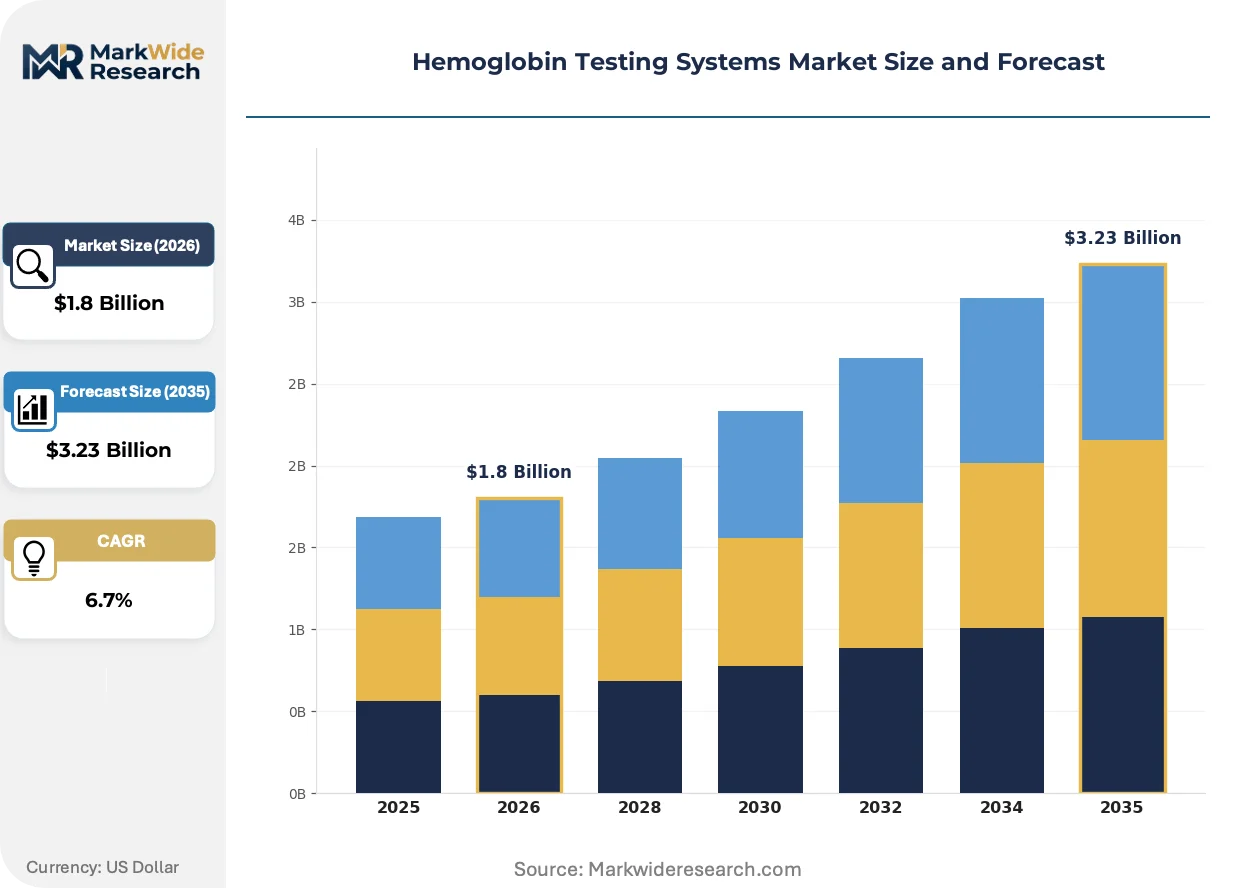
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Desktop Analyzers, Laboratory Analyzers, Point-of-Care Devices End User: Hospitals, Clinics, Blood Banks, Home Care Settings Technology: Colorimetric, Electrophoresis, HPLC, Spectrophotometry Application: Anemia Diagnosis, Thalassemia Screening, Sickle Cell Disease Testing, Blood Donation |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, F. Hoffmann-La Roche, Bio-Rad Laboratories, Danaher, EKF Diagnostics, Thermo Fisher Scientific, Mindray Medical International, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobin Testing Systems Market Evolving Landscape
Non-invasive hemoglobin monitoring is absorbing development resources from invasive methods, though photoplethysmography accuracy limitations constrain clinical adoption. Device architectures are converging around smartphone-connected form factors that eliminate dedicated display hardware.
Microfluidic cartridge systems are absorbing manufacturing investment as Asian contract manufacturers scale roll-to-roll lamination for disposable test strips. Blood banks in South Korea and Australia are piloting these platforms for donor screening, compressing turnaround times from 15 minutes to under 90 seconds. The technology is absorbing quality control functions previously performed by separate laboratory analyzers.
The EU's In Vitro Diagnostic Regulation is forcing redesigns of legacy hemoglobinometer portfolios as Class A and B self-certification routes disappear. Manufacturers must now engage notified bodies for technical documentation review, extending time-to-market by 12-18 months for routine screening devices. Small and mid-sized device firms are responding by narrowing product ranges to focus on highest-margin HPLC systems where premium pricing offsets certification costs.
Renal dialysis centers are consolidating hemoglobin testing into multi-parameter platforms that bundle electrolyte and hematocrit analysis. This bundling displaces standalone meters in outpatient nephrology settings across Germany and the United States. The shift is most visible in vertically integrated dialysis provider networks that negotiate system-wide analyzer contracts rather than device-by-device procurement.
Hemoglobin Testing Systems Market Segmentation
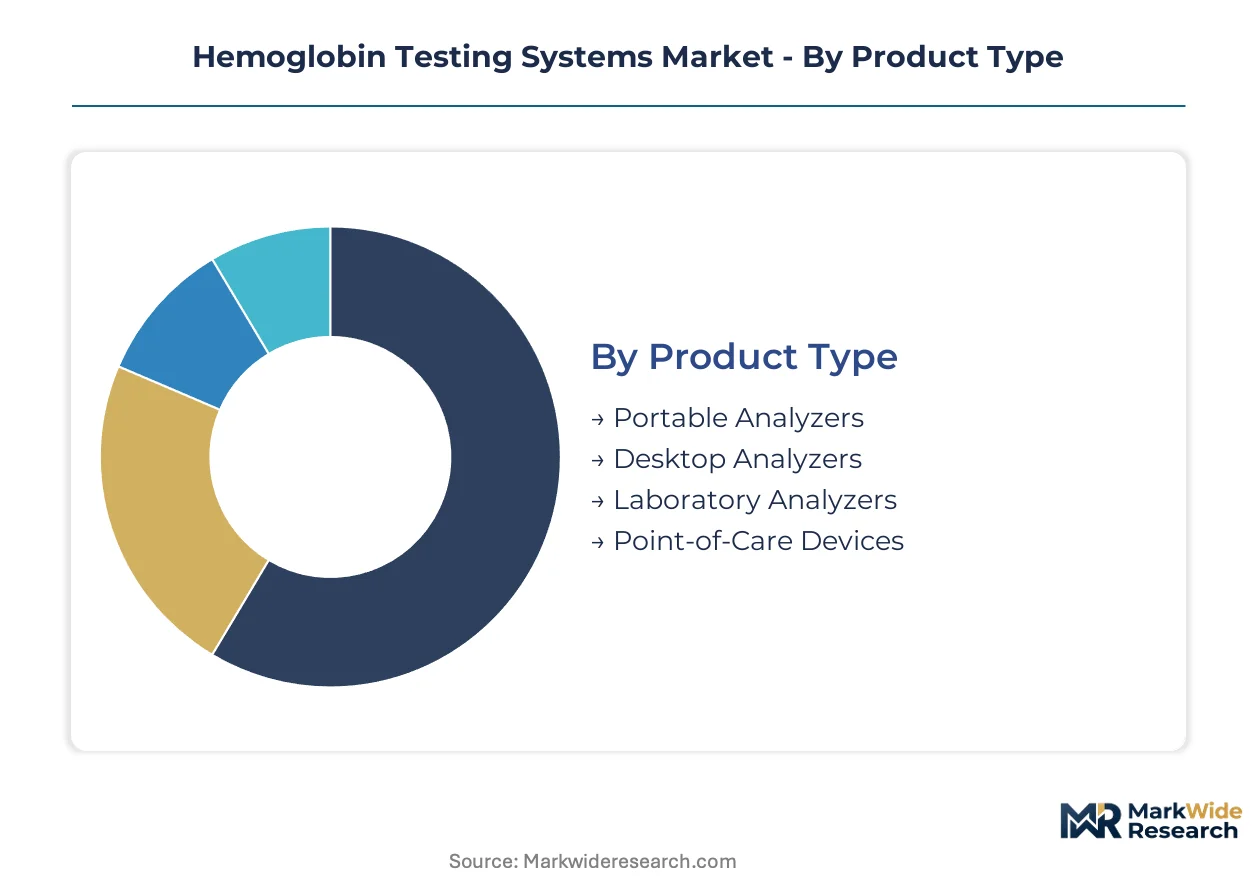
Device architecture and testing environment dictate procurement patterns across the hemoglobin testing landscape. Procurement committees weigh throughput requirements against regulatory classification, while decentralized screening programs favor portability over laboratory precision.
Product Type:
Volume concentration separates reference laboratories from field-deployed screening networks, with cost-per-test economics driving divergent hardware preferences.
- Portable Analyzers:Battery-operated units weighing under 500 grams deliver photometric results within 30 seconds. India's National Anemia Mukt Bharat Strategy deploys these across 600,000 sub-health centers where cold-chain logistics fail. These devices absorb the fastest volume expansion as WHO member states formalize universal maternal hemoglobin screening.
- Point-of-Care Devices:CLIA-waived instruments with touchscreen protocols enable operation by auxiliary health workers without laboratory training. The US FDA's 510(k) pathway prioritizes simplified workflows for waived-complexity classification, accelerating commercialization timelines for manufacturers targeting non-laboratory settings. These units are gaining share fastest in Latin American conditional cash transfer programs requiring rapid eligibility verification.
- Desktop Analyzers:Mid-throughput systems serve district hospitals with 50-200 daily sample volumes.
- Laboratory Analyzers:High-precision HPLC platforms dominate reference settings requiring hemoglobin variant resolution.
Laboratory analyzers lead volumes today; point-of-care devices are gaining share fastest.
End User:
Institutional purchasing power concentrates in vertically integrated networks, while fragmented primary care drives price sensitivity.
- Hospitals:Inpatient wards and emergency departments demand multi-parameter platforms bundling electrolyte and hematocrit analysis. German and US dialysis provider networks negotiate system-wide contracts that displace standalone meters. These facilities retain margin concentration through premium pricing for STAT turnaround requirements.
- Blood Banks:Donor screening operations in South Korea and Australia pilot microfluidic cartridge systems compressing turnaround from 15 minutes to 90 seconds. Quality control functions previously performed by separate analyzers now integrate into disposable test strip architectures, reducing capital expenditure for high-volume collection centers.
- Clinics:Outpatient settings prioritize compact footprint and minimal maintenance protocols.
- Home Care Settings:Self-monitoring applications remain limited by regulatory barriers to unsupervised HbA1c correlation.
Hospitals command the largest installed base; blood banks show steepest expansion trajectory.
Technology:
Method selection hinges on whether routine screening or variant identification determines clinical utility.
- Spectrophotometry:LED-based absorbance measurement at 540nm dominates routine anemia screening for cost efficiency and reagent stability. India's CDSCO procurement specifications favor these systems for ambient-temperature deployment in rural clinics lacking climate-controlled storage. The technology faces accuracy degradation in lipemic samples, constraining emergency department adoption.
- HPLC:Cation-exchange chromatography resolves hemoglobin variants with quantitative precision required for thalassemia and sickle cell disease diagnosis. Mediterranean and Southeast Asian screening programs mandate this capability where photometric methods fail. EMA's In Vitro Diagnostic Regulation extends conformity timelines for these Class C devices, freezing some product registrations.
- Colorimetric:Chemical reaction-based methods persist in resource-limited settings for lowest capital cost.
- Electrophoresis:Gel-based separation retains niche applications for research and confirmatory testing.
Spectrophotometry leads volumes today; HPLC commands premium expansion in variant-screening markets.
Application:
Diagnostic purpose shapes sensitivity requirements and reimbursement pathways.
- Anemia Diagnosis:Quantitative hemoglobin threshold determination supports WHO classification protocols for mild, moderate, and severe deficiency. Standardized cutoffs enable interoperability between devices and simplify ministry of health procurement specifications across divergent manufacturer platforms.
- Blood Donation:Pre-donation hemoglobin screening prevents deferral of iron-deficient donors while maintaining collection efficiency.
- Thalassemia Screening:Carrier detection programs in Cyprus, Sardinia, and Southeast Asia require HbA2 quantification.
- Sickle Cell Disease Testing:Newborn screening mandates in the United States and expanding African programs drive HPLC and isoelectric focusing demand.
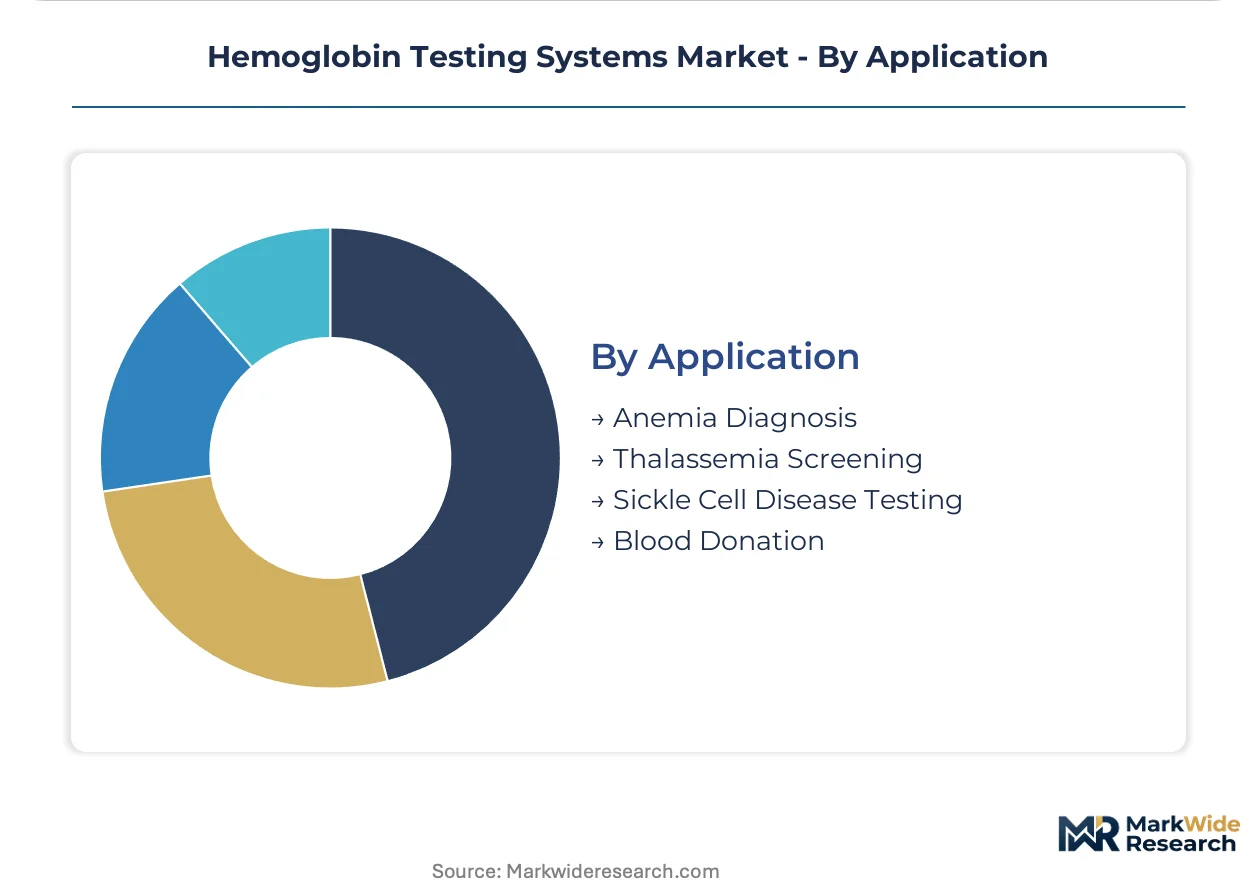
Anemia diagnosis leads volumes today; sickle cell disease testing is expanding most quickly in sub-Saharan African pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined IVD certification pathways. Cost-of-compliance gaps between the FDA's 510(k) process and EMA's IVDR implementation are accelerating this geographic rebalancing.
United States
Blood bank networks and dialysis provider chains drive institutional procurement of CLIA-waived devices. The FDA's streamlined 510(k) pathway compresses commercialization timelines for manufacturers targeting decentralized screening settings. Boston and San Diego clusters host development operations focused on smartphone-integrated meter architectures.
Germany
Reference laboratories in university hospital networks sustain demand for HPLC-based variant resolution systems. EMA's IVDR reclassification of hemoglobin meters as Class C devices has extended conformity timelines, freezing some product registrations. The Rhine-Ruhr industrial corridor concentrates reagent manufacturing for lyophilized controls serving European distribution.
India
The National Anemia Mukt Bharat Strategy mandates hemoglobin screening across 600,000 sub-health centers, driving portable analyzer procurement. CDSCO procurement specifications favor ambient-temperature-stable systems for rural deployment lacking cold-chain logistics. Hyderabad and Bengaluru clusters assemble battery-operated devices for government tender fulfillment.
Japan
Revised metabolic syndrome screening guidelines now include hemoglobin assessment for working-age adults, expanding institutional volume beyond traditional anemia markets. PMDA regulatory requirements maintain stringent clinical evidence standards for device registration. The Kanto region around Tokyo concentrates distribution infrastructure for hospital network procurement.
Brazil
Conditional cash transfer programs require rapid hemoglobin verification for beneficiary eligibility, accelerating point-of-care adoption. ANVISA regulatory pathways for IVD devices remain fragmented across state-level implementation. São Paulo's medical device corridor serves as the regional hub for Latin American distribution and technical service operations.
Hemoglobin Testing Systems Market Competitive Landscape
United States-based conglomerates anchor one tier through diagnostic automation platforms; European specialists hold position in HPLC variant-resolution systems. Market structure consolidates around integrated consumable-analyzer ecosystems that lock in installed-base loyalty. Three archetypes dominate: diversified healthcare conglomerates with hematology portfolios, pure-play diagnostic specialists, and Asian contract manufacturers scaling disposable cartridge production. Competitive moves concentrate on regulatory breadth maintenance and geographic expansion into anemia-screening mandate jurisdictions.
Among diversified healthcare conglomerates, Abbott Laboratories and Siemens Healthineers exemplify the integrated-platform archetype, anchoring positions through consumable-analyzer ecosystems. Danaher occupies a position emphasizing simultaneous FDA, EMA, and NMPA clearances across hematology portfolios. These three represent the regulatory-breadth strategy that smaller specialists struggle to replicate.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| F. Hoffmann-La Roche |
| Bio-Rad Laboratories |
| Danaher |
| EKF Diagnostics |
| Thermo Fisher Scientific |
| Mindray Medical International |
| Sysmex Corporation |
| Others |
Value Network & Pricing Analysis
Microfluidic cartridge manufacturing is concentrating production investment in Asian contract manufacturers, simultaneously compressing per-unit production costs and consolidating supplier power among roll-to-roll lamination specialists in South Korea and Taiwan. This technology transition rewards scaled producers while fragmenting pricing power for legacy analyzer vendors dependent on discrete component sourcing.
Pricing Analysis
Distributor margins in emerging markets absorb 25-35 percent of end-user pricing, compressing manufacturer netbacks for portable analyzers tendered to India's National Anemia Mukt Bharat Strategy. Three-tier pricing structure across premium HPLC, standard desktop, and economy portable tiers differentiates primarily by certification grade and after-sales service bundling. Pricing pressure stems from government procurement aggregation in India and Brazil, where single-tender volumes exceed 50,000 units. Blood banks and vertically integrated dialysis networks exhibit lowest price sensitivity, prioritizing throughput and LIS integration over per-test economics.
Supply Chain Analysis
Regional distribution centers in Singapore and Dubai serve as hub-and-spoke nodes for Middle Eastern and Southeast Asian markets, reducing lead times for lyophilized reagents requiring climate-controlled transit. Manufacturing concentrates in Germany for HPLC systems, the United States for CLIA-waived devices, and India for battery-operated portable units. Raw material dependencies include optical filters from Japan, precision pumps from Switzerland, and lyophilized hemoglobin controls from German chemical suppliers. Single-source vulnerability in hemoglobin calibrator production creates batch shortage risk. Distribution runs through medical device distributors with diagnostic specialization, though direct-to-hospital contracts are gaining share in German and US institutional networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into structural demand, with EMA's IVDR reclassification and India's anemia screening mandate together creating procurement velocity that favors prepared vendors.
For Market Incumbents: Cement installed-base loyalty through consumable-analyzer ecosystem lock-in, particularly in European hospital networks where IVDR compliance costs freeze competitor entry. Defend against Asian contract manufacturers by accelerating backward integration into microfluidic cartridge production. Prioritize simultaneous FDA, EMA, and NMPA certification maintenance as the primary competitive moat.
For New Entrants and Emerging Players: Launch via ambient-temperature-stable cartridge systems targeting sub-Saharan African primary care networks where cold-chain logistics fail. White space concentrates in telemedicine-integrated devices streaming results to national health information systems for Latin American conditional cash transfer programs. Avoid direct competition in HPLC variant-resolution systems where regulatory barriers and incumbent concentration are highest.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale diagnostic specialists with differentiated CLIA-waiver capabilities because fragmented regulatory consulting costs burden standalone firms. Five-to-ten year viability hinges on exposure to anemia-screening mandate jurisdictions rather than discretionary hospital capital expenditure cycles. Signal to watch: WHO member state formalization of universal maternal hemoglobin screening protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Investment | EMA's Class C reclassification extends timelines, freezing registrations for unprepared competitors. |
| CLIA Waiver Pathway Pursuit | FDA's streamlined 510(k) process accelerates commercialization for non-laboratory settings. |
| Government Tender Participation | India's 600,000 sub-health center deployment creates volume concentration for qualified vendors. |
| Consumable Ecosystem Development | Integrated reagent-analyzer systems lock in recurring revenue and displace standalone competitors. |
| Bluetooth-Enabled Device Launch | Telemedicine integration satisfies emerging data requirements for conditional cash transfer programs. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement records, and manufacturer production disclosures — were reconciled through bottom-up and top-down triangulation. Primary interviews with biomedical engineers, GPO contracts managers, hematology laboratory directors, and ministry of health procurement officers informed operational assumptions. Secondary validation drew from FDA 510(k) clearances, EMA IVDR technical documentation, CDSCO tender awards, and WHO anemia screening policy directives. Cross-referencing shipment data with installed-base estimates tested volume assumptions.
Data-stream reconciliation applied segment-specific growth drivers across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to procurement velocity in mandate-driven versus discretionary purchase environments. Modeled inputs included government screening program budget allocations, CLIA waiver approval trajectories, and microfluidic manufacturing capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR implementation delays or hemoglobin calibrator supply disruptions. Forecasts reflect documented assumptions about regulatory pathway efficiency and procurement program execution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Global Hematology Market
Hematology
Idiopathic Thrombocytopenic Purpura Market
Hematology
Hematopoietic Agents Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Heparin-Induced Thrombocytopenia (HIT) Treatment Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Blood Plasma Market
Hematology
Multiple Myeloma Therapeutics Market
Hematology
Multiple Myeloma Market
Hematology
Alpha Thalassemia Market
Hematology
Global Hemoglobin Meter Market
Hematology
Polycythemia Vera Market
Hematology
Global Hematology Diagnostics Market
Hematology
Sickle Cell Treatment Market