
 Graft Versus Host Disease (Gvhd) Treatment Market | 2026-2036
Graft Versus Host Disease (Gvhd) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Graft Versus Host Disease (Gvhd) Treatment Market Intelligence
The end-use vertical mix across hospital transplant centers and specialty clinics is broadening as outpatient administration protocols gain traction. Novartis AG leverages its transplant medicine heritage to sustain leadership in immunomodulatory development. Pfizer Inc. anchors its position through corticosteroid access and global distribution scale. Incyte Corporation differentiates via JAK inhibitor specialization in steroid-refractory patient subsets.
Graft Versus Host Disease constitutes an immune-mediated complication wherein donor T cells attack recipient tissues following allogeneic hematopoietic stem cell transplantation, with severity graded by organ involvement and histopathological confirmation. The condition demands immunosuppressive intervention to prevent organ failure and mortality in transplant recipients. Monoclonal antibodies capture expanding share as targeted biologics displace broad immunosuppression in steroid-refractory cases, while the injectable formulation segment dominates due to inpatient administration requirements during acute phases. Immune modulators represent the fastest-expanding product category as novel mechanisms address unmet need in chronic GvHD.
FDA accelerated approval designations and EMA conditional marketing authorizations compress development timelines for novel biologics, while REACH frameworks govern excipient and manufacturing chemical standards for European supply. The country's national pharmaceutical regulator in Japan applies distinct efficacy benchmarks that shape regional clinical trial investment. Stakeholders must monitor evolving payer evidence requirements for chronic versus acute GvHD indications to align pipeline prioritization with reimbursement access.
Market Dynamics
FDA and EMA accelerated approval pathways compress development timelines for novel biologics, forcing incumbent immunomodulatory developers to accelerate pipeline investments or cede position in steroid-refractory segments.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA conditional marketing authorization designations compress phase III-to-launch intervals for JAK inhibitors and monoclonal antibodies in refractory GvHD.
- Transplant Center Expansion:Hematopoietic stem cell transplant centers in the United States, Germany, and Japan are broadening prophylactic immunomodulatory protocol adoption to reduce acute GvHD incidence.
- Biologics Manufacturing Scale:Single-use bioreactor technology and continuous processing advances are reducing cost-per-dose for targeted monoclonal antibody production.
Market Restraints
- Plasma-Derived Protein Volatility:Immunoglobulin and albumin input costs fluctuate with donor collection volumes, compressing margin stability for plasma-dependent prophylactic therapies.
- Specialized Manufacturing Concentration:Contract manufacturing for complex biologics concentrates among CDMO clusters in Switzerland and Ireland, creating single-source vulnerability for European supply.
- Substitution by Cellular Therapies:Engineered T-cell and regulatory T-cell approaches threaten long-term displacement of pharmacologic GvHD prophylaxis in select transplant protocols.
Strategic Opportunities
- Chronic GvHD Underpenetration:Japan and South Korea present white space for fibrosis-targeted therapies where chronic GvHD diagnosis rates trail Western transplant centers.
- Outpatient Administration Shift:Subcutaneous formulation development for JAK inhibitors and monoclonal antibodies enables specialty clinic channel expansion beyond hospital transplant centers.
- REACH Excipient Harmonization:ECHA chemical safety data requirements for novel formulation components create first-mover advantage for sponsors with pre-validated excipient portfolios.
Industry Challenges
- Histopathology Specialist Scarcity:GvHD diagnosis requires dermatopathology and gastrointestinal pathology expertise concentrated at academic medical centers, creating diagnostic bottleneck.
- Bioreactor Capital Intensity:Commercial-scale mammalian cell culture facilities demand nine-figure capital deployment with five-year construction timelines, constraining capacity expansion.
- Multinational Trial Complexity:Divergent efficacy endpoints between FDA, EMA, and PMDA necessitate parallel protocol designs, inflating registrational study costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graft Versus Host Disease (Gvhd) Treatment Market |
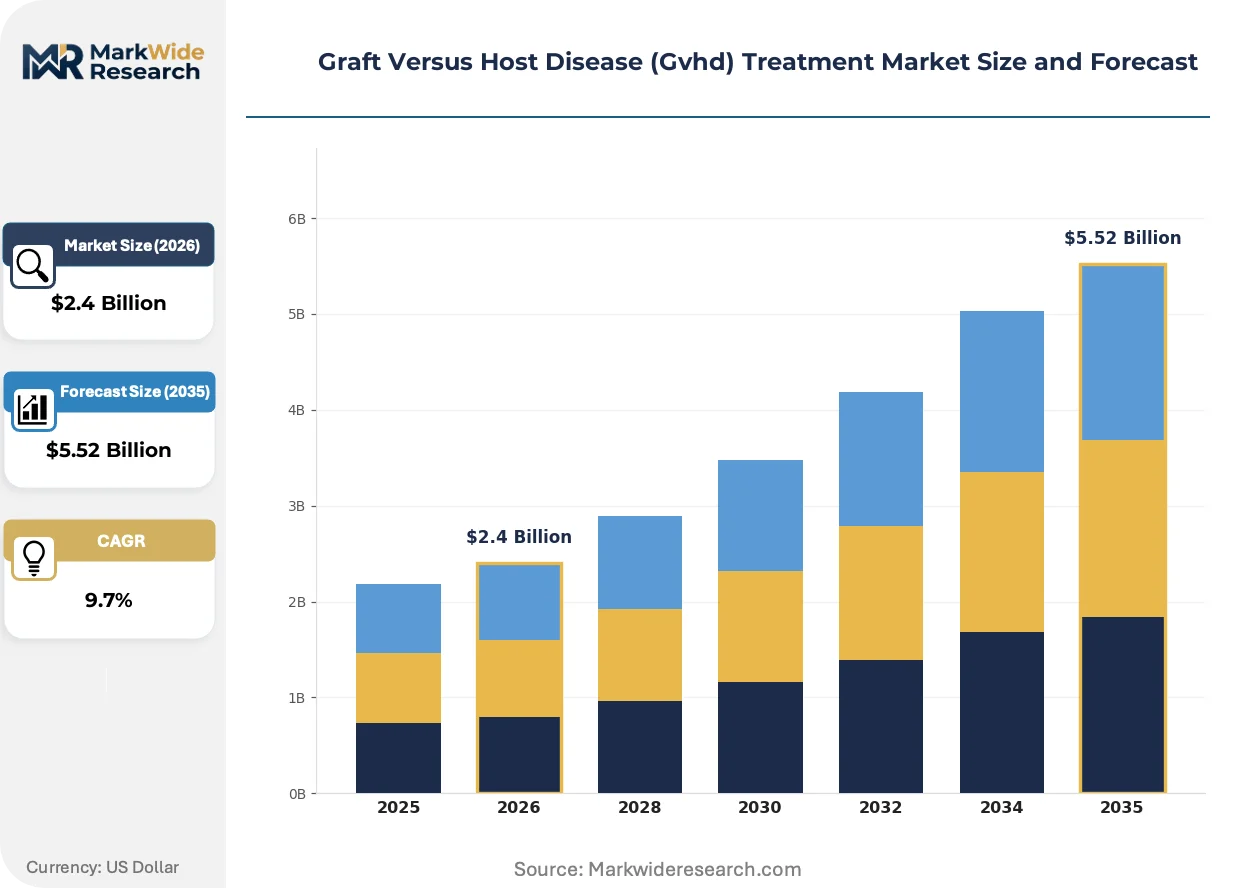
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Antimicrobial Agents, Monoclonal Antibodies, Immune Modulators Therapy Area: Hematology, Oncology, Immunology, Transplantation End User: Hospitals, Specialty Clinics, Outpatient Centers, Research Laboratories Formulation: Injectable, Oral, Topical, Infusion |
| Companies Covered | Novartis AG, Pfizer Inc., Incyte Corporation, AbbVie Inc., Bristol-Myers Squibb Company, Astellas Pharma Inc., Sanofi, Merck KGaA, Janssen Global Services, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graft Versus Host Disease (Gvhd) Treatment Market Strategic Shifts & Innovations
Targeted biologics are displacing broad immunosuppression in steroid-refractory GvHD, while formulation innovation and regulatory pathway optimization reshape competitive entry economics.
Rockville-based biologics developers are rewriting treatment paradigms through JAK1/JAK2 inhibitor selectivity refinement. Transplant centers in the United States are adopting these agents at accelerating pace for steroid-refractory acute GvHD. This mechanism-based precision is compressing corticosteroid exposure duration and reducing infection-related mortality in high-risk patient subsets.
EMA conditional marketing authorization frameworks are compressing evidence requirements for life-threatening conditions with unmet need. Biologics sponsors are leveraging this pathway to secure European market access with phase II data packages. Chronic GvHD indications with fibrotic organ involvement are responding fastest, as histopathological endpoints satisfy accelerated review criteria.
Hospital transplant centers are unbundling inpatient-only administration protocols. Subcutaneous formulation development enables specialty clinic and home-based delivery for stable chronic GvHD patients. Germany and Japan exhibit the sharpest pivot toward ambulatory care models, driven by reimbursement pressure and patient preference alignment.
Graft Versus Host Disease (Gvhd) Treatment Market Segmentation
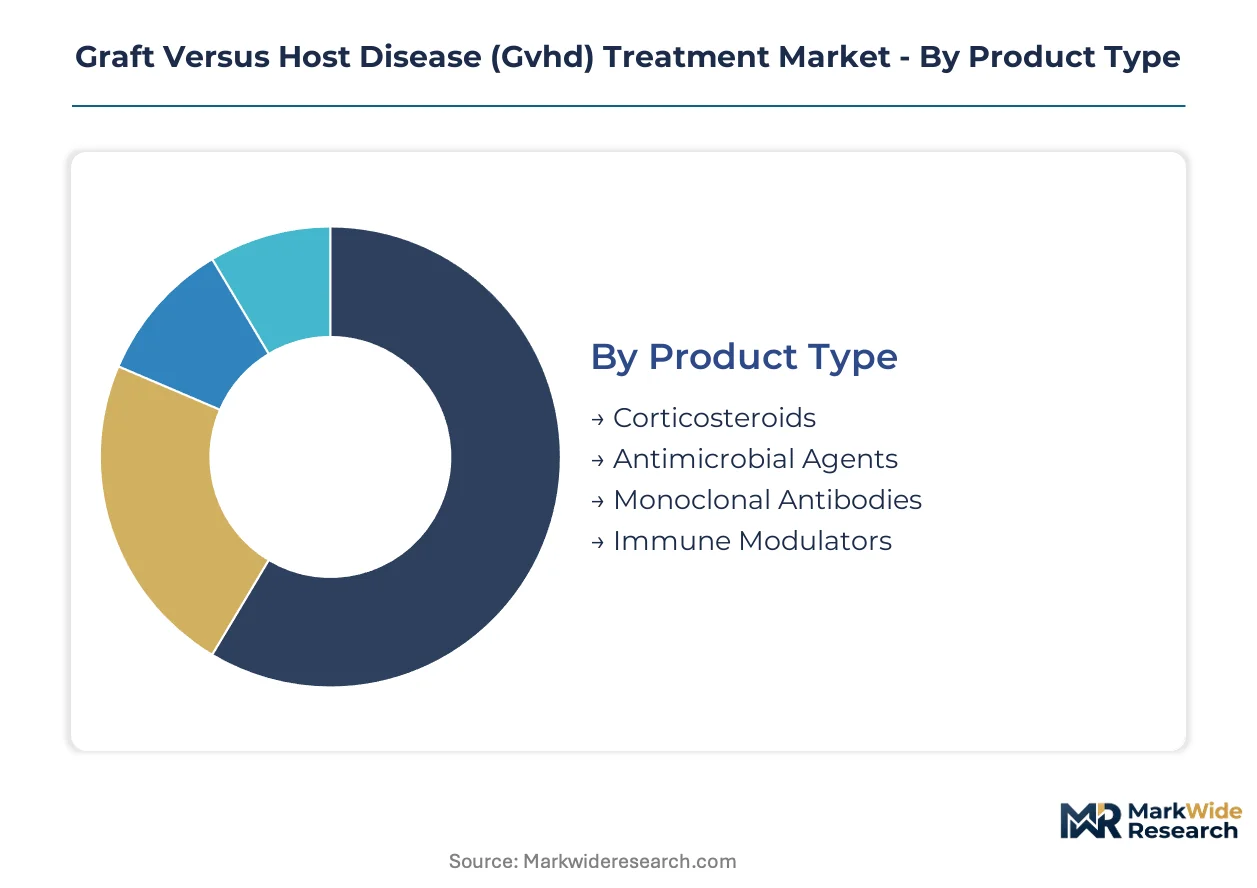
Graft Versus Host Disease treatment segments reveal divergent supply chain architectures, with biologics manufacturing concentration in mammalian cell culture facilities reshaping competitive economics across product categories. Transplant centers in the United States, Germany, and Japan drive differential demand patterns that fragment procurement strategies by end-use setting.
Product Type:
Supply concentration in plasma fractionation and recombinant biologics manufacturing creates divergent margin structures across therapeutic modalities.
- Corticosteroids:Synthetic glucocorticoid compounds with broad immunosuppressive action remain the first-line intervention for acute GvHD prophylaxis and induction. Hospital transplant centers in the United States anchor procurement volumes, though generic competition compresses pricing power for established molecules.
- Monoclonal Antibodies:Recombinant immunoglobulins targeting CD20, CD52, or TNF-alpha pathways deliver precision immunomodulation in steroid-refractory cases. CDMO clusters in Switzerland and Ireland concentrate fill-finish capacity, creating single-source vulnerability for European supply of these temperature-sensitive biologics.
- Antimicrobial Agents:Prophylactic antibacterial, antiviral, and antifungal compounds prevent opportunistic infection during immunosuppressive therapy.
- Immune Modulators:Small-molecule inhibitors and cytokine-directed therapies addressing JAK-STAT signaling pathways.
Today's leader: Corticosteroids. Tomorrow's challenger: Monoclonal Antibodies.
Therapy Area:
Clinical trial infrastructure and investigator expertise concentrate at academic medical centers with dual hematology-oncology specialization.
- Hematology:Allogeneic stem cell transplantation protocols and donor lymphocyte infusion procedures constitute the procedural foundation for GvHD pathophysiology. Transplant volume at centers in Germany and Japan determines regional prophylactic therapy demand intensity.
- Oncology:Malignancy treatment settings generate GvHD as treatment complication requiring concurrent immunosuppressive management. CAR-T and checkpoint inhibitor expansion at United States cancer centers creates overlapping immune-related adverse event expertise.
- Immunology:Autoimmune and primary immunodeficiency contexts where allogeneic transplantation addresses underlying disease.
- Transplantation:Solid organ and tissue transplant protocols with shared immunosuppressive regimen requirements.
Hematology commands current volume. Oncology presents the steepest expansion trajectory as cellular therapy toxicity management converges with GvHD expertise.
End User:
Reimbursement architecture and administration complexity determine channel concentration for acute versus chronic indication segments.
- Hospitals:Inpatient transplant centers manage acute GvHD with intravenous immunosuppression and intensive monitoring. Centers in the United States concentrate Medicare-reimbursed transplant volume, anchoring procurement scale for parenteral formulation suppliers.
- Specialty Clinics:Ambulatory hematology-oncology practices administer subcutaneous and oral maintenance therapy for chronic GvHD. Germany's outpatient reimbursement framework accelerates this channel's expansion relative to hospital-centric markets.
- Outpatient Centers:Infusion suites and day hospitals for intermediate-acuity administration.
- Research Laboratories:Academic and commercial sites conducting biomarker discovery and mechanism-of-action studies.
Hospital transplant centers dominate acute therapy. Specialty clinics are gaining share fastest as subcutaneous formulations enable ambulatory chronic GvHD management.
Formulation:
Stability requirements and administration setting constraints fragment manufacturing investment across delivery modalities.
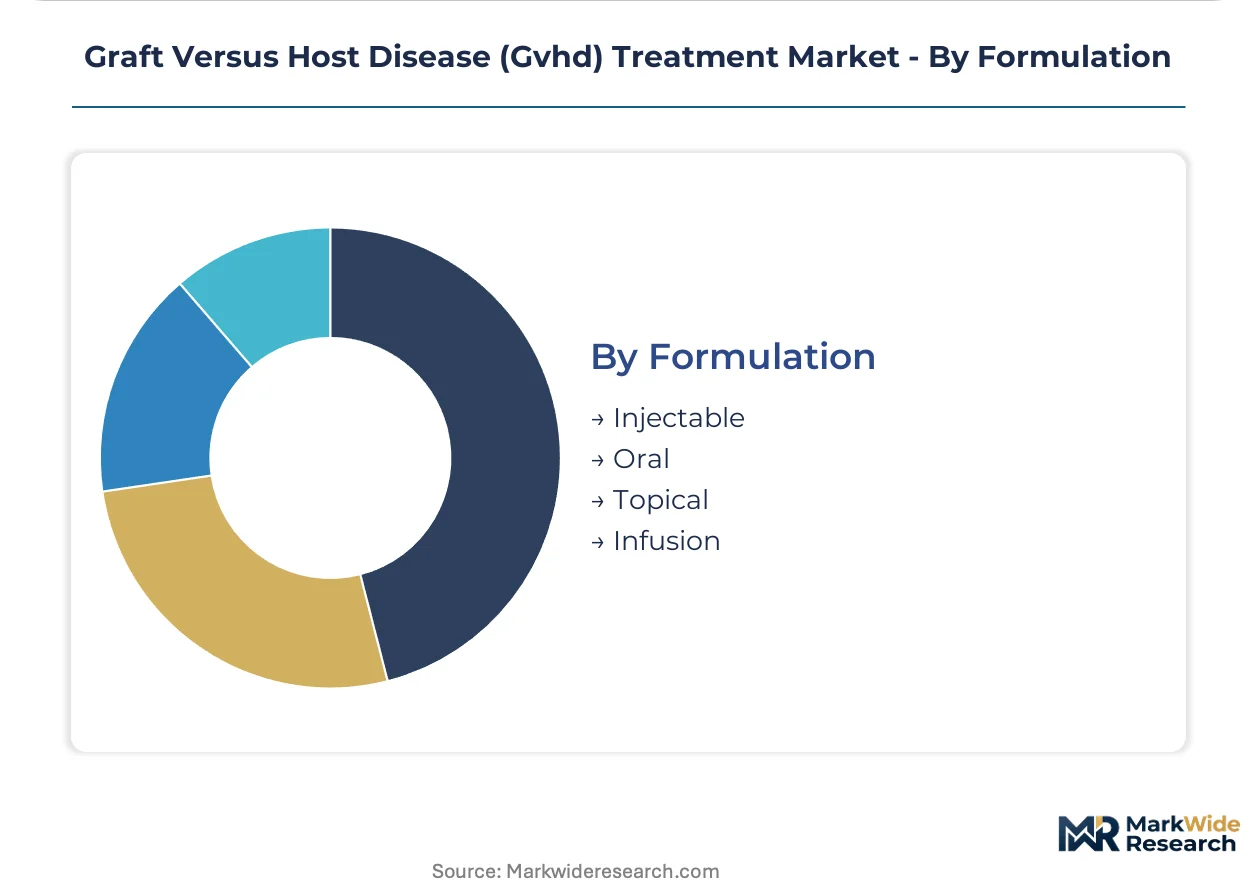
- Injectable:Parenteral formulations including intravenous bolus and continuous infusion dominate acute GvHD induction therapy. Cold chain distribution from manufacturing sites in Ireland and Switzerland to hospital pharmacies demands validated logistics infrastructure.
- Oral:Tablet and capsule presentations enable outpatient maintenance therapy with patient-administered dosing. Japan's PMDA bioequivalence requirements for narrow-therapeutic-index immunosuppressants create regional regulatory complexity for generic substitution.
- Topical:Cutaneous corticosteroid and calcineurin inhibitor preparations for limited skin GvHD.
- Infusion:Extended-duration parenteral delivery systems for prolonged immunosuppressive exposure.
Injectable formulations anchor current revenue. Oral presentations are climbing the fastest as chronic GvHD maintenance protocols extend treatment duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping biologics manufacturing location decisions, with REACH compliance costs in Europe and FDA accelerated approval fees in the United States creating divergent cost-of-entry calculations for GvHD therapy developers.
United States
Hospital transplant centers in the United States concentrate acute GvHD therapy procurement, with Medicare reimbursement anchoring volume scale. FDA breakthrough therapy designations compress development timelines for JAK inhibitors and monoclonal antibodies. Rockville-based biologics developers and Boston-area academic medical centers drive mechanism-based precision medicine adoption.
Germany
Germany's outpatient reimbursement framework accelerates specialty clinic channel expansion for chronic GvHD maintenance therapy. EMA conditional marketing authorization pathways enable European market access with phase II data packages. CDMO clusters in Switzerland and Ireland supply fill-finish capacity for temperature-sensitive biologics distributed to German hospital pharmacies.
Japan
Japan's transplant volume and chronic GvHD diagnosis rates trail Western centers, creating white space for fibrosis-targeted therapies. PMDA applies distinct efficacy benchmarks that shape regional clinical trial investment requirements. Tokyo and Osaka metropolitan areas concentrate hematology-oncology expertise and academic transplant center infrastructure.
Switzerland
Swissmedic governs marketing authorization for biologics manufactured in Basel and Zurich industrial clusters. Contract manufacturing concentration for complex monoclonal antibodies creates single-source supply vulnerability for European GvHD therapy distribution. Geneva-based pharmaceutical headquarters anchor strategic decision-making for immunomodulatory portfolio prioritization.
United Kingdom
NHS England reimbursement negotiations determine market access for novel biologics in steroid-refractory GvHD segments. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for life-threatening conditions. London and Cambridge research corridors concentrate biomarker discovery and mechanism-of-action study infrastructure.
Graft Versus Host Disease (Gvhd) Treatment Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbent immunomodulatory developers expand beyond corticosteroid franchises into targeted biologics. The market structure concentrates around large-cap pharmaceutical conglomerates with transplant medicine heritage, mid-cap biotech specialists in JAK-STAT pathway inhibition, and plasma fractionation incumbents with immunoglobulin supply advantages. Three archetypes define positioning: mechanism-driven biotech specialists, scale-oriented global distributors, and vertically integrated plasma processors. Capacity expansion in mammalian cell culture facilities and strategic partnerships for subcutaneous formulation development represent the dominant competitive moves.
Among large-cap pharmaceutical developers, Novartis AG and Pfizer Inc. exemplify divergent strategic postures within the immunomodulatory space. Novartis anchors its position through transplant medicine heritage and biologics manufacturing scale, while Pfizer leverages corticosteroid access and global distribution infrastructure. Incyte Corporation occupies a specialist position as a mechanism-focused developer refining JAK1/JAK2 inhibitor selectivity for steroid-refractory patient subsets.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Incyte Corporation |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Astellas Pharma Inc. |
| Sanofi |
| Merck KGaA |
| Janssen Global Services, LLC |
| Others |
Cost & Logistics Intelligence
Plasma protein input cost indices cascade through GvHD therapy manufacturing into three-tier pricing structures across premium biologics, standard immunomodulators, and economy corticosteroid tiers. Hospital transplant centers in the United States absorb premium markups for temperature-sensitive monoclonal antibodies, while German outpatient clinics drive cost compression in oral maintenance segments through reimbursement pressure.
Pricing Analysis
Distributor margin layers in European biologics distribution compress net realized prices for manufacturers by twelve to eighteen percentage points versus direct hospital contracting in the United States. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and cold chain requirements, with JAK inhibitors commanding brand premiums over generic corticosteroid alternatives. Pricing pressure stems from biosimilar entry in immunoglobulin segments, tightening margins for plasma-dependent prophylactic therapies. Specialty clinics exhibit highest price sensitivity due to fixed reimbursement caps, while academic medical centers demonstrate lowest sensitivity given research funding offsets.
Supply Chain Analysis
Mammalian cell culture inputs rest on Swiss and Irish CDMO clusters for fill-finish capacity of monoclonal antibodies used in steroid-refractory GvHD. Plasma-derived proteins, recombinant biologics, and synthetic small molecules constitute the core input dependencies. Single-source vulnerability concentrates in Basel-area manufacturing for temperature-sensitive biologics distributed across European hospital pharmacies. Distribution runs through cold chain logistics networks from manufacturing sites to hospital transplant centers, with specialty clinics emerging as secondary channel nodes for subcutaneous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA conditional marketing authorization fees in Europe run substantially below FDA breakthrough therapy program costs, creating geographic-arbitrage incentives for biologics sponsors prioritizing European market entry timelines.
For Market Incumbents: Acquire subcutaneous formulation capabilities to defend against outpatient channel displacement of inpatient-only biologics. Incumbent immunomodulatory developers must accelerate JAK inhibitor pipeline investments or cede steroid-refractory segments to mechanism-focused specialists. Backward integration into plasma fractionation secures immunoglobulin supply stability against donor collection volatility. For New Entrants and Emerging Players: Capture chronic GvHD maintenance therapy white space in Japan and South Korea where diagnosis rates trail Western transplant centers. Fibrosis-targeted mechanisms present the most penetrable therapeutic niche given unmet need in steroid-refractory fibrotic organ involvement. Go-to-market positioning through specialty clinic partnerships enables ambulatory administration protocols outside hospital-centric procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotech specialists refining JAK-STAT selectivity for narrow patient subsets. Long-term viability over the next decade hinges on cellular therapy displacement risk versus pharmacologic prophylaxis persistence. Watch engineered T-cell regulatory approval timelines as inflection signal for portfolio rebalancing between biologics and cell therapy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II data packages satisfy EMA conditional marketing authorization for chronic GvHD fibrosis indications. |
| Manufacturing Scale-Up | Single-use bioreactor deployment in Swiss CDMO clusters reduces monoclonal antibody cost-per-dose. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for JAK inhibitors in refractory acute GvHD. |
| Licensing Agreement | Subcutaneous formulation partnerships enable specialty clinic channel expansion beyond hospital transplant centers. |
| Pipeline Diversification | Fibrosis-targeted mechanisms address underpenetrated chronic GvHD segments in Japanese transplant protocols. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down epidemiological triangulation converged on segment-level demand estimates.
Bottom-up volume builds aggregated treatment episodes across acute and chronic indication segments, while top-down approaches calibrated aggregate market evolution over the projection horizon. Segmentation dimensions included product type, therapy area, end-user channel, and formulation route. CAGRs derived from log-linear trend fitting across modeled periods, with transplant volume growth and regulatory approval velocity as key forecast inputs.
Regulatory pathway delays, plasma supply disruptions, and cellular therapy substitution acceleration are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about approval timeline compression and reimbursement stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Febrile Neutropenia Market
Hematology
Blood Disorder Therapeutics Market
Hematology
Patient Blood Management Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Hemocytometer Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Alpha Thalassemia Market
Hematology
Blood Screening Market
Hematology
Sickle Cell Anemia Market