
 Global Kidney Cancer Diagnostics Market | 2026-2036
Global Kidney Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kidney Cancer Diagnostics Market Foresight
Hospital procurement of integrated diagnostics platforms is rotating toward molecular and biomarker-based workflows, displacing standalone imaging contracts. Thermo Fisher Scientific leverages its ion semiconductor sequencing infrastructure to anchor clinical laboratory partnerships across North America. Illumina competes through high-throughput next-generation sequencing panels purpose-built for solid tumor profiling. Roche Holding AG sustains dominance in immunohistochemistry companion diagnostics through captive antibody development and automated staining systems.
Kidney cancer diagnostics encompasses tissue-based, blood-based, and imaging modalities designed to detect renal cell carcinoma, characterize histologic subtype, and guide systemic therapy selection. Biomarker assays analyze circulating tumor DNA, protein expression, and epigenetic markers with analytical sensitivity thresholds reaching fractional variant allele frequencies below one percent. Molecular diagnostics commands the fastest expansion trajectory as payers gradually expand coverage for minimal residual disease monitoring and therapy response prediction. Imaging agents face margin compression from radiotracer supply constraints, while biopsy kits retain stable utilization tied to mandatory histologic confirmation.
The FDA regulates in vitro diagnostics through premarket approval and de novo pathways, while the EMA's In Vitro Diagnostic Regulation enforces stricter performance documentation and post-market surveillance across Europe. ISO 15189 accreditation shapes quality management demands for diagnostic laboratories seeking hospital network contracts. Japan's PMDA maintains distinct clinical evidence requirements for novel oncology biomarkers that delay market entry relative to Western timelines. Stakeholders must monitor reimbursement coding decisions for multi-cancer early detection tests, as these rulings will determine whether liquid biopsy platforms capture routine screening volumes or remain confined to confirmed-malignancy settings.
Market Dynamics
Hospital laboratory directors are consolidating vendor relationships around integrated molecular platforms that combine next-generation sequencing with automated pathology workflows, compressing procurement cycles and displacing standalone imaging contracts.
Growth Catalysts
- Liquid Biopsy Coverage Expansion:United States payers are extending reimbursement codes for circulating tumor DNA assays used in renal cell carcinoma monitoring, creating predictable revenue streams for clinical laboratories.
- EMA In Vitro Diagnostic Regulation:Stricter performance documentation requirements across Europe are accelerating quality differentiation, rewarding manufacturers with robust clinical evidence packages.
- Minimal Residual Disease Monitoring:Academic medical centers in Germany and Japan are embedding ctDNA surveillance into post-surgical care pathways for localized kidney cancer patients.
Market Restraints
- Radiotracer Supply Concentration:Production of gallium-68 and fluorine-18 imaging agents depends on a limited network of cyclotron facilities, creating vulnerability to regional shortages.
- PMDA Evidence Requirements:Japan's pharmaceutical regulator demands extended local clinical trials for novel oncology biomarkers, delaying commercial entry by 18-24 months versus Western markets.
- Pathologist Workforce Constraints:Specialized genitourinary pathologists concentrate in major metropolitan academic centers, limiting molecular diagnostic interpretation capacity in community settings.
Strategic Opportunities
- Multi-Cancer Early Detection Tests:Screening panels incorporating kidney cancer signals among 50+ malignancies could capture asymptomatic populations if United States reimbursement coding expands beyond confirmed-disease settings.
- AI-Enabled Digital Pathology:Deep learning algorithms trained on renal tumor histology are reducing inter-observer variability in subtype classification, opening deployment in resource-limited settings.
- India Diagnostic Infrastructure:Tier-2 city hospital networks are investing in centralized molecular reference laboratories to serve dispersed oncology practices lacking on-site sequencing capability.
Industry Challenges
- Bioinformatics Pipeline Integration:Community hospital laboratories struggle to embed variant interpretation workflows into existing laboratory information management systems without dedicated informatics personnel.
- ISO 15189 Accreditation Timelines:Quality management system certification for novel molecular assays requires 12-18 months of documented proficiency testing, delaying contract awards.
- Cross-Platform Data Harmonization:Disparate file formats between sequencing instruments and electronic health record systems impede longitudinal patient tracking across care transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kidney Cancer Diagnostics Market |
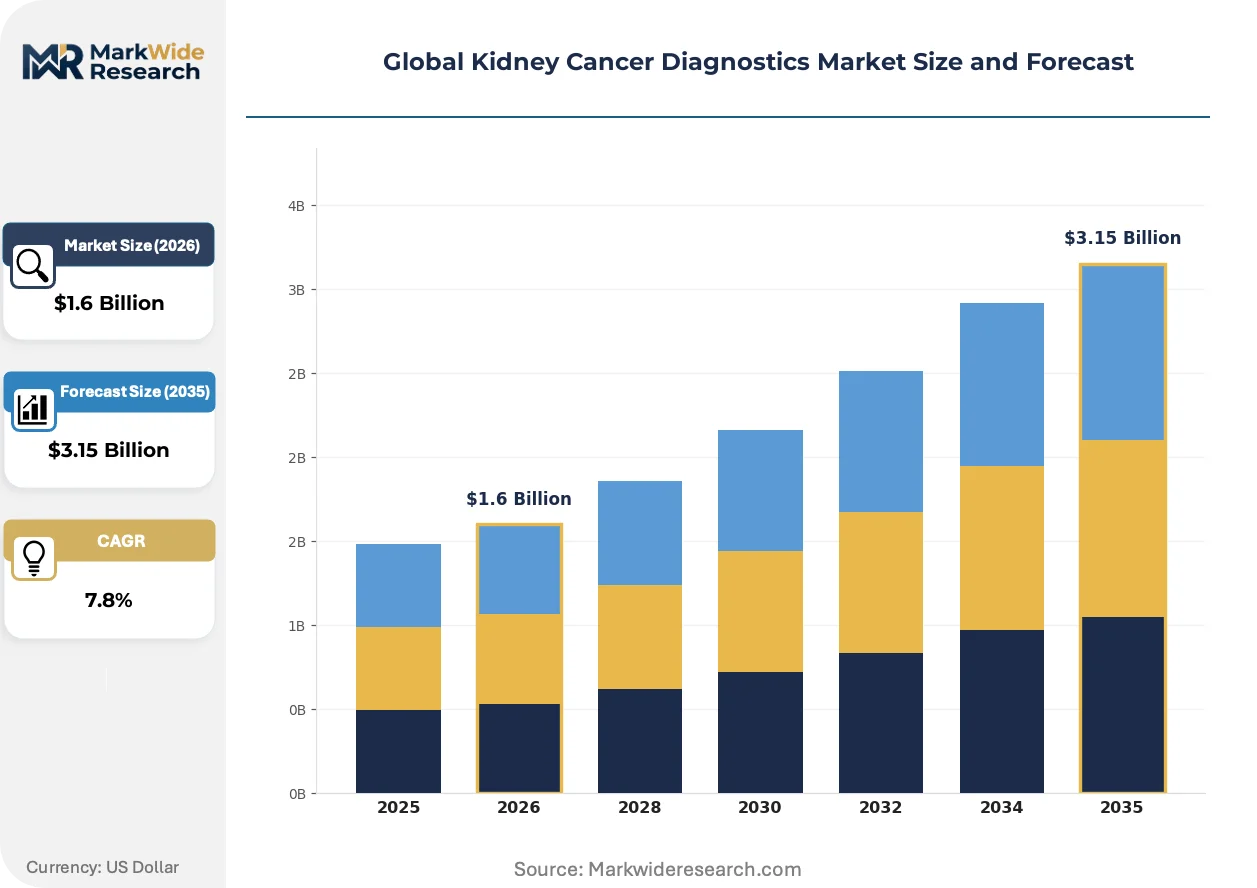
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Kits, Imaging Agents, Biomarker Assays, Molecular Diagnostics Diagnostic Technology: Computed Tomography, Magnetic Resonance Imaging, Ultrasound, Positron Emission Tomography Application: Early Detection, Tumor Characterization, Treatment Monitoring, Recurrence Evaluation End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Research Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Illumina Inc., Roche Holding AG, Siemens Healthineers AG, QIAGEN N.V., Quest Diagnostics Incorporated, Myriad Genetics Inc., NeoGenomics Laboratories, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kidney Cancer Diagnostics Market Shifts & Advancements
Diagnostic modality selection is fragmenting along risk-stratification lines, with high-complexity molecular assays penetrating tertiary centers while point-of-care alternatives target community access gaps.
Next-generation sequencing panel design is bifurcating between comprehensive solid tumor profiling covering 500+ genes and focused kidney cancer-specific assays analyzing 15-20 actionable alterations. Comprehensive panels dominate academic medical center contracts where research integration matters, while focused assays win community hospital bids on turnaround time and interpretability. This split is compressing mid-range panel offerings and forcing manufacturers to commit to one architectural philosophy.
REACH regulation enforcement across Europe is tightening supply chain documentation for diagnostic reagents containing hazardous substances, particularly affecting immunohistochemistry antibody formulations. Manufacturers are reformulating staining protocols to eliminate restricted chemicals, incurring validation costs that favor larger suppliers with dedicated regulatory affairs teams. Smaller European IVD developers are responding by outsourcing formulation to contract manufacturers with established compliance infrastructure.
Hospital procurement committees are unbundling diagnostic service contracts from equipment lease agreements, separating instrument placement from per-test reagent commitments. This shift disrupts the traditional razor-and-blade model that locked laboratories into single-vendor ecosystems. United States health system purchasing cooperatives are driving this change, using consolidated volume to negotiate transparent reagent pricing across multiple platform suppliers.
Global Kidney Cancer Diagnostics Market Segmentation
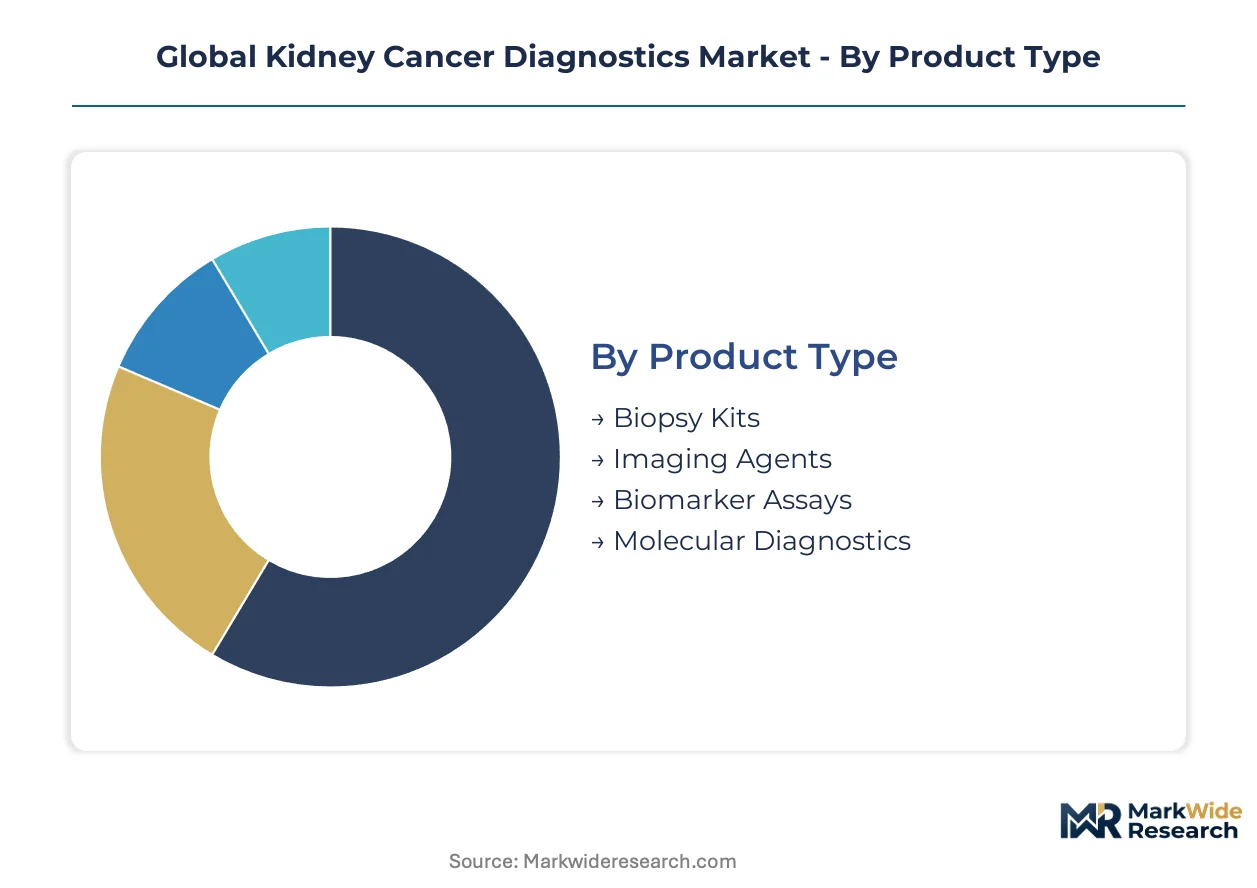
Kidney cancer diagnostics requires precise matching of modality capabilities to clinical intent across detection, characterization, and surveillance stages. Regulatory pathways and reimbursement coding differ materially by product architecture, creating divergent commercialization timelines for manufacturers.
Product Type:
FDA premarket approval timelines stretch longest for novel biomarker assays, while imaging agents navigate abbreviated 510(k) pathways when predicate devices exist.
- Molecular Diagnostics:Next-generation sequencing panels and PCR-based assays detect somatic mutations in VHL, PBRM1, and BAP1 genes with turnaround times under 10 days. Academic medical centers in Germany and Japan are embedding these platforms into surgical oncology workflows to guide adjuvant therapy decisions.
- Biomarker Assays:Circulating tumor DNA and protein-based tests analyze blood samples for minimal residual disease monitoring. United States payers are expanding Category 1 CPT codes for renal cell carcinoma surveillance, creating predictable reimbursement for clinical laboratories.
- Biopsy Kits:Core needle and fine-needle aspiration systems enable histologic confirmation of renal masses. These retain stable utilization tied to mandatory tissue acquisition before systemic therapy initiation.
- Imaging Agents:Radiolabeled tracers including gallium-68 and fluorine-18 compounds visualize tumor metabolism and receptor expression. Supply concentration across limited cyclotron networks creates regional vulnerability to shortages.
Established volume favors Biopsy Kits; emerging adoption favors Molecular Diagnostics.
Diagnostic Technology:
Capital intensity and radiologist training requirements stratify deployment across tertiary centers versus community settings.
- Computed Tomography:Multiphase CT protocols remain the frontline modality for incidental renal mass detection and staging, with sub-centimeter resolution. Hospital networks in the United States prioritize scanner replacement cycles that accommodate dual-energy capabilities for improved tissue characterization.
- Magnetic Resonance Imaging:MRI excels in cystic mass evaluation using Bosniak classification and in patients with contrast allergies. German university hospitals are expanding 3 Tesla installations to reduce indeterminate findings requiring invasive biopsy.
- Positron Emission Tomography:FDG-PET and novel radiotracers assess metastatic burden and treatment response. Production bottlenecks at regional cyclotron facilities constrain utilization growth outside major metropolitan clusters.
- Ultrasound:Point-of-access screening and biopsy guidance applications leverage portability and lower cost. Tier-2 city hospitals in India deploy these as triage tools before referral to centralized imaging centers.
Capital deployment concentrates on Computed Tomography; functional imaging expansion favors Magnetic Resonance Imaging.
Application:
Clinical utility and evidence requirements vary sharply across the care continuum from asymptomatic screening to terminal surveillance.
- Early Detection:Screening of high-risk populations including von Hippel-Lindau carriers and end-stage renal disease patients drives demand for combined imaging and liquid biopsy protocols. United States integrated delivery networks are piloting multi-cancer early detection panels that incorporate kidney cancer signals.
- Treatment Monitoring:Serial imaging and ctDNA assessment track response to tyrosine kinase inhibitors and immune checkpoint blockade. Japanese academic centers are establishing standardized intervals for post-therapy surveillance to optimize resource allocation.
- Tumor Characterization:Histologic subtype classification and molecular profiling guide nephrectomy approach selection and systemic therapy sequencing. Pathology laboratories seek automated immunohistochemistry platforms to reduce inter-observer variability in clear cell versus papillary differentiation.
- Recurrence Evaluation:Post-surgical surveillance protocols combine cross-sectional imaging with biomarker trending to detect metastatic relapse. German oncology practices are embedding these workflows into disease management programs with defined escalation thresholds.
Reimbursement stability favors Tumor Characterization; pipeline innovation favors Early Detection.
End User:
Procurement authority and test volume concentration determine vendor contract structures and platform standardization incentives.
- Hospitals:Integrated health systems consolidate molecular diagnostics under centralized laboratory medicine departments, displacing point-of-care alternatives. United States hospital networks are negotiating enterprise agreements that bundle sequencing instruments with bioinformatics support.
- Diagnostic Laboratories:Independent and hospital-affiliated labs seek CLIA-certified platforms with broad assay menus to serve multiple oncology indications. ISO 15189 accreditation timelines of 12-18 months delay market entry for novel test developers.
- Specialty Clinics:Urology and genitourinary oncology practices demand rapid turnaround on biomarker assays to inform same-visit treatment decisions. These settings favor simplified reporting formats over comprehensive genomic profiling.
- Research Institutions:Academic medical centers prioritize platforms enabling prospective sample banking and protocol integration. EMA In Vitro Diagnostic Regulation performance documentation requirements are accelerating quality differentiation in European procurement.
Contract consolidation favors Hospitals; access expansion favors Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan command the highest per-capita spending on renal malignancy screening, while academic medical centers in these markets anchor adoption of molecular diagnostic platforms.
United States
FDA breakthrough device designations accelerate commercial timelines for novel circulating tumor DNA assays, with hospital networks in Boston and Houston expanding liquid biopsy programs into post-surgical surveillance pathways. Medicare reimbursement coding decisions for multi-cancer early detection tests shape whether these platforms capture asymptomatic screening volumes or remain confined to confirmed-malignancy settings.
Germany
EMA In Vitro Diagnostic Regulation enforcement rewards manufacturers with robust clinical evidence packages, compressing market access timelines for quality-differentiated products. University hospitals in Munich and Heidelberg embed next-generation sequencing into surgical oncology workflows, driving demand for automated pathology integration.
Japan
PMDA evidence requirements demand extended local clinical trials for novel oncology biomarkers, delaying commercial entry by 18-24 months versus Western markets. Academic medical centers in Tokyo and Osaka establish standardized intervals for post-therapy surveillance, optimizing resource allocation across imaging and molecular modalities.
India
Tier-2 city hospital networks in Maharashtra and Karnataka invest in centralized molecular reference laboratories, serving dispersed oncology practices lacking on-site sequencing capability. CDSCO regulatory pathways for imported diagnostic reagents create documentation burdens that favor established suppliers with dedicated regulatory affairs teams.
United Kingdom
NHS England integrated care systems consolidate molecular diagnostics under centralized laboratory medicine departments, displacing point-of-care alternatives in favor of enterprise sequencing contracts. Research institutions in London and Cambridge prioritize platforms enabling prospective sample banking and protocol integration.
Global Kidney Cancer Diagnostics Market Competitive Landscape
Player mix skews toward diversified life sciences conglomerates with captive diagnostic divisions, creating a tiered structure where scale-driven manufacturers compete against specialized molecular testing laboratories. Strategic archetypes include integrated platform vendors bundling instruments with bioinformatics support, reference laboratories leveraging CLIA certification for broad assay menus, and automated staining system specialists defending installed bases through reagent lock-in. Dominant competitive moves center on hospital network enterprise agreements and regulatory evidence package investments that accelerate quality differentiation under EMA and PMDA frameworks.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Illumina Inc. occupy positions anchoring clinical laboratory partnerships through sequencing infrastructure, while Roche Holding AG exemplifies the companion diagnostics archetype with automated immunohistochemistry systems. These three entities represent the concentration of procurement authority around vendors capable of delivering combined instrument, reagent, and interpretive support across North American and European hospital networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Illumina Inc. |
| Roche Holding AG |
| Siemens Healthineers AG |
| QIAGEN N.V. |
| Quest Diagnostics Incorporated |
| Myriad Genetics Inc. |
| NeoGenomics Laboratories |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
ISO 15189 accreditation requirements gate both supply qualification and price differentiation in molecular diagnostics, forcing manufacturers to absorb 12-18 month validation costs that separate premium-tier vendors from commodity reagent suppliers.
Pricing Analysis
Cost-plus contracts with radiotracer indexation dominate imaging agent procurement, tying per-dose pricing to cyclotron operating costs and isotope availability. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and bioinformatics bundling. Cost compression in economy-tier biopsy kits is intensifying because hospital purchasing cooperatives unbundle equipment leases from reagent commitments. Community hospital laboratories exhibit highest price sensitivity; academic medical centers prioritize turnaround time over per-test cost.
Supply Chain Analysis
The United States and Germany concentrate precision sequencing instrument manufacturing, while Belgium and the Netherlands anchor radiotracer production through cyclotron networks. Supply chains draw from semiconductor substrates, rare earth magnets, and fluorine-18 precursor chemicals. Single-source vulnerability concentrates in gallium-68 generator production, where regional facility outages cascade into imaging appointment delays. Distribution runs through hospital network enterprise agreements and diagnostic laboratory CLIA-certified hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as hospital procurement unbundles traditional razor-and-blade contracts, creating niches for modular platform vendors who decouple instrument placement from reagent lock-in.
For Market Incumbents: Compound defensive positioning through captive antibody development and automated staining system integration. Threats from liquid biopsy substitution in surveillance settings demand preemptive bioinformatics pipeline investments. Priority levers include backward integration into sequencing consumables and ISO 15189 certification acceleration in community hospital networks. For New Entrants and Emerging Players: Differentiate on AI-enabled digital pathology deployment in Tier-2 Indian city hospital networks, where centralized molecular reference laboratory partnerships remain underpenetrated. Target urology specialty clinics with simplified biomarker reporting formats for same-visit treatment decisions. Go-to-market angle: turnkey variant interpretation workflows requiring zero dedicated informatics personnel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined diagnostic platforms, reducing barrier thresholds for cloud-native entrants. Long-term viability favors acquisition targets with established hospital network enterprise agreements and EMA clinical evidence packages. Signal to watch: Medicare reimbursement coding decisions for multi-cancer early detection tests as inflection indicator for liquid biopsy addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise sequencing contracts with integrated bioinformatics support displace point-of-care alternatives. |
| FDA Breakthrough Device Pathway | Accelerated commercial timelines for novel circulating tumor DNA assays expand liquid biopsy adoption. |
| Reimbursement Strategy | Category 1 CPT code expansion for renal cell carcinoma surveillance creates predictable laboratory revenue. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance rewards manufacturers with robust clinical evidence packages. |
| Software Companion Development | Deep learning algorithms reduce inter-observer variability in renal tumor histology classification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, pathology department heads, diagnostic platform engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA filings, EMA In Vitro Diagnostic Regulation guidance documents, hospital procurement databases, and CMS Medicare reimbursement coding decisions. Bottom-up test volume estimates triangulated against top-down health system spending data.
Across the analysis window, the forecasting framework modeled product type, diagnostic technology, application stage, and end-user procurement authority. CAGRs derived from segmented volume projections and pricing trajectory assumptions. Industry-specific inputs included radiotracer supply capacity constraints and liquid biopsy coverage expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained payer reimbursement expansion or cyclotron network stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway timelines and hospital consolidation patterns. Recalibration cycles align with material shifts in Medicare coding decisions and EMA enforcement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fungal Antigens Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Global Stroke Diagnostics Market