
 Global Yersinia Diagnostics Market | 2026-2036
Global Yersinia Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yersinia Diagnostics Market Analysis
Clinical microbiologist shortages across European reference laboratories is reorganizing how hospital networks contract for outsourced Yersinia testing. Becton Dickinson leverages its automated blood culture platform to anchor large-volume hospital contracts in North America. bioMérieux differentiates through syndromic gastrointestinal panel integration, while QIAGEN competes on sample-to-answer workflow automation for mid-tier laboratories.
Yersinia diagnostics encompasses laboratory methods for detecting pathogenic Yersinia enterocolitica, Y. pseudotuberculosis, and Y. pestis through culture isolation, serological assays, and nucleic acid amplification with detection limits typically reaching 10-100 colony-forming units per milliliter. These methods serve clinical infectious disease management, food safety surveillance, and biothreat preparedness applications. Polymerase chain reaction technology dominates instrument revenue due to its sensitivity for detecting virulence genes like ail and yst, while next-generation sequencing occupies emerging outbreak investigation workflows where strain-level resolution proves essential. Reagents capture recurring margin pools as laboratories standardize on closed-system consumables to maintain assay consistency.
The FDA's classification of multiplex molecular panels under 510(k) pathways shapes product development timelines for US market entrants, while the EMA's In Vitro Diagnostic Regulation enforces post-market surveillance requirements across European Economic Area states. ISO 15189 accreditation standards for medical laboratories drive quality system investments that filter down to preferred vendor selections. Stakeholders must monitor how WHO pandemic preparedness frameworks recalibrate national stockpiling requirements for plague-capable diagnostics.
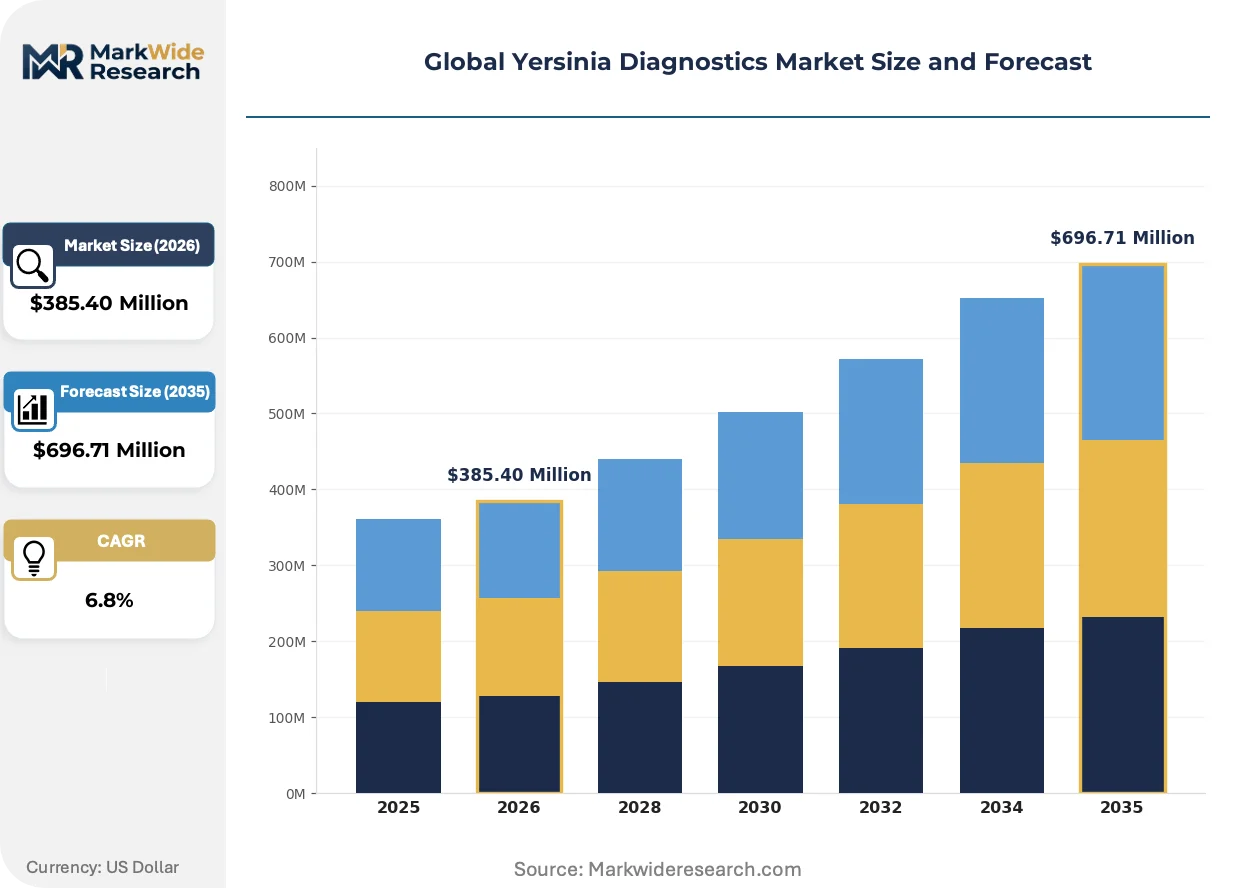
Market Dynamics
Multiplex molecular panel consolidation is compressing standalone assay demand as laboratories prioritize syndromic coverage over single-pathogen testing, forcing manufacturers to bundle Yersinia detection within broader gastrointestinal portfolios or exit hospital microbiology contracts entirely.
Growth Catalysts
- Foodborne surveillance mandates:Japan's METI-funded prefectural health institute programs are driving instrument placements for pathogen detection infrastructure. State-level laboratory networks in Germany are expanding molecular testing capacity for enteric disease monitoring.
- Biothreat preparedness frameworks:WHO pandemic preparedness guidelines are recalibrating national stockpiling requirements for plague-capable diagnostics across multiple member states.
- Automated workflow integration:Mid-tier clinical laboratories are adopting sample-to-answer platforms to offset clinical microbiologist shortages in European reference networks.
Market Restraints
- Reagent lock-in costs:Closed-system consumable requirements for assay consistency create recurring margin capture by platform manufacturers, elevating total cost of ownership for budget-constrained public health laboratories.
- Regulatory pathway friction:FDA's 510(k) classification timelines for multiplex molecular panels extend product development cycles for US market entrants beyond typical venture capital horizons.
- Serological assay displacement:Culture-dependent and antibody-based methods face substitution pressure from nucleic acid amplification technologies with superior detection limits for virulence gene targets.
Strategic Opportunities
- Next-generation sequencing integration:Strain-level resolution capabilities for outbreak investigation workflows are opening premium service tiers in reference laboratory markets.
- Point-of-care decentralization:Untapped demand exists in veterinary and agricultural inspection stations requiring rapid Yersinia screening for food safety compliance.
- EMA post-market surveillance alignment:In Vitro Diagnostic Regulation enforcement creates vendor consolidation opportunities for quality-system-compliant manufacturers across European Economic Area states.
Industry Challenges
- Specialized workforce scarcity:Clinical microbiologist training pipelines have failed to match retirement rates in France, Germany, and the United Kingdom, forcing hospital networks toward outsourced testing arrangements.
- ISO 15189 accreditation complexity:Medical laboratory quality system investments filter through to extended vendor qualification timelines and preferred supplier list narrowing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yersinia Diagnostics Market |
| Market Size in 2026 | $385.40 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Instruments, Reagents, Software End User: Hospitals, Laboratories, Research Institutes, Diagnostics Centers Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing, Immunofluorescence Application: Clinical Diagnosis, Outbreak Investigation, Research, Environmental Testing |
| Companies Covered | Becton Dickinson, Bio-Rad Laboratories, F. Hoffmann-La Roche, bioMérieux, QIAGEN, Abbott Laboratories, Hologic, Danaher Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yersinia Diagnostics Market Emerging Trajectories
Diagnostic platform architecture is splintering between high-throughput hospital systems and distributed rapid-testing nodes, with technology choices increasingly dictated by workforce availability and reimbursement structure rather than analytical performance alone.
Polymerase chain reaction technology is bifurcating the installed base: reference laboratories in Japan and Germany are deploying high-plex systems for syndromic panels, while smaller clinical sites in Italy and Spain are adopting lower-complexity cartridge-based instruments. This split is compressing the addressable market for mid-range open-platform thermal cyclers as buyers migrate toward integrated sample-to-answer workflows or outsource entirely to regional hubs.
The FDA's updated guidance on multiplex gastrointestinal panel testing is compressing product development timelines for assay manufacturers seeking 510(k) clearance, with particular impact on firms attempting to differentiate through novel virulence gene combinations. US-based developers are responding by front-loading clinical validation studies and pre-submission engagement to avoid regulatory hold points.
Consolidated procurement by hospital network purchasing organizations is displacing individual laboratory autonomy in vendor selection across North American and Western European markets. Group purchasing organizations are extracting volume commitments in exchange for sole-source or dual-source contracts, compressing margins for manufacturers while securing supply continuity for members. This concentration is most visible in integrated delivery networks across the United States and hospital trusts in England.
Global Yersinia Diagnostics Market Segmentation
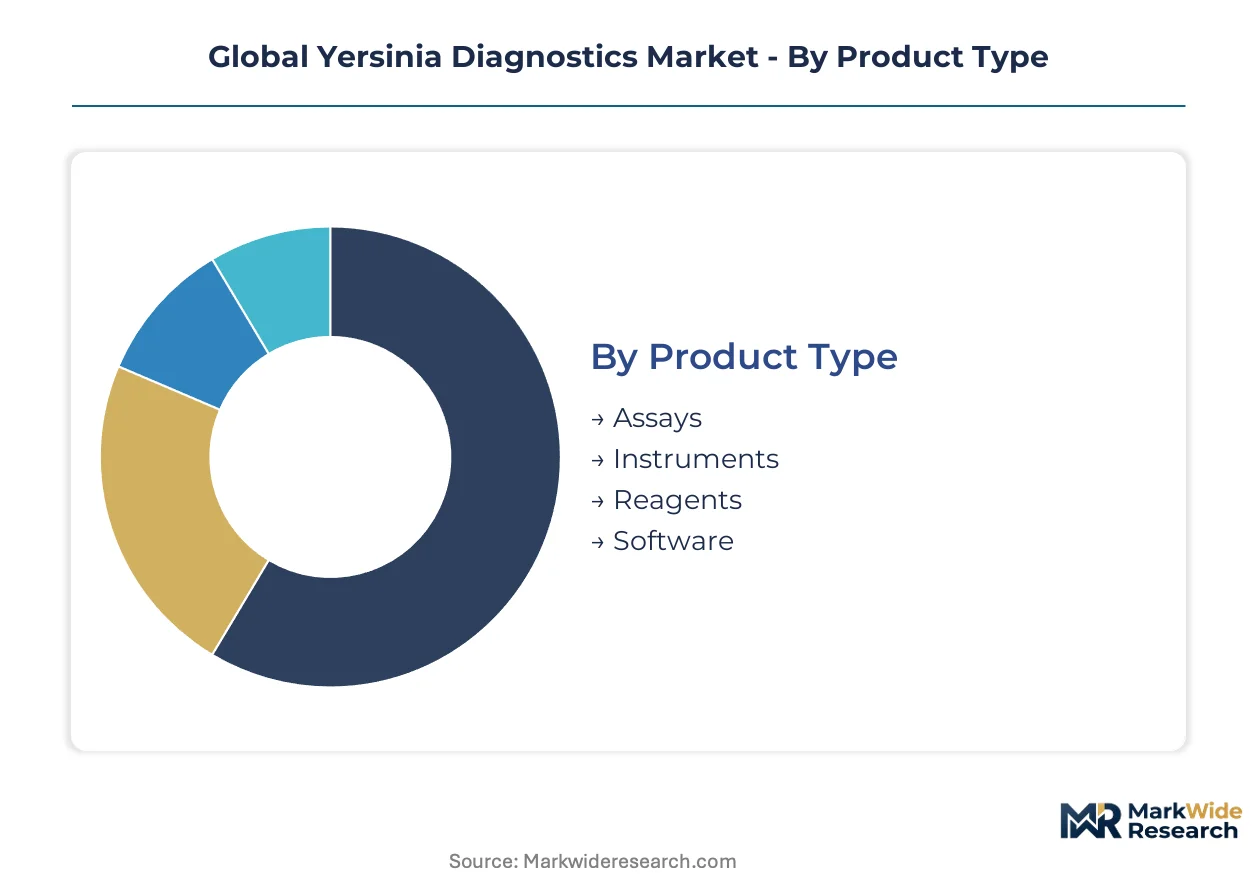
Segmentation in Yersinia diagnostics reveals how substitution pressures and workflow integration reshape purchasing decisions across laboratory tiers. Understanding which product categories and technology platforms face displacement helps vendors prioritize R&D investments and distribution partnerships.
Product Type:
Assays face the most acute substitution threat as multiplex gastrointestinal panels absorb standalone Yersinia testing into broader syndromic menus, forcing pure-play assay manufacturers toward bundled offerings or exit.
- Assays:Nucleic acid amplification test kits targeting virulence genes like ail and yst require refrigerated cold-chain distribution and deliver results within 4-6 hours. Demand concentrates in German state laboratory networks expanding molecular enteric surveillance, though panel consolidation pressures standalone volumes.
- Instruments:Thermal cyclers, automated extractors, and sample-to-answer platforms represent capital-intensive infrastructure with 7-10 year replacement cycles. Japanese prefectural health institutes under METI-funded programs anchor placements, while European mid-tier laboratories defer purchases amid microbiologist shortages.
- Reagents:Closed-system consumables capture recurring revenue through vendor lock-in.
- Software:Laboratory information management systems and pathogen surveillance analytics enable outbreak tracking.
Reagents retain volume leadership through recurring consumable demand; instruments hold the steepest expansion curve as automation penetrates understaffed European networks.
End User:
Customer concentration varies sharply by procurement autonomy, with consolidated purchasing organizations in North America extracting volume commitments that squeeze margins for manufacturers serving fragmented independent sites.
- Hospitals:Acute care facilities with onsite microbiology laboratories prioritize rapid turnaround for sepsis and enteric presentations. Automated blood culture platforms anchor large-volume contracts in the United States, though staffing gaps push smaller hospitals toward outsourced reference testing.
- Laboratories:Public health reference networks and commercial diagnostic providers process high-throughput screening for foodborne surveillance. German state laboratories and Japan's prefectural institutes drive molecular capacity expansion.
- Research Institutes:Academic and government facilities conduct virulence mechanism studies and antimicrobial resistance profiling.
- Diagnostics Centers:Independent outpatient testing sites focus on serological screening and travel medicine consultations.
Laboratories retain volume leadership through surveillance mandate scale; hospitals hold the steepest expansion curve as integrated delivery networks consolidate microbiology services.
Technology:
Platform choices increasingly bifurcate between high-plex reference systems and cartridge-based distributed devices, compressing the mid-range open-platform market as buyers migrate toward integrated workflows or regional hub outsourcing.
- Polymerase Chain Reaction:Real-time and digital PCR methods detect virulence genes with sensitivity reaching 10-100 colony-forming units per milliliter. Japanese and German reference laboratories deploy high-plex systems for syndromic panels, while Italian and Spanish clinical sites adopt lower-complexity cartridge instruments.
- Enzyme-Linked Immunosorbent Assay:Antibody-based serological detection offers lower cost per test but inferior sensitivity for early infection. Displacement pressure from nucleic acid amplification technologies accelerates as reimbursement shifts toward molecular confirmation.
- Next-Generation Sequencing:Whole-genome and targeted amplicon sequencing delivers strain-level resolution for outbreak investigation workflows.
- Immunofluorescence:Direct fluorescent antibody testing provides rapid presumptive identification in resource-limited settings.
Polymerase chain reaction retains volume leadership across installed base scale; next-generation sequencing holds the steepest expansion curve as reference laboratories premium-price outbreak investigation services.
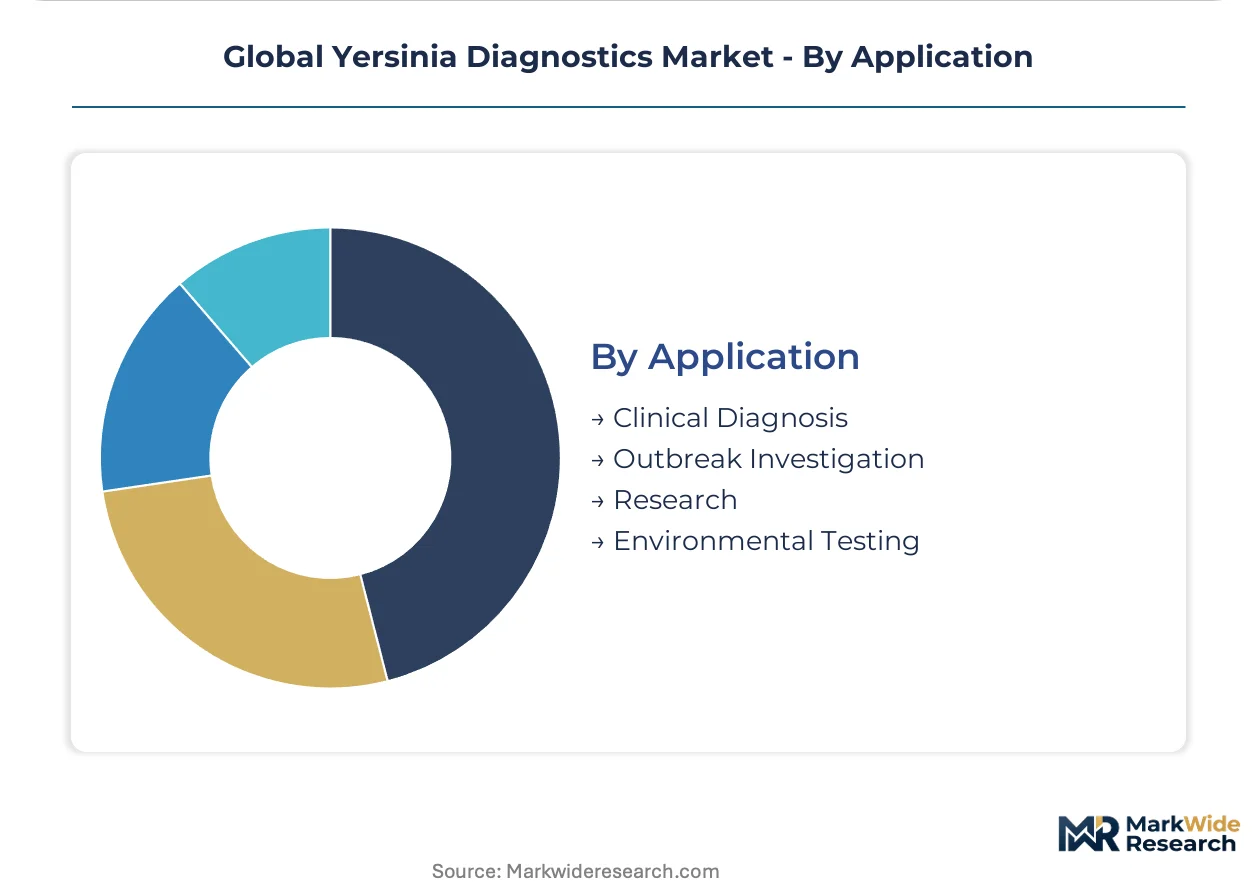
Application:
Revenue stability varies by funding source durability, with biothreat preparedness budgets proving more volatile than clinical diagnostic reimbursement while offering higher per-test margins for plague-capable platforms.
- Clinical Diagnosis:Patient-facing infectious disease management for enterocolitis, pseudotuberculosis, and plague presentations drives routine test volumes. Syndromic gastrointestinal panel adoption in the United States compresses standalone Yersinia ordering as clinicians prioritize broad pathogen coverage.
- Outbreak Investigation:Public health response to foodborne clusters and biothreat events requires rapid strain typing and source attribution. WHO pandemic preparedness frameworks recalibrate national stockpiling requirements across member states.
- Research:Virulence factor characterization and host-pathogen interaction studies support academic and government funding streams.
- Environmental Testing:Food safety surveillance and water quality monitoring extend detection to agricultural and municipal inspection workflows.
Clinical diagnosis retains volume leadership through sustained patient flow; outbreak investigation holds the steepest expansion curve as genomic epidemiology capabilities premium-tier reference laboratory offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on multiplex gastrointestinal panels shapes product development timelines for US-based assay manufacturers, while EMA's In Vitro Diagnostic Regulation enforces post-market surveillance requirements across European Economic Area states. Japan's METI-funded prefectural programs and Germany's state laboratory networks anchor molecular testing infrastructure expansion.
United States
Hospital network purchasing organizations consolidate microbiology procurement across integrated delivery networks, extracting volume commitments from manufacturers. FDA's 510(k) classification for multiplex molecular panels extends development cycles beyond typical venture capital horizons. Boston and San Francisco Bay Area clusters host reference laboratories deploying high-plex syndromic systems for enteric disease surveillance.
Germany
State-level laboratory networks expand molecular testing capacity for foodborne pathogen detection amid clinical microbiologist shortages. EMA's In Vitro Diagnostic Regulation drives quality system investments that filter through to preferred vendor selections. Berlin-Brandenburg and Bavaria concentrate reference laboratory infrastructure serving outsourced hospital network contracts.
Japan
METI-funded surveillance programs drive instrument placements at prefectural health institutes for enteric disease monitoring. PMDA regulatory pathways shape product registration timelines for molecular diagnostic platforms. Kanto and Kansai regions anchor high-throughput reference laboratory capacity for syndromic gastrointestinal panel deployment.
France
Clinical microbiologist training pipelines fail to match retirement rates, forcing hospital networks toward outsourced testing arrangements. ANSM enforces medical device vigilance requirements for in vitro diagnostic platforms. Île-de-France and Auvergne-Rhône-Alpes concentrate reference laboratory capacity serving regional hospital consortiums.
United Kingdom
Hospital trusts consolidate microbiology procurement through centralized purchasing agreements, narrowing preferred supplier lists. ISO 15189 accreditation standards drive extended vendor qualification timelines. London-Southeast and Midlands clusters anchor public health reference laboratory networks for foodborne surveillance.
Global Yersinia Diagnostics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with automated platform specialists commanding premium pricing in high-throughput hospital systems while reagent manufacturers capture recurring margin pools through closed-system consumables. The market structures around three tiers: multinational conglomerates with diversified life science portfolios, specialized diagnostic platform developers, and regional reagent suppliers. Consolidation pressures intensify as group purchasing organizations extract volume commitments and syndromic panel adoption compresses standalone assay demand.
Among diversified conglomerates, Becton Dickinson and bioMérieux occupy positions exemplifying contrasting strategic archetypes—automated blood culture platform anchoring versus syndromic gastrointestinal panel integration. QIAGEN represents the sample-to-answer workflow automation specialist serving mid-tier laboratories. These three companies illustrate how vendor selection increasingly filters through workforce availability and procurement consolidation rather than analytical performance differentiation alone.
| Leading Market Players |
|---|
| Becton Dickinson |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| bioMérieux |
| QIAGEN |
| Abbott Laboratories |
| Hologic |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Long-term sole-source contracts with integrated delivery networks lock in both reagent supply continuity and predictable cost structures for manufacturers serving high-volume hospital microbiology departments. These arrangements compress margin flexibility for assay developers while securing captive demand for closed-system consumables across North American and Western European markets.
Pricing Analysis
Price spreads between Japanese prefectural health institutes and Italian mid-tier clinical sites exceed threefold for equivalent sample-to-answer platforms due to bundled service tiers and localization requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from CE-IVD marked alternatives and research-use-only reagents. Cost compression in the economy tier intensifies because group purchasing organizations extract volume commitments exceeding ten thousand annual tests. Public health reference laboratories exhibit highest price sensitivity due to fixed budget allocations, while biothreat preparedness programs demonstrate lowest sensitivity given national security funding priorities.
Supply Chain Analysis
Germany and Japan anchor precision manufacturing for automated extraction modules and thermal cycler optical components, while the United States concentrates on software and assay development. Cold-chain distribution of refrigerated reagents draws from specialized logistics networks with temperature-validated packaging. Single-source vulnerability persists for virulence gene oligonucleotide synthesis, where capacity concentrates among three contract manufacturers. Distribution runs through authorized distributor networks serving hospital procurement committees and reference laboratory consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA 510(k) clearance timelines and ISO 15189 accreditation requirements create structural switching costs that protect incumbent positions.
For Market Incumbents: Shield installed base revenue by embedding reagent lock-in through expanded assay menus on existing sample-to-answer platforms, countering displacement from emerging syndromic panel specialists. Deepen backward integration into oligonucleotide manufacturing to reduce single-source dependency for virulence gene probe supply. For New Entrants and Emerging Players: Anchor in veterinary and agricultural inspection stations where food safety compliance mandates create unmet demand for rapid Yersinia screening outside regulated clinical channels. Pursue point-of-care cartridge development for distributed testing nodes, leveraging lower regulatory burden and faster procurement cycles than hospital microbiology contracts. For Investors and Strategic Acquirers: Capital is best deployed toward quality-system-compliant manufacturers with established EMA post-market surveillance infrastructure and existing ISO 15189 accreditation relationships. Long-term viability hinges on consolidation capture as In Vitro Diagnostic Regulation enforcement narrows vendor pools. Monitor PMDA registration timelines for Japanese market entry as inflection indicator for platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Syndromic Panel Integration | Multiplex gastrointestinal coverage absorbs standalone Yersinia testing into broader hospital contracts. |
| Sample-to-Answer Automation | Mid-tier European laboratories adopt closed workflows to offset clinical microbiologist shortages. |
| Next-Generation Sequencing Premium Tier | Strain-level resolution enables outbreak investigation pricing power at reference laboratories. |
| EMA Post-Market Surveillance Alignment | Quality system investments filter through to preferred vendor status across European Economic Area states. |
| Point-of-Care Veterinary Expansion | Agricultural inspection stations require rapid screening for food safety compliance mandates. |
Methodological Framework
A standing panel of clinical microbiologists, hospital procurement managers, reference laboratory directors, and regulatory affairs specialists provided ongoing calibration for assay demand and platform adoption assumptions. Primary fieldwork combined structured interviews with diagnostic platform manufacturers and secondary validation through FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, and prefectural health institute procurement records. Bottom-up test volume estimates triangulated against top-down instrument placement data across German state laboratory networks and Japanese METI-funded programs.
Consistency checks validated volume and value outputs against external benchmarks including hospital capital expenditure disclosures and group purchasing organization contract announcements. The analytical framework modeled segmentation across product type, end user, technology platform, and application use case throughout the projection horizon. CAGRs derived from instrument replacement cycle analysis, reagent consumable attach rates, and surveillance mandate expansion trajectories in foodborne pathogen monitoring programs.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory pathway stability and continued clinical microbiologist workforce contraction; material deviation in either would warrant model refresh. Specific risks include accelerated serological assay displacement, sudden biothreat preparedness budget reallocation, or disruptive point-of-care technology validation. Recalibration cycles align with material shifts in FDA guidance timelines, EMA enforcement patterns, and national stockpiling requirement updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Global Urinalysis Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market