
 Multiplex Molecular Diagnostics Market | 2026-2036
Multiplex Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Multiplex Molecular Diagnostics Market Outlook
Modular panel bundling is recalibrating procurement decisions across hospital and reference laboratory settings. bioMérieux leverages its syndrome-based assay portfolios to anchor European infectious disease workflows. QIAGEN N.V. sustains instrument placement through reagent rental models that lock in long-term consumable revenue. Thermo Fisher Scientific Inc. dominates clinical research channels with end-to-end sequencing and qPCR infrastructure.
Multiplex molecular diagnostics refers to simultaneous detection and quantification of multiple nucleic acid targets within a single analytical reaction, typically operating through fluorogenic probe chemistries, spatially discrete microarray features, or massively parallel sequencing readouts to reduce per-target cost and sample volume requirements. The primary commercial purpose centers on syndromic infectious disease panels, companion oncology profiling, and pharmacogenomic screening where turnaround time and differential diagnosis breadth determine clinical utility. Reagents and kits command the largest revenue share due to recurring consumable pull-through tied to installed instrument bases, while next-generation sequencing applications represent the fastest-expanding technology segment as oncology panels migrate from hotspot testing to comprehensive genomic profiling. Polymerase chain reaction retains mature, high-margin positioning in routine pathogen detection where regulatory clearance pathways and laboratory familiarity sustain incumbent positions.
FDA premarket review pathways and CLIA complexity categorization shape assay development priorities and commercial launch sequencing for US market participants. EMA's In Vitro Diagnostic Regulation and IVDR conformity assessment requirements are restructuring European market access timelines and notified body capacity. China's NMPA innovation approval track for genetic diagnostics is accelerating domestic platform registration. Stakeholders must monitor regulatory divergence across these jurisdictions to optimize clinical trial placement and manufacturing localization decisions.
Market Dynamics
Hospital laboratories are consolidating procurement around syndromic infectious disease panels, compressing vendor selection criteria toward regulatory breadth and reagent rental economics rather than instrument features alone.
Growth Catalysts
- CLIA complexity categorization:The FDA's framework for high-complexity molecular testing creates predictable pathways for assay developers seeking US hospital laboratory placement.
- Centralized reference laboratory networks:Germany's dense hospital federation structure accelerates panel standardization across multi-site health systems.
- Digital PCR migration:Academic medical centers are adopting droplet-based quantification methods for oncology minimal residual disease monitoring.
Market Restraints
- Polymerase supply concentration:Thermostable enzyme production clusters in contract manufacturing organizations across Switzerland and South Korea, exposing reagent kitters to single-source risk.
- IVDR notified body bottlenecks:EMA's In Vitro Diagnostic Regulation has reduced conformity assessment capacity to twelve designated entities, extending European launch timelines.
- Fluorogenic probe cost volatility:Black Forest dye synthesis facilities face raw material constraints from Chinese pharmaceutical intermediate suppliers.
Strategic Opportunities
- Pharmacogenomic screening expansion:China's NMPA innovation approval track for genetic diagnostics is accelerating domestic platform registration for warfarin and clopidogrel metabolism assays.
- Point-of-care convergence:Microfluidic cartridge miniaturization is integrating with smartphone-based fluorescence readers for emergency department infectious disease triage.
- Companion diagnostic mandates:FDA's draft guidance on co-development requirements is creating pull-through for oncology panel expansion beyond hotspot testing.
Industry Challenges
- Bioinformatics interpretation staffing:Clinical laboratories report persistent vacancies in variant classification specialists capable of ACMG guideline-aligned reporting.
- Legacy LIS integration complexity:Hospital information systems built on HL7 v2.x architectures require middleware development for NGS data pipeline connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiplex Molecular Diagnostics Market |
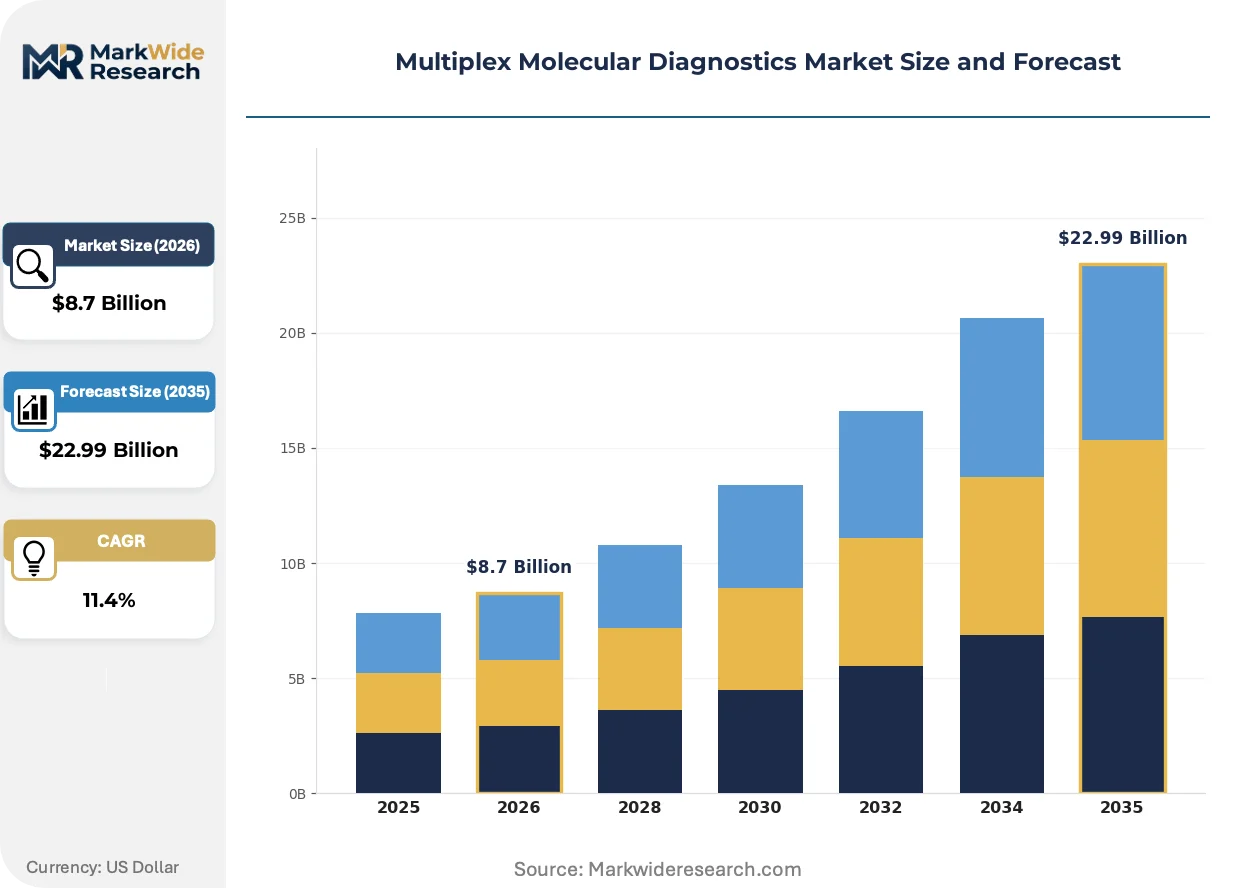
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software Application: Genetic Testing, Infectious Disease Testing, Oncology, Pathogen Detection End User: Hospitals, Clinics, Research Laboratories, Diagnostics Centers Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Microarrays, CRISPR |
| Companies Covered | bioMérieux, QIAGEN N.V., Danaher Corporation, Thermo Fisher Scientific Inc., DiaSorin S.p.A., F. Hoffmann-La Roche Ltd., Hologic, Inc., Abbott, Illumina, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiplex Molecular Diagnostics Market Strategic Shifts
Multiplex molecular diagnostics is experiencing platform convergence between real-time PCR stability and next-generation sequencing depth, reshaping how laboratories architect testing menus across infectious disease and oncology service lines.
Massively parallel sequencing readouts are integrating with automated nucleic acid extraction workflows to compress turnaround times for comprehensive genomic profiling. Large cancer centers in the United States are deploying these integrated platforms for same-day somatic variant reporting in solid tumor cases. The structural consequence is that hotspot PCR panels are ceding ground to broader gene coverage in reimbursement-sensitive indications.
EMA's In Vitro Diagnostic Regulation is restructuring European commercial launch sequencing through str notified body conformity assessment requirements. Manufacturers now face eighteen-to-twenty-four-month certification timelines versus six-to-nine months under the prior directive. Germany and France are experiencing the most pronounced registration delays as their domestic notified bodies reach capacity limits.
Laboratory procurement committees are consolidating vendor relationships around reagent rental models that exchange instrument placement for multi-year consumable commitments. Reference laboratories in China and the United States are displacing capital purchase structures with per-test pricing arrangements. This behavioral shift is most visible among health systems operating more than fifty hospital laboratories under centralized supply chain governance.
Multiplex Molecular Diagnostics Market Segmentation
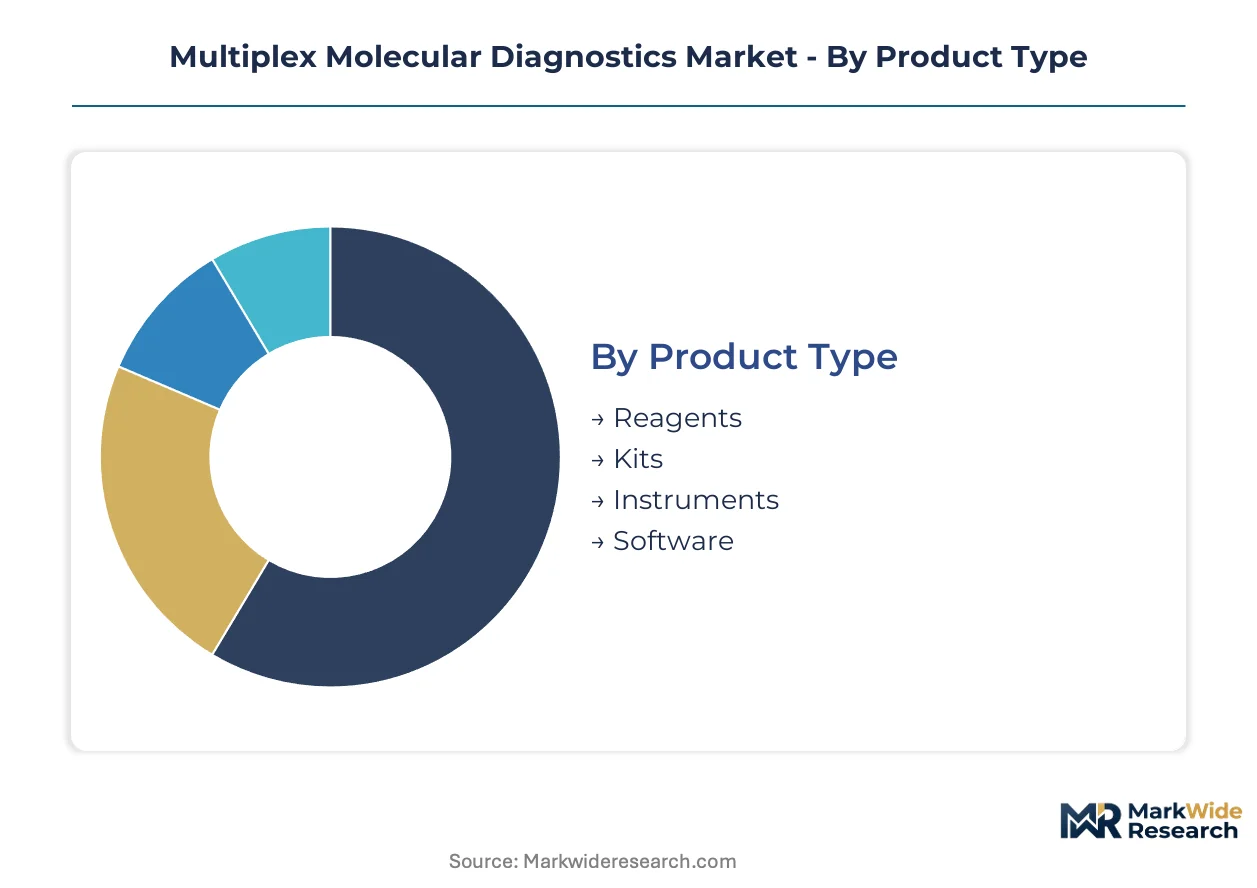
Laboratory procurement committees evaluate multiplex platforms through multiple lenses simultaneously. Product economics, clinical application breadth, and technology maturity each reshape vendor selection criteria and long-term contract structures.
Product Type:
Recurring consumable economics dominate capital allocation decisions across hospital and reference laboratory settings.
- Reagents:Enzyme master mixes, nucleotide triphosphates, and buffer formulations constitute the highest-margin recurring revenue stream. Thermostable polymerase formulations from Swiss and South Korean contract manufacturers anchor supply agreements for US hospital networks facing CLIA high-complexity testing expansion.
- Kits:Pre-formulated assay panels bundle primers, probes, and controls for syndromic infectious disease workflows. bioMérieux and QIAGEN N.V. leverage syndrome-based portfolios to lock in multi-year reagent rental commitments across European hospital federations.
- Instruments:Real-time PCR thermal cyclers and automated nucleic acid extraction platforms represent capital-intensive placement decisions.
- Software:Bioinformatics pipelines for variant classification and LIS integration address persistent staffing vacancies in clinical laboratories.
Reagents lead on scale; software leads on momentum.
Application:
Reimbursement pathways and regulatory clearance timelines determine which clinical indications absorb capital investment fastest.
- Infectious Disease Testing:Syndromic respiratory and bloodstream infection panels compress time-to-diagnosis in emergency departments. Centralized reference laboratory networks in Germany and China standardize these workflows across multi-site health systems.
- Oncology:Solid tumor and hematologic malignancy profiling migrates from hotspot PCR testing toward comprehensive genomic profiling using next-generation sequencing. Large US cancer centers deploy integrated platforms for same-day somatic variant reporting.
- Genetic Testing:Pharmacogenomic screening for warfarin and clopidogrel metabolism accelerates under China's NMPA innovation approval track.
- Pathogen Detection:Multiplex panels for sepsis and meningitis target rapid differential diagnosis in acute care settings.
Infectious disease testing leads on scale; oncology leads on momentum.
End User:
Testing volume concentration and supply chain governance structures differentiate procurement behavior across facility types.
- Hospitals:Integrated delivery networks consolidate vendor relationships around reagent rental models exchanging instrument placement for per-test pricing. Health systems operating more than fifty hospital laboratories displace capital purchase structures with multi-year consumable commitments.
- Research Laboratories:Academic medical centers adopt droplet-based digital PCR methods for minimal residual disease monitoring in oncology clinical trials.
- Diagnostics Centers:Independent reference laboratories face margin pressure from centralized hospital network procurement.
- Clinics:Point-of-care microfluidic cartridge miniaturization targets emergency department triage applications.
Hospitals lead on scale; research laboratories lead on momentum.
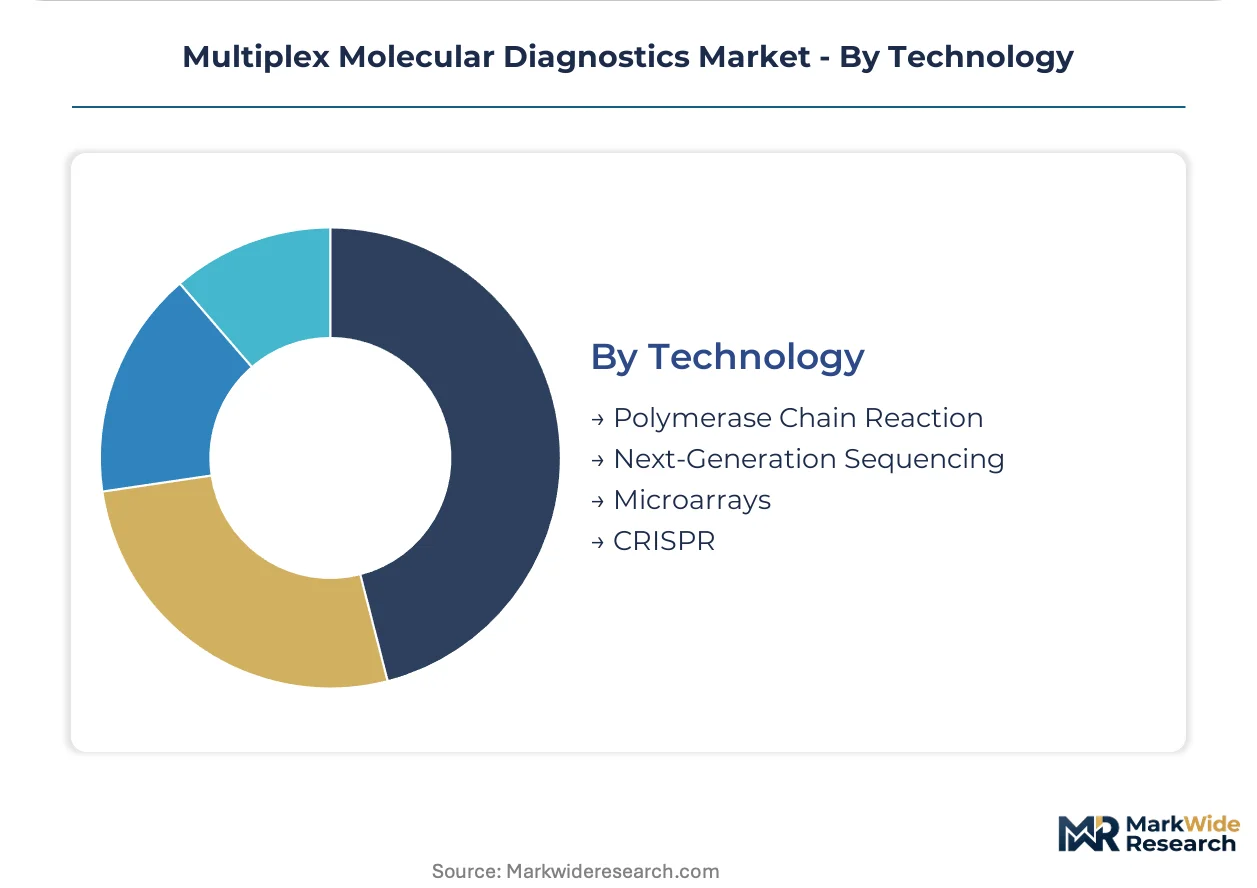
Technology:
Platform convergence between established PCR stability and sequencing depth reshapes laboratory architecture decisions.
- Polymerase Chain Reaction:Mature fluorogenic probe chemistries retain incumbent positioning in routine pathogen detection where regulatory clearance pathways and laboratory familiarity sustain high-margin positions. FDA premarket review frameworks create predictable commercial launch sequencing.
- Next-Generation Sequencing:Massively parallel readouts integrate with automated extraction workflows to compress turnaround times for comprehensive genomic profiling. Oncology panels expand beyond hotspot testing toward broad gene coverage as reimbursement structures evolve.
- Microarrays:Spatially discrete feature platforms serve targeted pharmacogenomic screening applications.
- CRISPR:Guide RNA-based detection methods target point-of-care diagnostic miniaturization.
Polymerase chain reaction leads on scale; next-generation sequencing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multiplex molecular diagnostics originated in academic medical centers across the United States and Germany during the late 1990s, where fluorogenic probe chemistries first enabled simultaneous pathogen detection. Commercial scaling followed through Swiss and South Korean manufacturing clusters that now anchor global reagent supply chains.
United States
Hospital laboratory consolidation around syndromic infectious disease panels drives procurement centralization. FDA premarket review pathways and CLIA high-complexity categorization create predictable regulatory frameworks for assay developers. The Boston-Cambridge corridor anchors oncology panel innovation, while Texas Medical Center laboratories deploy integrated NGS workflows for same-day somatic variant reporting.
Germany
Dense hospital federation structures accelerate panel standardization across multi-site health systems. EMA's In Vitro Diagnostic Regulation and IVDR conformity assessment requirements extend launch timelines to eighteen-to-twenty-four months. The Rhine-Main metropolitan region concentrates notified body capacity and reference laboratory networks serving Central European markets.
China
Centralized reference laboratory networks expand pharmacogenomic screening for warfarin and clopidogrel metabolism assays. NMPA innovation approval tracks accelerate domestic platform registration for genetic diagnostics. Yangtze River Delta cities host contract manufacturing organizations producing thermostable polymerase formulations for regional kitters.
Switzerland
Thermostable enzyme production clusters expose reagent kitters to single-source supply risk amid concentrated contract manufacturing. Swissmedic oversight aligns with IVDR requirements for European market access. Basel and Zurich anchor dye synthesis and fluorogenic probe chemistry facilities serving global diagnostic manufacturers.
South Korea
Contract manufacturing organizations produce polymerase master mixes for US hospital networks facing CLIA expansion. MFDS regulatory frameworks support export-oriented production for Asia-Pacific markets. Seoul-Incheon bioclusters specialize in high-volume enzyme fermentation and nucleotide triphosphate formulation.
Multiplex Molecular Diagnostics Market Competitive Environment
Premium-margin players sit above commodity-margin players across reagent rental economics and regulatory breadth dimensions. The vendor base stratifies between syndrome-based assay portfolio owners, end-to-end sequencing infrastructure providers, and instrument-placement specialists locking in consumable pull-through. Three archetypes dominate: European infectious disease workflow anchors, North American oncology profiling integrators, and Asian contract manufacturing enablers. Competitive moves concentrate on reagent rental model expansion and multi-year consumable commitment extraction.
Among European-based diagnostic specialists, bioMérieux and QIAGEN N.V. occupy positions anchoring syndrome-based assay portfolios across hospital federation procurement structures. Thermo Fisher Scientific Inc. represents the North American archetype of end-to-end sequencing and qPCR infrastructure dominance in clinical research channels. These three entities exemplify how geographic origin and corporate structure correlate with divergent platform strategies—French and Dutch limited liability structures versus American incorporation—while each sits within distinct margin tiers based on recurring revenue attachment rates.
| Leading Market Players |
|---|
| bioMérieux |
| QIAGEN N.V. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| DiaSorin S.p.A. |
| F. Hoffmann-La Roche Ltd. |
| Hologic, Inc. |
| Abbott |
| Illumina, Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up reagent specialists anchor supply discipline through multi-year consumable lock-ins that compress hospital laboratory procurement cycles and stabilize per-test pricing across volatile polymerase input costs.
Pricing Analysis
Reagent rental models exchanging instrument placement for per-test consumable commitments dominate hospital network procurement, with price differentiation resting on CLIA high-complexity certification tier and syndrome-based assay panel breadth. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared oncology panels from research-use-only infectious disease workflows. Cost compression in economy-tier pathogen detection kits is intensifying because Chinese contract manufacturers are expanding thermostable polymerase fermentation capacity. Academic medical centers show least price sensitivity due to grant-funded digital PCR adoption, while independent diagnostics centers face acute margin pressure from centralized hospital procurement.
Supply Chain Analysis
Regional distribution centers in Basel, Seoul-Incheon, and Yangtze River Delta cities anchor hub-and-spoke patterns serving US hospital networks and European hospital federations. Thermostable enzyme production clusters in Switzerland and South Korea, fluorogenic probe synthesis in Black Forest facilities, and nucleotide triphosphate formulation in Chinese contract manufacturers create multi-node dependencies. Single-source vulnerability concentrates in Swiss polymerase master mix suppliers serving CLIA high-complexity testing expansion. Distribution runs through centralized reference laboratory networks in Germany, China, and the United States that standardize panel procurement across multi-site health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multiplex molecular diagnostics market compounds steadily as recurring consumable economics tied to installed instrument bases generate predictable revenue streams regardless of capital expenditure cycles.
For Market Incumbents: Hedge regulatory breadth erosion by accelerating IVDR conformity assessment submissions before notified body capacity constraints worsen in Germany and France. Backward integration into thermostable enzyme production reduces exposure to Swiss and South Korean contract manufacturing concentration. Lock in multi-year reagent rental extensions with health systems operating more than fifty hospital laboratories before point-of-care microfluidic miniaturization disrupts centralized testing economics. For New Entrants and Emerging Players: Smartphone-based fluorescence reader integration with microfluidic cartridges offers a technology-first wedge into emergency department infectious disease triage where turnaround time sensitivity exceeds brand loyalty. China's NMPA innovation approval track for pharmacogenomic screening presents the most penetrable regulatory pathway for warfarin and clopidogrel metabolism assays. Pursue hospital system partnership structures that exchange instrument placement for exclusive consumable supply rather than competing on capital purchase price. For Investors and Strategic Acquirers: Valuations sit cheapest among European syndrome-based assay specialists facing IVDR transition cost absorption and extended launch timelines. The five-to-ten year viability window favors platforms with installed bases above ten thousand instruments generating above-seventy-percent recurring revenue attachment. Watch FDA draft guidance on companion diagnostic co-development requirements as the signal for oncology panel expansion beyond hotspot testing.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Conformity Assessment Acceleration | EMA's reduced notified body capacity to twelve designated entities extends European launch timelines for assay developers. |
| Reagent Rental Model Expansion | Per-test pricing arrangements displace capital purchases across health systems operating more than fifty hospital laboratories. |
| Digital PCR Platform Integration | Droplet-based quantification methods anchor minimal residual disease monitoring in academic medical center oncology trials. |
| Pharmacogenomic Panel Registration | China's NMPA innovation approval track accelerates domestic platform registration for genetic diagnostics. |
| Point-of-Care Miniaturization | Microfluidic cartridge integration with smartphone fluorescence readers targets emergency department infectious disease triage. |
Study Parameters
Multiple input streams — primary interviews with hospital laboratory directors, regulatory affairs specialists at diagnostic manufacturers, and GPO contracts managers — were reconciled against FDA 510(k) filings, EMA IVDR submission databases, and hospital procurement records. Conversations with biomedical engineers and reference laboratory network administrators provided operational validation. Secondary sources included CMS Medicare reimbursement data, CLIA complexity categorization registries, and Chinese NMPA genetic diagnostic approval tracks. Bottom-up instrument placement and consumable pull-through estimates were triangulated against top-down market sizing from syndromic panel shipment data.
Historical volume trajectories were cross-referenced against panel input from oncology and infectious disease service line expansion to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include technology platform, application indication, end-user facility type, and regional regulatory cluster. CAGRs were derived from instrument installed base growth rates and consumable revenue per test trends. Forecast inputs incorporated NGS migration timelines from hotspot testing to comprehensive genomic profiling and IVDR transition cost absorption curves.
The model holds under stable CLIA high-complexity testing expansion and intact reagent rental economics; deviation in FDA premarket review pathway restructuring or polymerase supply disruption would shift trajectory. Forecasts reflect documented assumptions around hospital laboratory consolidation rates and reimbursement pathway evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Microdialysis Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Antigen Kit Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market