
 Diabetes Testing System Market | 2026-2036
Diabetes Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Testing System Market Insights
The Diabetes Testing System Market is restructuring around a sharp split between premium continuous glucose monitoring ecosystems and commodity blood glucose meter segments. Abbott leverages factory-calibrated sensor architectures to eliminate fingerstick requirements for Type 2 patients. Dexcom sustains its position through Medicare reimbursement and endocrinology clinic partnerships. Roche competes on laboratory-grade accuracy standards that anchor hospital and reference lab procurement.
A diabetes testing system comprises devices, consumables, and software platforms that quantify blood glucose concentration through electrochemical or optical transduction, typically reporting results within five seconds to fifteen minutes depending on modality. These systems enable therapeutic dosing decisions, hypoglycemia alerts, and long-term glycemic trend analysis for insulin-dependent and non-insulin-dependent patients. Continuous glucose monitors now capture the fastest-expanding margin pool as sensor wear duration extends and algorithm-driven predictive alerts replace reactive monitoring. Blood glucose meters remain structurally mature with volume concentrated in emerging markets where cost sensitivity dominates procurement. Test strips retain significant revenue weight due to recurring purchase patterns despite meter commoditization.
The FDA regulates glucose monitoring systems under 21 CFR Part 862 with Class II controls for self-monitoring devices and Class III pathways for implantable sensors, while CMS national coverage determinations dictate reimbursement eligibility and patient access thresholds. ISO 15197 accuracy standards and EU MDR conformity requirements shape product development priorities for manufacturers seeking multi-regional approval. Stakeholders must monitor evolving FDA guidance on integrated closed-loop systems and CMS decisions on non-adjunctive CGM claims as these determinations will redistribute market power between incumbent sensor makers and emerging algorithm-centric entrants.
Market Dynamics
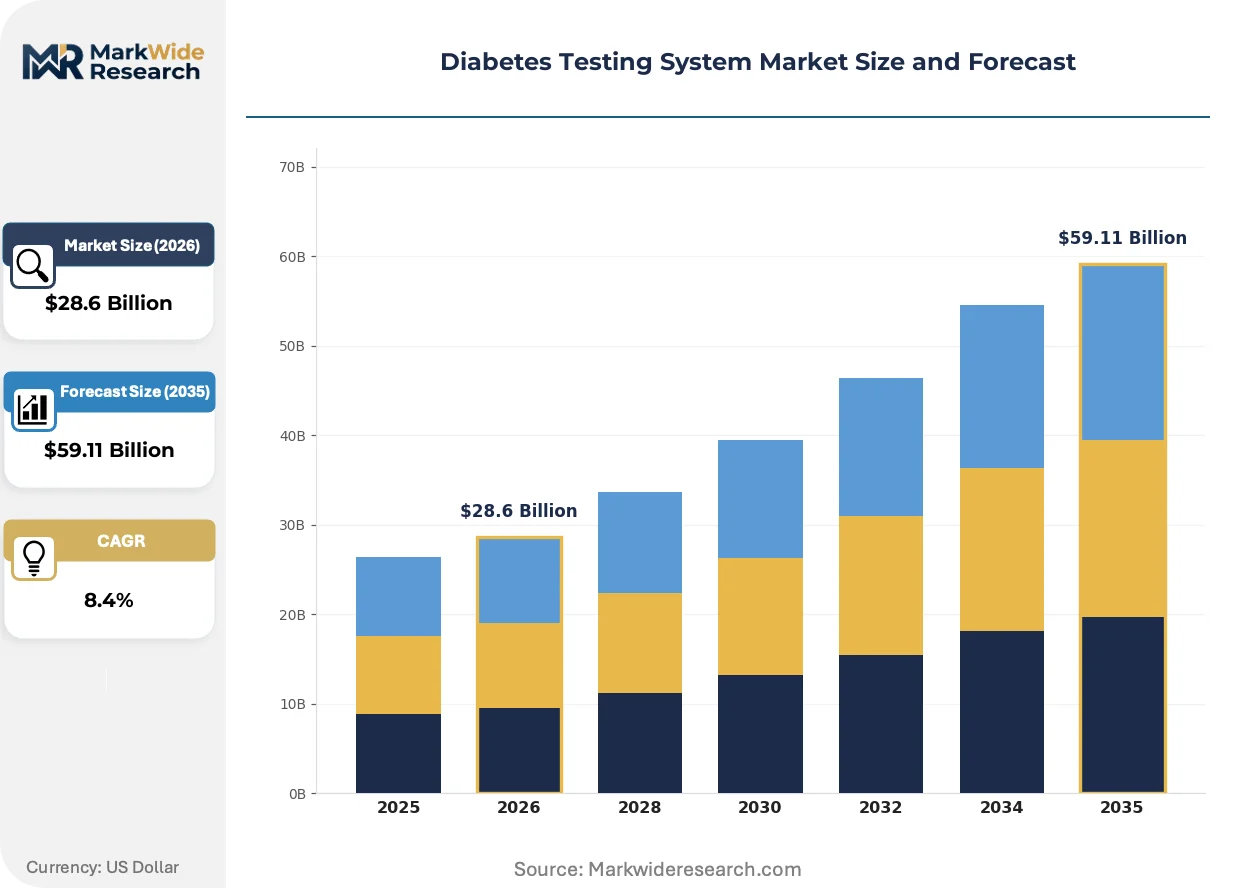
The diabetes testing system market restructures around a decisive migration from episodic fingerstick monitoring to continuous glucose monitoring ecosystems, with sensor wear duration extension and algorithmic predictive alerts compressing the addressable market for traditional blood glucose meters.
Growth Catalysts
- CMS Non-Adjunctive Reimbursement:Medicare coverage expansion for therapeutic continuous glucose monitors eliminates prior authorization burdens for insulin-dependent patients in the United States, accelerating clinic-to-home care transitions.
- Factory-Calibrated Optical Transduction:Advances in fluorescence-based enzymatic sensing eliminate fingerstick calibration requirements, reducing patient adherence friction and expanding Type 2 diabetes addressability.
- Japan's Super-Aged Demographics:Patients over 75 years constitute the fastest-expanding diabetes prevalence cohort, driving demand for passive monitoring solutions that minimize cognitive load and manual intervention.
Market Restraints
- Platinum Electrode Supply Concentration:Electrochemical test strip manufacturing depends on South African and Russian platinum group metal refining, exposing consumables producers to geopolitical supply disruptions and input cost volatility.
- FDA Class III Pathway Friction:Implantable long-term glucose sensors face 18-24 month premarket approval timelines versus 6-9 months for external Class II devices, delaying next-generation product commercialization.
- Flash Glucose Monitoring Substitution:Factory-calibrated interstitial fluid sensors capture moderate-complexity patients who previously required blood glucose meter and test strip combinations, eroding recurring revenue pools in the self-monitoring segment.
Strategic Opportunities
- India's Undiagnosed Diabetes Burden:Approximately 57% of diabetes cases remain undetected, creating first-mover advantage for affordable continuous monitoring platforms that bypass clinic-based diagnostic bottlenecks.
- Integrated Closed-Loop Convergence:Algorithm-driven insulin pump coordination with real-time glucose data streams enables artificial pancreas systems, opening premium pricing tiers for sensor-pump-controller ecosystems.
- Pharmacy Channel Direct Distribution:Retail pharmacy CGM dispensing bypasses durable medical equipment supplier markups, capturing margin compression benefits while expanding patient access in Germany's APotheken-led healthcare system.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Extended-wear sensor development requires rare expertise in hydrogel-enzyme stabilization and foreign body response mitigation, constraining R&D velocity for mid-tier manufacturers.
- ISO 15197 Accuracy Certification Timelines:Third-party laboratory validation for 95% consensus error grid compliance adds 8-12 months to product launch schedules, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Testing System Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Test Strips, Lancets End User: Home Care, Hospitals, Laboratories, Diabetes Clinics Technology: Electrochemical, Optical, Thermal, Hybrid Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Others |
| Companies Covered | Dexcom, Abbott, Medtronic, F. Hoffmann-La Roche, Ascensia Diabetes Care, LifeScan, Senseonics, ARKRAY, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Testing System Market Trends and Innovations
Sensor miniaturization and predictive algorithm deployment are redrawing competitive boundaries between point-of-care diagnostics and wearable health technology, with software-driven differentiation displacing hardware-centric value propositions.
Factory-calibrated continuous glucose monitors eliminate patient-driven calibration routines through stabilized enzyme formulations and proprietary drift-correction algorithms. Endocrinology clinics in the United States and Germany adopt these systems at replacement-cycle velocity for insulin-dependent cohorts. This capability is decentralizing glucose data authority from laboratory reference methods to patient-owned mobile platforms, compressing the clinical intermediary role in therapeutic decision-making.
EU MDR conformity requirements for self-monitoring blood glucose systems mandate post-market clinical follow-up and enhanced biological safety documentation, elevating compliance costs for legacy meter manufacturers. The regulation forces portfolio rationalization among multi-product diagnostics conglomerates. Small-format sensor producers targeting European market entry now prioritize notified body relationships over speed-to-market, reshaping competitive entry sequencing.
Patient-consumers increasingly demand unbundled data portability, with glucose history export functionality influencing device selection independent of accuracy metrics. Direct-to-consumer subscription models for sensor replenishment displace traditional durable medical equipment procurement in United States commercial insurance segments. This behavioral pivot concentrates fastest in employer-sponsored health plans where wellness incentive structures reward continuous monitoring adherence.
Diabetes Testing System Market Segmentation
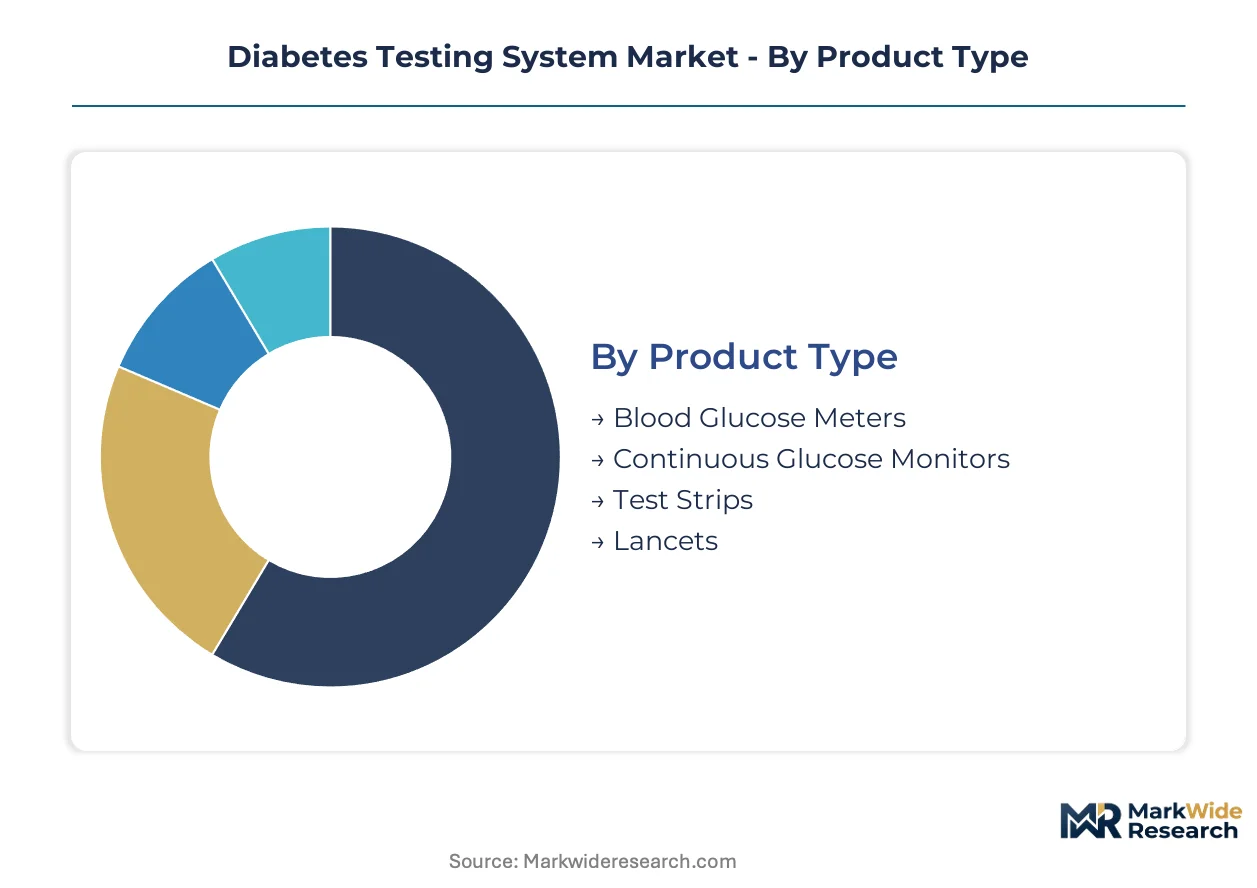
Technology modality and patient care setting determine margin structure and regulatory pathway in diabetes testing. Product architecture choices between electrochemical and optical transduction create divergent competitive moats. End-user concentration shapes distribution economics and reimbursement strategy.
Product Type:
Sensor architecture defines calibration requirements, wear duration, and recurring revenue mechanics across the four hardware categories.
- Blood Glucose Meters:Handheld electrochemical devices measuring capillary glucose through enzymatic reaction on disposable strips. Demand concentrates in India's undiagnosed diabetes population and emerging markets where cost sensitivity dominates procurement decisions.
- Continuous Glucose Monitors:Interstitial fluid sensors with factory-calibrated optical transduction eliminating fingerstick requirements. CMS non-adjunctive reimbursement in the United States accelerates clinic-to-home transitions for insulin-dependent patients.
- Test Strips:Disposable electrochemical consumables with platinum electrode dependency creating supply chain exposure to South African and Russian refining concentration.
- Lancets:Spring-loaded penetration devices for capillary blood sampling, structurally commoditized with volume tied to meter install base replacement cycles.
Continuous glucose monitors lead on scale; continuous glucose monitors lead on momentum.
End User:
Care setting determines device complexity tolerance, data integration requirements, and procurement authority concentration.
- Home Care:Self-monitoring patients prioritizing passive data capture and mobile platform integration. Japan's super-aged demographics drive demand for solutions minimizing cognitive load and manual intervention.
- Hospitals:Acute care settings requiring laboratory-grade accuracy standards and EMR connectivity for glycemic management protocols.
- Laboratories:Reference methods and quality control calibration anchoring diagnostic accuracy claims for distributed testing networks.
- Diabetes Clinics:Specialized endocrinology practices deploying CGM ecosystems through Medicare reimbursement partnerships and algorithm-driven therapeutic decision support.
Home care leads on scale; diabetes clinics lead on momentum.
Technology:
Transduction mechanism determines calibration burden, environmental sensitivity, and intellectual property differentiation.
- Electrochemical:Enzymatic glucose oxidation producing measurable current response, dominant in test strips and legacy meters with established ISO 15197 certification pathways.
- Optical:Fluorescence-based interstitial sensing enabling factory calibration and extended wear duration through drift-correction algorithms.
- Thermal:Temperature differential measurement for non-invasive glucose estimation, constrained by accuracy limitations in regulatory validation.
- Hybrid:Multi-sensor fusion combining electrochemical reference with optical continuous monitoring for closed-loop insulin delivery systems.
Electrochemical leads on scale; optical leads on momentum.
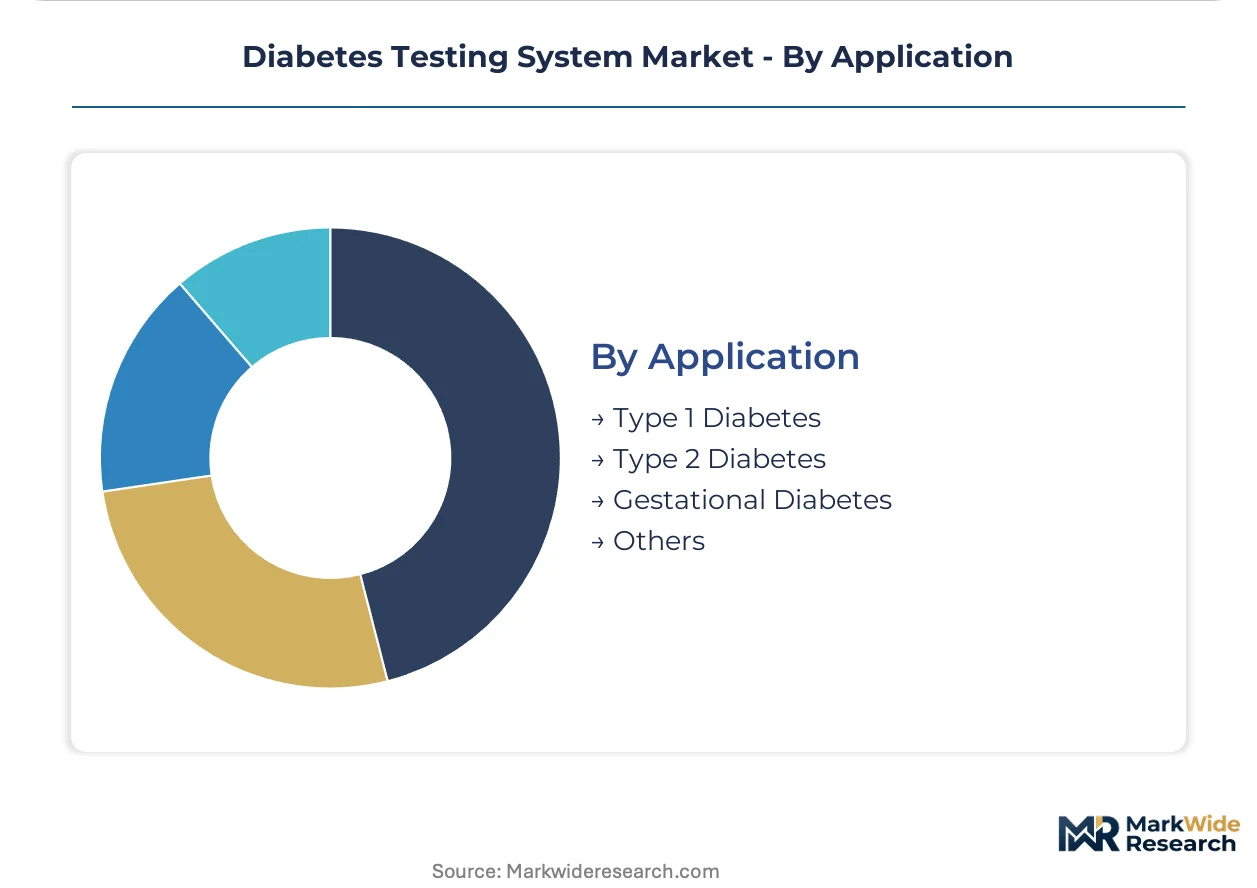
Application:
Disease severity and insulin dependency status determine monitoring intensity and reimbursement eligibility thresholds.
- Type 1 Diabetes:Absolute insulin deficiency requiring intensive glucose monitoring and pump integration, qualifying for premium CGM coverage under CMS guidelines.
- Type 2 Diabetes:Progressive insulin resistance representing the largest addressable population, with factory-calibrated sensors expanding access beyond insulin-dependent cohorts.
- Gestational Diabetes:Pregnancy-specific glycemic control requiring short-duration monitoring with obstetric clinic coordination.
- Others:Steroid-induced hyperglycemia and cystic fibrosis-related diabetes with specialized monitoring protocols in academic medical centers.
Type 2 diabetes leads on scale; Type 1 diabetes leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement generosity contrasts with India's cost-constrained procurement, creating divergent competitive entry strategies across major diabetes testing markets.
United States
CMS non-adjunctive coverage for therapeutic CGMs eliminates prior authorization barriers for insulin-dependent patients. FDA 21 CFR Part 862 Class II pathways for external sensors compress approval timelines versus implantable Class III routes. The Minneapolis-Saint Paul corridor hosts Medtronic's operational concentration for integrated pump-sensor systems.
Germany
Apotheken-led pharmacy distribution concentrates CGM dispensing through retail channels that bypass durable medical equipment markups. EU MDR conformity requirements for self-monitoring devices mandate enhanced post-market clinical follow-up documentation. The Mannheim-Ludwigshafen-Heidelberg triangle anchors Roche's diagnostic manufacturing and reference laboratory calibration infrastructure.
Japan
Patients over 75 years constitute the fastest-expanding diabetes prevalence cohort, driving demand for passive monitoring that minimizes manual intervention. PMDA regulatory frameworks for software-as-medical-device classification shape algorithm-driven product submissions. The Kansai region around Osaka hosts ARKRAY's electrochemical sensor development and domestic manufacturing footprint.
India
Approximately 57% of diabetes cases remain undetected, creating first-mover opportunity for affordable continuous monitoring platforms. CDSCO medical device rules under the Drugs and Cosmetics Act govern glucose meter registration and import licensing. The Mumbai-Pune corridor concentrates domestic diagnostics manufacturing and distribution logistics for western India market penetration.
China
Type 2 diabetes prevalence expansion among urban populations drives volume demand for factory-calibrated sensors eliminating fingerstick requirements. NMPA Class II medical device registration pathways for blood glucose monitoring systems require domestic clinical trial data. The Yangtze River Delta around Shanghai hosts contract manufacturing clusters for electrochemical test strip production serving Asia-Pacific export markets.
Diabetes Testing System Market Competitive Landscape
Top-tier vendors anchor premium CGM ecosystems, while mid-tier consumables specialists defend test strip volumes through emerging market penetration. The vendor base stratifies across three tiers: integrated sensor-pump platforms, factory-calibrated standalone monitors, and commoditized meter-strip combinations. Strategic archetypes include algorithm-centric software differentiators, platinum supply chain integrators, and pharmacy channel direct distributors. Competitive moves concentrate on Medicare reimbursement partnerships and EU MDR notified body relationship cultivation.
Within the integrated ecosystem tier, Dexcom and Abbott exemplify divergent calibration philosophies—Dexcom through clinic partnership networks and Abbott through factory-calibrated optical architectures. Medtronic occupies a position spanning sensor manufacturing and insulin pump coordination. Among laboratory-grade accuracy specialists, F. Hoffmann-La Roche anchors hospital and reference lab procurement through ISO 15197 certification depth. These three archetypes—algorithm-driven, factory-calibrated, and laboratory-anchored—capture distinct margin pools across care settings.
| Leading Market Players |
|---|
| Dexcom |
| Abbott |
| Medtronic |
| F. Hoffmann-La Roche |
| Ascensia Diabetes Care |
| LifeScan |
| Senseonics |
| ARKRAY |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Platinum group metal costs cascade from South African and Russian refining through electrochemical test strip manufacturing into three-tier pricing structure across premium, standard, and economy levels. Factory-calibrated optical sensors command premium positioning by eliminating calibration consumables, while commodity meters compete on landed cost in emerging markets.
Pricing Analysis
Capacity additions in China's Yangtze River Delta contract manufacturing clusters are reshaping price floors for electrochemical test strips. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15197-certified laboratory-grade systems from retail pharmacy meters and undifferentiated emerging market units. Pricing pressure stems from flash glucose monitoring substitution eroding recurring strip revenue. Hospital procurement committees demonstrate lowest price sensitivity; India's undiagnosed population segments exhibit highest cost consciousness.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to European distribution centers compresses margins on low-value consumables. Electrochemical sensor production draws from South African platinum, Chinese printed circuit board substrates, and German precision molding equipment. Single-source vulnerability concentrates in platinum group metal refining. Distribution runs through pharmacy retail in Germany, durable medical equipment suppliers in the United States, and direct-to-consumer subscription platforms in employer-sponsored health plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
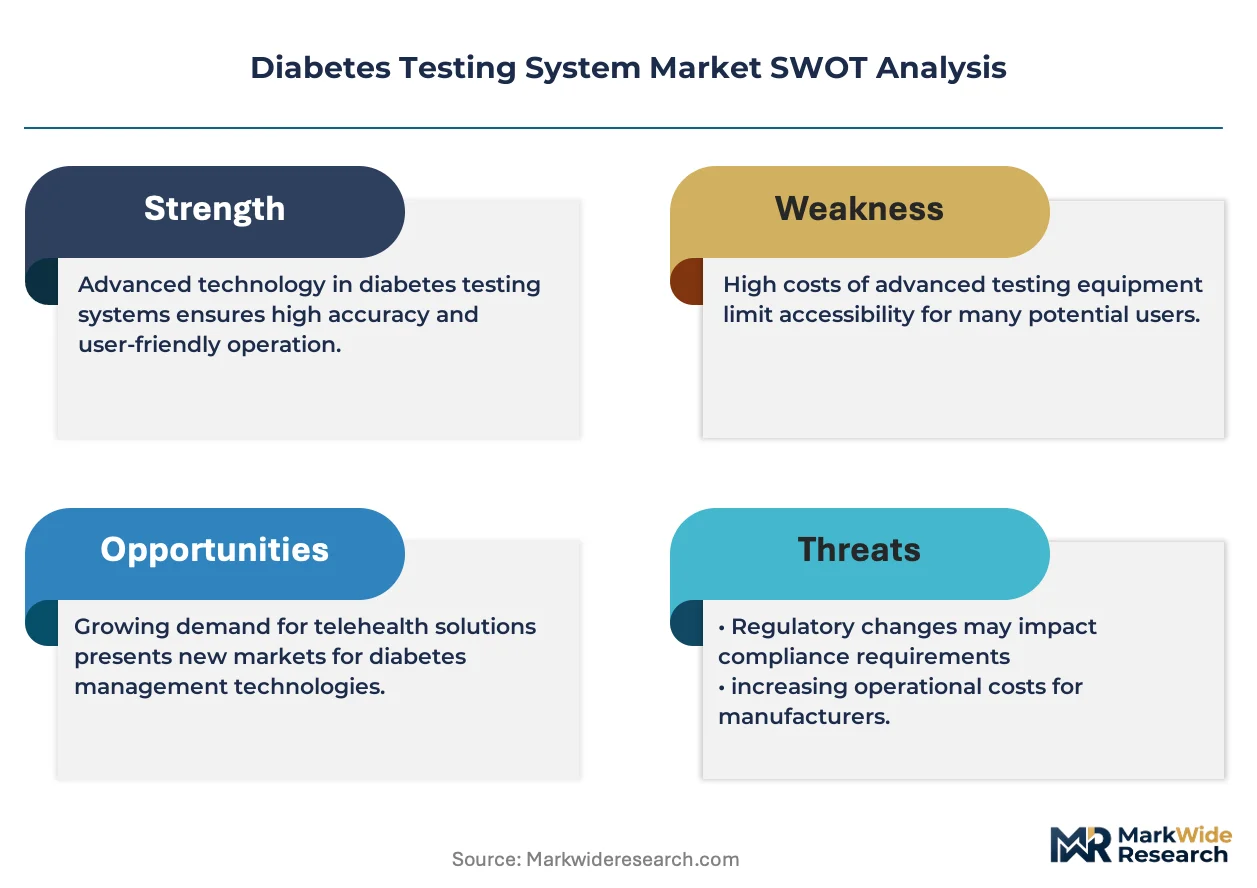
This market represents a late-cycle quality story as patient-consumers migrate toward factory-calibrated continuous monitoring with algorithm-driven predictive alerts. Premium specification demand concentrates in Medicare-eligible insulin-dependent cohorts seeking integrated closed-loop ecosystems.
For Market Incumbents: Extend sensor wear duration through hydrogel-enzyme stabilization investments to defend against emerging algorithm-centric entrants. Deepen Medicare reimbursement partnerships and endocrinology clinic integration to anchor therapeutic CGM positioning. Prioritize EU MDR notified body relationship cultivation ahead of legacy meter portfolio rationalization.
For New Entrants and Emerging Players: Launch via direct-to-consumer pharmacy channel models in Germany's Apotheken-led system to bypass incumbent DME markups. Target India's undiagnosed diabetes burden with affordable factory-calibrated platforms that circumvent clinic diagnostic bottlenecks. Emphasize mobile platform data portability as patient selection criterion independent of accuracy metrics.
For Investors and Strategic Acquirers: Consolidation pressure builds where biocompatibility engineering talent scarcity constrains R&D velocity for mid-tier manufacturers. Five-to-ten year viability favors algorithm-driven sensor-pump-controller ecosystems over commoditized meter-strip combinations. Watch CMS decisions on non-adjunctive CGM claims expansion as inflection signal for market power redistribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS non-adjunctive coverage determination unlocks Medicare patient access for therapeutic CGMs. |
| Hospital System Partnership | Endocrinology clinic alliances anchor prescription volume and algorithm-driven therapeutic decision support. |
| Software Companion Development | Predictive alert algorithms displace hardware-centric value propositions in patient platform selection. |
| CE Marking Pathway | EU MDR conformity documentation elevates compliance costs forcing portfolio rationalization among legacy manufacturers. |
| FDA Submission | Class II 510(k) pathway for external sensors compresses approval timelines versus implantable Class III routes. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market cluster. The research combines interviews with endocrinologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and pharmacy channel distributors with secondary validation against FDA 510(k) filings, CMS Medicare coverage determinations, EU MDR notified body documentation, and hospital procurement databases. Bottom-up patient population estimates triangulate against top-down manufacturer revenue analysis.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the projection horizon. Segmentation dimensions modeled include technology modality, care setting, insulin dependency status, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, reimbursement expansion scenarios, and sensor wear duration extension curves. Forecast inputs incorporate platinum group metal price volatility and algorithm regulatory classification precedents.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA Class III pathway delays or platinum supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Sperm Density Testing Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Global Transplant Diagnostics Market