
 Healthcare Automatic Identification and Data Capture (AIDC) Market | 2026-2036
Healthcare Automatic Identification and Data Capture (AIDC) Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Automatic Identification and Data Capture (AIDC) Market Intelligence
Acute care hospitals are collapsing the historical distance between procurement and clinical operations as they mandate bedside scanning for medication administration. Zebra Technologies leverages its printer-scanner ecosystem to anchor hospital ward deployments across North America. SATO Holdings Corporation sustains competitive position through specialized RFID tag durability for sterilization cycles in surgical supply chains. Honeywell competes on ruggedized mobile computer form factors that withstand repeated disinfection protocols in intensive care environments.
Healthcare Automatic Identification and Data Capture encompasses machine-readable data collection technologies—barcode symbologies, radio-frequency identification tags, biometric sensors, and voice-directed terminals—that capture patient, specimen, pharmaceutical, and asset identifiers with near-zero error rates, typically achieving read accuracies above 99.9% in controlled clinical settings. These systems automate identity verification and chain-of-custody documentation across care delivery workflows. Barcode scanners occupy the largest installed base due to low per-unit cost and universal compatibility with legacy hospital information systems. RFID readers represent the fastest-expanding product category as item-level tagging extends from high-value implantable devices to standard pharmaceutical inventory. Biometric systems command premium positioning where patient misidentification carries severe liability exposure, such as blood transfusion and surgical site verification protocols.
FDA enforces unique device identification through its GUDID database, compelling manufacturers to adopt GS1-standard barcoding for Class II and III medical devices. EMA aligns with EU MDR traceability mandates that require device-level serialization across the European Economic Area. Japan's PMDA promotes JIS-standardized auto-identification for pharmaceutical distribution integrity. Stakeholders must evaluate cloud-based deployment architectures against hybrid configurations as cybersecurity frameworks from HIPAA and GDPR impose divergent data residency and breach notification obligations on cross-border healthcare networks.
Market Dynamics
Hospital procurement departments are collapsing the traditional separation between supply chain and clinical workflows by mandating bedside scanning for medication administration and specimen tracking.
Growth Catalysts
- FDA UDI Mandate:The GUDID database compels Class II and III medical device manufacturers to adopt GS1-standard barcoding, forcing supply chain digitization across United States hospital networks.
- Surgical RFID Integration:Sterilization-trackable RFID tags now anchor implantable device traceability in orthopedic and cardiovascular operating suites, eliminating manual documentation errors.
- EU MDR Traceability:Device-level serialization requirements across the European Economic Area accelerate barcode and RFID deployment in German and French hospital procurement systems.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-dominant chip fabrication creates vulnerability in RFID reader and mobile computer production, extending lead times for hospital hardware orders.
- Legacy System Integration Costs:Proprietary hospital information system architectures in older United States academic medical centers demand expensive middleware for AIDC connectivity.
- Biometric Hardware Premium:Fingerprint and iris recognition sensors carry 3-4x cost multiples versus barcode scanners, limiting deployment to high-liability transfusion and surgical verification protocols.
Strategic Opportunities
- Home Healthcare Expansion:Remote patient monitoring programs in Japan and Germany create demand for portable barcode and RFID solutions outside traditional hospital walls.
- AI-Vision Convergence:Computer vision systems paired with existing camera infrastructure offer retrofit patient identification without dedicated hardware replacement cycles.
- India PLI Incentives:Production-linked incentive schemes for electronics manufacturing attract AIDC hardware assembly, reducing import dependence for domestic hospital procurement.
Industry Challenges
- Interoperability Standards Gap:Competing RFID frequency protocols between 860-960 MHz UHF and 13.56 MHz HF create confusion in multi-vendor hospital deployments, requiring costly dual-mode reader investments.
- Cybersecurity Certification Burden:HIPAA and GDPR breach notification rules impose divergent data residency and encryption requirements on cloud-based AIDC architectures, complicating cross-border hospital network design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Automatic Identification and Data Capture (AIDC) Market |
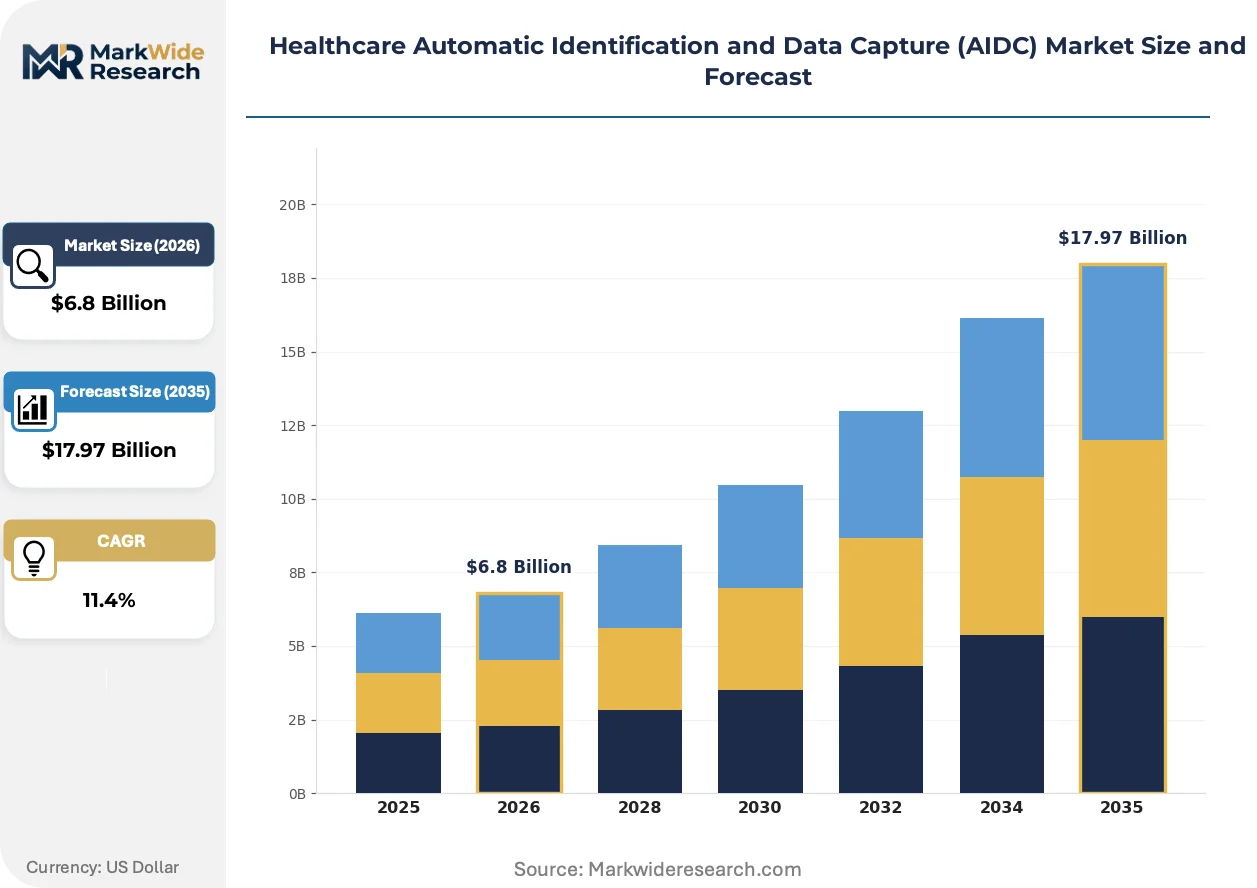
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barcode Scanners, RFID Readers, Biometric Systems, Voice Recognition Devices Application: Patient Identification, Asset Tracking, Medication Administration, Inventory Management End User: Hospitals, Diagnostic Laboratories, Pharmacies, Long-Term Care Facilities Deployment Type: On-Premises, Cloud-Based, Hybrid, Mobile Platforms |
| Companies Covered | SICK AG, SATO Holdings Corporation, Zebra Technologies, Bluebird Inc., Denso Wave, Honeywell, Cognex Corporation, TSC Auto ID Technology Co., Ltd., Datalogic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Automatic Identification and Data Capture (AIDC) Market Strategic Shifts & Innovations
Active RFID and real-time location systems are displacing passive barcode dominance in asset-intensive hospital environments, while biometric verification protocols expand beyond traditional patient wristband models.
Passive UHF RFID tagging is fragmenting the implantable medical device traceability landscape. Surgical supply chains in United States tertiary hospitals now demand sterilization-cycle survivable tags for instrument sets and high-value implants. This fragmentation is compressing the historical barcode-RFID cost gap and enabling item-level tracking for standard inventory previously managed through lot-level barcoding.
EU MDR device traceability mandates are restructuring European hospital procurement specifications. The regulation requires Unique Device Identification persistence across the device lifecycle, compelling German and French distributors to deploy serialized data capture infrastructure. Class III cardiovascular and orthopedic implant suppliers face the steepest compliance timelines, accelerating RFID reader investments in sterile processing departments.
Bedside medication administration verification is reshaping nursing workflow patterns in acute care settings. United States hospital systems now require dual-identifier scanning—patient wristband plus medication label—before any pharmaceutical dispensing, replacing paper-based triple-check protocols. This behavioral shift concentrates demand for cordless 2D imagers and antimicrobial-coated mobile computers in medical-surgical units and emergency departments.
Healthcare Automatic Identification and Data Capture (AIDC) Market Segmentation
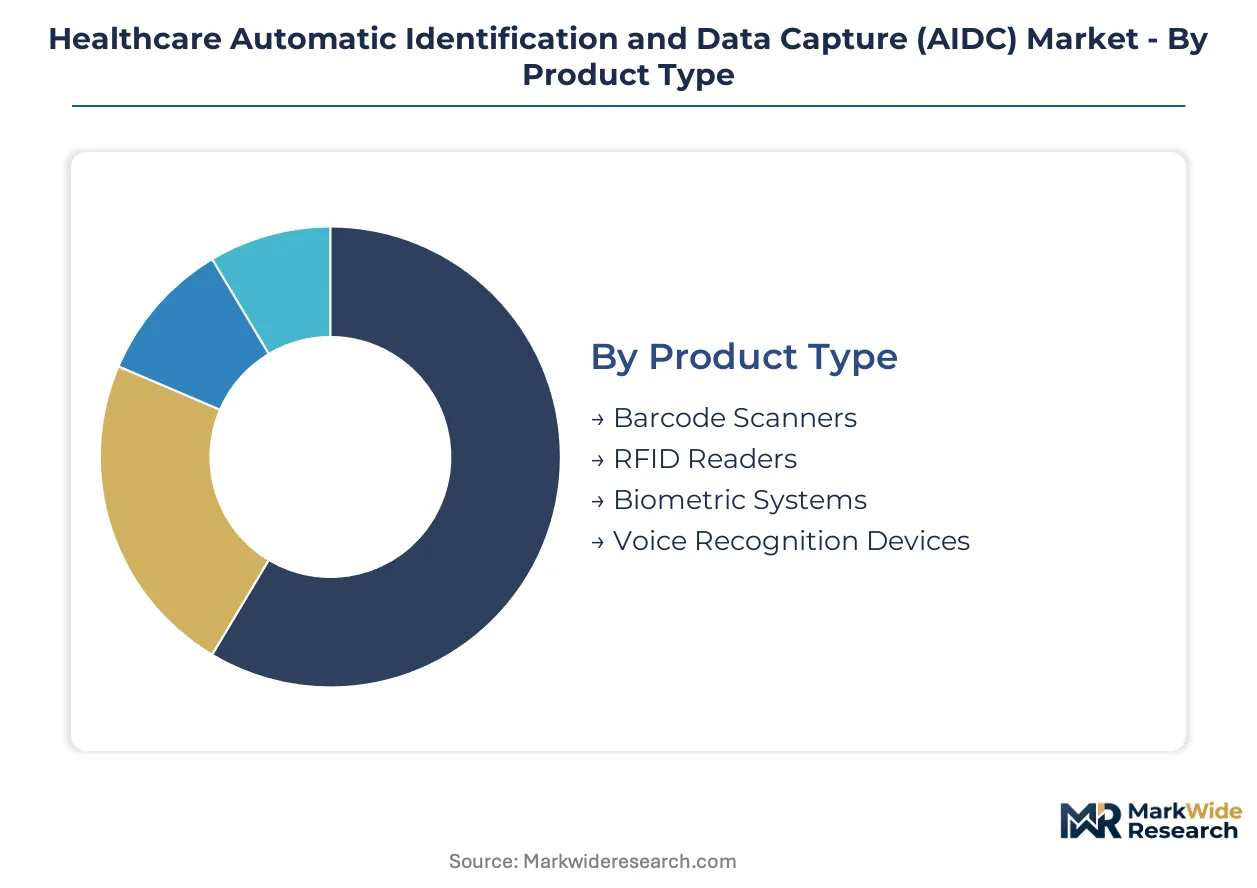
Healthcare AIDC segmentation reveals distinct procurement patterns across product categories, with hospital systems prioritizing integration-ready solutions that satisfy FDA UDI and EU MDR compliance mandates. Technology selection varies sharply by care setting intensity, from high-throughput barcode scanning in emergency departments to biometric verification in surgical suites.
Product Type:
Barcode scanners dominate domestic hospital procurement in the United States and Germany, while RFID readers capture export-led demand from Japanese and French medical device manufacturers seeking sterilization-trackable tags.
- Barcode Scanners:Linear and 2D imagers utilizing laser or CCD sensors achieve read rates above 99.9% on GS1-standard medication labels. United States acute care hospitals concentrate demand for cordless, antimicrobial-coated units in medical-surgical units driven by Joint Commission bedside verification mandates. The installed base spans legacy infrastructure, constraining rapid replacement cycles despite superior RFID accuracy.
- RFID Readers:UHF and HF frequency readers capture passive and active tag data for implantable device traceability. German and French orthopedic suppliers drive export demand for sterilization-cycle survivable tags under EU MDR serialization requirements. Semiconductor supply concentration from Taiwan fabrication creates lead time vulnerability for hospital hardware procurement.
- Biometric Systems:Fingerprint and iris recognition sensors command premium positioning in blood transfusion and surgical site verification protocols where patient misidentification carries severe liability exposure.
- Voice Recognition Devices:Hands-free terminals enable specimen collection documentation in sterile processing environments, penetrating slowly due to accent recognition limitations in diverse clinical workforces.
Barcode scanners command the established base. The steepest expansion runs through RFID readers.
Application:
Patient identification absorbs the highest per-unit technology investment, while medication administration generates volume demand through ward-level scanner deployment across cost-tiered hospital systems.
- Patient Identification:Dual-identifier verification protocols—wristband plus biometric or barcode cross-check—eliminate wrong-patient errors in high-acuity settings. United States health systems facing malpractice exposure drive concentration in academic medical centers and tertiary referral hospitals. HIPAA breach notification rules complicate cloud-based biometric data architectures.
- Medication Administration:Bedside scanning with electronic medication administration record integration replaces paper triple-check protocols in medical-surgical and emergency departments. Japan's PMDA pharmaceutical distribution integrity standards accelerate barcode standardization in domestic hospital networks.
- Asset Tracking:Real-time location systems utilizing active RFID tags monitor mobile medical equipment utilization rates, reducing rental expenditure and capital duplication.
- Inventory Management:Automated dispensing cabinet integration with perpetual inventory systems prevents pharmaceutical stockouts and expiration waste in hospital pharmacies.
Patient identification captures premium pricing. Medication administration scales fastest across installed hospital bases.
End User:
Hospitals concentrate procurement volume in North American and Western European markets, while diagnostic laboratories in Japan and Germany drive specialized specimen tracking demand.
- Hospitals:Acute care systems integrate AIDC across admission, pharmacy, laboratory, and surgical workflows as enterprise-wide patient safety infrastructure. United States health networks consolidate vendor relationships to reduce middleware integration costs for legacy information systems.
- Diagnostic Laboratories:High-throughput specimen processing facilities in Japan and Germany deploy automated tube identification and sortation systems. JIS-standardized auto-identification requirements from PMDA shape domestic procurement specifications.
- Pharmacies:Retail and hospital dispensaries utilize barcode verification for dispense-to-patient accuracy, with mail-order facilities adding automated packaging line integration.
- Long-Term Care Facilities:Skilled nursing and assisted living operators lag acute care adoption due to thinner operating margins and lower regulatory pressure for electronic verification.
Hospitals anchor procurement volume. Diagnostic laboratories expand most quickly as precision medicine drives specimen complexity.
Deployment Type:
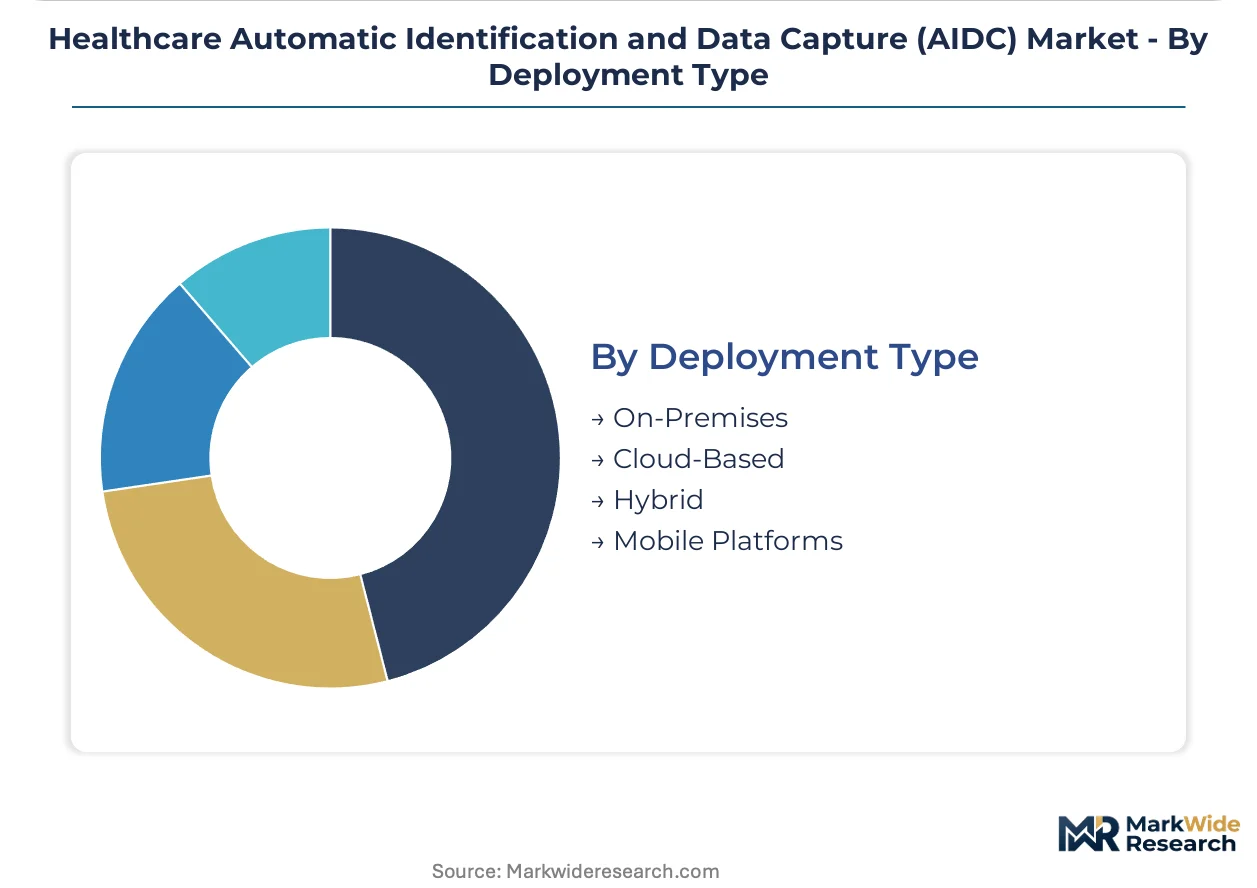
On-premises architectures satisfy HIPAA and GDPR data residency requirements in United States and German hospital networks, while cloud-based platforms gain traction in smaller facilities with limited IT staffing.
- On-Premises:Local server installations maintain physical control over patient identifier databases, satisfying strict breach notification timelines under United States and European privacy frameworks. German university hospitals prefer this architecture for surgical workflow data.
- Cloud-Based:SaaS delivery models reduce capital expenditure for community hospitals and long-term care chains, though GDPR cross-border transfer restrictions limit European adoption.
- Hybrid:Edge computing configurations process time-sensitive identification locally while archiving to cloud repositories, balancing latency and scalability requirements.
- Mobile Platforms:Smartphone and tablet-based scanning applications leverage existing clinical device fleets, avoiding dedicated hardware procurement in cost-constrained settings.
On-premises deployment retains the dominant share. Mobile platforms climb fastest as bring-your-own-device policies spread through nursing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and Japan concentrate demand for AIDC hardware, driven by converging regulatory mandates and digitization investments. These three markets absorb the majority of barcode scanner and RFID reader shipments, with secondary demand emerging from diagnostic laboratories and surgical supply chains.
United States
Acute care hospitals mandate bedside scanning for medication administration under Joint Commission patient safety standards. FDA enforces unique device identification through the GUDID database, compelling Class II and III medical device manufacturers to adopt GS1-standard barcoding. Boston and New York metropolitan health networks anchor enterprise-wide AIDC deployments across admission, pharmacy, and surgical workflows.
Germany
Orthopedic and cardiovascular implant suppliers drive sterilization-trackable RFID tag demand for surgical instrument sets. EU MDR traceability requirements mandate device-level serialization across the European Economic Area, restructuring procurement specifications for German hospital networks. Bavarian medical technology clusters concentrate RFID reader investments in sterile processing departments.
Japan
PMDA pharmaceutical distribution integrity standards accelerate barcode standardization in domestic hospital networks and high-throughput diagnostic laboratories. JIS-standardized auto-identification requirements shape procurement specifications for specimen tracking systems. Tokyo and Osaka metropolitan areas deploy automated tube identification in precision medicine facilities.
United Kingdom
NHS digitization programs expand patient identification infrastructure across acute trusts and community health services. GDPR data residency requirements favor on-premises AIDC architectures over cloud-based alternatives in London and Southeast England health networks. Blood transfusion services drive biometric verification adoption where misidentification carries severe liability exposure.
India
Production-linked incentive schemes for electronics manufacturing attract AIDC hardware assembly, reducing import dependence for domestic hospital procurement. CDSCO medical device regulations are aligning with international traceability standards, accelerating barcode adoption in Mumbai and Delhi-NCR tertiary hospitals. Diagnostic laboratory chains in Maharashtra and Karnataka deploy automated specimen identification systems.
Healthcare Automatic Identification and Data Capture (AIDC) Market Key Industry Players
Player mix skews toward diversified industrial technology conglomerates with established healthcare verticals, supplemented by specialized auto-identification pure-plays. Market structure exhibits moderate consolidation around printer-scanner ecosystem providers and RFID component specialists. Three archetypes dominate: full-stack hardware-software integrators, sterilization-durable tag specialists, and ruggedized mobile computer manufacturers. Competitive intensity centers on middleware integration capabilities for legacy hospital information systems and strategic partnerships with medical device manufacturers seeking UDI compliance.
Among diversified technology conglomerates, Honeywell and Zebra Technologies exemplify the full-stack integration archetype, anchoring hospital ward deployments through antimicrobial-coated mobile computers and cordless 2D imagers. SATO Holdings Corporation occupies a specialist position focused on RFID tag durability for sterilization cycles in surgical supply chains. These three companies represent distinct competitive vectors: ecosystem breadth, hardware ruggedization, and application-specific material science.
| Leading Market Players |
|---|
| SICK AG |
| SATO Holdings Corporation |
| Zebra Technologies |
| Bluebird Inc. |
| Denso Wave |
| Honeywell |
| Cognex Corporation |
| TSC Auto ID Technology Co., Ltd. |
| Datalogic |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Taiwan semiconductor foundries shapes both RFID reader production economics and hospital hardware price floors across United States and German procurement markets. Contract manufacturers serving Zebra Technologies and Honeywell face margin compression when 300mm wafer allocation tightens, forcing tiered pricing adjustments downstream through distributor networks.
Pricing Analysis
Cost-plus contracts with Taiwan Semiconductor Manufacturing Company indexation anchor mobile computer and RFID reader pricing for North American hospital networks. Three-tier pricing structure across premium antimicrobial-coated units, standard ward-grade scanners, and economy tethered imagers reflects FDA UDI compliance certification levels. Pricing pressure stems from CDSCO alignment demands in Indian tertiary hospitals seeking import substitution. Academic medical centers show lowest price sensitivity due to Joint Commission liability exposure, while long-term care facilities resist hardware refresh cycles.
Supply Chain Analysis
Inventory buffers for UHF RFID chips stretch to sixteen-week lead times when Taiwan fabrication capacity diverts to automotive sensor demand. Semiconductor supply concentrates in Taiwan, South Korea, and Japan for reader chipsets, while stainless steel antimicrobial housings source from Chinese and German metalwork specialists. Single-source vulnerability in 13.56 MHz HF transceiver modules creates procurement risk for European sterile processing departments. Distribution runs through GPO contracts in United States health networks and direct OEM relationships in German university hospital systems.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare AIDC represents a service-attach opportunity where software subscription layers for electronic medication administration record integration expand faster than hardware replacement cycles. Recurring revenue from middleware maintenance and FDA GUDID compliance updates now exceeds scanner unit margins for incumbent vendors.
For Market Incumbents: Secure sterilization-durable RFID tag certification portfolios against emerging pure-play specialists from Japanese medical device clusters. Defend hospital ward deployments by deepening backward integration into antimicrobial coating supply chains, reducing Taiwanese semiconductor exposure through dual-source reader chipset qualification.
For New Entrants and Emerging Players: Lead with AI-vision retrofit solutions targeting United States community hospitals with limited capital budgets for dedicated scanner hardware. Penetrate diagnostic laboratory specimen tracking in Maharashtra and Karnataka where CDSCO traceability alignment creates procurement specification windows. Partner with Indian electronics manufacturing service providers leveraging PLI incentives for cost-competitive mobile computer assembly.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization-durable tag specialists with EU MDR serialization compliance over commoditized barcode scanner manufacturers. Long-term viability rests on software companion development capabilities for hospital information system integration. Monitor FDA UDI enforcement intensity as inflection signal for Class III implant supplier RFID adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Joint Commission bedside verification mandates lock in multi-year scanner deployment contracts across admission and pharmacy workflows. |
| FDA Submission | Unique Device Identification database registration enables Class II and III medical device manufacturer sales to United States health networks. |
| Software Companion Development | Electronic medication administration record integration differentiates hardware vendors in United States medical-surgical unit procurement. |
| CE Marking Pathway | EU MDR traceability compliance opens German and French orthopedic implant supplier RFID tag markets. |
| Reimbursement Strategy | PMDA pharmaceutical distribution integrity standards accelerate barcode standardization in Japanese hospital network procurement specifications. |
Research Approach
Desk research of FDA GUDID database filings, EU MDR technical documentation, and Japanese PMDA pharmaceutical distribution standards preceded structured interviews with hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and sterile processing department heads. Secondary validation drew from hospital procurement databases, GS1 healthcare implementation case studies, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up unit shipment estimates triangulated against top-down healthcare IT capital expenditure projections.
Variance decomposition across product type, application intensity, end-user scale, and deployment architecture informed analytical framework construction throughout the forecast period. CAGRs derived from logistic diffusion modeling of bedside scanning mandate compliance curves and RFID sterilization-cycle adoption thresholds in orthopedic surgical supply chains. Modeled inputs included Joint Commission survey deficiency rates and EU MDR notified body certification timelines.
Forecasts assume regulatory continuity in FDA UDI enforcement, EU MDR serialization requirements, and PMDA JIS standardization regimes; material policy shifts would require re-modeling adoption velocity assumptions. Semiconductor supply concentration in Taiwan fabrication and HIPAA-GDPR data residency friction represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global E-Health Market
Health Informatics
Allergy Care Market
Health Informatics
Healthcare BI Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
AI in Healthcare Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Laboratory Informatics Market
Health Informatics
US Healthcare Payer Analytics Market