
 In Vitro Diagnostics Test Kit Market | 2026-2036
In Vitro Diagnostics Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Diagnostics Test Kit Market Analytics
China is rewriting competitive dynamics in the in vitro diagnostics test kit landscape through aggressive capacity expansion in molecular diagnostics manufacturing clusters. Danaher sustains technology leadership through integrated workflow automation spanning sample prep to result reporting. Abbott Laboratories anchors point-of-care penetration with handheld immunoassay platforms designed for decentralized settings. Siemens Healthineers competes on imaging-diagnostic convergence, bundling test kits with installed analytical instruments.
An in vitro diagnostics test kit comprises reagent-based consumables paired with calibrated detection systems, typically employing monoclonal antibodies, nucleic acid primers, or chromogenic substrates to quantify biomarkers in blood, urine, or tissue specimens with defined sensitivity thresholds. These kits serve clinical decision-making by enabling standardized, reproducible disease screening and therapeutic monitoring across distributed healthcare settings. Molecular diagnostics represents the fastest-expanding product category, driven by PCR and next-generation sequencing adoption for oncology and infectious disease profiling. Immunoassays retain the largest revenue share, particularly in clinical laboratories processing high-volume routine panels where ELISA automation drives per-test economics. Point-of-care applications are capturing disproportionate investment as manufacturers miniaturize lateral flow and cartridge-based systems for home care and ambulatory deployment.
FDA oversight of in vitro diagnostics through premarket notification and approval pathways directly shapes product development timelines and commercial access in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking across European markets. China's NMPA has accelerated review timelines for innovative diagnostics under priority review channels, redirecting multinational submission strategies toward domestic registration. Stakeholders must monitor evolving convergence between software-enabled algorithms and kit-based testing, as regulatory frameworks for AI-integrated diagnostics remain unsettled across major jurisdictions.
Market Dynamics
Companion diagnostics for precision oncology is compressing development cycles as pharmaceutical sponsors now require biomarker stratification in Phase II trials, forcing IVD manufacturers to synchronize kit validation with drug approval timelines.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for CE marking are elevating barriers for marginal competitors, consolidating share among established kit manufacturers with robust quality management systems.
- Molecular diagnostics manufacturing clusters in China:Domestic producers scaling PCR and NGS capacity for infectious disease surveillance are redirecting regional supply chains and compressing import dependency.
- Next-generation sequencing:Declining per-run costs are expanding oncology profiling from academic medical centers into community hospital laboratories, broadening addressable test volumes.
Market Restraints
- Monoclonal antibody raw material concentration:Bioreactor capacity for high-affinity antibodies concentrates among three contract manufacturers, exposing kit producers to allocation risk during demand surges.
- FDA laboratory-developed test framework uncertainty:Pending reclassification of LDTs as medical devices threatens to disrupt clinical laboratory economics and kit substitution patterns.
- Lateral flow sensitivity ceilings:Intrinsic limits in visual detection thresholds constrain point-of-care applications for low-abundance biomarkers without reader instrumentation.
Strategic Opportunities
- Home-based infectious disease surveillance:Post-pandemic consumer familiarity with self-testing creates white space for multiplex respiratory panels beyond COVID-19 into influenza and RSV.
- AI-integrated diagnostic algorithms:Regulatory frameworks for software-as-medical-device remain unsettled, offering first-mover advantage to kit manufacturers bundling interpretive algorithms with consumables.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing are attracting component suppliers and contract kit assemblers to establish regional supply nodes.
Industry Challenges
- Bioinformatics pipeline integration:NGS kit deployment requires laboratory information system upgrades and staff retraining, slowing adoption in resource-constrained settings.
- ISO 13485 certification backlog:Notified body capacity constraints are extending quality management system audit timelines, delaying market entry for novel kit submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Diagnostics Test Kit Market |
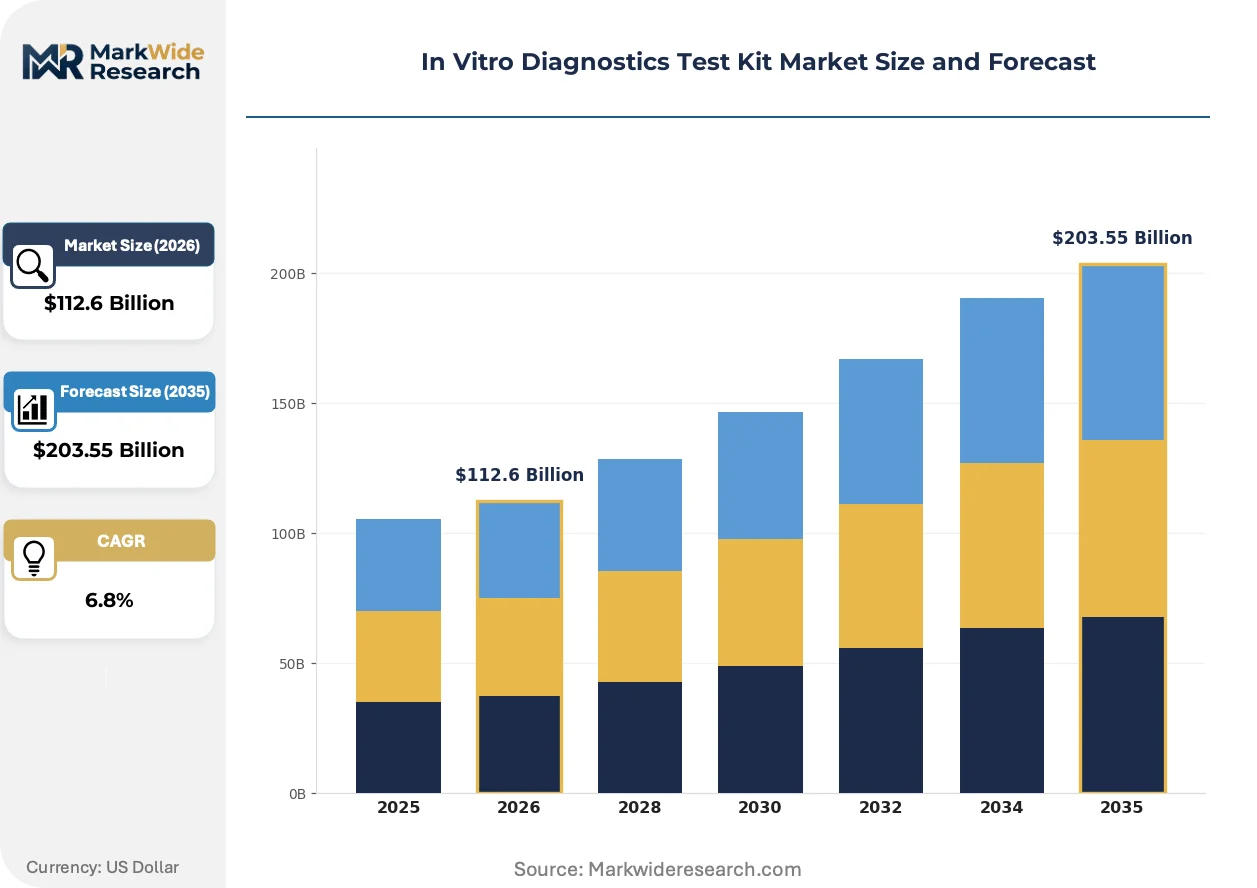
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Microbiology, Hematology Application: Clinical Laboratories, Hospitals, Home Care, Point-of-Care Technology: ELISA, PCR, Next-Generation Sequencing, Lateral Flow Assays End User: Healthcare Providers, Research Institutions, Diagnostic Laboratories, Pharma Companies |
| Companies Covered | F. Hoffmann-La Roche Ltd, Danaher, Abbott Laboratories, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., bioMérieux SA, Becton, Dickinson and Company, QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Diagnostics Test Kit Market Evolving Landscape
Workflow automation is compressing hands-on time requirements while expanding test throughput, reshaping capital equipment procurement criteria and reagent consumption economics across laboratory segments.
Digital PCR technology is hybridizing with next-generation sequencing workflows, enabling absolute quantification of circulating tumor DNA without standard curve dependencies. Oncology reference laboratories are adopting these hybrid platforms for minimal residual disease monitoring. The convergence is compressing validation timelines by consolidating biomarker detection onto unified instrumentation.
China's NMPA priority review channels for innovative diagnostics are accelerating domestic approval timelines, redirecting multinational submission strategies toward Shanghai and Beijing registration offices. This regulatory tailwind is concentrating molecular diagnostics launches in the Chinese market ahead of European CE marking. Domestic manufacturers are exploiting this asymmetry to build installed base before global competitors secure access.
Hospital procurement consortia are consolidating purchasing authority for high-volume immunoassay panels, displacing decentralized laboratory buying. This concentration is compressing price negotiation cycles and favoring kit suppliers with multi-year consumable contracts. The shift is most visible in Germany's university hospital networks and France's hospital group purchasing organizations.
In Vitro Diagnostics Test Kit Market Segmentation
Segmentation in the In Vitro Diagnostics Test Kit Market reveals distinct technology-adoption curves and purchasing authority patterns. Manufacturers configure kit portfolios differently depending on whether target customers operate centralized laboratory automation or decentralized point-of-care workflows.
Product Type:
Mature consumable categories dominate installed base economics while emerging molecular platforms capture disproportionate R&D investment.
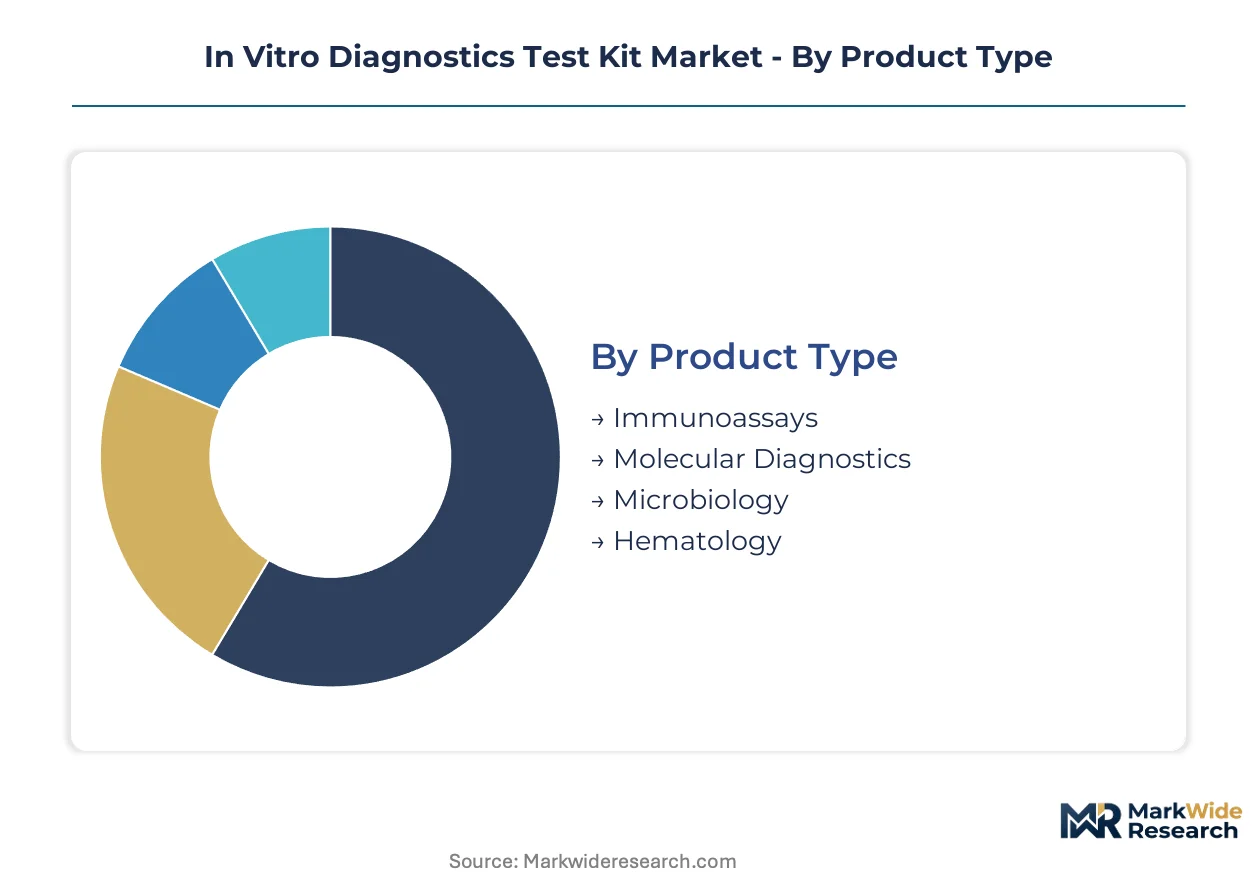
- Immunoassays:Antibody-antigen reaction systems employing monoclonal or polyclonal detection antibodies with chromogenic, chemiluminescent, or fluorescent readouts. Clinical laboratories in Germany and the United States concentrate procurement for high-throughput cardiac and thyroid panels, though monoclonal antibody raw material concentration among three contract manufacturers exposes producers to allocation risk during demand surges.
- Molecular Diagnostics:Nucleic acid amplification and detection systems utilizing PCR primers, fluorescent probes, or sequencing adapters to quantify pathogen or oncogene targets. China's domestic manufacturing clusters are scaling PCR and NGS capacity for infectious disease surveillance, redirecting regional supply chains and compressing import dependency for respiratory and oncology profiling.
- Microbiology:Culture-based and rapid antigen detection systems for bacterial and fungal identification in clinical specimens.
- Hematology:Cell counting and coagulation assay consumables supporting complete blood count and hemostasis monitoring in hospital laboratories.
Immunoassays retain volume leadership; molecular diagnostics holds the steepest expansion curve.
Application:
Customer-site requirements split between high-throughput automation tolerance and portability constraints.
- Clinical Laboratories:Centralized facilities processing batched specimens through automated analyzers with integrated quality control systems. Hospital procurement consortia in Germany's university networks and France's group purchasing organizations are consolidating purchasing authority, displacing decentralized laboratory buying and compressing price negotiation cycles for multi-year consumable contracts.
- Hospitals:Acute care settings demanding rapid turnaround for emergency department and intensive care decision support.
- Home Care:Self-administered testing environments requiring minimal technical training and result interpretation without laboratory infrastructure. Post-pandemic consumer familiarity with self-testing in the United States and United Kingdom creates white space for multiplex respiratory panels beyond COVID-19 into influenza and RSV surveillance.
- Point-of-Care:Near-patient deployment settings including physician offices, ambulatory clinics, and retail health locations. Lateral flow sensitivity ceilings constrain applications for low-abundance biomarkers without reader instrumentation, though miniaturized cartridge-based systems are capturing disproportionate manufacturer investment for decentralized deployment.
Clinical laboratories command the largest kit volumes; home care applications are climbing the fastest.
Technology:
Detection chemistry and signal amplification methods stratify by capital equipment requirements and analytical sensitivity thresholds.
- ELISA:Enzyme-linked immunosorbent assay platforms employing microplate formats with colorimetric or chemiluminescent endpoint detection. High-volume clinical laboratories leverage ELISA automation to drive per-test economics for routine infectious disease and hormone panels.
- PCR:Polymerase chain reaction systems utilizing thermal cycling and fluorescent probe hybridization for nucleic acid quantification. China's NMPA priority review channels are accelerating domestic approval timelines, redirecting multinational submission strategies toward Shanghai and Beijing registration offices ahead of European CE marking.
- Next-Generation Sequencing:Massively parallel sequencing workflows generating comprehensive genomic profiles for oncology and rare disease applications. Declining per-run costs are expanding adoption from academic medical centers into community hospital laboratories, though bioinformatics pipeline integration requires laboratory information system upgrades and staff retraining that slows deployment in resource-constrained settings.
- Lateral Flow Assays:Immunochromatographic strip formats enabling visual result interpretation without instrumentation. Intrinsic detection threshold limits constrain use for low-abundance biomarkers, restricting penetration to high-concentration analytes in infectious disease and fertility testing.
PCR retains the broadest installed base; next-generation sequencing is gaining share fastest.
End User:
Purchasing authority and technical capability requirements diverge sharply across institutional categories.
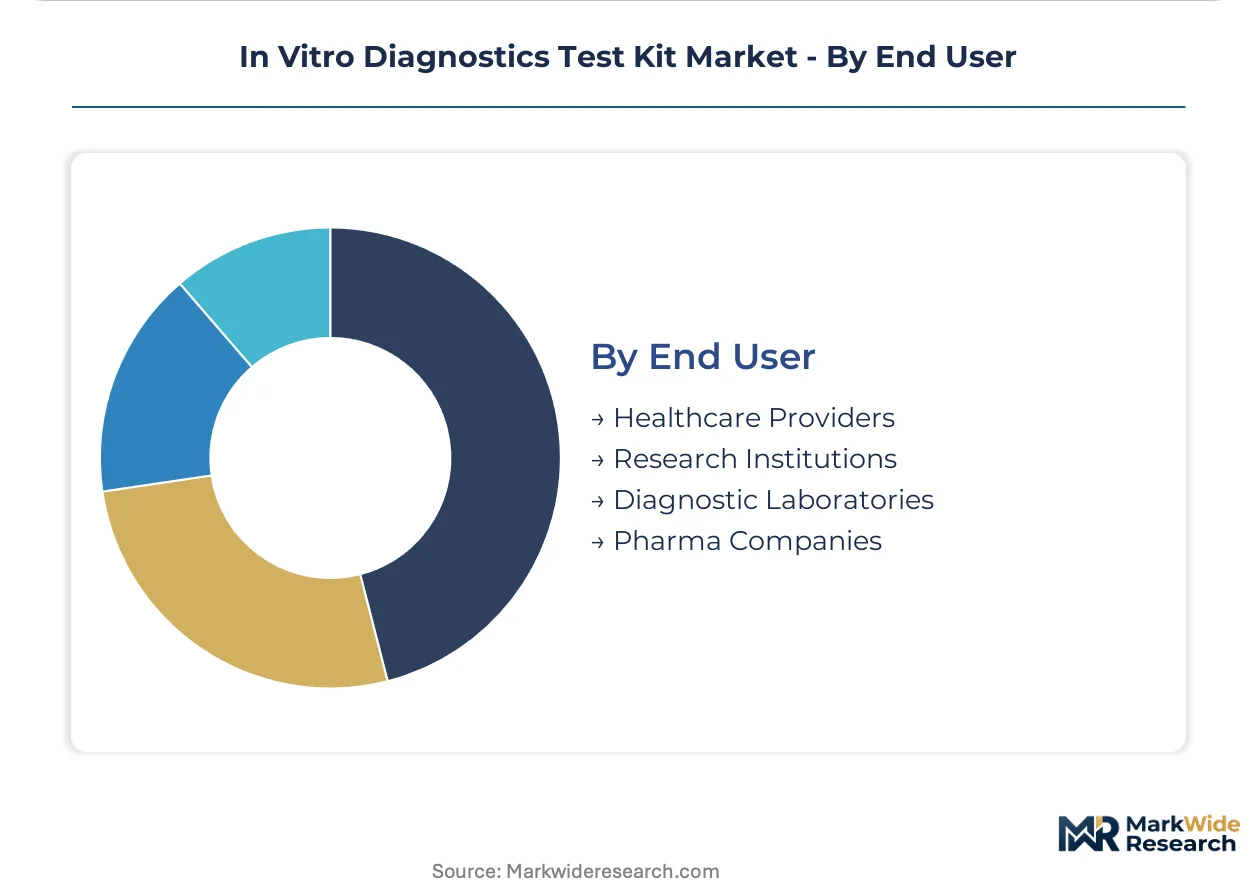
- Healthcare Providers:Hospital systems and physician networks integrating diagnostic results into treatment decisions. Workflow automation is compressing hands-on time requirements while expanding test throughput, reshaping capital equipment procurement criteria and reagent consumption economics.
- Research Institutions:Academic and government laboratories employing investigational protocols without diagnostic claims. These users prioritize analytical flexibility and custom assay development support over regulatory clearance status.
- Diagnostic Laboratories:Independent reference laboratories and hospital-affiliated clinical labs operating under accredited quality management systems. ISO 13485 certification backlog from notified body capacity constraints is extending quality management system audit timelines, delaying market entry for novel kit submissions.
- Pharma Companies:Biopharmaceutical sponsors requiring companion diagnostics for precision oncology trials. Biomarker stratification in Phase II trials is compressing development cycles, forcing IVD manufacturers to synchronize kit validation with drug approval timelines.
Diagnostic laboratories consume the highest kit volumes; pharma company demand is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioreactor capacity for monoclonal antibodies concentrates among contract manufacturers in the United States, Switzerland, and Germany, exposing kit producers to allocation risk during demand surges. Diagnostic consumable demand clusters in jurisdictions with consolidated hospital procurement and evolving regulatory frameworks for laboratory-developed tests.
United States
Hospital procurement consortia are consolidating purchasing authority for high-volume immunoassay panels, displacing decentralized laboratory buying. The FDA's evolving framework for laboratory-developed tests is reshaping product registration pathways and threatening to disrupt clinical laboratory economics. The Boston-Cambridge corridor anchors precision oncology companion diagnostic development, with pharmaceutical sponsors requiring biomarker stratification in Phase II trials.
Germany
University hospital networks are compressing price negotiation cycles through centralized group purchasing organizations for multi-year consumable contracts. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking, elevating barriers for marginal competitors. The Munich-Stuttgart axis concentrates workflow automation engineering for integrated sample prep to result reporting systems.
China
Domestic manufacturers are scaling molecular diagnostics production for infectious disease surveillance, redirecting regional supply chains and compressing import dependency. The NMPA has accelerated review timelines for innovative diagnostics under priority review channels, redirecting multinational submission strategies toward Shanghai and Beijing registration offices. The Yangtze River Delta manufacturing clusters are expanding PCR and NGS capacity ahead of European CE marking timelines.
Japan
Academic medical centers are adopting hybrid digital PCR and next-generation sequencing platforms for minimal residual disease monitoring, consolidating biomarker detection onto unified instrumentation. METI standards coordination shapes quality management system expectations for automated analyzer integration. The Kanto region around Tokyo concentrates reference laboratory networks processing oncology profiling for community hospital outreach.
India
Production-linked incentives for domestic medical device manufacturing are attracting component suppliers and contract kit assemblers to establish regional supply nodes. CDSCO regulatory harmonization with IMDRF guidelines is streamlining import substitution pathways for molecular diagnostic reagents. The Maharashtra-Gujarat industrial corridor is emerging as a contract manufacturing hub for lateral flow and cartridge-based point-of-care systems.
In Vitro Diagnostics Test Kit Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The vendor base stratifies between diversified conglomerates with full workflow portfolios and focused players in detection chemistry or sample preparation niches. Three archetypes dominate: integrated diagnostic platform providers, molecular assay specialists, and point-of-care miniaturization engineers. Competitive moves concentrate on strategic partnerships for algorithm integration and geographic expansion through prioritized regulatory submissions.
Among Swiss and German diversified conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthineers AG exemplify platform integrators bundling test kits with installed analytical instruments and imaging systems. Danaher occupies a position representing workflow automation leadership through integrated sample preparation to result reporting architectures. These three anchors illustrate how technology leadership concentrates in players spanning reagent chemistry, instrumentation, and software interpretation layers rather than standalone consumable supply.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Danaher |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| bioMérieux SA |
| Becton, Dickinson and Company |
| QIAGEN N.V. |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing clusters anchor molecular diagnostics capacity expansion, and their scale economics translate into downstream pricing power for domestic Chinese producers competing against imported reagent kits. This geographic concentration of PCR and NGS manufacturing feeds into tiered pricing structures across immunoassay, molecular, and point-of-care product categories.
Pricing Analysis
The EU Medical Device Regulation dictates the pricing tier structure by elevating compliance costs for CE marking, separating premium-certified kit suppliers from standard-tier competitors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and NMPA priority review channel access. Pricing pressure stems from hospital procurement consortia consolidating purchasing authority for high-volume immunoassay panels in Germany and France. Clinical laboratories in university hospital networks exhibit highest price sensitivity due to multi-year consumable contract negotiations, while pharma-sponsored companion diagnostics show lowest sensitivity given biomarker stratification requirements in oncology trials.
Supply Chain Analysis
Contract manufacturing capacity for monoclonal antibodies concentrates among three bioreactor operators in the United States, Switzerland, and Germany. Raw material dependencies center on high-affinity antibody production, nucleic acid primer synthesis, and chromogenic substrate supply. Single-source vulnerability in bioreactor allocation exposes kit producers to demand surge disruptions during infectious disease outbreaks. Distribution runs through hospital group purchasing organizations and diagnostic laboratory networks rather than direct-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics dominate value capture in this market, with consumable reagent contracts and algorithm licensing expanding faster than capital instrument sales. Recurring revenue from multi-year consumable agreements now exceeds one-time analyzer placement value in mature installed bases.
For Market Incumbents: Pre-empt NMPA priority review channel capture by accelerating Shanghai and Beijing registration submissions ahead of European CE marking timelines. Consolidate bioreactor capacity through captive supply agreements with antibody contract manufacturers to mitigate allocation risk during demand surges. Defend against domestic Chinese molecular diagnostics producers by bundling interpretive algorithms with consumable contracts.
For New Entrants and Emerging Players: Pursue home-based infectious disease surveillance white space in the United States and United Kingdom, where post-pandemic self-testing familiarity enables multiplex respiratory panel adoption beyond COVID-19. Target India's PLI scheme for medical device manufacturing to establish regional supply nodes for lateral flow and cartridge-based point-of-care systems. Anchor go-to-market strategy through retail health channel partnerships rather than hospital procurement consortia.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors workflow automation specialists with integrated sample-to-result architectures over standalone reagent suppliers. Long-term viability rests on software-enabled algorithm bundling and AI-integrated diagnostic platforms as regulatory frameworks mature. Acquisition target archetype: point-of-care miniaturization engineers with cartridge-based systems and pending NMPA submissions. Signal to watch: FDA laboratory-developed test framework reclassification as medical devices, which would disrupt clinical laboratory economics and accelerate kit substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Priority Review Submission | Accelerates domestic China approval timelines ahead of European CE marking access. |
| Companion Diagnostic Partnership | Synchronizes kit validation with pharma oncology drug approval timelines. |
| Algorithm Licensing Program | Captures recurring revenue from software-as-medical-device interpretive layers. |
| Bioreactor Capacity Agreement | Secures monoclonal antibody allocation against demand surge disruption. |
| Hospital GPO Contract Consolidation | Locks multi-year consumable volumes through Germany and France procurement networks. |
Research Methodology
The analysis maps immunoassay, molecular diagnostics, microbiology, and hematology sub-sectors, each validated through laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Primary interview data triangulates against FDA 510(k) filings, NMPA registration databases, EU MDR notified body records, and hospital procurement contract disclosures. Secondary validation draws from CMS Medicare reimbursement data, clinical laboratory accreditation records, and pharmaceutical companion diagnostic partnership announcements. Bottom-up reagent volume estimates and top-down market sizing converge through iterative reconciliation.
Assumptions held fixed include regulatory framework stability across FDA, NMPA, and EU MDR jurisdictions, while pricing elasticity and technology substitution rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, application setting, detection technology, and end-user category alongside regional regulatory cluster differentiation. CAGRs derive from installed base expansion, test menu extension, and per-test economics evolution. Forecast inputs incorporate bioreactor capacity expansion timelines and NMPA review channel throughput rates.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates, hospital capital expenditure cycles, or biopharma R&D funding would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and infectious disease surveillance investment continuity. Quarterly review of NMPA submission approval velocities, FDA LDT framework guidance releases, and hospital GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
IVD Antibody Market
Diagnostics
Antibody Testing Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market