
 Antimicrobial Susceptibility Testing Market | 2026-2036
Antimicrobial Susceptibility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Susceptibility Testing Market Intelligence
A capital-intensity divergence between automated platform developers and manual test kit suppliers is reorganizing competitive tiers in antimicrobial susceptibility testing. Danaher Corporation leverages its diagnostics conglomerate structure to sustain integrated instrument-consumable ecosystems. Bruker anchors its position through mass spectrometry-based pathogen identification linked to susceptibility workflows. bioMérieux differentiates via biofilm detection capabilities and rapid phenotypic readouts.
Antimicrobial susceptibility testing encompasses laboratory methods that determine bacterial, fungal, or viral response to antimicrobial agents, typically measuring minimum inhibitory concentrations through broth microdilution, disk diffusion, or automated optical detection systems with turnaround times ranging from hours to days. Its primary purpose is guiding clinician selection of effective therapeutics and tracking resistance patterns for infection control programs. Automated systems capture the largest installed base among product types, while molecular methods represent the fastest-expanding technology segment as PCR and MALDI-TOF protocols shorten detection windows. Hospitals remain the dominant end-user channel, though diagnostic centers are gaining volume as point-of-care decentralization advances.
FDA antimicrobial device guidance and CLSI breakpoint standards shape product validation requirements and market access timelines in the United States, while EUCAST guidelines and the EU IVD Regulation establish conformity benchmarks across European markets. The FDA's streamlined pathway for novel AST platforms is reshaping how developers prioritize resistance gene panels over traditional phenotypic workflows. Stakeholders must weigh instrument placement strategies against the trajectory of laboratory consolidation and reimbursement shifts for rapid molecular testing.
Market Dynamics
Consolidation among hospital networks and diagnostic laboratories is compressing procurement cycles for antimicrobial susceptibility testing platforms, favoring vendors with integrated instrument-consumable ecosystems over standalone kit suppliers.
Growth Catalysts
- CLSI breakpoint updates:Revised susceptibility interpretive standards in the United States mandate platform upgrades, forcing clinical laboratories toward automated systems with real-time breakpoint integration.
- German hospital network consolidation:Rhineland and Bavarian health systems are centralizing microbiology services, creating volume concentration that rewards scalable AST platform vendors.
- PCR-based resistance gene detection:Molecular amplification protocols for mecA, vanA, and carbapenemase genes are shortening time-to-result from days to hours in bloodstream infection workflows.
Market Restraints
- Reagent supply concentration:Critical broth microdilution panels and antimicrobial disks depend on single-source suppliers in Southern Germany, exposing buyers to allocation risk during demand surges.
- EU IVD Regulation transition costs:Conformity assessment requirements for Class C devices are extending validation timelines and requiring substantial documentation investment from kit manufacturers.
- Manual method persistence:Disk diffusion and agar dilution techniques retain preference in resource-constrained settings, limiting penetration of higher-margin automated platforms in lower-tier laboratories.
Strategic Opportunities
- Indian diagnostic center expansion:Tier-2 and Tier-3 cities under CDSCO jurisdiction are building centralized microbiology hubs, creating first-mover positioning for rapid phenotypic systems.
- Point-of-care decentralization:Physician office laboratories and urgent care chains are adopting cartridge-based AST devices, bypassing traditional hospital laboratory channels entirely.
- Japan PMDA streamlined pathway:Novel rapid susceptibility platforms with demonstrated clinical utility receive priority review, compressing time-to-market for MALDI-TOF linked resistance detection systems.
Industry Challenges
- Clinical microbiologist shortage:Specialized training requirements for resistance mechanism interpretation are creating hiring bottlenecks in US hospital laboratories, constraining platform utilization rates.
- Legacy LIS integration complexity:Automated AST platforms must interface with disparate laboratory information systems across multi-site health networks, extending implementation timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Susceptibility Testing Market |
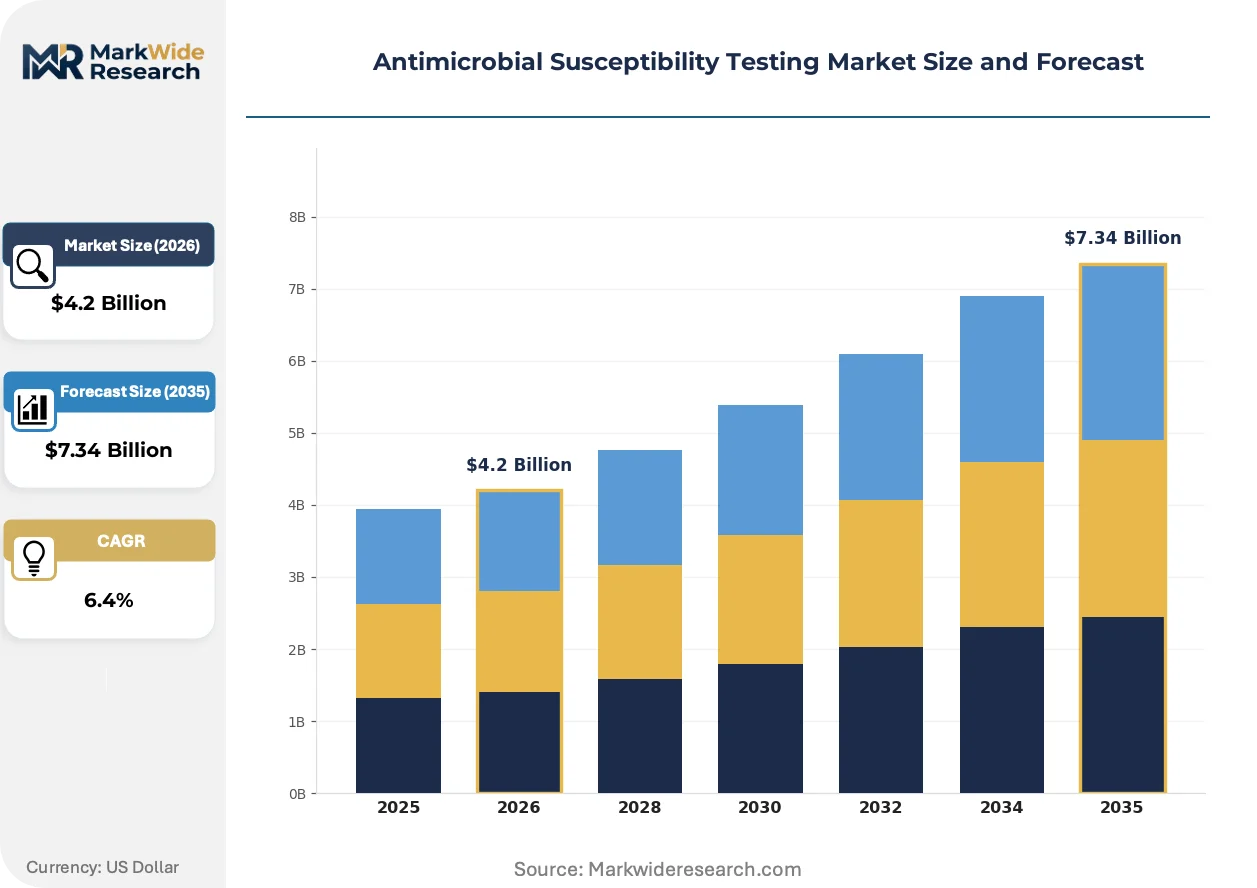
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $7.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Reagents, Consumables Technology: Phenotypic Testing, Molecular Methods, Bakery Media, Microdilution End User: Hospitals, Clinical Laboratories, Research Institutions, Diagnostic Centers Application: Infectious Disease Testing, Environmental Testing, Food Safety Testing, Research Studies |
| Companies Covered | Danaher Corporation, Bruker, bioMérieux, HiMedia Laboratories, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, Bio-Rad Laboratories, Accelerate Diagnostics, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Susceptibility Testing Market Strategic Shifts & Innovations
Next-generation susceptibility testing is compressing detection windows while fragmenting the vendor landscape between molecular specialists and integrated platform conglomerates.
Digital imaging algorithms coupled with machine learning classification are displacing manual plate reading in broth microdilution workflows. Large US reference laboratories are deploying these systems at scale, reducing technician oversight hours and enabling 24-hour continuous operation. The shift is displacing conventional photometric endpoint detection and compressing staffing models in high-volume microbiology operations.
EMA guidance on antimicrobial susceptibility device validation is tightening evidence requirements for resistance gene claim substantiation. Kit manufacturers must now submit expanded clinical isolate panels across multiple member states, elevating development costs. French and Italian notified bodies are applying these standards most stringently, delaying market entry for novel carbapenemase detection assays.
Diagnostic procurement committees are consolidating vendor relationships into multi-year enterprise agreements spanning instrumentation, consumables, and service. US integrated delivery networks are replacing transactional purchasing with total-cost-of-ownership contracts, bundling AST platforms with blood culture and identification systems. This pattern concentrates most visibly in Texas and Florida health systems, where laboratory standardization across acquired hospitals is a stated integration priority.
Antimicrobial Susceptibility Testing Market Segmentation
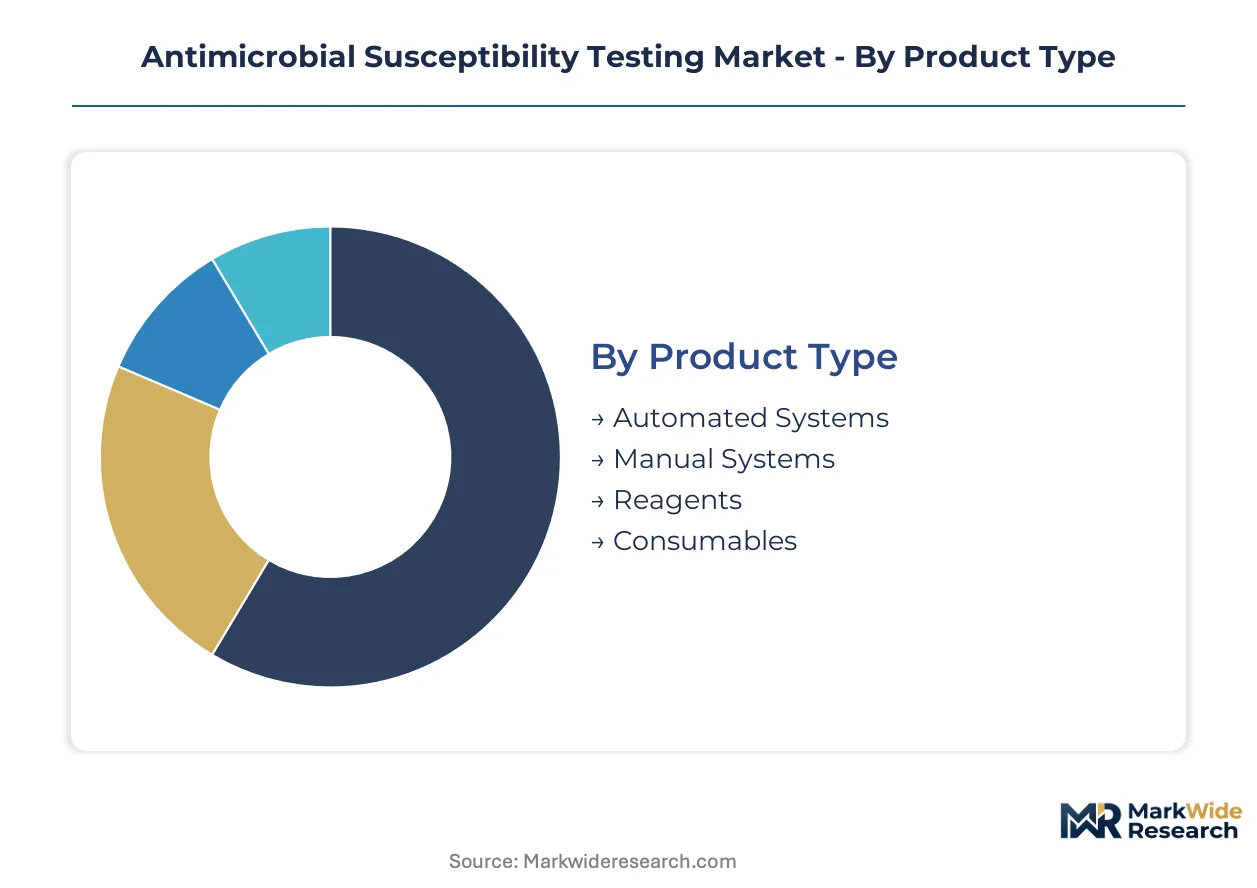
Segmentation in antimicrobial susceptibility testing reveals how regulatory pathways and reimbursement structures fragment procurement decisions across product categories. Laboratories select platforms based on FDA clearance status, CLSI breakpoint compatibility, and total-cost-of-ownership models that vary sharply by setting.
Product Type:
FDA device classification tiers and EU MDR conformity routes create divergent commercial timelines for each product category.
- Automated Systems:Integrated instrument-consumable platforms with optical detection and software-guided interpretation. Hospital networks in Texas and Florida concentrate procurement through multi-year enterprise agreements bundling AST with blood culture systems. Established volume favors Automated Systems; emerging adoption favors Consumables.
- Manual Systems:Disk diffusion and agar dilution setups requiring technician interpretation per CLSI standards. Resource-constrained laboratories in India and Southeast Asia retain these workflows due to lower capital requirements and simpler maintenance protocols.
- Reagents:Broth microdilution panels, antimicrobial disks, and quality control organisms governed by FDA lot release requirements.
- Consumables:Cartridges, cassettes, and single-use disposables for molecular platforms subject to EU IVD Regulation Class C documentation.
Capital intensity separates instrument vendors from consumable suppliers; recurring revenue models favor the latter.
Technology:
Time-to-result requirements and resistance mechanism complexity determine technology selection in bloodstream infection versus surveillance workflows.
- Phenotypic Testing:Broth microdilution and disk diffusion measuring visible microbial growth inhibition against standardized antimicrobial concentrations. German hospital networks centralizing microbiology services in Rhineland and Bavaria deploy these for definitive susceptibility determination. Established volume favors Phenotypic Testing; steepest expansion trajectory favors Molecular Methods.
- Molecular Methods:PCR amplification and MALDI-TOF mass spectrometry detecting resistance genes including mecA, vanA, and carbapenemase variants. US clinical laboratories adopt these for bloodstream infection protocols requiring sub-24-hour turnaround.
- Bakery Media:Specialized culture formulations supporting fastidious organism growth and standardized susceptibility readouts.
- Microdilution:Miniaturized broth-based panels enabling parallel antimicrobial testing with reduced reagent volumes.
Reimbursement compression in US hospital outpatient settings favors faster molecular protocols over growth-dependent methods.
End User:
Procurement authority concentration and laboratory consolidation patterns reshape vendor access across customer types.
- Hospitals:Acute care facilities with centralized microbiology laboratories managing bloodstream infection, respiratory, and surgical site surveillance. Integrated delivery networks in the United States compress vendor lists through standardization mandates. Established volume favors Hospitals; emerging adoption favors Diagnostic Centers.
- Clinical Laboratories:Independent and hospital-affiliated reference labs processing outsourced susceptibility testing for smaller facilities.
- Research Institutions:Academic medical centers and public health laboratories tracking resistance epidemiology and novel mechanism discovery.
- Diagnostic Centers:Decentralized facilities in Indian Tier-2 and Tier-3 cities building centralized microbiology hubs under CDSCO oversight, plus urgent care chains in the United States adopting cartridge-based point-of-care devices.
Channel fragmentation between consolidated hospital systems and distributed diagnostic networks requires dual go-to-market structures.
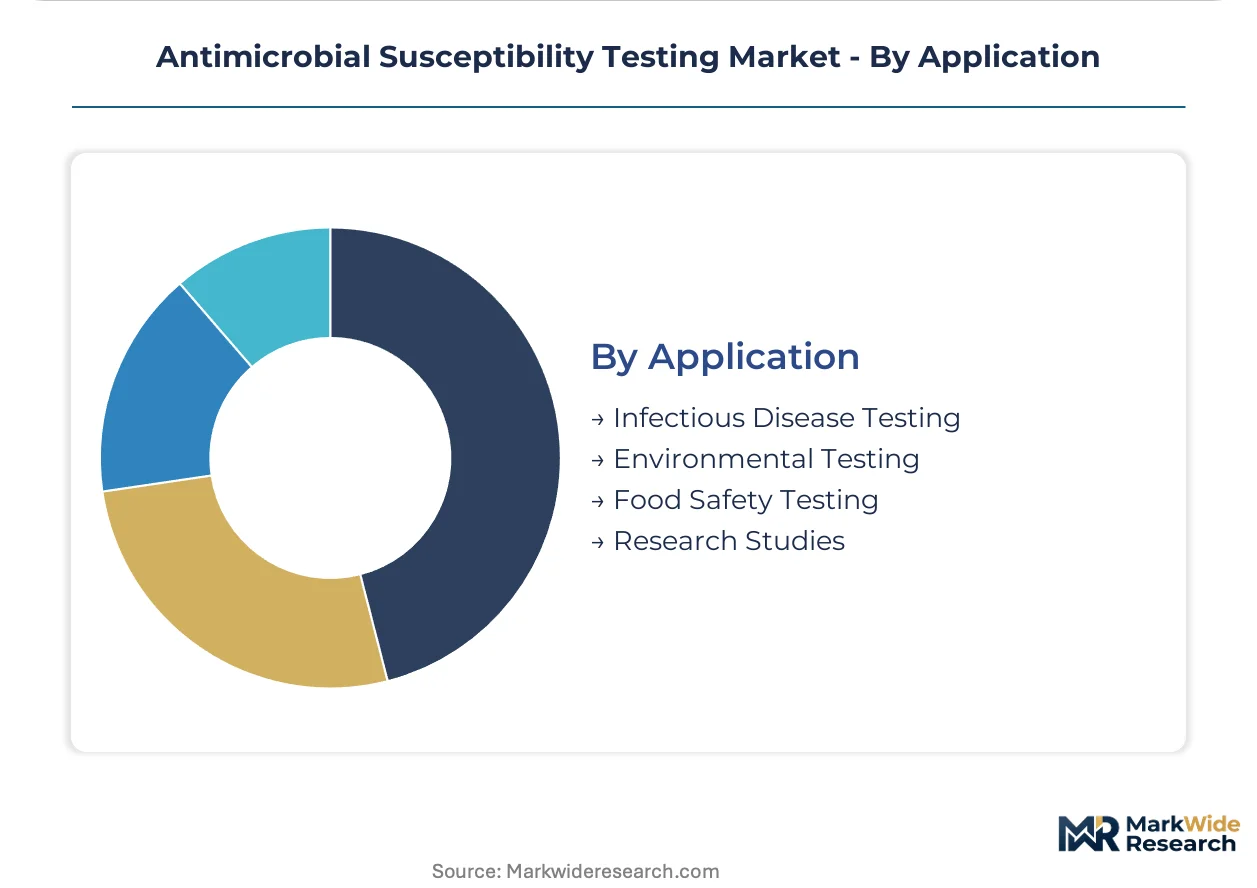
Application:
Regulatory jurisdiction and evidence requirements separate clinical diagnostic applications from industrial and environmental monitoring uses.
- Infectious Disease Testing:Patient-directed susceptibility determination guiding antimicrobial therapy selection in bloodstream, respiratory, urinary, and soft tissue infections. FDA breakthrough device designation and Japan PMDA priority review pathways accelerate platform entry for rapid resistance detection in sepsis workflows. Established volume favors Infectious Disease Testing; emerging adoption favors Environmental Testing.
- Environmental Testing:Surveillance of antimicrobial resistance in wastewater, agricultural runoff, and healthcare facility environments. European environmental agencies and the EPA expand monitoring mandates for carbapenemase dissemination in water systems.
- Food Safety Testing:Veterinary and agricultural antimicrobial residue and resistance monitoring under FDA and EFSA jurisdiction.
- Research Studies:Epidemiological surveillance, resistance mechanism characterization, and novel therapeutic validation in academic and government laboratories.
Clinical reimbursement stability contrasts with grant-dependent funding cycles in environmental and research applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature markets prioritizing rapid molecular turnaround and emerging economies retaining manual phenotypic workflows due to capital constraints and infrastructure limitations.
United States
Hospital network consolidation in Texas and Florida drives enterprise procurement of integrated AST platforms bundling blood culture and identification systems. FDA streamlined pathways for novel antimicrobial devices accelerate molecular method approvals, compressing validation timelines for resistance gene panels. Clinical laboratories in Boston and the San Francisco Bay Area deploy machine learning-enhanced digital imaging for continuous 24-hour operation.
Germany
Rhineland and Bavarian health systems centralize microbiology services, creating procurement volume concentration that rewards scalable platform vendors. EUCAST guidelines establish conformity benchmarks for susceptibility interpretive standards, while MDR Class C requirements extend validation timelines for kit manufacturers. Stuttgart and Munich clusters host critical reagent suppliers for broth microdilution panels, exposing buyers to allocation risk during demand surges.
India
Tier-2 and Tier-3 cities under CDSCO jurisdiction build centralized microbiology hubs, creating first-mover positioning for rapid phenotypic systems. Manual disk diffusion persists in resource-constrained settings, limiting automated platform penetration. Hyderabad and Bangalore diagnostic networks expand reference laboratory capacity to serve decentralized hospital chains.
Japan
PMDA priority review pathways compress time-to-market for MALDI-TOF linked resistance detection systems with demonstrated sepsis workflow utility. Tokyo and Osaka academic medical centers anchor epidemiological surveillance for novel resistance mechanisms. METI funding programs support domestic platform development for carbapenemase detection assays.
United Kingdom
London and Southeast integrated care systems standardize AST procurement across acquired hospital trusts, mirroring US enterprise contracting patterns. MHRA alignment with EUCAST breakpoints mandates platform upgrade cycles in NHS microbiology laboratories. Manchester and Birmingham reference laboratories consolidate outsourced testing for smaller district general hospitals.
Antimicrobial Susceptibility Testing Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in antimicrobial susceptibility testing. Conglomerate diagnostics platforms leverage instrument-consumable ecosystems to capture multi-year hospital network contracts. Mass spectrometry specialists anchor pathogen identification-to-susceptibility workflows. Independent kit manufacturers face margin compression from regulatory documentation burdens and procurement consolidation. Competitive moves concentrate on strategic partnerships linking identification systems to susceptibility platforms, and geographic licensing agreements for resistance gene assay distribution.
Among integrated diagnostics conglomerates, Danaher Corporation exemplifies the instrument-consumable ecosystem archetype through its diagnostics platform structure. Bruker occupies a position representing mass spectrometry-based workflow integration. bioMérieux sits within the phenotypic rapid-readout specialization tier, differentiated by biofilm detection capabilities. These three anchors illustrate how capital intensity divergence between automated platform developers and manual test kit suppliers reorganizes competitive tiers.
| Leading Market Players |
|---|
| Danaher Corporation |
| Bruker |
| bioMérieux |
| HiMedia Laboratories |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| Accelerate Diagnostics |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
EU MDR Class C conformity requirements gate both supplier qualification timelines and price differentiation between validated rapid molecular platforms and legacy phenotypic kits. This dual-gating mechanism compresses margins for manual test manufacturers while sustaining premium positioning for integrated automated ecosystems.
Pricing Analysis
Long-term enterprise contracts spanning instrumentation, consumables, and service dominate hospital network procurement in Texas and Florida health systems. Three-tier pricing structure across premium automated platforms, standard rapid phenotypic systems, and economy manual kits reflects FDA clearance status and CLSI breakpoint integration depth. Cost compression in the manual tier is intensifying because Indian diagnostic centers and Southeast Asian laboratories prioritize capital expenditure minimization over turnaround speed. Academic medical centers and public health surveillance programs exhibit lowest price sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Just-in-time inventory strategies prevail among US clinical laboratories managing automated platform consumables, while strategic stockpiling of critical reagents concentrates in Southern Germany around Stuttgart and Munich supplier clusters. Manufacturing of broth microdilution panels and antimicrobial disks draws from Germany, the United States, and India, with specialized culture media production resting on yeast extract, peptone, and antimicrobial compound inputs. Single-source vulnerability in Southern German reagent suppliers exposes buyers to allocation risk during bloodstream infection outbreak surges. Distribution runs through diagnostic distributors and direct hospital system contracts, with GPO channels consolidating volume in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial susceptibility testing is entering a cyclical recovery phase as hospital laboratory capital expenditure resumes post-consolidation. CLSI breakpoint update cycles and FDA streamlined pathway approvals for novel platforms drive replacement demand.
For Market Incumbents: Consolidate vendor relationships into multi-year enterprise agreements bundling AST platforms with blood culture and identification systems to preempt standalone molecular specialists. Deepen backward integration into critical reagent manufacturing in Germany to mitigate single-source supply risk. Prioritize software companion development for legacy LIS integration to reduce implementation friction in multi-site health networks. For New Entrants and Emerging Players: Point-of-care service-layer gaps in urgent care chains and physician office laboratories offer white-space positioning outside consolidated hospital procurement channels. Target Indian Tier-2 and Tier-3 diagnostic center expansion under CDSCO jurisdiction with rapid phenotypic systems requiring minimal technician training. Pursue licensing agreements for resistance gene assay distribution rather than full platform development to compress time-to-revenue. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cartridge-based molecular platforms as manufacturing scale economies mature. Five-to-ten year viability favors automated platform specialists with installed base expansion potential over manual kit manufacturers facing EU IVD Regulation documentation burdens. Watch FDA breakthrough device designation velocity for rapid sepsis susceptibility platforms as inflection indicator for molecular method reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year enterprise agreements with Texas and Florida integrated delivery networks lock in recurring consumable revenue streams. |
| FDA Submission | Streamlined pathway for novel AST platforms accelerates resistance gene panel approvals ahead of breakpoint update cycles. |
| CE Marking Pathway | MDR Class C conformity assessment under French and Italian notified bodies validates European market access for kit manufacturers. |
| Software Companion Development | Machine learning-enhanced digital imaging integration reduces technician oversight hours in high-volume US reference laboratories. |
| Reimbursement Strategy | Molecular method coding alignment with CMS outpatient prospective payment sustains premium pricing for sub-24-hour turnaround systems. |
Research Approach
Initial hypotheses were tested against primary input from clinical microbiologists, hospital procurement managers, diagnostic platform engineers, and regulatory affairs specialists and refined through secondary validation against FDA 510(k) filings, EMA device guidance documents, CLSI breakpoint update records, and hospital GPO contract databases. Bottom-up sizing of automated system placements and consumable consumption combined with top-down triangulation against diagnostic capital expenditure surveys produced volume and value estimates.
Variance-decomposition across product type, technology modality, end-user channel, and application area informed the analytical framework. Segment-level growth trajectories were derived from installed base expansion rates, replacement cycle timing, and reimbursement policy shifts. Resistance gene detection assay adoption curves and laboratory consolidation patterns served as industry-specific forecast inputs throughout the modeling period.
Underlying assumptions cover regulatory pathway stability, reagent supply continuity, and hospital capital budget recovery, with deviation risk concentrated in EU IVD Regulation transition delays and clinical microbiologist workforce shortages constraining platform utilization. Revision becomes warranted when FDA breakthrough device designation velocity or CMS molecular testing reimbursement thresholds cross material inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Mono Rapid Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Blood Pressure Test Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Pneumococcal Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
In-Vitro Diagnostic Services Market