
 Brain Cancer Diagnostics Market | 2026-2036
Brain Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Cancer Diagnostics Market Outlook
Modular assay bundling is broadening buyer choice in brain cancer diagnostics, allowing hospitals to combine imaging, biomarker, and genetic testing components into configurable panels rather than purchasing discrete tests separately. Illumina Inc. leverages its sequencing infrastructure to anchor molecular profiling workflows for glioma classification. Thermo Fisher Scientific Inc. sustains competitive positioning through integrated sample-to-answer systems spanning tissue processing and bioinformatics. GE Healthcare dominates advanced imaging hardware installations across neuro-oncology departments in North America and Europe.
Brain cancer diagnostics encompasses the detection, classification, and monitoring of primary and metastatic central nervous system malignancies through molecular, histopathological, and radiological methods, with magnetic resonance spectroscopy providing metabolic biomarker quantification at field strengths of 3 Tesla or higher to distinguish tumor recurrence from radiation necrosis. The primary commercial purpose is to enable precise tumor grading, guide surgical and therapeutic intervention selection, and track treatment response over patient care timelines. Imaging techniques command the largest installed base across hospital radiology departments, while genetic tests represent the fastest-expanding margin pool as next-generation sequencing panels replace single-gene assays for IDH mutation and MGMT methylation status determination. Biomarker analysis occupies a maturing but essential position in liquid biopsy development for cerebrospinal fluid circulating tumor DNA monitoring.
The FDA regulates in vitro diagnostic devices and companion assays through premarket notification and approval pathways, while the Clinical Laboratory Improvement Amendments establish quality standards for molecular testing in hospital and reference laboratories. The European Medicines Agency coordinates centralized marketing authorization for companion diagnostics paired with oncology therapeutics, with CE marking required under the In Vitro Diagnostic Regulation for commercial access. Stakeholders must monitor evolving reimbursement policies for multi-omic testing platforms and prepare for integrated diagnostic pathway contracts that bundle imaging, pathology, and molecular analysis under single episode-based payment structures.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing commercialization timelines for novel neuro-oncology assays, while hospital networks accelerate molecular diagnostic adoption through centralized procurement frameworks. This regulatory-commercial convergence is redistributing competitive advantage toward integrated platform providers.
Growth Catalysts
- IDH mutation profiling:Next-generation sequencing panels for glioma classification are displacing single-gene assays in academic medical centers across the United States.
- CE marking under IVDR:The European Union's In Vitro Diagnostic Regulation is harmonizing quality standards for companion diagnostics paired with oncology therapeutics.
- Neuro-oncology center clustering:Specialized treatment hubs in Boston, Houston, and Heidelberg are concentrating demand for advanced magnetic resonance spectroscopy systems.
Market Restraints
- Helium supply volatility:Superconducting magnet cooling requirements expose imaging hardware manufacturers to rare gas price shocks and export quota disruptions.
- Reimbursement fragmentation:Medicare's non-uniform coverage determinations for multi-omic testing create payment uncertainty for hospital laboratories.
- CSF sample instability:Cerebrospinal fluid circulating tumor DNA degrades within hours without cold-chain logistics, limiting liquid biopsy adoption in community settings.
Strategic Opportunities
- Epilepsy monitoring unit crossover:Long-term electroencephalography infrastructure in seizure centers can be repurposed for perioperative brain mapping during tumor resection.
- Japan's Sakigake designation:METI's fast-track approval pathway accelerates market entry for AI-assisted radiology algorithms in glioblastoma detection.
- Artificial intelligence-pathology convergence:Deep learning classification of H&E-stained sections is reducing inter-observer variability in WHO grade determination.
Industry Challenges
- Bioinformatics pipeline standardization:Variant interpretation workflows lack cross-platform interoperability, forcing laboratories to maintain redundant annotation databases.
- Neuro-pathologist workforce constraints:Fellowship-trained specialists concentrate in coastal academic centers, creating diagnostic backlogs in interior regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Cancer Diagnostics Market |
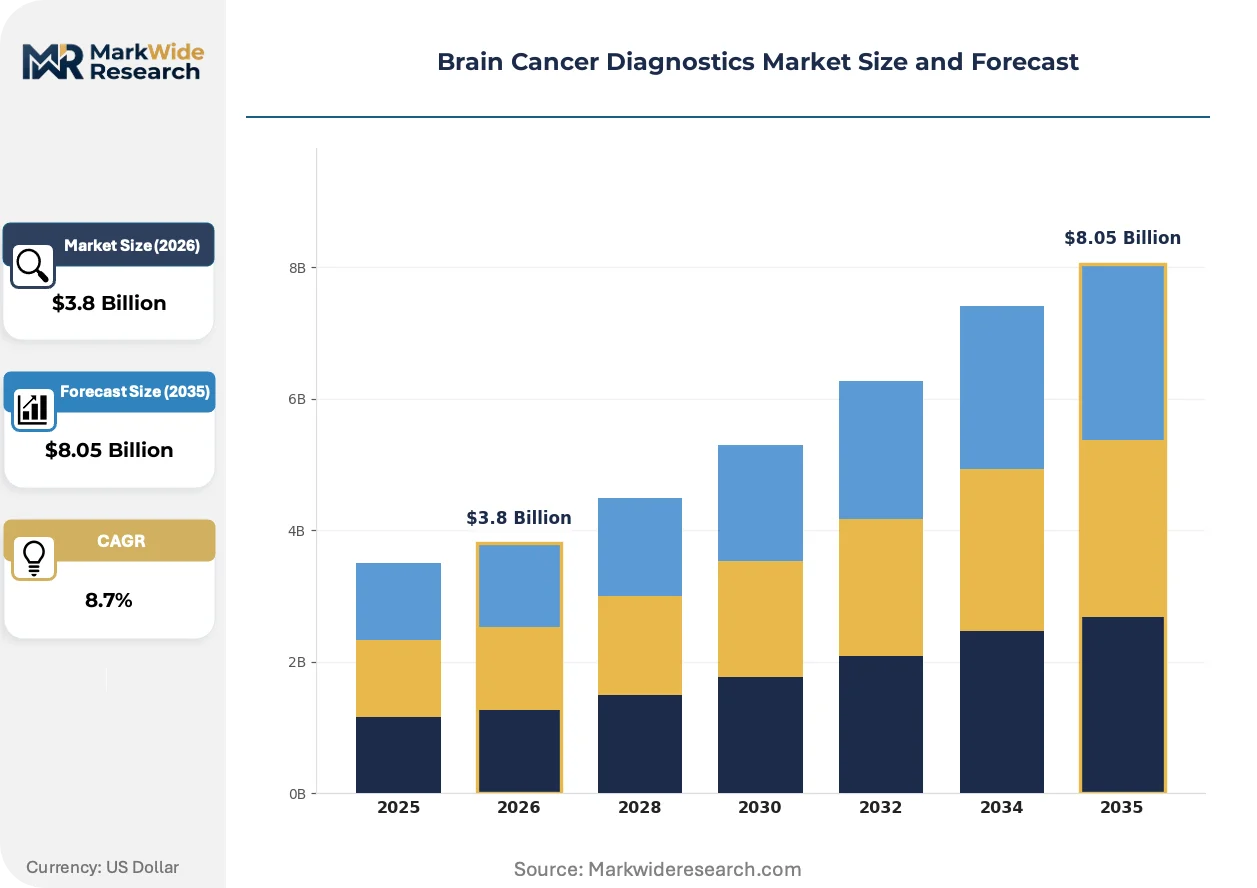
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Techniques, Biomarkers, Genetic Tests, Diagnostic Devices End User: Hospitals, Diagnostic Centers, Research Laboratories, Oncology Clinics Technology: Magnetic Resonance Imaging, Positron Emission Tomography, Computed Tomography, Hematological Analysis Application: Early Detection, Monitoring Progression, Treatment Response, Prognostic Assessment |
| Companies Covered | Illumina Inc., Thermo Fisher Scientific Inc., GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., F. Hoffmann-La Roche Ltd., Agilent Technologies Inc., QIAGEN N.V., Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Cancer Diagnostics Market Strategic Shifts
Multi-omic assay integration is collapsing traditional boundaries between radiology, pathology, and molecular diagnostics, enabling synchronous tumor characterization from tissue, imaging, and liquid biopsy inputs. This convergence is compressing diagnostic timelines from weeks to days.
Magnetic resonance spectroscopy at 3 Tesla field strength is consolidating metabolic biomarker quantification into standard-of-care glioma monitoring protocols. Major academic medical centers in the United States and Germany are retiring standalone perfusion imaging contracts in favor of bundled spectroscopy suites. The technology is consolidating vendor relationships around integrated hardware-software platforms that combine acquisition, post-processing, and reporting into single-workflow installations.
The European Medicines Agency's centralized marketing authorization for companion diagnostics is harmonizing commercial access requirements across member states. Manufacturers now face unified clinical evidence standards rather than fragmented national submissions. Small-to-mid sized assay developers are responding by prioritizing EMA-aligned study designs over legacy FDA-first strategies.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, negotiating standalone maintenance agreements with third-party technical service organizations. This disintermediation is most visible in North American neuro-oncology departments with mature in-house biomedical engineering capabilities. Vendor response has shifted toward subscription-based reagent and consumable lock-in to defend recurring revenue streams.
Brain Cancer Diagnostics Market Segmentation
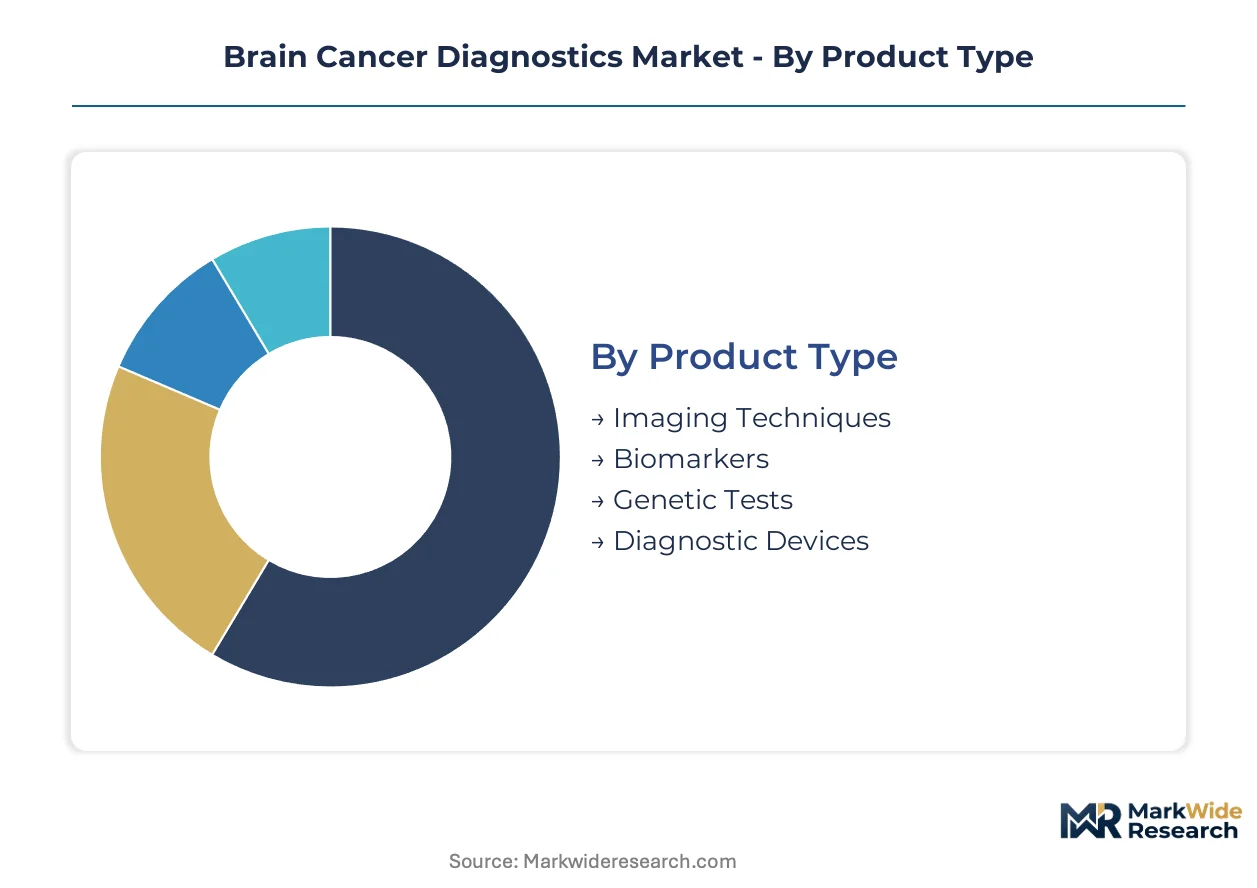
Segmentation in brain cancer diagnostics reveals how procurement decisions split between capital-intensive imaging infrastructure and consumable-driven molecular testing. Hospital networks negotiate bundled contracts across categories while research laboratories drive adoption of emerging biomarker platforms.
Product Type:
Customization versus standardization tension runs deepest here, with imaging systems requiring site-specific installation against genetic tests shipping as standardized kits.
- Imaging Techniques:Magnetic resonance spectroscopy and perfusion-weighted sequences operate at 3 Tesla field strength to distinguish tumor recurrence from radiation necrosis. Demand clusters at academic medical centers in Boston, Houston, and Heidelberg where neuro-oncology departments maintain dedicated MRI suites.
- Biomarkers:Cerebrospinal fluid circulating tumor DNA assays and metabolic metabolite panels enable liquid biopsy monitoring without repeat craniotomy. Growth concentrates in specialized treatment hubs seeking non-invasive longitudinal tracking.
- Genetic Tests:Next-generation sequencing panels for IDH mutation and MGMT methylation status are displacing single-gene assays in molecular pathology workflows.
- Diagnostic Devices:Integrated sample-to-answer systems span tissue processing through bioinformatics reporting for intraoperative consultation.
Leading the category by volume: Imaging Techniques. Growing fastest: Genetic Tests.
End User:
Cost tier stratification separates capital-equipped hospitals from reference laboratories purchasing assay services.
- Hospitals:Integrated delivery networks centralize molecular diagnostic procurement across multiple neuro-oncology sites, negotiating enterprise-wide pricing for multi-omic testing platforms. The FDA's breakthrough device designation pathway accelerates assay validation timelines for hospital laboratories seeking in-house NGS capability.
- Diagnostic Centers:Independent reference laboratories process CSF liquid biopsies and molecular profiling for community oncology practices lacking pathology infrastructure. Cold-chain logistics requirements limit specimen referral radius.
- Research Laboratories:Academic centers drive adoption of experimental biomarker platforms including methylation array classifiers and AI-assisted radiomics.
- Oncology Clinics:Community practices rely on send-out testing for molecular profiling, with reimbursement fragmentation creating payment uncertainty for multi-gene panels.
Commanding highest absolute spend: Hospitals. Expanding most quickly: Research Laboratories.
Technology:
Application focus differentiates anatomical visualization from metabolic and functional assessment modalities.
- Magnetic Resonance Imaging:Advanced sequences including MR spectroscopy and diffusion tensor imaging dominate glioma characterization workflows. The European Medicines Agency's centralized marketing authorization for companion diagnostics harmonizes hardware-software integration requirements across member states.
- Positron Emission Tomography:Amino acid radiotracers distinguish high-grade glioma from treatment-related changes with superior specificity to standard glucose metabolism imaging. German and Dutch centers lead clinical adoption.
- Computed Tomography:Emergency department triage and surgical planning rely on rapid cranial CT for mass effect assessment and hemorrhage exclusion.
- Hematological Analysis:CSF cytology and protein electrophoresis support leptomeningeal metastasis detection in breast and lung cancer surveillance protocols.
Widest installed base: Magnetic Resonance Imaging. Steepest expansion trajectory: Positron Emission Tomography.
Application:
Customer type splits between acute intervention decisions and longitudinal disease management.
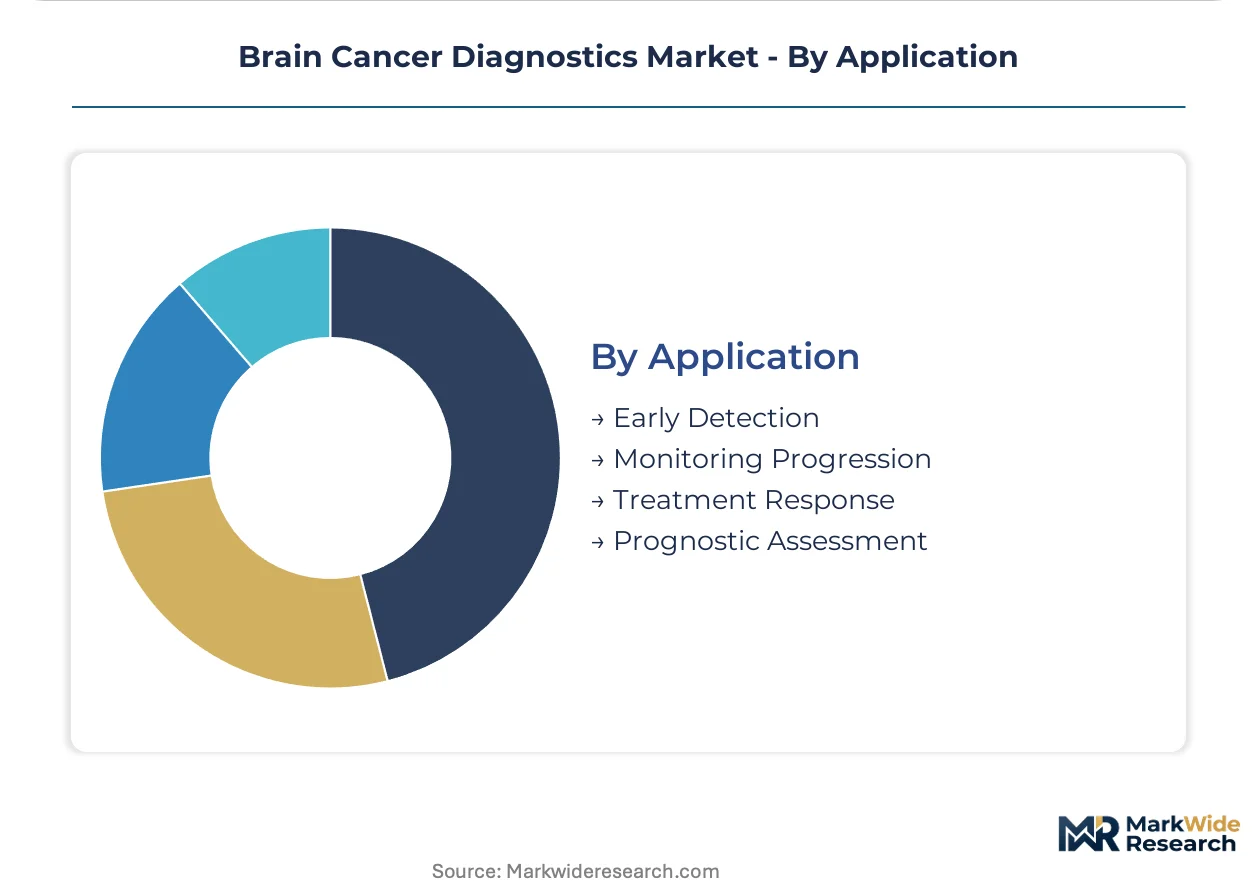
- Early Detection:Screening asymptomatic high-risk populations remains limited by low prevalence, with MRI surveillance protocols concentrated in Li-Fraumeni syndrome and neurofibromatosis specialty clinics.
- Monitoring Progression:Serial imaging and liquid biopsy tracking guide treatment modification timing for recurrent glioblastoma. Japanese neuro-oncology centers leverage METI's Sakigake designation for accelerated AI-assisted radiology algorithm deployment.
- Treatment Response:Pseudoprogression versus true tumor growth differentiation drives demand for advanced MRI sequences and amino acid PET within weeks of chemoradiation completion.
- Prognostic Assessment:Molecular classification including IDH mutation status and 1p/19q codeletion stratifies survival expectations and guides clinical trial enrollment.
Highest procedure volume: Monitoring Progression. Gaining share fastest: Treatment Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuro-oncology research parks in Boston, Houston, and Heidelberg concentrate specialized diagnostic infrastructure through targeted tax incentives and federal research grants. These clusters anchor regional procurement patterns for advanced imaging and molecular profiling platforms.
United States
The FDA's breakthrough device designation pathway accelerates commercialization timelines for novel neuro-oncology assays. Medicare coverage determinations for multi-omic testing create payment frameworks that hospital networks navigate through centralized procurement. Academic medical centers in Boston and Houston maintain dedicated MRI suites with 3 Tesla spectroscopy systems for glioma monitoring.
Germany
The EMA's centralized marketing authorization harmonizes companion diagnostic requirements across member states. Heidelberg anchors European neuro-oncology concentration with integrated research hospitals and molecular pathology laboratories. German centers lead clinical adoption of amino acid PET radiotracers for distinguishing tumor recurrence from treatment effects.
Japan
METI's Sakigake designation fast-tracks approval for AI-assisted radiology algorithms in glioblastoma detection. PMDA oversight ensures alignment with international clinical evidence standards for companion diagnostics. Tokyo and Osaka academic hospitals drive adoption of experimental biomarker platforms including methylation array classifiers.
United Kingdom
NICE technology appraisals establish reimbursement thresholds for molecular testing panels in NHS trusts. The MHRA's post-Brexit regulatory framework maintains convergence with EMA standards for in vitro diagnostics. London and Cambridge neuro-oncology centers concentrate demand for integrated sample-to-answer systems.
China
NMPA marketing authorization for innovative medical devices accelerates domestic assay development timelines. National reimbursement catalog updates determine hospital laboratory purchasing priorities for genetic testing. Beijing and Shanghai tertiary hospitals lead adoption of next-generation sequencing panels for IDH mutation profiling.
Brain Cancer Diagnostics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, reagent, and bioinformatics segments. The vendor base stratifies into three tiers: integrated platform providers commanding enterprise contracts, modular assay developers serving reference laboratories, and imaging hardware specialists defending installed base relationships. Consolidation pressure favors scale players with cross-category bundling capability. Strategic partnerships between sequencing infrastructure and AI software firms reshape competitive positioning.
Among diversified life sciences conglomerates, Thermo Fisher Scientific Inc. and F. Hoffmann-La Roche Ltd. exemplify integrated platform providers spanning sample processing through clinical reporting. Illumina Inc. represents sequencing infrastructure specialists anchoring molecular profiling workflows. GE Healthcare occupies a position within imaging hardware installations across North American and European neuro-oncology departments. These three archetypes reflect the market's structural segmentation between capital equipment, consumable reagents, and analytical software.
| Leading Market Players |
|---|
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies Inc. |
| QIAGEN N.V. |
| Canon Medical Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up diagnostic imaging specialists anchor supply consolidation in North America and Europe, translating installed base density into pricing discipline through multi-year service contracts and reagent lock-in provisions.
Pricing Analysis
Short lead-time premiums apply to magnetic resonance spectroscopy systems and next-generation sequencing consumables, with academic medical centers paying expedited delivery surcharges for intraoperative consultation workflows. Three-tier pricing structure across premium, standard, and economy levels segments buyers by service bundling intensity and bioinformatics support depth. Price differentiation hinges on FDA breakthrough device designation status and ISO 13485 certification tier. Cost compression in economy-tier genetic test panels is intensifying because reference laboratories negotiate volume-based reagent discounts. Community oncology clinics exhibit highest price sensitivity due to Medicare reimbursement fragmentation, while integrated hospital networks demonstrate lowest sensitivity through enterprise procurement leverage.
Supply Chain Analysis
CE marking under IVDR and FDA premarket notification pathways gate commercial access for in vitro diagnostic manufacturers, creating qualification backlogs that constrain vendor eligibility. Manufacturing concentrates in the United States, Germany, and China, with superconducting magnet fabrication anchored in Massachusetts and Bavaria. Helium supply for MRI cooling draws from Qatar and Algeria, exposing hardware producers to export quota volatility. Single-source vulnerability persists in next-generation sequencing reagent chemistries. Distribution runs through hospital procurement departments and group purchasing organizations, with third-party technical service organizations disintermediating legacy vendor maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around fellowship-trained neuro-pathologists and qualified helium logistics providers prop pricing power for integrated platform vendors across the analysis window.
For Market Incumbents: Lock in neuro-oncology department relationships through subscription-based reagent and consumable contracts that defend recurring revenue against third-party technical service disintermediation. Expand backward integration into bioinformatics pipeline development to reduce redundant annotation database maintenance costs. Prioritize FDA breakthrough device designation pursuit for novel neuro-oncology assays to compress commercialization timelines ahead of emerging modular assay developers.
For New Entrants and Emerging Players: AI-assisted radiology algorithms for glioblastoma detection offer a technology-first wedge into Japanese academic hospitals leveraging METI's Sakigake fast-track pathway. Target community oncology clinics in interior United States regions where neuro-pathologist workforce constraints create diagnostic backlogs and send-out testing dependency. Pursue reference laboratory partnerships as the primary go-to-market angle, bypassing capital-intensive hospital capital equipment procurement cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular assay developers with EMA-aligned study designs in Germany and the Netherlands, where centralized marketing authorization harmonization reduces regulatory capital requirements. Long-term viability centers on multi-omic integration capability spanning imaging, pathology, and liquid biopsy inputs. Watch for Medicare national coverage determination shifts for multi-gene panels as the inflection indicator for hospital laboratory purchasing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA harmonization reduces fragmented national submission costs for companion diagnostic developers. |
| Hospital System Partnership | Enterprise-wide pricing negotiations with integrated delivery networks lock in multi-omic platform adoption. |
| Software Companion Development | Deep learning classification of H&E-stained sections reduces inter-observer variability in WHO grade determination. |
| Reimbursement Strategy | Medicare coverage determinations for multi-omic testing establish payment certainty for hospital laboratories. |
| FDA Submission | Breakthrough device designation accelerates commercialization timelines for novel neuro-oncology assays. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among neuro-oncologists, hospital procurement managers, molecular pathology laboratory directors, and biomedical engineers at academic medical centers. FDA 510(k) databases, EMA centralized marketing authorization records, CMS Medicare coverage determinations, and hospital GPO contract repositories provided segmentation validation. Bottom-up procedure volume estimates triangulated against top-down expenditure data from national health accounts.
Data-stream reconciliation across imaging system installations, genetic test procedure volumes, and liquid biopsy adoption rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user, technology, application, and regional regulatory cluster. CAGRs derived from weighted average growth contributions across segment-level drivers, with helium supply volatility and neuro-pathologist workforce constraints incorporated as supply-side ceiling functions.
Several conditions sit outside the modeled scope, including novel therapeutic approvals altering companion diagnostic demand and disruptive imaging modalities displacing magnetic resonance spectroscopy. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway continuity. A model refresh is warranted upon material change in Medicare national coverage determinations for multi-omic testing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Serological Testing Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Global Fecal Occult Blood Tests Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Liver Function Tests Market