
 Global Hemoglobin A1c Testing Devices Market | 2026-2036
Global Hemoglobin A1c Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemoglobin A1c Testing Devices Market Foresight
China is tilting toward domestic production of diagnostic reagents and consumables for glycated hemoglobin measurement. Abbott Laboratories leverages its FreeStyle Libre ecosystem to extend glucose management into integrated HbA1c workflows. Siemens Healthineers anchors its position through automated immunoassay platforms that serve high-throughput clinical laboratories. Danaher Corporation competes via Beckman Coulter's ion-exchange chromatography systems that dominate reference lab accuracy benchmarks.
Hemoglobin A1c testing devices quantify the percentage of glycated hemoglobin in blood samples, typically reporting results as HbA1c percentages or estimated average glucose values, with most systems targeting precision within ±0.5 percentage points to meet clinical decision thresholds. These instruments serve the core purpose of monitoring long-term glycemic control in diabetic patients and identifying pre-diabetic populations before symptomatic progression. Point-of-care devices command expanding placement in physician offices and retail clinics where CLIA-waived operation eliminates complex laboratory infrastructure. Laboratory analyzers retain margin concentration through reimbursement premiums tied to NGSP certification and IFCC traceability standards. Immunoassay technology leads volume deployment while boronate affinity methods gain traction in decentralized settings for their minimal sample preparation requirements.
FDA 510(k) pathways and CLIA categorization determine market access timelines for novel HbA1c platforms in the United States. EMA's In Vitro Diagnostic Regulation and IVDR conformity assessment reshape CE marking obligations for manufacturers serving European diagnostic centers and clinical laboratories. Japan's PMDA enforces JIS-compliant accuracy standards that filter entrants into its specialist clinic and hospital laboratory procurement channels. Stakeholders must monitor evolving payer coverage for continuous glucose monitoring alternatives that could displace periodic HbA1c testing frequency in well-controlled patient populations.
Market Dynamics
CLIA-waived point-of-care platforms are compressing traditional laboratory workflows while automated high-throughput analyzers defend reference-grade accuracy premiums, bifurcating the competitive landscape between decentralized convenience and centralized precision.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage for preventive diabetes screening in the United States drives placement of CLIA-waived devices in federally qualified health centers.
- NGSP certification mandates:Laboratory accreditation requirements in Germany and Japan institutionalize demand for IFCC-traceable systems in hospital networks.
- Capillary blood sampling:Microvolume collection methods eliminate phlebotomy infrastructure, accelerating adoption in retail pharmacy clinics and mobile health units.
Market Restraints
- Reagent cost volatility:Boronic acid derivatives and synthetic hemoglobin variants face price instability from specialty chemical suppliers concentrated in Switzerland and Germany.
- FDA 510(k) backlog:Novel platform submissions encounter extended review timelines, delaying commercialization for ion-exchange chromatography innovations.
- Continuous glucose monitor substitution:Real-time glucose data streams from wearable sensors threaten periodic HbA1c testing frequency in well-controlled Type 1 diabetes populations.
Strategic Opportunities
- India's Ayushman Bharat expansion:The national health insurance scheme creates procurement volume for affordable point-of-care devices in tier-2 and tier-3 cities.
- EMA IVDR transition:Conformity assessment bottlenecks reward early-compliant manufacturers with preferential access to European diagnostic center tenders.
- AI-assisted result interpretation:Machine learning algorithms integrated with immunoassay readers is hybridizing diagnostic workflows, enabling predictive glycemic trend analysis beyond static percentage reporting.
Industry Challenges
- NGSP/IFCC harmonization complexity:Dual certification requirements demand parallel validation studies, stretching quality assurance timelines for multi-regional product launches.
- Reference laboratory integration:Point-of-care devices must demonstrate seamless data interoperability with legacy laboratory information systems, complicating hospital procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemoglobin A1c Testing Devices Market |
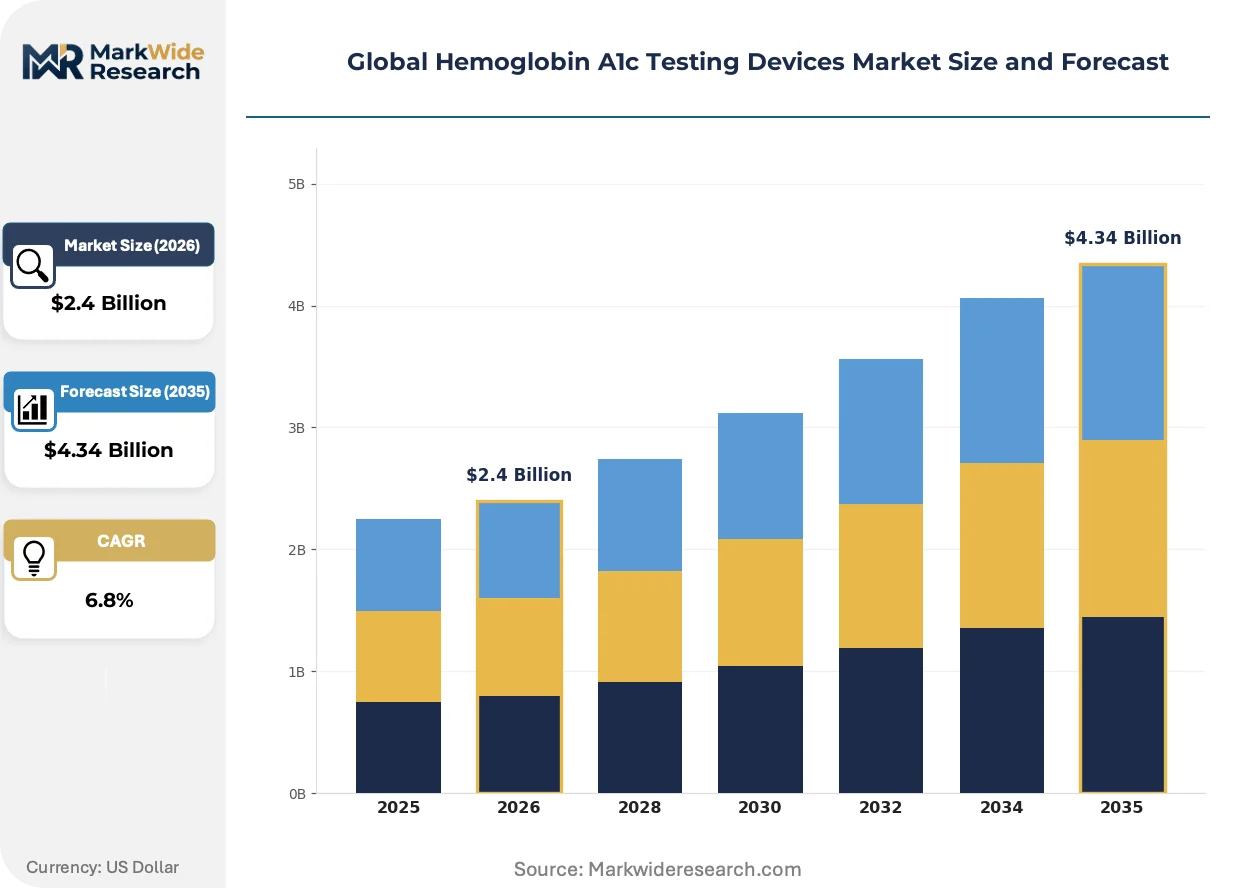
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Care Devices, Laboratory Analyzers, Portable Meters, Automated Systems Technology: Immunoassay, Capillary Electrophoresis, Ion-Exchange Chromatography, Boronate Affinity, Enzymatic Assay End User: Diagnostic Centers, Clinical Laboratories, Specialist Clinics, Research Institutes Application: Diabetes Monitoring, Cardiovascular Risk Assessment, Pre-Diabetes Screening, Gestational Diabetes Management |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, Danaher Corporation, Trinity Biotech, ARKRAY, Inc., A. Menarini Diagnostics s.r.l, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemoglobin A1c Testing Devices Market Shifts & Advancements
Technological convergence between miniaturized biosensors and cloud-connected analytics is redefining how glycemic control data is generated, transmitted, and acted upon across care settings.
Capillary electrophoresis microchips are hybridizing with smartphone-based readout systems, enabling laboratory-comparable precision without benchtop infrastructure. Community health programs in Brazil and Mexico are piloting these platforms for rural diabetes screening. The structural consequence is compressing the cost-per-test floor for decentralized HbA1c measurement while challenging traditional reference lab volume.
Japan's PMDA has tightened JIS T 1201 accuracy tolerances for self-monitoring blood glucose correlates, forcing manufacturers to recalibrate algorithmic conversion between HbA1c percentages and estimated average glucose values. Domestic hospital laboratories are responding by consolidating procurement around systems with demonstrated JIS compliance, filtering out lower-tier competitors.
Subscription-based reagent supply contracts are displacing capital equipment purchases in European hospital networks. Procurement departments in France and the Netherlands now prioritize per-test pricing over upfront analyzer acquisition, compressing vendor margins while locking in multi-year volume commitments. This shift is most visible in academic medical centers managing large diabetic populations through integrated care pathways.
Global Hemoglobin A1c Testing Devices Market Segmentation
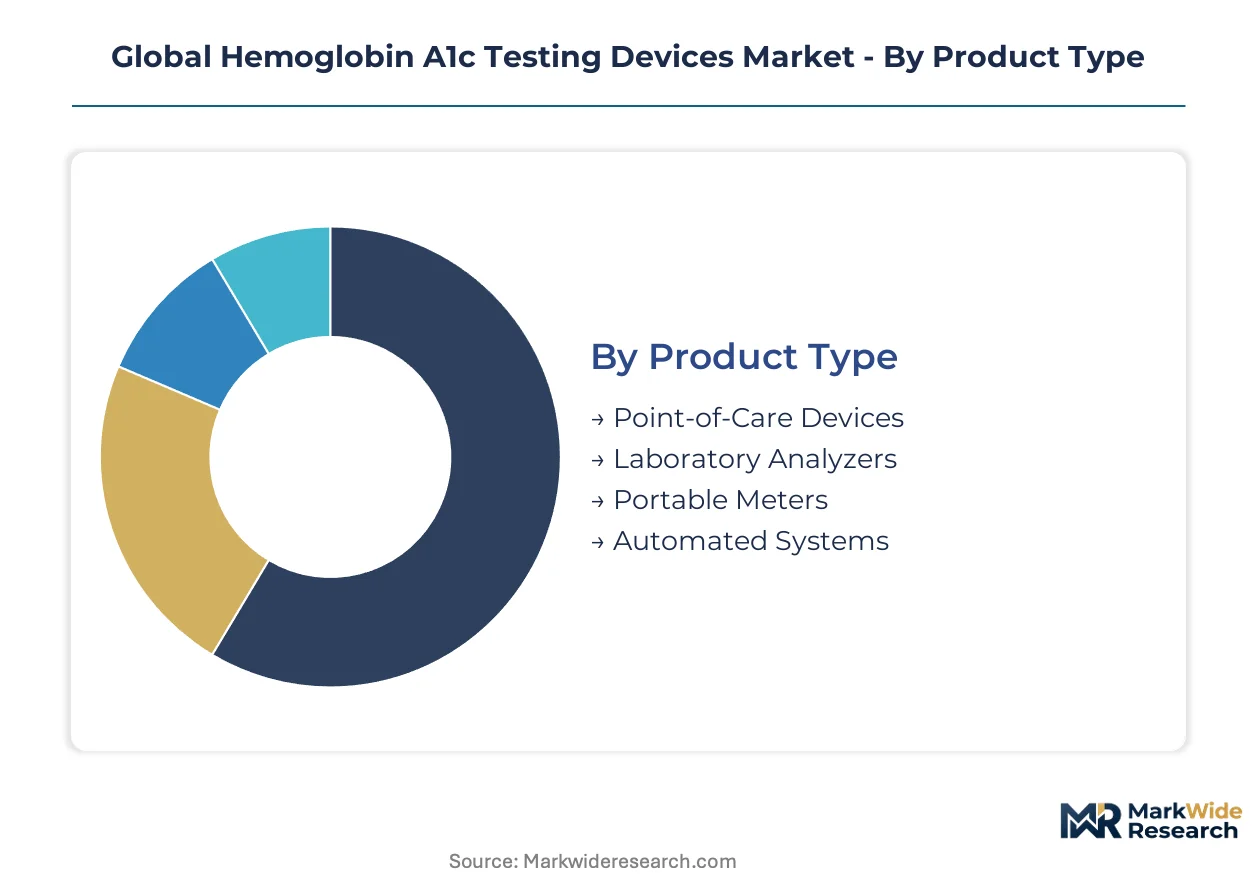
Hemoglobin A1c testing devices fragment across four intersecting dimensions that determine procurement workflows, reimbursement pathways, and competitive positioning. Product form factors and underlying measurement technologies create distinct value propositions for centralized laboratories versus decentralized care settings. End-user concentration and clinical application urgency further stratify vendor targeting strategies.
Product Type:
The use-case spectrum spans from bedside glucose management to high-throughput reference laboratory operations, with form factor decisions directly constraining where testing can occur.
- Laboratory Analyzers:Benchtop systems processing 100+ samples hourly through automated immunoassay or chromatography pipelines. Siemens Healthineers and Beckman Coulter dominate hospital network tenders in Germany and Japan where NGSP certification carries reimbursement weight.
- Point-of-Care Devices:CLIA-waived platforms delivering results within minutes from capillary blood draws. Demand concentrates in United States federally qualified health centers following CMS preventive screening expansion, with placement accelerating in retail pharmacy clinics.
- Portable Meters:Handheld units bridging clinical precision with field deployment flexibility. Community health programs in Brazil and Mexico pilot these for rural diabetes screening where laboratory infrastructure remains absent.
- Automated Systems:Integrated workflow solutions combining sample handling, analysis, and data management. Academic medical centers in France and the Netherlands favor subscription-based per-test contracts over capital purchases.
Established volume favors Laboratory Analyzers; emerging adoption favors Point-of-Care Devices.
Technology:
Measurement methodology determines accuracy benchmarks, regulatory clearance complexity, and operational skill requirements across care settings.
- Immunoassay:Antibody-based detection platforms offering standardized protocols and broad laboratory compatibility. This technology claims the largest installed base in United States hospital networks due to FDA 510(k) familiarity and established reimbursement codes.
- Ion-Exchange Chromatography:Gold-standard separation technique resolving hemoglobin variants with reference-grade precision. Beckman Coulter systems set accuracy benchmarks that filter procurement decisions in Japan's PMDA-regulated hospital laboratories.
- Boronate Affinity:Glycated hemoglobin capture chemistry requiring minimal sample preparation. Decentralized settings in India favor this approach for Ayushman Bharat screening programs where technician training remains limited.
- Capillary Electrophoresis:Microchip-based separation achieving laboratory precision in miniaturized formats. Smartphone-integrated prototypes are expanding most quickly in Latin American community health pilots.
- Enzymatic Assay:Proteolytic cleavage methods offering alternative chemistry for resource-constrained environments. Niche deployment in tier-2 Indian cities where reagent cold chain logistics prove challenging.
Immunoassay retains procurement dominance; Capillary Electrophoresis climbs the fastest on miniaturization advances.
End User:
Site-of-care economics and patient throughput requirements create divergent purchasing criteria across institutional settings.
- Clinical Laboratories:High-volume facilities demanding IFCC-traceable systems with laboratory information system integration. Germany's hospital networks institutionalize NGSP certification requirements that lock in premium analyzer procurement.
- Diagnostic Centers:Specialized facilities balancing test menu breadth with operational efficiency. Independent operators in the United States face margin pressure from CLIA-waived device competition in adjacent physician offices.
- Specialist Clinics:Endocrinology and diabetes-focused practices prioritizing rapid turnaround for patient counseling. Japan's specialist clinic procurement channels filter for JIS T 1201 compliance that eliminates lower-tier competitors.
- Research Institutes:Academic and pharmaceutical research settings requiring method flexibility and data granularity. Method development programs favor systems with open architecture for algorithmic customization.
Clinical Laboratories anchor revenue concentration; Specialist Clinics represent the steepest expansion trajectory on point-of-care migration.
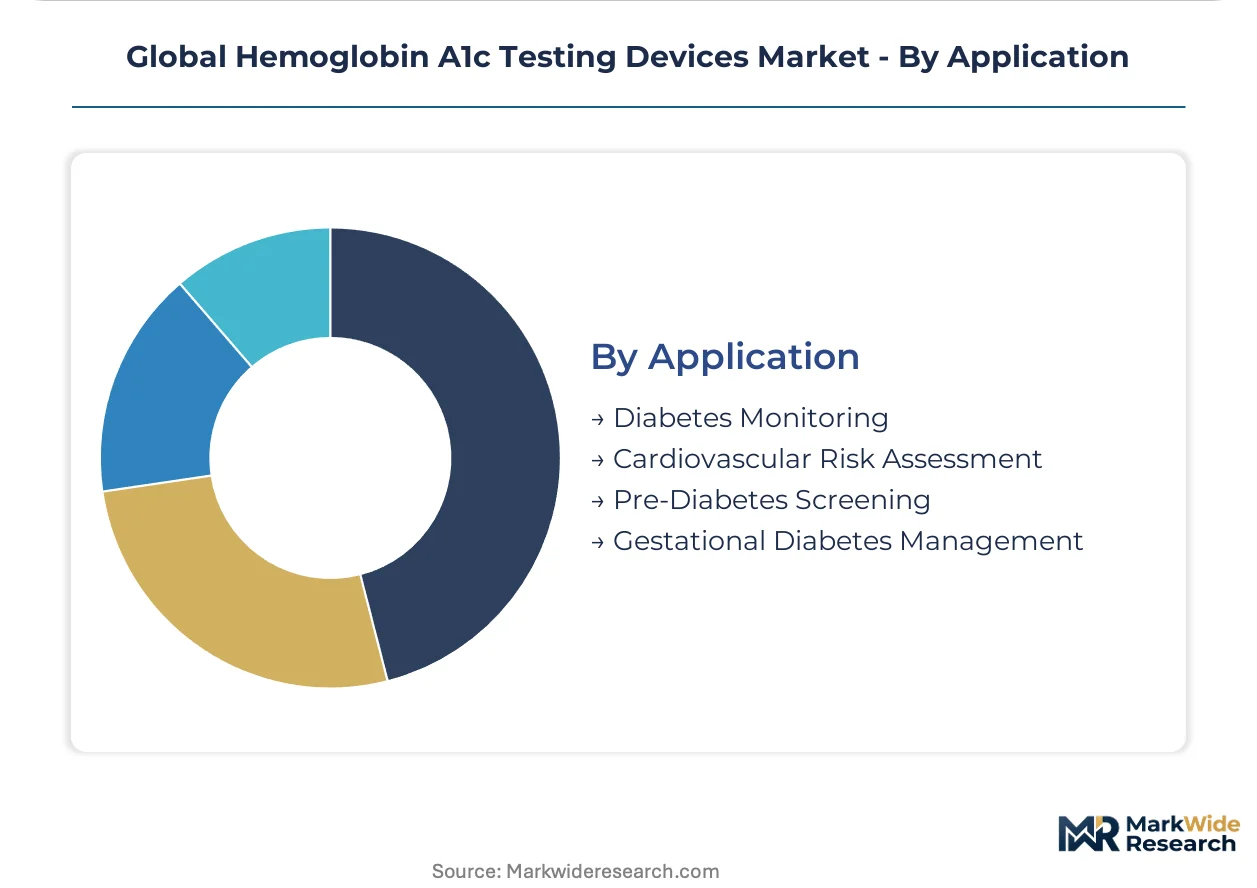
Application:
Clinical indication urgency and screening program mandates reshape demand timing and volume predictability.
- Diabetes Monitoring:Longitudinal glycemic control tracking for diagnosed patient populations. United States Medicare preventive screening expansion sustains baseline demand despite continuous glucose monitor substitution threats in Type 1 populations.
- Pre-Diabetes Screening:Population-level identification of at-risk individuals before symptomatic progression. India's Ayushman Bharat national health insurance scheme generates procurement volume for affordable point-of-care platforms in tier-2 and tier-3 cities.
- Cardiovascular Risk Assessment:HbA1c as proxy marker for macrovascular complication probability. European integrated care pathways in France and the Netherlands bundle this testing within diabetes management protocols.
- Gestational Diabetes Management:Trimester-specific glycemic monitoring for maternal-fetal health. Specialist obstetric clinics in Japan enforce stringent accuracy tolerances that consolidate procurement around PMDA-compliant systems.
Diabetes Monitoring sustains volume leadership; Pre-Diabetes Screening gains share fastest on national screening program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between established screening programs and emerging procurement waves. The United States and Germany favor CLIA-waived point-of-care placement in outpatient settings, while India and Brazil deploy portable units through national health initiatives. Japan maintains the strictest accuracy tolerances, filtering procurement toward reference-grade laboratory systems.
United States
Federally qualified health centers drive point-of-care device placement following CMS preventive screening expansion. FDA 510(k) pathways and CLIA-waived designations determine market access timelines for novel platforms. Hospital outpatient networks in Texas and Florida concentrate procurement volume where diabetes prevalence strains specialist clinic capacity.
Germany
NGSP certification mandates institutionalize demand for IFCC-traceable systems across hospital networks. EMA's In Vitro Diagnostic Regulation reshapes CE marking obligations for manufacturers serving diagnostic centers. Bavaria's academic medical centers favor subscription-based reagent contracts over capital equipment purchases.
Japan
Specialist clinics and hospital laboratories enforce JIS T 1201 accuracy standards that eliminate lower-tier competitors. PMDA compliance filters entrants into procurement channels serving endocrinology practices. Tokyo and Osaka medical districts consolidate purchasing around systems with demonstrated reference lab precision.
India
Ayushman Bharat national health insurance generates procurement volume for affordable point-of-care platforms in tier-2 and tier-3 cities. CDSCO regulatory pathways govern import and domestic manufacturing of diagnostic reagents. Maharashtra and Gujarat diagnostic clusters pilot boronate affinity methods where technician training remains limited.
Brazil
Community health programs deploy portable meters for rural diabetes screening where laboratory infrastructure remains absent. ANVISA registration requirements shape product development priorities for multinational entrants. São Paulo and Minas Gerais state health systems anchor pilot programs integrating smartphone-based readout systems.
Global Hemoglobin A1c Testing Devices Market Competitive Landscape
Capability concentration sits with reference-grade chromatography specialists; scale advantage sits with diversified diagnostic conglomerates. The vendor base stratifies across three tiers: multinational platform holders with integrated glucose management ecosystems, mid-scale immunoassay specialists defending laboratory contracts, and regional point-of-care assemblers capturing procurement in emerging markets. Dominant competitive moves include strategic partnerships for AI-assisted result interpretation and backward integration into boronic acid derivative supply.
Among diversified diagnostic conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions spanning both laboratory and point-of-care vectors. Danaher Corporation exemplifies the reference-grade precision tier through its analytical systems subsidiary. These three entities anchor the competitive structure, representing distinct strategic postures: ecosystem integration, automated platform dominance, and chromatography accuracy leadership respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Trinity Biotech |
| ARKRAY, Inc. |
| A. Menarini Diagnostics s.r.l |
| Tosoh Corporation |
| Others |
Supply & Pricing Matrix
Basel's specialty chemical cluster supplies boronic acid derivatives that anchor reagent pricing power for glycated hemoglobin measurement systems. Swiss and German chemical manufacturers concentrate production of these high-purity inputs, translating upstream capacity constraints into downstream margin pressure for device assemblers competing on per-test economics.
Pricing Analysis
Long-term reagent supply contracts dominate procurement in European hospital networks, displacing capital equipment purchases. Three-tier pricing structure across premium, standard, and economy levels separates NGSP-certified laboratory analyzers from CLIA-waived point-of-care devices and portable field units. Cost compression in the economy tier is intensifying because India's Ayushman Bharat program demands affordable platforms for tier-2 and tier-3 city deployment. Diagnostic centers in the United States show least price sensitivity due to reimbursement premiums tied to IFCC traceability.
Supply Chain Analysis
Boronic acid derivatives and synthetic hemoglobin variants draw from Switzerland, Germany, and Japan as primary feedstock sources. Ion-exchange resins, monoclonal antibodies, and microchip substrates constitute critical component dependencies alongside these specialty chemicals. Single-source vulnerability concentrates in Swiss suppliers of analytical-grade boronic acid, exposing device manufacturers to reagent cost volatility. Distribution runs through regional diagnostic distributors serving hospital networks, with direct procurement emerging in academic medical centers managing integrated care pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
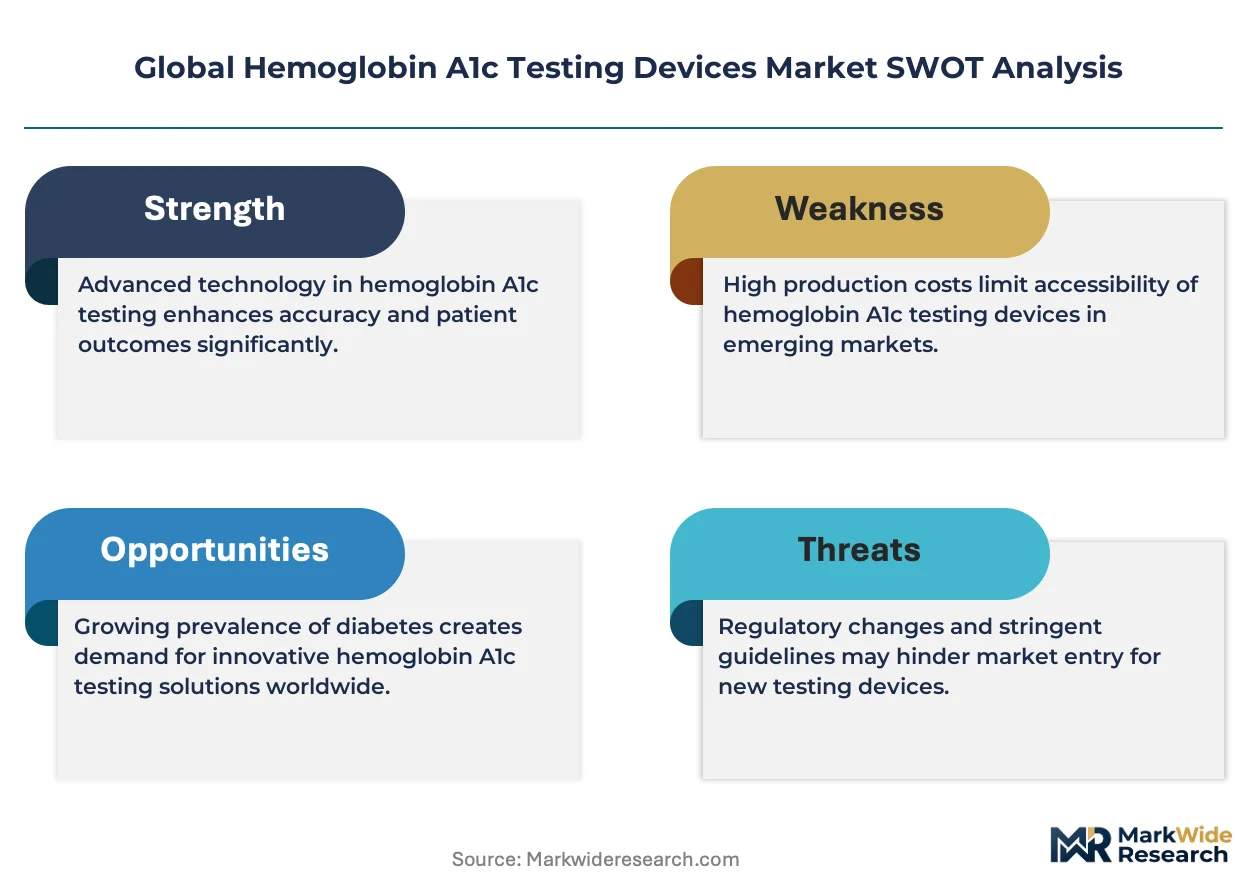
This market's defensive moat rests on regulatory entrenchment: NGSP certification and IFCC traceability standards create switching costs that lock hospital laboratories into validated platform ecosystems.
For Market Incumbents: Entrench position through backward integration into boronic acid derivative supply and AI-assisted result interpretation capabilities. Continuous glucose monitor substitution threatens periodic HbA1c testing frequency in well-controlled Type 1 diabetes populations. Capacity addition in India's Maharashtra and Gujarat diagnostic clusters captures Ayushman Bharat procurement volume before regional assemblers consolidate.
For New Entrants and Emerging Players: Brazil's rural community health programs present underpenetrated demand for smartphone-integrated capillary electrophoresis platforms where laboratory infrastructure remains absent. Tier-2 Indian cities offer secondary white-space for boronate affinity devices requiring minimal technician training. Partner with ANVISA-registered distributors for rapid pilot-to-scale pathways in São Paulo state health systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reference-grade chromatography specialists with demonstrated JIS T 1201 compliance for premium laboratory contracts. Long-term viability hinges on platform interoperability with legacy laboratory information systems and cloud-connected analytics. Monitor FDA 510(k) clearance timelines for ion-exchange chromatography innovations as inflection indicator for competitive access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Platform Development | CMS reimbursement expansion in United States federally qualified health centers accelerates point-of-care placement. |
| NGSP Certification Investment | Germany's hospital networks institutionalize IFCC-traceable system requirements that filter procurement decisions. |
| AI-Assisted Result Interpretation | Machine learning algorithms integrated with immunoassay readers enable predictive glycemic trend analysis beyond static reporting. |
| Subscription-Based Reagent Contracts | French and Dutch academic medical centers prioritize per-test pricing over capital equipment acquisition. |
| JIS T 1201 Compliance Pathway | Japan's PMDA tightens accuracy tolerances that consolidate procurement around reference-grade laboratory systems. |
Research Methodology
A standing panel of hospital laboratory directors, CLIA-waived device operators, GPO contracts managers, and biomedical engineers provided ongoing calibration against secondary validation. Primary interviews with regulatory affairs specialists at FDA, EMA, and PMDA combined with bottom-up and top-down triangulation. Secondary sources encompassed CMS Medicare reimbursement databases, NGSP certification registries, IFCC traceability documentation, and hospital procurement records from Germany, Japan, and the United States.
Scenario-bracketing framed projections across the analysis window with sensitivity testing for continuous glucose monitor substitution rates and national screening program expansion timing. Segmentation dimensions modeled included product form factor, measurement technology, end-user site-of-care, and clinical application urgency. CAGRs derived from installed base growth trajectories, replacement cycle analysis, and test volume elasticity to reimbursement policy shifts.
Practitioners should monitor FDA 510(k) backlog resolution, EMA IVDR transition bottlenecks, and continuous glucose monitor reimbursement expansion for early signals of forecast revision. Cross-checking against NGSP laboratory survey data and IFCC reference method implementation reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Sperm Count Test Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Liver Function Tests Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Global Veterinary POC Diagnostic Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Melioidosis Diagnostic Market