
 Vaccine Ampoules Market | 2026-2036
Vaccine Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Ampoules Market Analytics
The capital-intensity divergence between borosilicate glass specialists and commodity converters is unwinding competitive stability in vaccine ampoules. Gerresheimer AG leverages captive tubing furnaces and vertical integration from glass tube to finished ampoule to sustain margin control across European and North American supply chains. SCHOTT AG anchors premium positioning through FIOLAX borosilicate glass and proprietary forming technology that dominates high-value mRNA vaccine contracts.
Vaccine ampoules are sealed glass or polymer containers engineered to hold sterile liquid or lyophilized vaccine doses, typically manufactured from borosilicate Type I glass meeting USP <660> and EP 3.2.1 chemical durability requirements to prevent alkali leaching and ensure container closure integrity. Their primary purpose is maintaining sterility, dosage precision, and thermal stability from fill-finish through cold-chain distribution to point of administration. Glass material commands the structural core of value pools given its inertness and regulatory acceptance, while plastic and resin alternatives are gaining fastest in pre-filled and emergency-stockpile applications where breakage risk and weight reduction outweigh traditional barrier requirements. Screw cap configurations lead in multi-dose institutional settings, whereas snap cap designs are accelerating in single-dose mass-immunization programs where speed of access and reduced needle-stick risk reshape procurement priorities.
FDA container closure guidance, EMA GMP Annex 1 sterile manufacturing revisions, and USP <1207> package integrity standards collectively tighten compliance thresholds and extend qualification timelines for new ampoule suppliers. India's CDSCO and China's NMPA are converging toward ICH Q3D elemental impurity and ISO 15378 GMP standards, raising barriers for regional converters while creating pathway opportunities for certified multinationals. Stakeholders must monitor regulatory divergence between US-EU pharmacopeial alignment and emerging-market adaptation speeds when siting fill-finish partnerships and qualification investments.
Market Dynamics
Single-dose prefilled formats are compressing multi-dose vial procurement across mRNA and viral-vector vaccine programs, forcing ampoule converters to retool forming lines and sterilization tunnels for smaller fill volumes and higher output speeds.
Growth Catalysts
- EMA GMP Annex 1 sterile manufacturing revisions:The 2022 update mandates enhanced container closure integrity testing, driving pharmaceutical manufacturers toward borosilicate Type I ampoules with proven barrier performance and documented extractables profiles.
- India's CDSCO ICH Q3D alignment:Elemental impurity standards convergence is disqualifying regional glass converters without certified furnace controls, opening procurement pathways for multinationals with validated tubing supply.
- mRNA platform scale-up:Lipid nanoparticle formulations require ultra-low alkali leaching specifications that only borosilicate glass with hydrolytic Class I certification can reliably deliver across frozen storage conditions.
Market Restraints
- Borosilicate glass tubing supply concentration:Germany and India host the dominant continuous melting furnaces for FIOLAX-grade tubing, creating geographic single-point vulnerability for converters without captive furnace operations.
- Aluminum oxide and rare earth input volatility:Boron and cerium price swings directly compress forming margins for mid-tier converters locked into annual supply contracts with limited pass-through mechanisms.
- Polymer cyclic olefin copolymer substitution:COC pre-filled syringes and polymer ampoules are capturing emergency stockpile tenders where breakage tolerance and weight reduction override glass barrier requirements.
Strategic Opportunities
- China's NMPA GMP-ISO 15378 harmonization:The regulatory pathway for imported primary packaging materials is shortening, creating first-mover advantage for certified suppliers establishing local qualification partnerships with domestic fill-finish operators.
- Cell and gene therapy cryogenic storage:Ultra-low temperature ampoule formats with specialized thermal shock resistance are penetrating autologous therapy logistics where standard borosilicate specifications fail at minus 150 degrees Celsius.
- Modular fill-finish skids:Compact, container-agnostic processing lines are enabling distributed manufacturing models that favor standardized ampoule formats over customized vial geometries.
Industry Challenges
- USP <1207> package integrity validation:Container closure qualification timelines now extend 18-24 months for new ampoule designs, compressing product development windows and freezing out speculative R&D programs.
- Forming technician scarcity:Automated IS machine programming and precision mold maintenance require skills concentrated in Germany and Italy, constraining capacity expansion in emerging manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Ampoules Market |
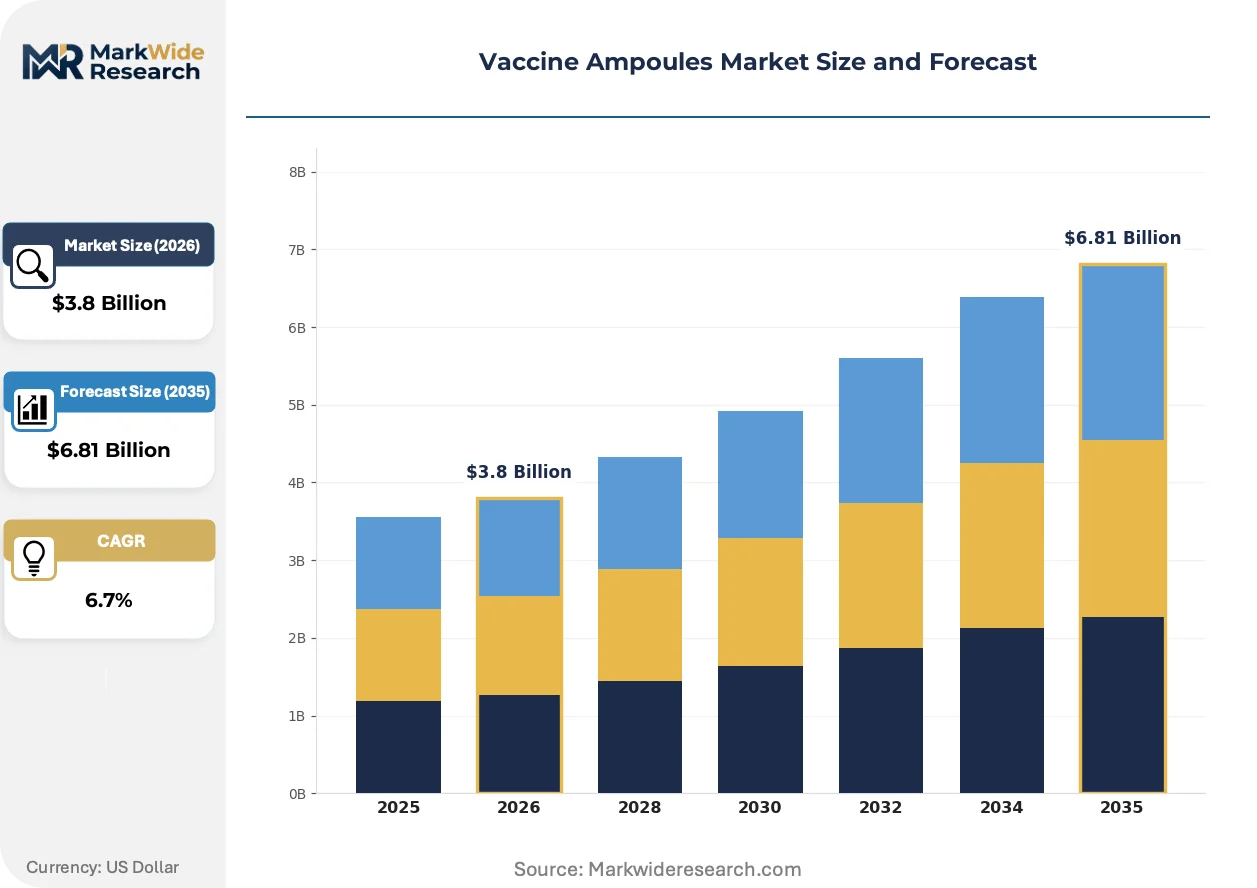
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Cap, Snap Cap, Dropper, Others Material: Glass, Plastic, Resin, Aluminum End User: Pharmaceutical Companies, Research Labs, Hospitals, Clinics Capacity: 1ml, 2ml, 5ml, 10ml |
| Companies Covered | Gerresheimer AG, SCHOTT AG, Nipro Corporation, Stevanato Group, SGD Pharma, Hindustan National Glass & Industries Ltd., Piramal Glass Pvt. Ltd., Bormioli Pharma S.p.A., Shandong Pharmaceutical Glass Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Ampoules Market Evolving Landscape
Ready-to-use sterile formats are displacing bulk-sterilized components across high-value vaccine fill-finish operations, compressing validation timelines and redefining supplier qualification criteria around integrated supply rather than discrete component sourcing.
Polymer barrier coatings applied to borosilicate glass interiors are supplanting uncoated Type I formats in parenteral applications where sodium ion migration risks compromise biologic stability. Biopharma fill-finish operators in Switzerland and the United States are adopting these siliconized or carbon-coated ampoules for lyophilized mRNA intermediates. The technology is supplanting traditional delamination-prone geometries by enabling thinner wall sections without sacrificing chemical durability, reducing per-dose glass mass and cold-chain shipping costs.
REACH restrictions on boron compound processing are tightening emissions controls at European glass melting operations, forcing furnace technology upgrades and selective capacity rationalization. The regulation's industrial consequence is accelerated consolidation among tubing suppliers unable to fund scrubber and regenerative thermal oxidizer installations. High-value pharmaceutical ampoule grades are most affected, with German and Italian converters responding by securing long-term renewable power purchase agreements to offset carbon border adjustment exposure.
Direct contracting between vaccine developers and primary packaging suppliers is collapsing the traditional distributor-mediated procurement channel for critical pandemic stockpile programs. National immunization authorities in India and Brazil are establishing approved vendor lists that bypass regional wholesalers, compressing lead times but concentrating compliance liability on manufacturers. This pattern is most visible in mRNA vaccine procurement, where developers like BioNTech and Moderna maintain direct supply relationships with SCHOTT and Gerresheimer for serialized, traceable ampoule lots.
Vaccine Ampoules Market Segmentation
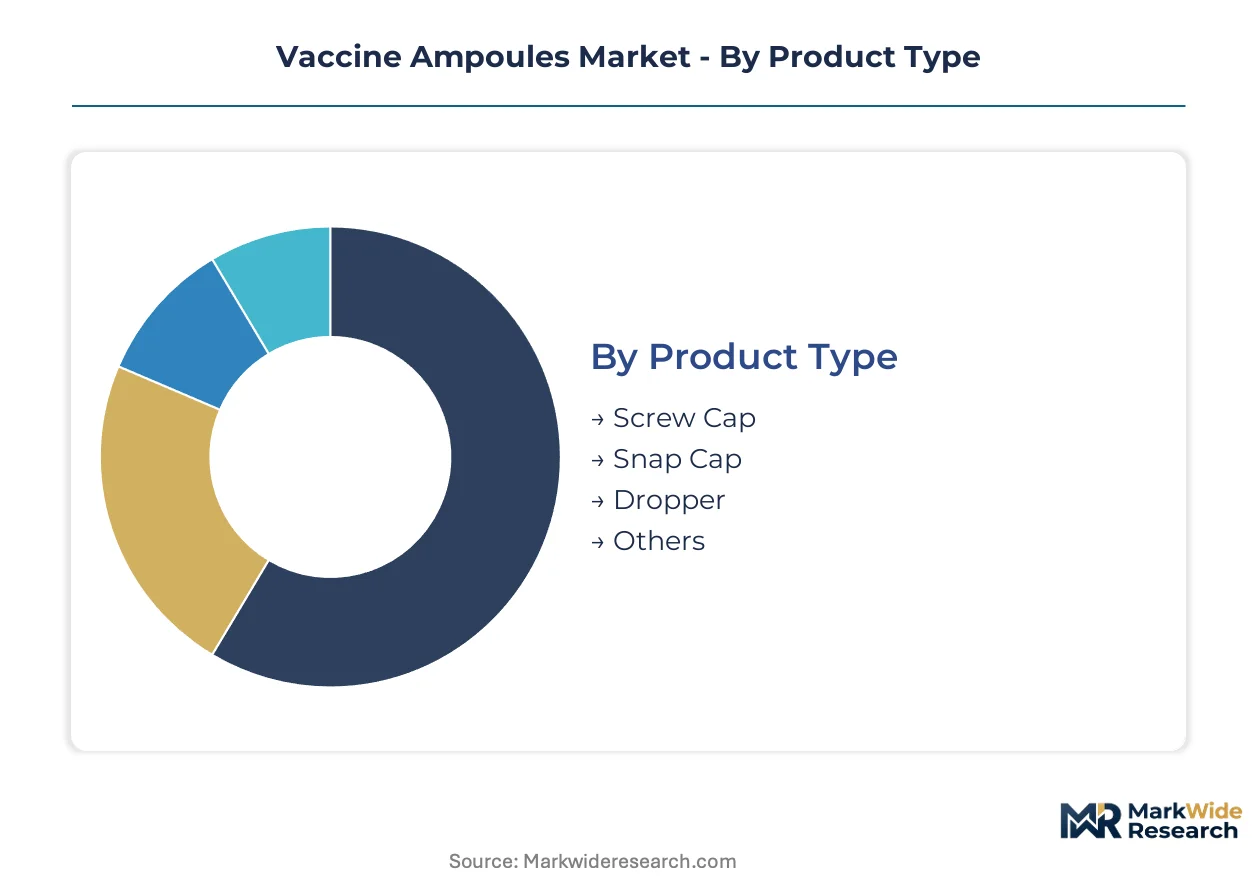
Vaccine ampoule segmentation tracks procurement priorities across fill-finish automation, cold-chain logistics, and regulatory compliance tiers. Pharmaceutical manufacturers select formats based on line speed compatibility, container closure integrity requirements, and single-dose versus multi-dose program economics.
Product Type:
Screw cap configurations command premium margin pools in institutional multi-dose settings where reseal reliability and contamination control justify higher unit pricing.
- Screw Cap:Threaded aluminum or polymer closures enable multiple withdrawals in hospital pharmacy environments. Demand concentrates in Germany and Switzerland where centralized immunization hubs prioritize dosing flexibility over speed of access.
- Snap Cap:Break-off ring designs eliminate reseal function in favor of rapid single-dose extraction. Mass immunization programs in India and Brazil are rotating procurement toward this format to reduce needle-stick incidents and accelerate throughput in high-volume campaigns.
- Dropper:Integrated bulb assemblies serve oral and nasal vaccine delivery formats. Pediatric and veterinary applications in China's tier-one cities represent the primary demand concentration.
- Others:Specialty formats including crimp-seal and tamper-evident designs for controlled-temperature chain vaccines.
Screw cap holds installed capacity. Snap cap is rotating up the share rankings.
Material:
Glass chemistry grades separate margin capture between certified tubing suppliers and commodity converters.
- Glass:Borosilicate Type I dominates mRNA and viral-vector platforms. FIOLAX-grade tubing from German and Indian furnace operations supplies fill-finish lines requiring USP hydrolytic Class I certification and documented extractables profiles.
- Plastic:Cyclic olefin copolymer and polypropylene formats penetrate emergency stockpile tenders where weight reduction and breakage tolerance override barrier requirements. India's CDSCO is qualifying polymer alternatives for field deployment scenarios.
- Resin:Barrier-coated polymer laminates serve single-use pre-filled applications in research settings.
- Aluminum:Collapsible tube formats retain niche use in veterinary and bulk adjuvant packaging.
Glass commands pricing power through certification scarcity. Plastic is climbing fastest in procurement volume.
End User:
Customer scale determines contract structure, with direct manufacturer relationships replacing distributor channels in high-value segments.
- Pharmaceutical Companies:Integrated vaccine developers including mRNA platform operators specify serialized, traceable ampoule lots with integrated RFID or 2D barcode tracking. Direct contracting with SCHOTT and Gerresheimer bypasses traditional procurement intermediaries.
- Research Labs:Small-batch lyophilized formats and non-standard fill volumes characterize preclinical and Phase I/II supply. Swissmedic and FDA IND requirements drive qualification rigor despite lower absolute volumes.
- Hospitals:Central pharmacy operations in the United States and Germany source ready-to-use sterile formats to compress validation timelines.
- Clinics:Distributed immunization sites in Brazil and India's tier-two cities prioritize breakage-resistant formats and simplified cold-chain handling.
Pharmaceutical companies hold contract value concentration. Clinics are expanding fastest in unit demand.
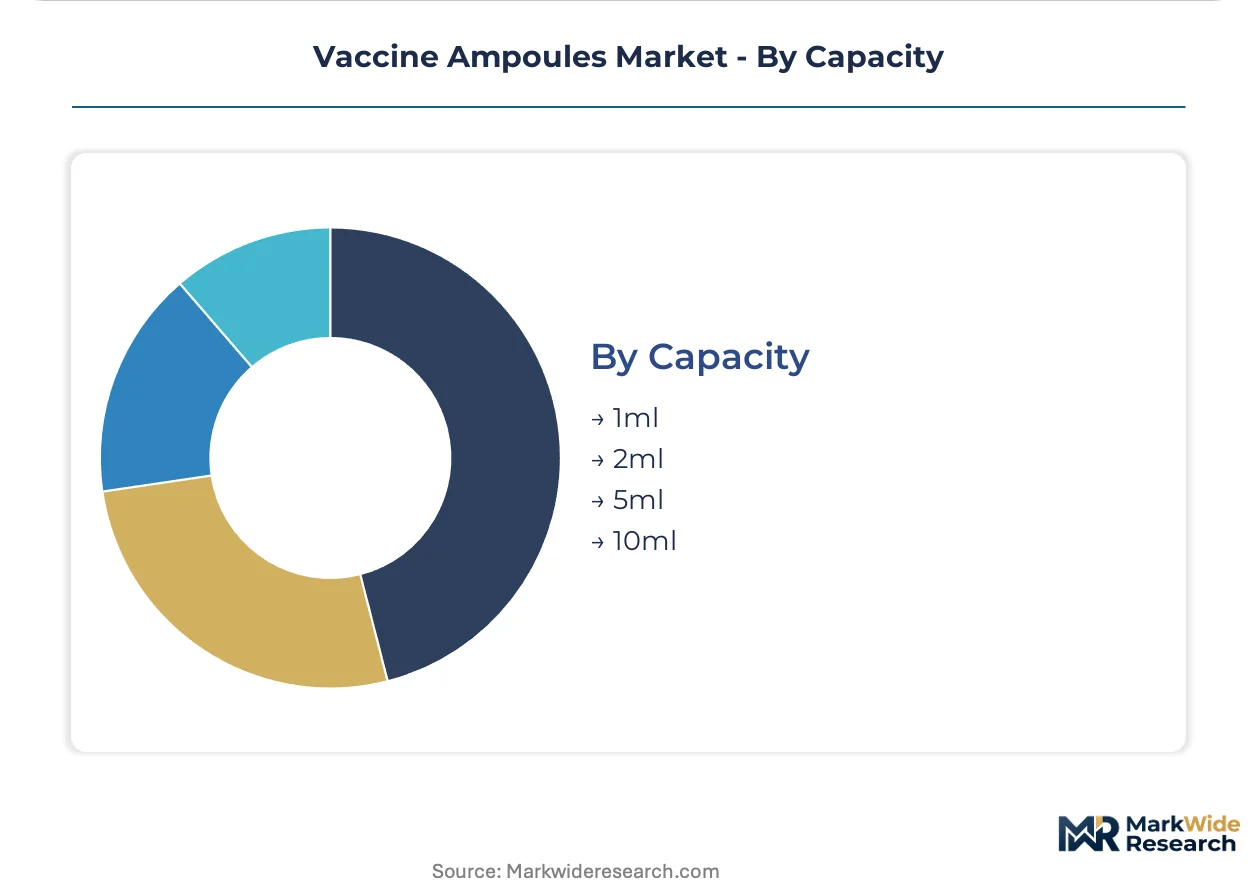
Capacity:
Fill volume specifications align with dose regimen economics and cold-chain storage density.
- 1ml:Single-dose mRNA and subunit vaccines minimize overfill waste and enable higher vial density in ultra-low temperature storage. Moderna and BioNTech commercial programs specify tight dimensional tolerances for automated inspection systems.
- 2ml:Standard pediatric and booster dose formats balance fill accuracy with line speed optimization.
- 5ml:Multi-dose institutional formats predominate in influenza and routine immunization programs.
- 10ml:Bulk diluent and adjuvant packaging for reconstitution workflows in centralized pharmacy operations.
1ml holds technology investment focus. 2ml maintains volume leadership in current procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. German and Swiss buyers absorb premium pricing for certified borosilicate formats, while Indian and Brazilian mass immunization programs prioritize unit cost minimization over barrier specifications.
Germany
FIOLAX-grade borosilicate tubing from SCHOTT's Mainz furnaces supplies mRNA vaccine fill-finish lines requiring USP hydrolytic Class I certification. EMA GMP Annex 1 revisions mandate enhanced container closure integrity testing, disqualifying converters without documented extractables profiles. The Rhine-Main industrial cluster concentrates continuous melting capacity and automated forming operations serving BioNTech and other platform developers.
India
CDSCO's ICH Q3D elemental impurity alignment is disqualifying regional glass converters lacking certified furnace controls, opening procurement pathways for multinationals with validated tubing supply. Government immunization programs rotate procurement toward snap-cap formats to accelerate throughput in high-volume campaigns. The Gujarat pharmaceutical belt hosts expanding fill-finish capacity targeting export markets.
China
NMPA GMP-ISO 15378 harmonization shortens regulatory pathways for imported primary packaging materials, creating first-mover advantage for certified suppliers establishing local qualification partnerships. Domestic developers of mRNA and viral-vector vaccines specify serialized, traceable ampoule lots with integrated tracking. The Yangtze River Delta concentrates biopharma manufacturing investment and cold-chain infrastructure expansion.
United States
FDA container closure guidance and USP 1207 package integrity standards extend qualification timelines for new ampoule suppliers, compressing product development windows. Moderna maintains direct supply relationships with certified manufacturers for serialized lots. The Greater Boston biotech corridor drives demand for ready-to-use sterile formats that compress validation timelines.
Brazil
ANVISA's convergence toward ICH standards raises barriers for regional converters while creating pathway opportunities for certified multinationals. National immunization authorities establish approved vendor lists that bypass regional wholesalers, concentrating compliance liability on manufacturers. São Paulo's pharmaceutical distribution hub prioritizes breakage-resistant formats for distributed immunization sites.
Vaccine Ampoules Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. German and Italian specialists command premium positioning through captive tubing supply and proprietary forming technology, while Asian converters compete on scale and unit economics. The market separates into three strategic archetypes: integrated tubing-to-ampoule manufacturers, regional glass converters dependent on merchant tubing supply, and polymer format specialists targeting emergency stockpile applications. Dominant competitive moves include backward integration into borosilicate furnace operations and direct contracting partnerships with mRNA platform developers.
Among European integrated manufacturers, Gerresheimer AG and SCHOTT AG exemplify the technology-leadership archetype through upstream control over glass tubing production. Nipro Corporation occupies a position within the Asian converter tier, representing scale-driven competitive positioning. These three companies anchor the supplier base that pharmaceutical manufacturers engage for high-value vaccine programs requiring documented extractables profiles and serialized lot traceability.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| Nipro Corporation |
| Stevanato Group |
| SGD Pharma |
| Hindustan National Glass & Industries Ltd. |
| Piramal Glass Pvt. Ltd. |
| Bormioli Pharma S.p.A. |
| Shandong Pharmaceutical Glass Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between mRNA platform developers and certified borosilicate tubing suppliers lock in multi-year supply access while anchoring price visibility against volatile rare earth and aluminum oxide input costs. These arrangements concentrate procurement leverage with German and Indian furnace operators who control FIOLAX-grade tubing output.
Pricing Analysis
After-sales service contracts for sterilization validation and extractables documentation drive lifetime value capture for integrated tubing-to-ampoule manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates certified USP hydrolytic Class I formats from regional converter output and polymer emergency-stockpile alternatives. Cost compression in mid-tier converter segments is intensifying because annual supply contracts lack pass-through mechanisms for boron price swings. Mass immunization programs in Brazil and India exhibit highest price sensitivity, while Swiss and German pharmaceutical developers absorb premiums for serialized, traceable lots.
Supply Chain Analysis
Germany and India anchor continuous melting furnace operations for pharmaceutical-grade borosilicate tubing, with Italian converters supplying precision forming expertise. The supply chain draws from concentrated rare earth and aluminum oxide feedstocks, with furnace operations tethered to emissions-compliant energy sourcing. Single-source vulnerability runs through SCHOTT's Mainz and Gerresheimer's captive furnace networks, where equipment failure or regulatory shutdown would cascade through mRNA vaccine fill-finish lines. Distribution runs through direct manufacturer contracting that bypasses traditional regional wholesalers for pandemic stockpile programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vaccine ampoule demand is recovering cyclically as post-pandemic mRNA platform investments normalize and cell therapy cold-chain requirements expand. The cyclical driver is biopharma capital expenditure reactivation following regulatory clarity on container closure integrity standards.
For Market Incumbents: Shield premium positioning by securing captive renewable power purchase agreements for furnace operations ahead of EU carbon border adjustments. Accelerate backward integration into certified tubing supply where merchant dependence exposes margin compression from ICH Q3D elemental impurity enforcement. Polymer substitution in emergency stockpiles and REACH emissions restrictions on boron processing constitute the primary threats requiring defensive certification investment and green furnace technology deployment. For New Entrants and Emerging Players: Ready-to-use sterile format gaps in distributed manufacturing models offer white-space entry where incumbents under-serve modular fill-finish skid operators. Target cryogenic storage ampoule development for autologous cell therapy logistics, where standard borosilicate specifications fail at ultra-low temperatures. Partner with domestic fill-finish operators in China and Brazil for local qualification pathways as NMPA and ANVISA converge toward ICH standards. For Investors and Strategic Acquirers: Capital is best deployed toward integrated tubing-to-ampoule manufacturers with validated furnace controls and documented extractables profiles across the 5-10 year biologics expansion horizon. Acquisition target archetype: mid-tier converters with installed forming capacity but lacking captive tubing supply, positioned for rollup into multinational qualification networks. Watch EMA GMP Annex 1 enforcement intensity as the signal indicating accelerated consolidation among non-compliant regional suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tubing Supply | Captive FIOLAX-grade furnace operations insulate Gerresheimer and SCHOTT from merchant supply volatility. |
| Ready-to-Use Sterile Format Expansion | Pre-sterilized ampoules compress CDSCO and FDA validation timelines for Indian and US fill-finish operators. |
| Cryogenic Storage Format Development | Ultra-low temperature ampoules penetrate autologous therapy logistics where standard borosilicate fails. |
| Direct Contracting Partnerships | BioNTech and Moderna bypass distributors for serialized lots with integrated RFID traceability. |
| Green Furnace Technology Upgrade | Regenerative thermal oxidizer installations respond to REACH boron compound processing restrictions. |
Research Methodology
Cross-validation between primary interviews with fill-finish operations managers, regulatory affairs leads at CDSCO and FDA, and glass converter procurement directors anchors the qualitative findings against secondary data from USP pharmacopeial filings, EMA GMP Annex 1 revision texts, and customs trade records for borosilicate tubing imports. Bottom-up triangulation across automated forming line capacity assessments and top-down validation through pharmaceutical packaging expenditure patterns ensure methodological robustness.
Sensitivity analysis on boron price volatility and regulatory qualification timeline extensions frames the analytical approach across the projection horizon. Segmentation dimensions modeled include material chemistry grade, closure configuration type, fill-finish capacity tier, end-user contract structure, and regional regulatory cluster alignment. CAGRs were derived from installed base growth rates and replacement cycle analysis, with mRNA platform scale-up assumptions and cold-chain infrastructure investment patterns serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in USP, EP, and ICH Q3D regimes; material policy shifts in elemental impurity thresholds or container closure testing protocols would require re-modeling. Recalibration cycles align with material shifts in EMA enforcement patterns, NMPA harmonization milestones, and biopharma platform technology transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market