
 Triptorelin Market | 2026-2036
Triptorelin Market Size, Share, and Industry Trends Forecast 2026-2036
Triptorelin Market Analytics
REACH is restructuring the cost-of-entry calculus for European peptide manufacturers by mandating exhaustive substance registration and toxicity documentation. Ipsen Pharma leverages its Lyon-based manufacturing footprint to sustain dominant supply of one-month and three-month depot formulations across EU member states. Ferring Pharmaceuticals anchors its position through specialized R&D in controlled-release polymer matrices. Dr. Reddy's Laboratories competes on cost-engineered generic alternatives that navigate complex EMA bioequivalence pathways.
Triptorelin is a synthetic decapeptide analogue of gonadotropin-releasing hormone (GnRH), formulated as pamoate or acetate salts in microsphere depot suspensions for sustained release over one, three, or six months. It functions as a potent GnRH agonist that initially stimulates then downregulates pituitary gonadotropin secretion, serving primary commercial purposes in hormone-dependent malignancy and reproductive disorder management. The therapy area dimension shows prostate cancer commanding the largest revenue pool due to aging demographics, while central precocious puberty represents the fastest-growing segment driven by expanded pediatric endocrinology screening. Pre-filled syringe formats concentrate margin pools through premium pricing of patient-administered subcutaneous delivery systems that reduce clinic dependency.
FDA peptide quality guidelines, EMA GMP Annex 1 sterile manufacturing requirements, and China's NMPA pharmacovigilance protocols collectively shape product standards, batch release timelines, and market access conditions across major jurisdictions. These frameworks compel manufacturers to maintain redundant quality systems and region-specific stability data packages. Stakeholders must monitor evolving biosimilar interchangeability designations and peptide-specific immunogenicity assessment requirements that will determine competitive positioning in the decade ahead.
Market Dynamics
FDA's tightened bioequivalence standards for peptide therapeutics are compressing competitive entry timelines and elevating manufacturing compliance costs across the triptorelin value chain. This regulatory pressure is restructuring the economics of depot formulation production.
Growth Catalysts
- Prostate cancer screening expansion:Aging demographics in the United States are enlarging the addressable patient pool for androgen deprivation therapy. American oncology centers are broadening triptorelin access protocols.
- REACH substance registration:European manufacturers completing exhaustive toxicity documentation are securing preferential supply positions. ECHA compliance is becoming a competitive moat for established peptide producers.
- Pre-filled syringe adoption:Patient-administered subcutaneous delivery systems are reducing clinic dependency. Pediatric endocrinology practices are integrating these formats for central precocious puberty management.
Market Restraints
- Polymer matrix input volatility:Controlled-release formulation depends on specialized biodegradable polymers. Supply tightness in medical-grade PLGA resins is compressing margin structures.
- Sterile manufacturing concentration:EMA GMP Annex 1-compliant facilities cluster in Germany and France. Limited qualified CDMO capacity is extending batch release timelines.
- Peptide synthesis complexity:Solid-phase synthesis of decapeptide analogues requires protected amino acid building blocks. Purification bottlenecks constrain output scaling.
Strategic Opportunities
- Pediatric endocrinology expansion:Central precocious puberty remains underdiagnosed in India. CDSCO pathway navigation offers first-mover positioning for depot formulations.
- Six-month depot penetration:Extended-release formulations reduce injection frequency. Urology clinics in the United States are converting patients from one-month to longer-acting alternatives.
- EMA bioequivalence guidance evolution:Peptide-specific immunogenicity assessment protocols are creating differentiation avenues. Manufacturers with robust antibody monitoring datasets gain regulatory preference.
Industry Challenges
- Peptide analytical chemistry talent scarcity:Mass spectrometry and HPLC method development for complex peptide characterization requires specialized expertise. European manufacturers report extended hiring cycles for QC leadership.
- Stability data package compilation:Region-specific ICH Q1A requirements demand redundant real-time and accelerated testing. Shelf-life extension submissions consume 18-24 month validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triptorelin Market |
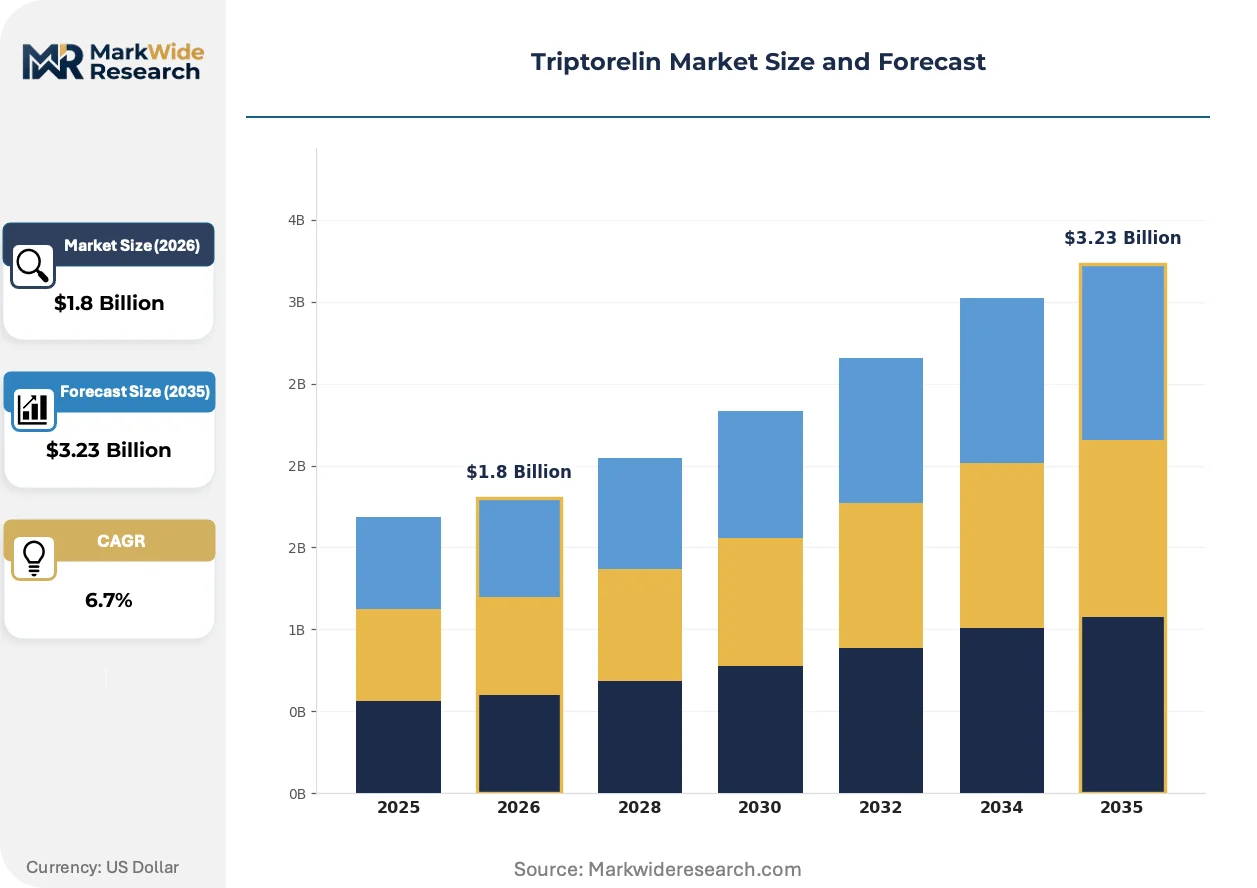
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Powder, Pre-filled Syringe, Liquid End User: Hospitals, Clinics, Specialty Pharmacies, Research Institutions Therapy Area: Endometriosis, Prostate Cancer, Central Precocious Puberty, Uterine Fibroids Administration Route: Subcutaneous, Intramuscular, Intravenous, Oral |
| Companies Covered | Ipsen Pharma, Ferring Pharmaceuticals, Dr. Reddy's Laboratories Ltd, Azurity Pharmaceuticals, Debiopharm Group, Bachem, Teva Pharmaceutical Industries Ltd, Merck KGaA, Anhui Anke Bioengineering (Group) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triptorelin Market Evolving Landscape
Depot formulation technologies are converging with patient-centric delivery designs, compressing the gap between clinical efficacy and administration convenience. Three developments are restructuring competitive positioning.
Microsphere engineering is unifying polymer degradation kinetics with active pharmaceutical ingredient release profiles. Urology clinics in Germany are adopting three-month and six-month depot suspensions to reduce patient visit frequency. This unifying capability is compressing the market share of conventional one-month formulations by enabling protocol consolidation.
EMA's revised GMP Annex 1 sterile manufacturing requirements are mandating barrier isolation technology and continuous environmental monitoring. Peptide depot producers are retrofitting fill-finish lines with restricted access barrier systems. French and German manufacturing sites face the steepest compliance capital requirements, accelerating facility consolidation.
After-sales service unbundling is fragmenting traditional supplier-buyer relationships. Hospital pharmacy procurement teams are separating device training from product supply contracts. This shift is most visible in United States academic medical centers, where in-house compounding capabilities reduce dependency on manufacturer-supported injection programs.
Triptorelin Market Segmentation
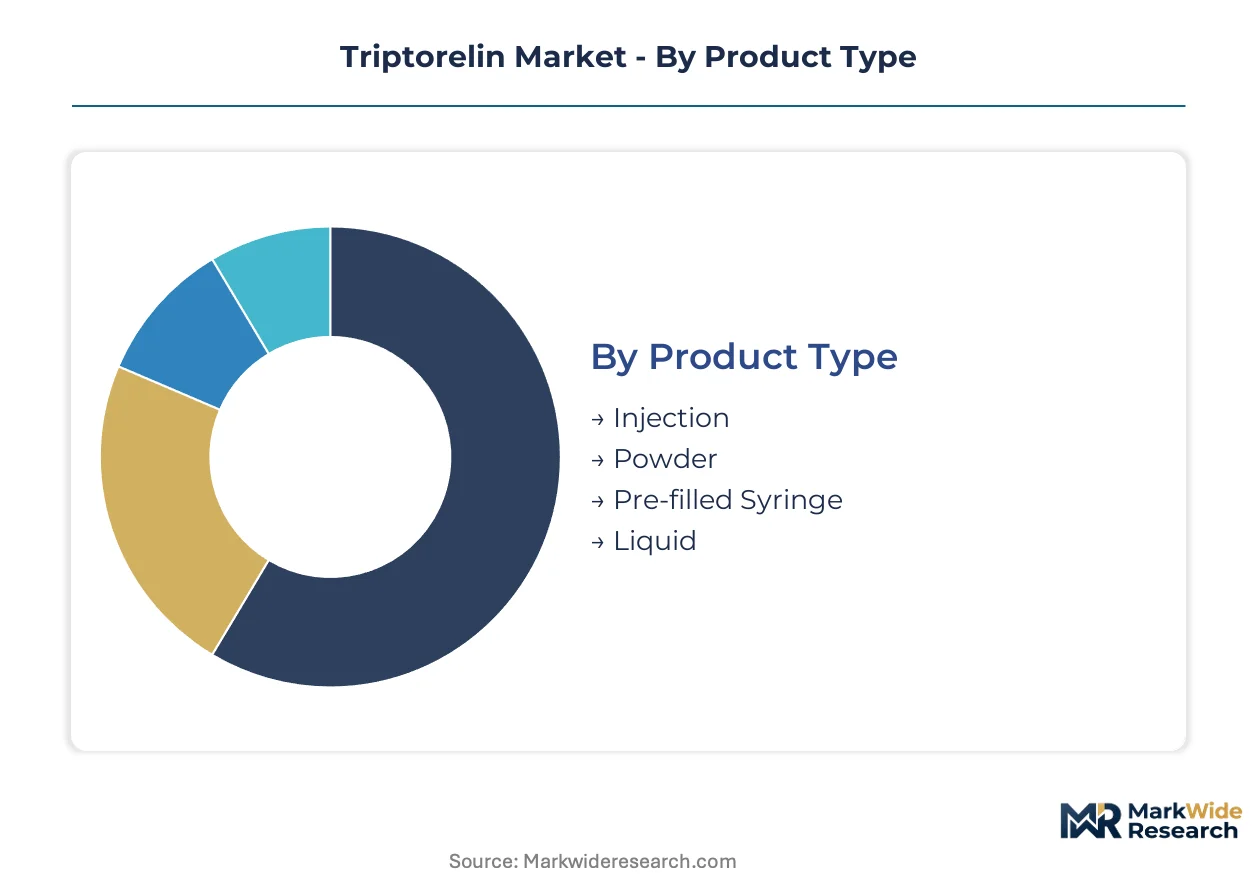
Triptorelin formulation diversity creates distinct margin architectures across administration technologies. Product type selection dictates manufacturing complexity, cold-chain requirements, and pricing power in hospital procurement negotiations.
Product Type:
Hospital pharmacy procurement teams weight total cost-of-therapy against administration labor and waste reduction when selecting presentation formats.
- Pre-filled Syringe:Ready-to-use subcutaneous delivery systems eliminate compounding steps and reduce dosing errors. Demand concentrates in German urology clinics where nurse time optimization drives premium acceptance for patient-administered formats.
- Injection:Conventional vial-and-syringe presentations require reconstitution of lyophilized peptide with sterile diluent. Volume concentrates in American oncology centers with established pharmacy compounding infrastructure and protocol familiarity.
- Powder:Lyophilized bulk peptide for institutional compounding enables batch customization for pediatric dosing. Research institutions in France utilize this format for clinical trial material preparation.
- Liquid:Ready-to-use solutions shorten preparation time in high-throughput infusion centers. Shelf-life limitations restrict distribution to facilities with rapid inventory turnover.
Volume sits with Injection; growth tilts toward Pre-filled Syringe.
End User:
Site-of-care economics and reimbursement pathways fragment purchasing authority across institutional settings.
- Hospitals:Integrated health systems leverage formulary control and 340B pricing advantages to consolidate triptorelin purchasing. American academic medical centers anchor volume through prostate cancer service line expansion.
- Specialty Pharmacies:Limited distribution networks manage prior authorization complexity and patient adherence monitoring. These channels capture margin through hub services and injection training programs.
- Clinics:Independent urology and endocrinology practices prioritize procurement flexibility and minimal order quantities. German outpatient clinics drive sustained prescription volumes for depot formulations.
- Research Institutions:Clinical trial supply demands drive purchases of non-commercial presentations and comparator products. Investigator-sponsored studies in central precocious puberty generate specialized procurement requirements.
Revenue concentrates in Hospitals; expansion accelerates fastest in Specialty Pharmacies.
Therapy Area:
Disease prevalence, treatment duration, and competitive alternatives reshape segment economics across indications.
- Prostate Cancer:Androgen deprivation therapy for hormone-sensitive malignancy generates sustained multi-year dosing cycles. Aging demographics in the United States enlarge the addressable patient pool for long-acting depot protocols.
- Central Precocious Puberty:Pediatric endocrinology screening expansion is accelerating diagnosis rates and treatment initiation. This segment climbs the fastest as delayed puberty intervention gains clinical acceptance.
- Endometriosis:GnRH agonist suppression of estrogen-driven pathology serves second-line therapy positioning after hormonal contraceptives. French gynecology practices maintain consistent prescribing patterns for refractory cases.
- Uterine Fibroids:Pre-surgical volume reduction and symptomatic management create intermittent dosing opportunities. Fibroid embolization competition constrains long-term maintenance therapy adoption.
Prostate Cancer anchors revenue; Central Precocious Puberty drives volume expansion.
Administration Route:
Pharmacokinetic requirements and patient self-administration capability determine route selection for each indication.
- Intramuscular:Deep gluteal or deltoid injection of depot suspensions enables controlled release over one to six months. German urology clinics favor this route for prostate cancer patients with reliable clinic access.
- Subcutaneous:Abdominal or thigh injection permits patient or caregiver administration without clinical supervision. Pediatric endocrinology practices integrate this capability for central precocious puberty home management.
- Intravenous:Bolus or infusion delivery serves research protocols and specialized clinical scenarios requiring immediate peptide bioavailability. Limited commercial utilization restricts formulation development investment.
- Oral:Gastrointestinal degradation of peptide structure renders this route pharmacologically ineffective. No commercial products exist; research interest focuses on absorption enhancer technologies.
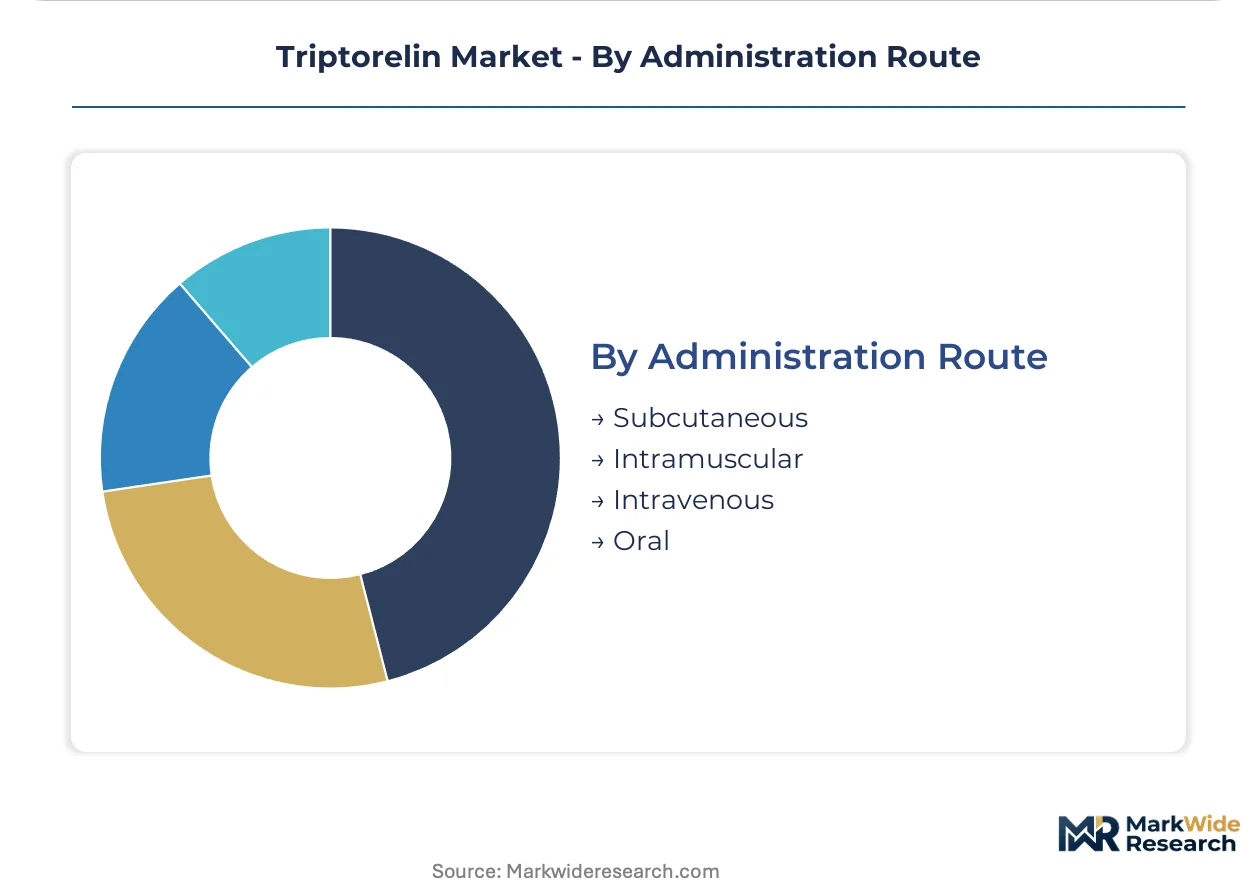
Intramuscular dominates current volume; Subcutaneous gains share through patient-administration protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharma parks in Hyderabad and Bavaria concentrate peptide manufacturing through tax incentives and specialized infrastructure. FDA, EMA, and CDSCO frameworks fragment regulatory pathways across major demand centers.
United States
American oncology centers drive prostate cancer protocol expansion through androgen deprivation therapy. FDA tightened bioequivalence standards for peptide therapeutics in 2023, elevating manufacturing compliance costs. Boston and San Francisco biotech clusters anchor clinical trial networks for depot formulation development.
Germany
German urology clinics sustain prescription volumes for long-acting depot formulations through aging demographics. EMA GMP Annex 1 sterile manufacturing requirements mandate barrier isolation technology retrofitting. The Rhine-Main industrial corridor concentrates qualified CDMO capacity for peptide fill-finish operations.
France
French gynecology practices maintain consistent prescribing patterns for endometriosis second-line therapy. ANSM enforces pharmacovigilance protocols for GnRH agonist immunogenicity monitoring. Lyon-based manufacturing sites leverage polymer matrix expertise for controlled-release formulation supply.
India
Central precocious puberty underdiagnosis creates expansion opportunity for pediatric endocrinology screening. CDSCO pathway navigation offers first-mover positioning for depot formulations. Hyderabad's Genome Valley anchors peptide synthesis and sterile manufacturing infrastructure for export markets.
China
NMPA pharmacovigilance protocols shape batch release timelines for imported peptide therapeutics. Shanghai and Suzhou biotech parks concentrate CMO capacity for solid-phase synthesis operations. Domestic manufacturers compete on cost-engineered alternatives for hospital procurement tenders.
Triptorelin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and manufacturing tiers. The market structures around three strategic archetypes: established European pharmaceutical houses with depot expertise, Indian generic manufacturers navigating bioequivalence pathways, and Chinese peptide synthesis specialists. Capacity expansion and polymer matrix technology licensing represent dominant competitive moves.
Among European pharmaceutical houses, Ipsen Pharma and Ferring Pharmaceuticals exemplify the depot formulation specialist archetype through sustained supply of controlled-release polymer matrices. Dr. Reddy's Laboratories Ltd occupies a position within the cost-engineered generic tier, navigating complex regulatory pathways for market entry.
| Leading Market Players |
|---|
| Ipsen Pharma |
| Ferring Pharmaceuticals |
| Dr. Reddy's Laboratories Ltd |
| Azurity Pharmaceuticals |
| Debiopharm Group |
| Bachem |
| Teva Pharmaceutical Industries Ltd |
| Merck KGaA |
| Anhui Anke Bioengineering (Group) Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Medical-grade PLGA resin price indices cascade through triptorelin depot manufacturing into three distinct pricing tiers. Long-acting six-month formulations command premium positioning against one-month alternatives as polymer input costs concentrate margin pressure on shorter-duration products. German hospital pharmacy procurement teams exploit this structure through volume aggregation and formulary tiering.
Pricing Analysis
Lead-time-driven pricing stratification rewards advance contracting with qualified CDMOs while spot purchases of pre-filled syringe formats absorb scarcity premiums. Three-tier pricing structure across premium, standard, and economy levels separates patient-administered subcutaneous delivery systems from institutional vial-and-syringe presentations and bulk lyophilized powder for compounding. Cost compression in economy-tier generic alternatives intensifies as Indian manufacturers navigate EMA bioequivalence pathways with accelerated submissions. Pediatric endocrinology practices exhibit highest price sensitivity due to reimbursement caps, while American academic medical centers with 340B pricing advantages demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-hospital channels handle formulary-controlled purchasing through integrated health systems, while specialty pharmacy networks manage limited distribution for patient-administered formats. Manufacturing gravity centers on France, Germany, and India, with Lyon-based polymer matrix expertise anchoring European controlled-release formulation supply. Solid-phase synthesis draws from protected amino acid building blocks sourced through Swiss and Japanese specialty chemical suppliers. Single-source vulnerability concentrates in medical-grade PLGA resin production, where qualified polymer suppliers number fewer than five globally. Distribution runs through temperature-controlled logistics networks with validated cold-chain documentation for peptide stability maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA tightened bioequivalence standards for peptide therapeutics erect a cost-of-compliance barrier that entrenches established depot formulation specialists against generic challengers. This regulatory moat rewards manufacturers with redundant quality systems and region-specific stability data packages already validated across multiple jurisdictions.
For Market Incumbents: Hedge against polymer matrix input volatility through captive supply agreements or backward integration into medical-grade PLGA resin sourcing. Defensive consolidation moves include acquiring qualified CDMO capacity in the Rhine-Main corridor and investing in barrier isolation technology retrofitting ahead of EMA GMP Annex 1 enforcement deadlines. The threat of Indian cost-engineered alternatives penetrating European markets demands preemptive formulary lock-in with German urology clinic networks. For New Entrants and Emerging Players: Launch via CDSCO pathway navigation for central precocious puberty depot formulations in India, where pediatric endocrinology screening expansion creates first-mover white space. Target American specialty pharmacy limited distribution networks with patient-administered subcutaneous formats that reduce clinic dependency. The most penetrable segment remains six-month depot conversions from one-month protocols in United States urology practices seeking injection frequency reduction. For Investors and Strategic Acquirers: Distressed-cycle entries favor European pharmaceutical houses with depot expertise facing capital intensity pressure from sterile manufacturing compliance retrofitting. Long-term viability over the projection horizon rests on polymer matrix technology licensing positions and ECHA REACH registration completeness. The signal to watch is biosimilar interchangeability designation evolution for peptide therapeutics, which would restructure competitive economics for depot formulation incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Matrix Technology Licensing | Ferring Pharmaceuticals and Ipsen Pharma leverage Lyon-based controlled-release expertise to capture royalty streams from generic manufacturers. |
| EMA GMP Annex 1 Compliance Retrofit | French and German manufacturing sites face steepest capital requirements, accelerating facility consolidation among qualified CDMOs. |
| CDSCO Pathway Navigation | First-mover positioning in Indian central precocious puberty screening expansion requires localized clinical trial infrastructure investment. |
| Six-Month Depot Formulation Conversion | American urology clinics reduce patient visit frequency through extended-release protocol adoption, displacing one-month formulations. |
| Pre-filled Syringe Format Expansion | Pediatric endocrinology practices integrate patient-administered subcutaneous delivery for home management of central precocious puberty. |
Research Methodology
Document review covered FDA peptide quality guidelines, EMA GMP Annex 1 sterile manufacturing requirements, and ClinicalTrials.gov registry entries, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from ECHA REACH substance registration databases, CDSCO approval records, and NMPA pharmacovigilance protocols. Bottom-up patient volume modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Segmented outputs by product type, therapy area, administration route, and regional regulatory cluster informed the analytical framework throughout the projection horizon. CAGRs derived from patient population epidemiology, treatment duration assumptions, and pricing trajectory modeling across depot formulation duration tiers. Forecast inputs incorporated prostate cancer screening expansion rates, pediatric endocrinology diagnosis trends, and polymer matrix technology adoption curves.
The model assumes a particular technology adoption path for microsphere depot engineering; alternative pathways for biodegradable polymer degradation kinetics would alter the outlook for formulation duration preferences. Forecasts reflect assumptions regarding regulatory pathway stability, reimbursement continuity, and sterile manufacturing capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Global Mono Vaccine Market
Biopharmaceuticals
Prokaryotic Recombinant Protein Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Metabolism Drugs Market