
 Adalimumab Biosimilar Market | 2026-2036
Adalimumab Biosimilar Market Size, Share, and Industry Trends Forecast 2026-2036
Adalimumab Biosimilar Market Analysis
The EU Green Deal's pharmaceutical sustainability criteria is pivoting procurement standards across European hospital networks. Amgen Inc. leverages its manufacturing scale to sustain supply commitments across multiple geographies. Pfizer anchors its position through integrated distribution networks that reach hospital and clinic end users directly.
Adalimumab biosimilars are recombinant monoclonal antibodies targeting tumor necrosis factor-alpha, manufactured through mammalian cell culture in bioreactors exceeding 10,000-liter capacity, and prescribed primarily to reduce inflammation in autoimmune conditions. The application dimension shows Crohn's Disease and Inflammatory Bowel Disease representing concentrated demand growth as gastroenterology clinics expand biologic therapy access. Hospitals dominate the end user segment due to infusion protocol requirements and rheumatology department purchasing concentration.
The FDA interchangeable biosimilar pathway, EMA biosimilar comparability guidelines, and WHO prequalification standards collectively determine market access timelines and substitution authority across jurisdictions. These frameworks create divergent entry speeds, with US state-level pharmacy substitution laws adding complexity to national rollout strategies. Stakeholders must monitor payer policy evolution around automatic substitution and rebate contracting as these mechanisms determine commercial traction regardless of regulatory approval status.
Market Dynamics
The adalimumab biosimilar market pivots on payer substitution authority as the central structural force, with pharmacy-level interchangeability determinations in the United States and Germany compressing brand loyalty faster than clinical differentiation alone permits.
Growth Catalysts
- IRA Medicare price negotiation:The Inflation Reduction Act's biologic price benchmarks create direct substitution incentives for hospital formularies managing rheumatology department budgets.
- Gastroenterology clinic expansion:Crohn's Disease and Inflammatory Bowel Disease treatment centers in South Korea and Germany are scaling biologic therapy access protocols.
- EMA biosimilar comparability guidelines:Streamlined extrapolation pathways accelerate approval timelines for secondary indications beyond rheumatoid arthritis.
Market Restraints
- Single-source API concentration:Mammalian cell culture media and specialized bioreactor components concentrate among Korean and German suppliers, creating input vulnerability.
- US state-level substitution heterogeneity:Pharmacy laws in Texas, Florida, and California diverge on automatic interchangeability, fragmenting national rollout strategies.
- Originator patent thickets:Remaining formulation and device patents in the United States delay full generic substitution despite molecule expiration.
Strategic Opportunities
- Underpenetrated gastroenterology in India:CDSCO approval pathways and government hospital procurement expansion create first-mover positioning for biosimilar entrants.
- WHO prequalification for emerging markets:African and Southeast Asian tender markets reward manufacturers achieving WHO standards with multi-year supply contracts.
- Pre-filled syringe-to-auto-injector convergence:Device technology upgrades enable patient self-administration, expanding addressable populations beyond infusion centers.
Industry Challenges
- Bioprocess engineer scarcity:Mammalian cell culture expertise at 10,000-liter bioreactor scale concentrates among a limited talent pool in Basel, Boston, and Seoul.
- Immunogenicity surveillance infrastructure:Post-market pharmacovigilance systems require multi-year data collection commitments that strain mid-cap manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adalimumab Biosimilar Market |
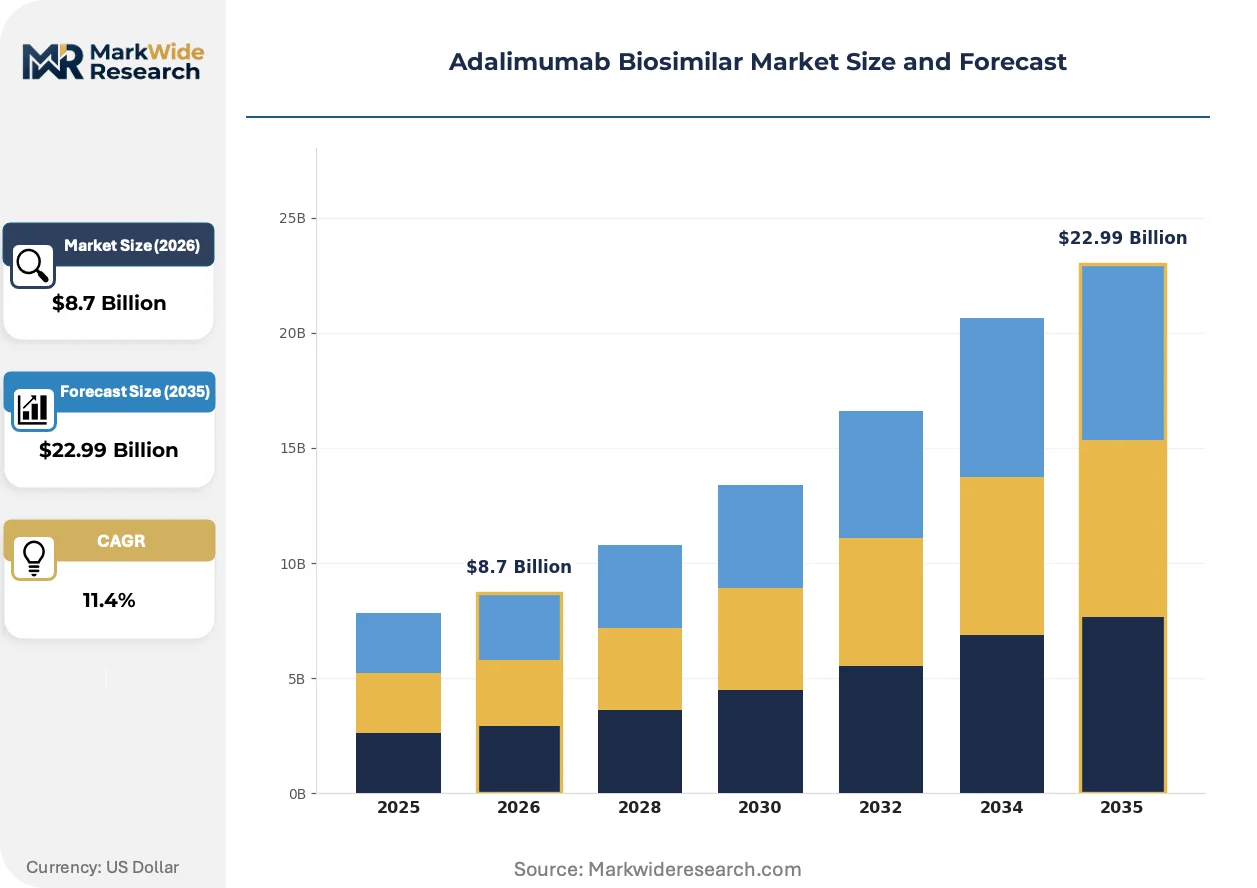
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reference Product, Originator, Biosimilar, Biologics Application: Rheumatoid Arthritis, Psoriasis, Inflammatory Bowel Disease, Crohn's Disease End User: Hospitals, Clinics, Pharmacies, Research Institutions Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | Amgen Inc., Pfizer, Sandoz, Celltrion, Inc., Boehringer Ingelheim, Samsung Bioepis, Coherus Biosciences, Fresenius Kabi, Zydus Cadila, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adalimumab Biosimilar Market Emerging Trajectories
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times while regulatory convergence around analytical similarity criteria is narrowing the evidentiary gap between reference products and biosimilars.
Single-use bioreactor systems is absorbing capital allocation from stainless steel infrastructure as contract manufacturers in Germany and South Korea prioritize facility flexibility over fixed-asset utilization. Mid-scale CDMOs serving European hospital networks are adopting disposable technologies at 2,000-5,000 liter scales to enable rapid product changeovers. This shift is absorbing the traditional economies-of-scale advantage that anchored originator manufacturing strategies.
The FDA interchangeable biosimilar designation pathway now requires switching studies demonstrating no impact on efficacy or safety versus multiple switches between reference and biosimilar. This evidentiary bar is compressing approval timelines for manufacturers with robust immunogenicity datasets. Rheumatology and gastroenterology clinics in the United States are restructuring formularies to prioritize interchangeability status in payer contracting.
Hospital procurement consolidation through group purchasing organizations is displacing individual hospital pharmacy negotiations in the United States and Germany. Integrated delivery networks in Texas and Bavaria are centralizing biologic purchasing decisions, compressing vendor counts and favoring suppliers with direct distribution infrastructure. This concentration is most visible in academic medical centers managing high-volume autoimmune patient populations.
Adalimumab Biosimilar Market Segmentation
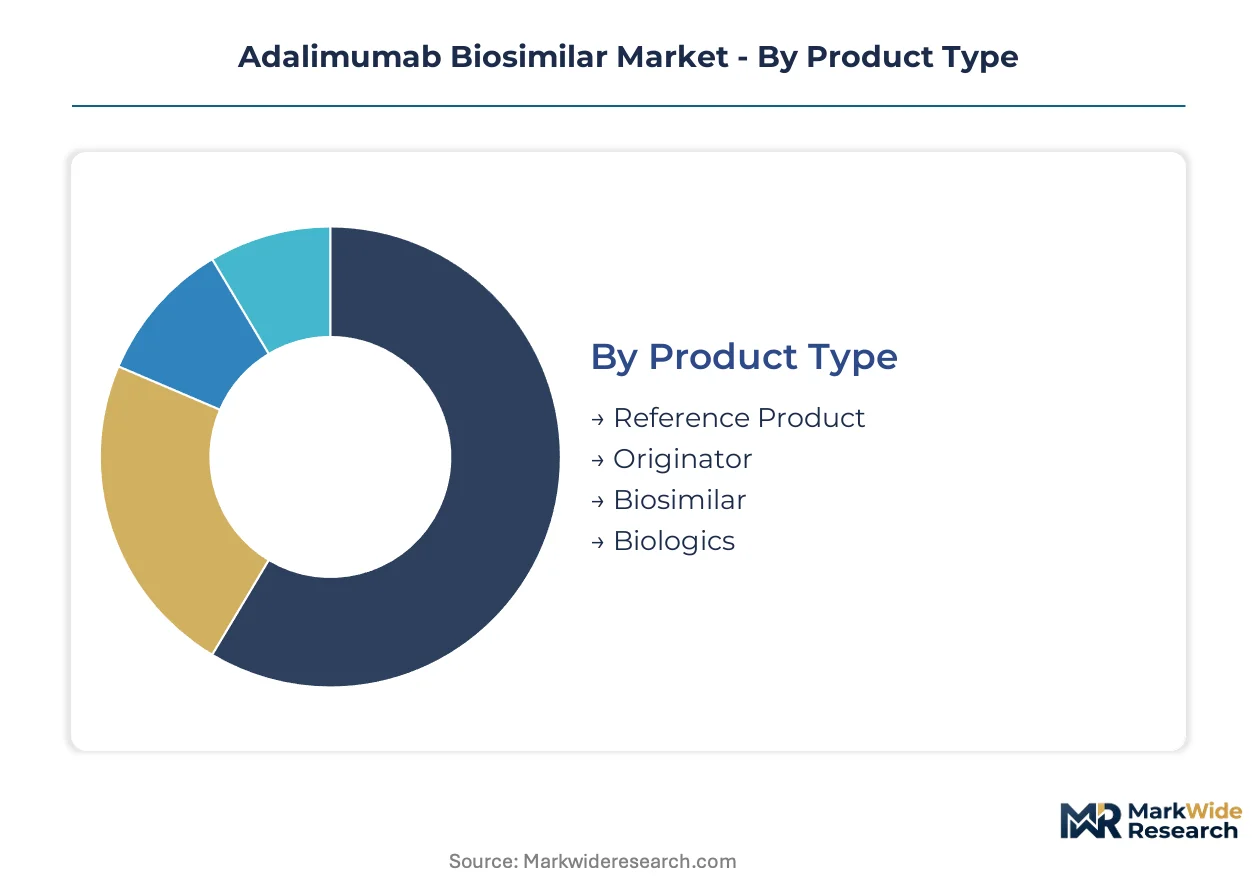
Adalimumab biosimilar segmentation reveals how procurement authority, clinical protocol requirements, and payer reimbursement structures fragment commercial pathways. Manufacturers must align formulation specifications, distribution infrastructure, and clinical evidence packages to the decision-making logic of each segment.
Product Type:
Procurement sophistication varies sharply across buyer types, with integrated delivery networks applying distinct technical criteria than independent specialty pharmacies.
- Reference Product:The originator adalimumab molecule maintains residual formulary presence in US academic medical centers where long-term immunogenicity datasets anchor clinical confidence. Rheumatology departments in Texas and Massachusetts cite switching risk protocols that delay biosimilar conversion for stable patients.
- Biosimilar:Recombinant monoclonal antibodies manufactured through mammalian cell culture in 10,000-liter bioreactors now dominate German hospital procurement through the EU Green Deal's pharmaceutical sustainability criteria. EMA comparability guidelines enable extrapolation across indications, compressing approval timelines versus full development programs.
- Originator:AbbVie's Humira retains contracted positions in US commercial insurance plans through rebate structures that offset net price erosion.
- Biologics:The broader therapeutic class encompasses originator and biosimilar TNF-alpha inhibitors competing within hospital formularies.
Biosimilar volumes lead procurement today; reference product positioning is eroding fastest among new patient starts.
Application:
Clinical indication expansion determines addressable patient pools, with gastroenterology protocols scaling faster than rheumatology conversion rates.
- Crohn's Disease:Gastroenterology clinics in South Korea and Germany are scaling biologic therapy access protocols, with CD and IBD treatment centers driving concentrated demand growth. Hospital infusion requirements and monitoring infrastructure concentrate procurement through integrated delivery networks.
- Inflammatory Bowel Disease:IBD encompasses ulcerative colitis and Crohn's presentations, with biologic penetration expanding beyond academic medical centers into community gastroenterology practices. FDA interchangeable designation requirements for switching studies reshape evidentiary investment priorities.
- Rheumatoid Arthritis:The original approved indication where biosimilar penetration is deepest, though stable patient switching resistance persists.
- Psoriasis:Dermatology biologic protocols favor IL-17 and IL-23 inhibitors, limiting adalimumab share in this application.
Crohn's Disease anchors current volumes; Inflammatory Bowel Disease is climbing the fastest as clinic infrastructure expands.
End User:
Site-of-care regulations and reimbursement differentials concentrate purchasing authority across distinct institutional types.
- Hospitals:Academic medical centers and community hospital systems manage rheumatology department budgets under IRA Medicare price negotiation benchmarks, with group purchasing organizations centralizing biologic procurement decisions in Texas and Bavaria.
- Clinics:Gastroenterology and rheumatology specialty clinics in South Korea operate under national health insurance biologic substitution protocols that accelerate biosimilar conversion versus US state-level heterogeneity.
- Pharmacies:Retail and specialty pharmacy channels face divergent automatic substitution authority across US state lines.
- Research Institutions:Clinical trial sites and academic research centers maintain separate procurement for investigator-initiated studies.
Hospitals dominate procurement value today; Clinics are gaining share fastest as site-of-care shifts accelerate.
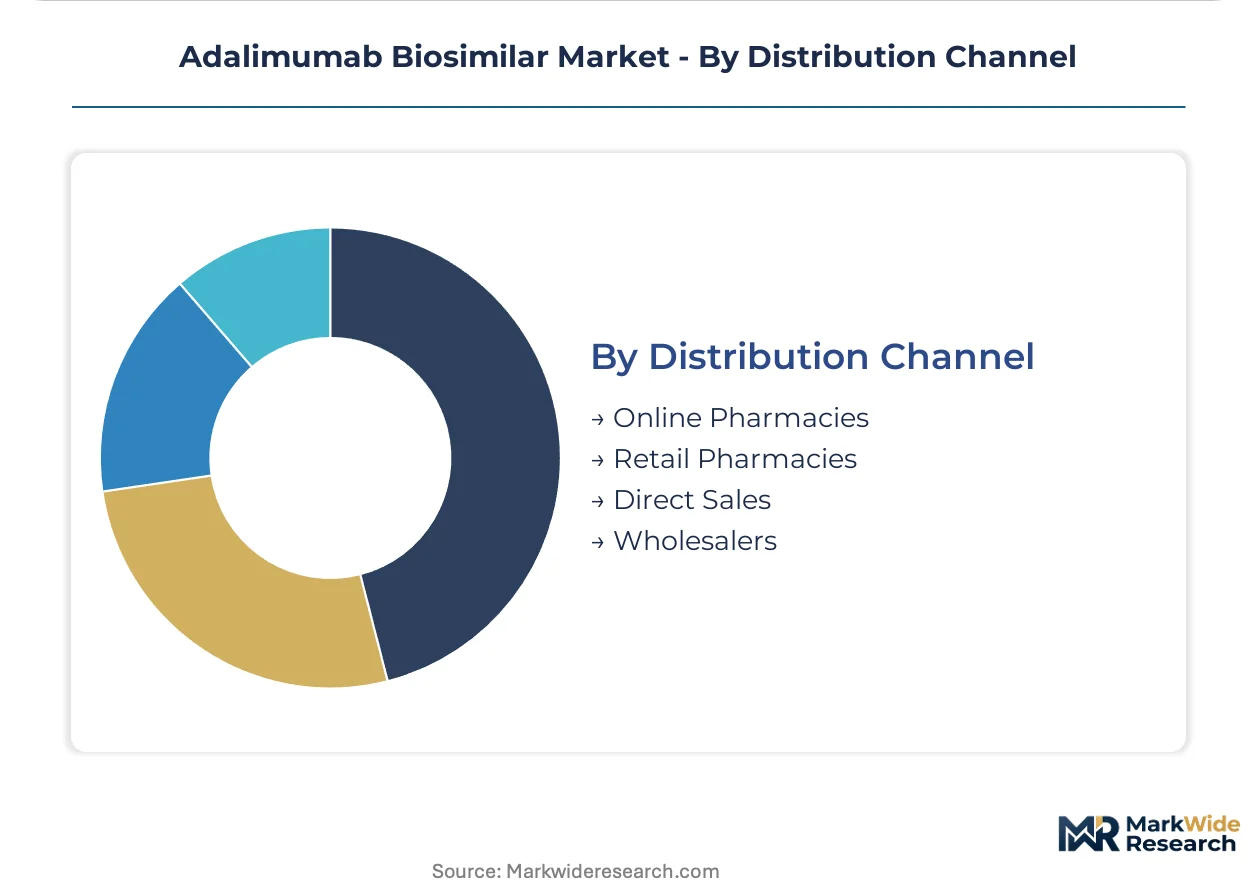
Distribution Channel:
Cold chain requirements and patient support program integration favor direct manufacturer-to-provider relationships over traditional wholesale.
- Direct Sales:Pfizer and Amgen deploy integrated distribution networks reaching hospital and clinic end users directly, bypassing wholesale markups while capturing utilization data for contracting negotiations.
- Wholesalers:McKesson and AmerisourceBergen maintain positions in independent pharmacy and smaller hospital system supply chains where direct infrastructure investment is uneconomical.
- Online Pharmacies:Mail-order channels expand in US commercial plans with patient cost-sharing designs favoring 90-day supplies.
- Retail Pharmacies:CVS, Walgreens, and independent pharmacies face state-level substitution law fragmentation that complicates inventory positioning.
Direct Sales commands the largest value flow today; Online Pharmacies are expanding most quickly as plan designs evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The adalimumab biosimilar industry traces its commercial scale to AbbVie's Humira launch in the early 2000s, with European and South Korean manufacturers pioneering the first wave of biosimilar development following the EU's 2005 biosimilar framework.
United States
Hospital procurement consolidation through group purchasing organizations accelerates biosimilar uptake in Texas and Massachusetts academic medical centers. The FDA's interchangeable designation pathway and IRA Medicare price negotiation create direct substitution incentives for rheumatology department budgets. Boston's biopharma corridor concentrates manufacturing expertise and payer policy development.
Germany
Gastroenterology clinics in Bavaria scale biologic therapy access protocols for Crohn's Disease and Inflammatory Bowel Disease patients. The EU Green Deal's pharmaceutical sustainability criteria pivots procurement standards across European hospital networks. Munich and Heidelberg anchor manufacturing clusters where single-use bioreactor adoption enables rapid product changeovers.
South Korea
National health insurance biologic substitution protocols accelerate biosimilar conversion faster than US state-level heterogeneity permits. The MFDS streamlined approval pathways compress market entry timelines for domestic manufacturers. Seoul's Songdo Biocluster concentrates mammalian cell culture capacity and contract manufacturing infrastructure.
India
CDSCO approval pathways and government hospital procurement expansion create first-mover positioning for biosimilar entrants targeting underpenetrated gastroenterology markets. Maharashtra and Gujarat host manufacturing zones where mid-scale CDMOs serve emerging market tender demand. Mumbai-based research institutions anchor immunogenicity surveillance capabilities.
United Kingdom
NHS England's biosimilar adoption targets drive formulary conversion in London and Manchester rheumatology departments. The MHRA post-Brexit regulatory autonomy enables accelerated approval timelines for EMA-aligned dossiers. The Golden Triangle research corridor maintains clinical trial infrastructure for switching studies.
Adalimumab Biosimilar Market Vendor Landscape
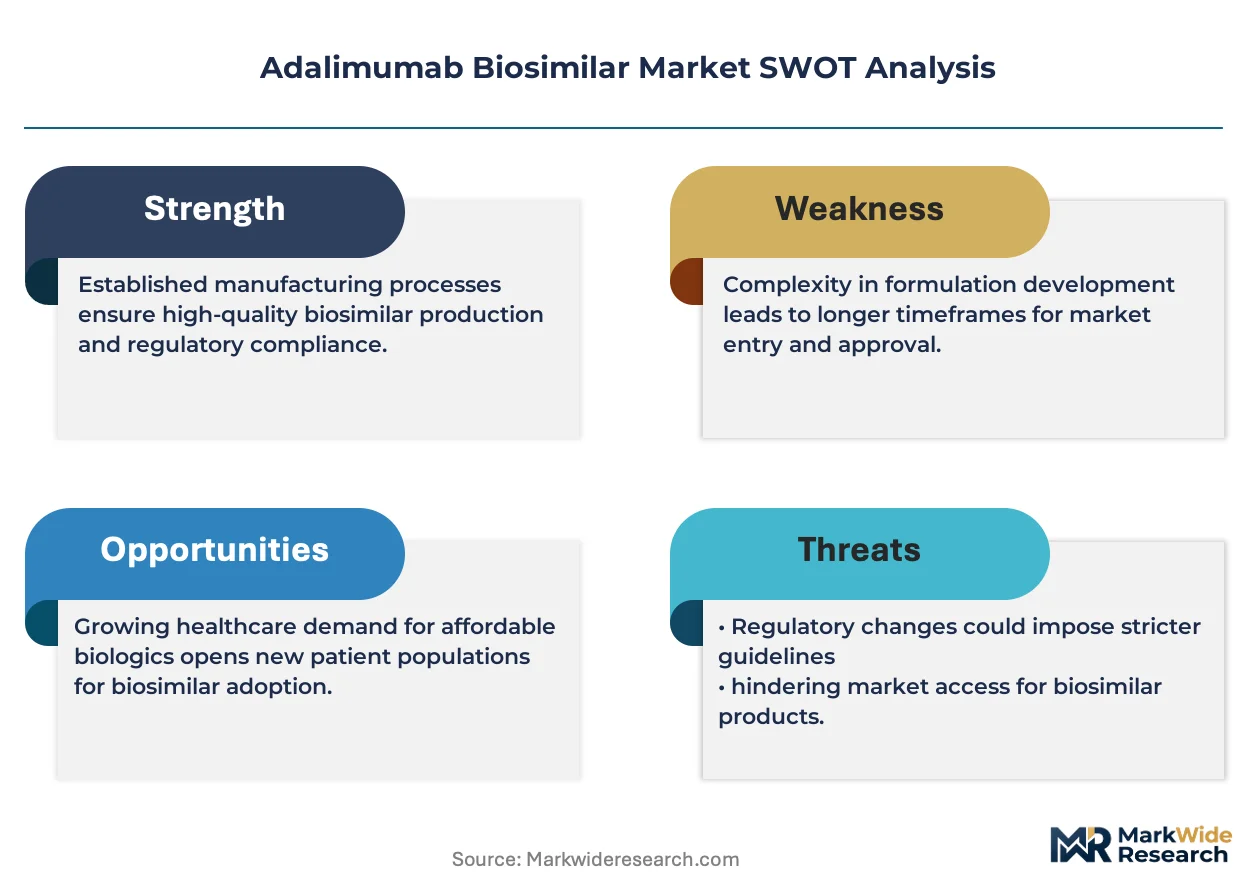
Capital-heavy producers compete with asset-light designers as the defining structural tension in adalimumab biosimilars. Integrated biopharmaceutical conglomerates with captive manufacturing infrastructure face pressure from specialist biosimilar developers outsourcing production to contract manufacturers. Three archetypes dominate: originator legacy players defending residual market share, full-stack biopharma companies with distribution networks, and pure-play biosimilar specialists leveraging regulatory expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing bioreactor access through multi-year CDMO agreements.
Among US-based biopharma conglomerates, Amgen Inc. and Pfizer occupy positions as scale-driven suppliers with integrated distribution reaching hospital and clinic end users directly. South Korean specialists Samsung Bioepis and Celltrion, Inc. exemplify the regulatory-first archetype, leveraging MFDS streamlined pathways and WHO prequalification to access emerging market tenders. Sandoz, as the generics division of a Swiss pharmaceutical group, represents the European biosimilar specialist model with established hospital procurement relationships across German and UK networks.
| Leading Market Players |
|---|
| Amgen Inc. |
| Pfizer |
| Sandoz |
| Celltrion, Inc. |
| Boehringer Ingelheim |
| Samsung Bioepis |
| Coherus Biosciences |
| Fresenius Kabi |
| Zydus Cadila |
| Others |
Supply Flow & Price Mechanics
Single-use bioreactor adoption at 2,000-5,000 liter scales simultaneously compresses capital deployment thresholds and fragments manufacturing concentration across German and South Korean contract manufacturing networks. This shift enables mid-scale CDMOs to undercut originator economies-of-scale while absorbing procurement volume from hospital group purchasing organizations.
Pricing Analysis
Three-tier pricing structure across interchangeability-designated, biosimilar-approved, and reference-originator levels stratifies procurement decisions in United States academic medical centers. Price differentiation hinges on FDA interchangeability certification and volume commitment scale under IRA Medicare price negotiation benchmarks. Cost compression in standard-tier biosimilars is intensifying because hospital formulary committees prioritize automatic substitution authority. Rheumatology departments in Texas and Massachusetts exhibit highest price sensitivity due to budget caps; gastroenterology clinics in South Korea show lowest sensitivity where national health insurance shields patient cost exposure.
Supply Chain Analysis
WHO prequalification and EMA biosimilar comparability certification gate access to European hospital tenders and African multi-year supply contracts. Mammalian cell culture media and specialized bioreactor components concentrate among Korean and German suppliers, creating single-source vulnerability for 10,000-liter scale manufacturers. Distribution runs through direct manufacturer-to-provider networks anchored by Pfizer and Amgen, bypassing wholesale markups while capturing utilization data for contracting negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adalimumab biosimilar market reads as a late-cycle quality story where gastroenterology clinic expansion toward Crohn's Disease and Inflammatory Bowel Disease protocols rewards manufacturers with robust immunogenicity datasets.
For Market Incumbents: Hedge against originator rebate erosion by securing captive bioreactor capacity through multi-year CDMO agreements in Seoul's Songdo Biocluster and Munich manufacturing zones. Prioritize FDA interchangeability designation investment to defend formulary positioning against emerging pure-play biosimilar specialists leveraging regulatory-first entry strategies. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer lowest-friction entry into underpenetrated Indian gastroenterology markets where CDSCO approval pathways and government hospital procurement expansion concentrate first-mover rewards. Target WHO prequalification to access African and Southeast Asian tender markets with multi-year supply contract visibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale CDMOs with disposable bioreactor infrastructure and EMA-aligned quality systems. Long-term viability hinges on manufacturers achieving FDA interchangeability status and securing integrated delivery network contracts. Watch for IRA Medicare price negotiation benchmark publication as inflection indicator for hospital formulary conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | 10,000-liter bioreactor deployment in Seoul and Munich anchors supply security for hospital GPO contracts. |
| Regulatory Approval Pathway | FDA interchangeable designation accelerates automatic substitution authority in Texas and Massachusetts rheumatology departments. |
| Backward Integration | In-house mammalian cell culture media production reduces Korean supplier concentration risk for mid-cap manufacturers. |
| Hospital System Partnership | Direct distribution agreements with Bavarian integrated delivery networks bypass wholesale markups and capture utilization data. |
| Pipeline Diversification | Extrapolation to Inflammatory Bowel Disease indications beyond rheumatoid arthritis expands addressable patient pools under EMA guidelines. |
Methodological Framework
Multiple input streams — formulary database audits, FDA and EMA regulatory filing reviews, and hospital procurement contract analysis — were reconciled with primary interviews across drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from ClinicalTrials.gov switching study registries, CMS Medicare Part B spending data, and EU Green Deal pharmaceutical sustainability criteria documentation. Bottom-up patient population modeling and top-down market sizing triangulation anchored volume estimates.
Historical biosimilar adoption curves in rheumatology and gastroenterology were cross-referenced against expert panel assessments of IRA Medicare price negotiation implementation pace across the analysis window. Segmentation dimensions modeled include product type, clinical indication, end-user institution category, and regional regulatory cluster. CAGRs were derived from patient population growth, biologic therapy penetration rates, and payer substitution policy evolution throughout the forecast period.
Originator patent litigation outcomes, state-level pharmacy substitution law amendments, and bioprocess engineer availability in Basel-Boston-Seoul corridors are the dominant revision risks to modeled forecasts. A model refresh is warranted upon material change in FDA interchangeable designation approval velocity or IRA Medicare price negotiation benchmark publication timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Immunology Biosimilars Market
Biosimilars
Global Biosimilars Market
Biosimilars
Imatinib Drug Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
US Biosimilars Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Biosimilar Testing Services Market