
 Amphotericin B Market | 2026-2036
Amphotericin B Market Size, Share, and Industry Trends Forecast 2026-2036
Amphotericin B Market Analysis
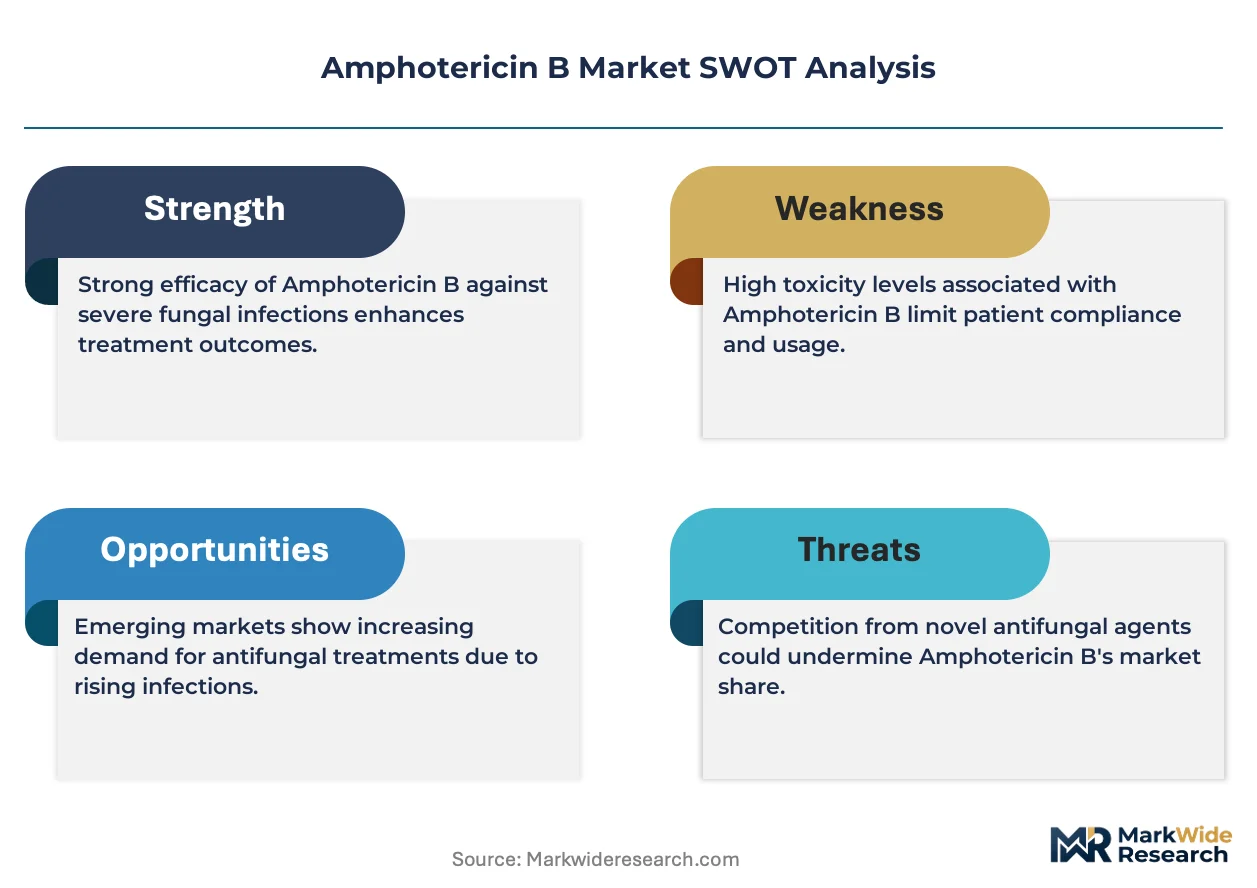
Skilled formulation scientists capable of liposomal encapsulation is collapsing across contract manufacturing organizations, tightening capacity for complex parenteral production. Gilead Sciences leverages decades of liposomal expertise to sustain dominance in high-margin hospital segments. Pfizer anchors North American supply chains through vertically integrated sterile manufacturing networks. Nanomerics differentiates through proprietary nanotechnology platforms targeting next-generation micelle formulations.
Amphotericin B is a polyene macrolide antifungal agent derived from Streptomyces nodosus, functioning through ergosterol binding in fungal cell membranes to induce pore formation and osmotic lysis. The compound requires intravenous administration due to negligible oral bioavailability, with liposomal encapsulation reducing nephrotoxicity compared to conventional deoxycholate suspensions. Liposomal formulation captures the dominant margin pool among product types, while micelles represent the fastest-growing category as nanotechnology platforms advance toward regulatory submission. Hospital end users command the largest volume share, though specialty pharmacies are gaining traction for outpatient antifungal stewardship programs requiring extended infusion monitoring.
FDA sterility guidelines and EMA Good Manufacturing Practice standards for parenteral antifungals enforce rigorous endotoxin limits and liposomal stability testing, elevating compliance costs while consolidating market access among validated manufacturers. The WHO Essential Medicines List inclusion for cryptococcal meningitis and leishmaniasis drives procurement through national health programs, particularly in endemic regions. Stakeholders must monitor evolving pharmacoeconomic evidence comparing liposomal versus conventional therapy in resource-limited settings, as payer formularies increasingly condition reimbursement on mortality and nephrotoxicity endpoints rather than acquisition cost alone.
Market Dynamics
Formulation science scarcity across contract manufacturing organizations is compressing liposomal production capacity, forcing hospital procurement toward validated suppliers with captive encapsulation expertise.
Growth Catalysts
- WHO Essential Medicines List inclusion:Cryptococcal meningitis and leishmaniasis designations drive national health program procurement in endemic regions, particularly India and Brazil.
- FDA sterility guideline tightening:Enhanced endotoxin limits and liposomal stability testing requirements consolidate market access among manufacturers with validated sterile injectable infrastructure.
- India hospital infrastructure expansion:Government leishmaniasis elimination programs and tertiary care network growth accelerate volume uptake of deoxycholate and liposomal variants.
Market Restraints
- Phospholipid input cost volatility:Hydrogenated soy phosphatidylcholine supply concentrates among Chinese and Indian chemical intermediates suppliers, exposing formulation costs to agricultural commodity swings.
- Nephrotoxicity liability in conventional formulations:Deoxycholate suspensions require intensive renal monitoring, limiting their deployment in outpatient settings and resource-constrained facilities without laboratory infrastructure.
- Single-source dependence for liposomal expertise:Gilead Sciences' decades-long accumulation of encapsulation know-how creates supply concentration risk for hospital formularies dependent on AmBisome.
Strategic Opportunities
- Micelle nanotechnology convergence:Polymeric micelle platforms combining amphiphilic block copolymers with active targeting ligands offer renal-sparing profiles without liposomal manufacturing complexity.
- Specialty pharmacy channel emergence:Outpatient antifungal stewardship programs requiring extended infusion monitoring create new distribution pathways beyond hospital captive pharmacies.
- CDSCO accelerated approval pathway:India's streamlined review for essential medicines enables faster market entry for liposomal generics targeting government procurement tenders.
Industry Challenges
- Formulation scientist talent collapse:Liposomal encapsulation expertise concentrates among retiring cohorts at legacy pharmaceutical manufacturers, constraining technology transfer to contract development organizations.
- Sterile manufacturing capex intensity:EMA Good Manufacturing Practice compliance for parenteral antifungals demands isolated filling lines and continuous particle monitoring systems requiring eight-figure capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphotericin B Market |
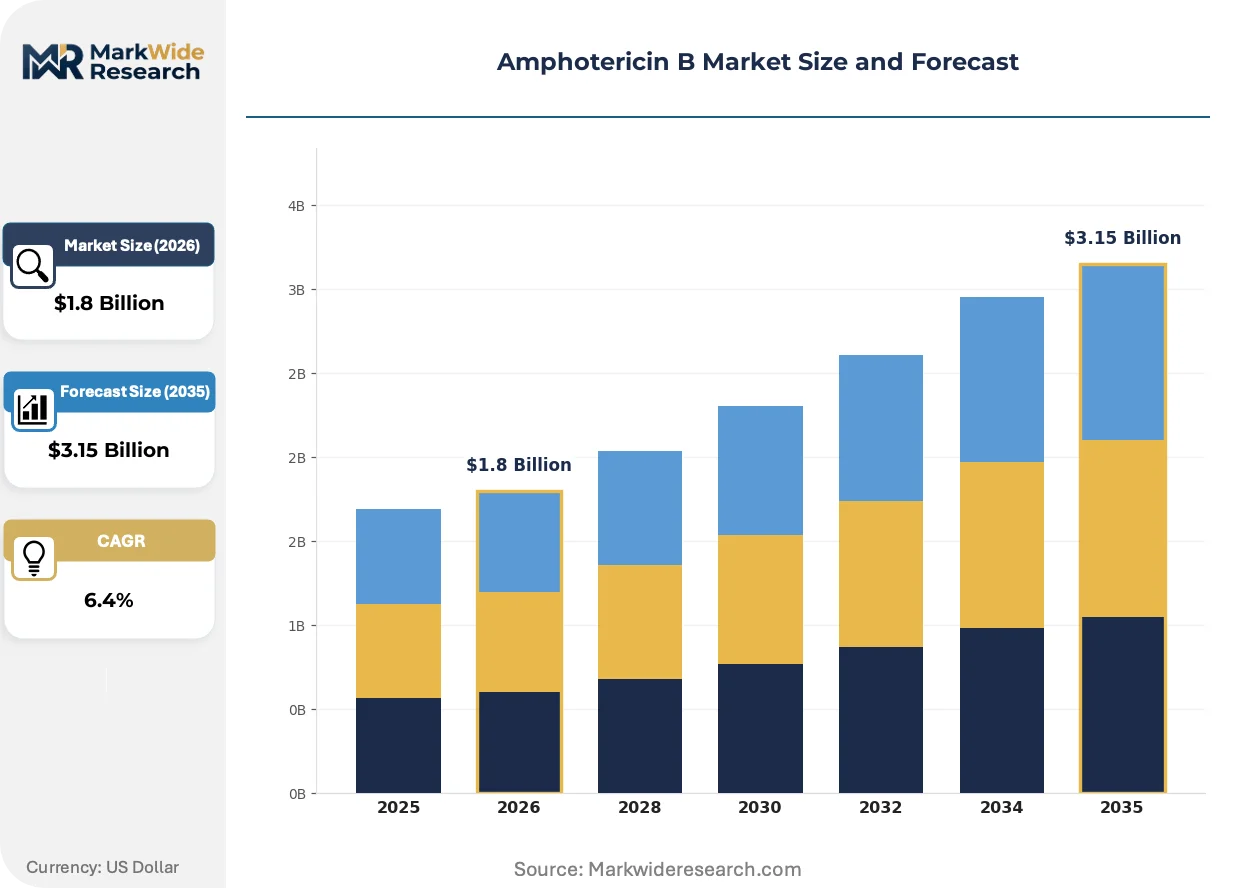
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Liposomal Formulation, Deoxycholate, Micelles Therapy Area: Fungal Infections, Cryptococcal Meningitis, Leishmaniasis, Aspergillosis End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Distribution Channel: Direct Sales, E-commerce, Wholesalers, Pharmacies |
| Companies Covered | Shanghai Pharmaceuticals New Asia Pharmaceutical, Nanomerics, Gilead Sciences, Astellas Pharma, DNDI, CSPC Pharmaceutical Group, Jemincare, Pfizer, North China Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphotericin B Market Emerging Trajectories
Encapsulation technologies are fragmenting competitive advantage away from chemical synthesis toward complex drug delivery engineering, with nanoscale formulation platforms determining clinical differentiation and procurement preference.
Nanomerics' proprietary molecular envelope technology is displacing conventional liposomal architectures in preclinical development pipelines. European research hospitals and biodefense procurement programs are piloting these micelle formulations for systemic fungal infections. The shift compresses reliance on phospholipid supply chains while enabling room-temperature stability profiles that liposomal suspensions cannot match.
EMA's revised Good Manufacturing Practice Annex 1 for sterile medicinal products mandates continuous environmental monitoring and barrier isolation technology for all new parenteral antifungal facilities. This elevates compliance capital requirements beyond mid-tier manufacturer reach. Liposomal Amphotericin B suppliers with existing validated infrastructure are absorbing market share from competitors facing facility reconstruction timelines.
Hospital pharmacy committees are conditioning formulary inclusion on pharmacoeconomic models incorporating nephrotoxicity-related length-of-stay costs rather than acquisition price alone. This behavioral pivot favors liposomal over deoxycholate variants in United States academic medical centers and United Kingdom NHS trusts. Specialty pharmacy networks are capturing outpatient continuation therapy volumes previously managed through hospital infusion centers, fragmenting traditional distribution relationships.
Amphotericin B Market Segmentation
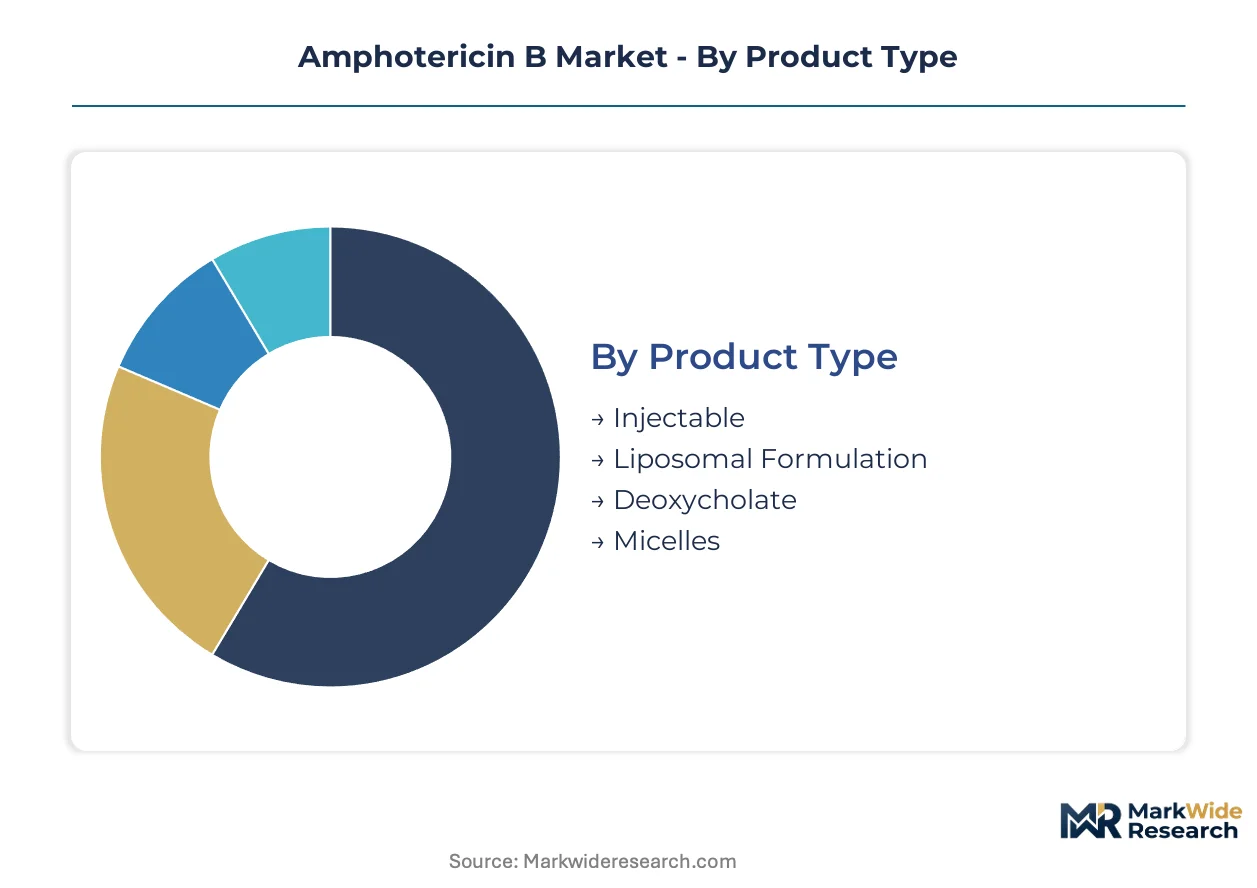
Formulation complexity and route of administration dictate procurement patterns across therapeutic settings. Segmentation reveals how liposomal engineering concentrates margin capture while conventional formulations serve volume markets in endemic disease regions.
Product Type:
Domestic production dominates deoxycholate and conventional injectable supply chains in India and Brazil, while liposomal formulations rely on import-dependent distribution networks in most markets outside North America and Europe.
- Liposomal Formulation:Phospholipid bilayer encapsulation reduces nephrotoxicity through altered biodistribution, concentrating renal-sparing demand in United States academic medical centers and United Kingdom NHS trusts with formulary committees weighing pharmacoeconomic models. Procurement contracts favor validated sterile manufacturing infrastructure.
- Deoxycholate:Conventional colloidal suspension maintains cost advantage for government leishmaniasis programs in India and Brazil, though intensive renal monitoring requirements restrict deployment to tertiary facilities with laboratory infrastructure. Volume concentrates in endemic regions with established WHO procurement channels.
- Injectable:Unencapsulated parenteral solutions serve niche compounding pharmacies and veterinary applications with limited regulatory oversight.
- Micelles:Polymeric amphiphilic block copolymer platforms enable room-temperature stability without phospholipid supply chain exposure, attracting European biodefense procurement and research hospital pilot programs.
Liposomal Formulation holds the largest share; momentum sits with Micelles.
Therapy Area:
Cost tier stratification separates prophylactic fungal coverage from curative protocols for life-threatening systemic infections, with reimbursement intensity varying across indication severity.
- Fungal Infections:Broad-spectrum coverage against Candida and endemic mycoses drives hospital formulary placement, with liposomal variants preferred for neutropenic patients in hematology-oncology units where nephrotoxicity avoidance justifies premium positioning.
- Cryptococcal Meningitis:WHO Essential Medicines List designation channels procurement through national health programs in sub-Saharan Africa and Southeast Asia, with induction therapy protocols specifying liposomal or deoxycholate based on renal function monitoring capacity.
- Leishmaniasis:Visceral and cutaneous forms drive volume in India's elimination program infrastructure and Brazil's endemic regions, with deoxycholate dominating government tenders despite liposomal availability for refractory cases.
- Aspergillosis:Invasive pulmonary and disseminated presentations in transplant recipients and hematologic malignancy patients concentrate in tertiary referral centers with antifungal stewardship programs.
Fungal Infections commands the dominant position; Cryptococcal Meningitis is climbing the fastest on Essential Medicines List procurement expansion.
End User:
Customer type fragmentation reflects the infusion monitoring requirements inherent to nephrotoxicity management, separating captive hospital pharmacy control from emerging ambulatory pathways.
- Hospitals:Tertiary care centers with sterile compounding capabilities and continuous renal monitoring infrastructure anchor procurement volume, particularly academic medical centers with antifungal stewardship committees.
- Specialty Pharmacies:Outpatient infusion centers with extended monitoring protocols capture continuation therapy previously managed through hospital discharge, fragmenting traditional distribution relationships in United States markets.
- Clinics:Limited to leishmaniasis treatment programs in endemic regions with established laboratory infrastructure for renal function surveillance.
- Homecare:Restricted to stable patients with established tolerance and caregiver training for infusion pump management in select European reimbursement environments.
Hospitals retain volume leadership; Specialty Pharmacies are gaining share fastest on ambulatory reimbursement shifts.
Distribution Channel:
Supply concentration in sterile manufacturing creates direct sales dominance for liposomal formulations, while conventional products fragment through wholesale intermediaries.
- Direct Sales:Manufacturer-to-hospital contracts for liposomal formulations bypass wholesale markup, reflecting sterile injectable cold chain requirements and GMP compliance documentation needs.
- Wholesalers:Three-tier distribution serves deoxycholate and conventional injectable volume in India and Brazil, with national health program tenders routing through government-authorized pharmaceutical distributors.
- Pharmacies:Retail channel captures limited outpatient prescription volume where oral azole step-down therapy fails or intolerance develops.
- E-commerce:Veterinary and research chemical supply constitutes primary volume, with human pharmaceutical sales restricted by prescription requirements and cold chain logistics.
Direct Sales captures the dominant margin pool; Wholesalers anchor volume in endemic disease markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between hospital-centric markets prioritizing nephrotoxicity reduction and endemic-disease regions optimizing procurement cost. The United States and Western Europe concentrate liposomal formulation demand through academic medical centers with antifungal stewardship committees. India and Brazil anchor deoxycholate volume through government leishmaniasis elimination infrastructure.
United States
Academic medical centers in Boston and New York Metro drive liposomal formulation procurement through pharmacoeconomic models weighting nephrotoxicity-related length-of-stay costs. FDA sterility guideline tightening for parenteral antifungals consolidates supply access among validated sterile injectable manufacturers. The Philadelphia corridor hosts concentrated hospital pharmacy committee decision-making for formulary placement.
Germany
EMA Good Manufacturing Practice Annex 1 compliance mandates for sterile medicinal products elevate capital requirements for new parenteral antifungal facilities. The Rhine-Main cluster around Frankfurt anchors hospital procurement networks for liposomal formulations. Bavaria's research hospitals pilot micelle nanotechnology platforms through European biodefense procurement programs.
India
Government leishmaniasis elimination programs and tertiary care network expansion accelerate deoxycholate and liposomal variant uptake across Maharashtra and Gujarat. CDSCO accelerated approval pathways for essential medicines enable faster market entry for liposomal generics targeting government tenders. The Delhi-NCR corridor concentrates hospital infrastructure procurement decision-making.
Brazil
ANVISA regulatory frameworks for sterile injectables shape import-dependent distribution networks for liposomal formulations while domestic production serves deoxycholate demand. Endemic visceral leishmaniasis regions in Minas Gerais and Bahia drive volume through national health program channels. São Paulo's tertiary referral centers anchor antifungal stewardship program implementation.
United Kingdom
NHS trust formulary committees condition liposomal inclusion on mortality and nephrotoxicity endpoints rather than acquisition cost alone. The London-Southeast corridor concentrates hospital pharmacy procurement for hematology-oncology units. MHRA compliance with EMA sterile manufacturing standards filters supplier access for parenteral antifungal tenders.
Amphotericin B Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Amphotericin B market. Liposomal encapsulation expertise concentrates among legacy pharmaceutical manufacturers with decades of sterile injectable infrastructure. Three archetypes define competitive positioning: integrated leaders with captive manufacturing networks, nanotechnology specialists pursuing next-generation micelle platforms, and regional generics suppliers serving government procurement tenders. Dominant competitive moves include sterile manufacturing capacity expansion and strategic technology licensing for advanced encapsulation platforms.
Within the integrated leader tier, Gilead Sciences and Pfizer exemplify manufacturers with validated liposomal production infrastructure and hospital direct sales networks. Nanomerics occupies a specialist position representing nanotechnology platform developers targeting micelle formulations with room-temperature stability profiles. Among Asia-Pacific suppliers, Shanghai Pharmaceuticals New Asia Pharmaceutical and CSPC Pharmaceutical Group anchor regional generic production for government tender markets.
| Leading Market Players |
|---|
| Shanghai Pharmaceuticals New Asia Pharmaceutical |
| Nanomerics |
| Gilead Sciences |
| Astellas Pharma |
| DNDI |
| CSPC Pharmaceutical Group |
| Jemincare |
| Pfizer |
| North China Pharmaceutical |
| Others |
Supply Flow & Price Mechanics
Polymeric micelle platforms displacing phospholipid-dependent liposomal architectures are simultaneously shifting procurement geography toward European nanotechnology developers and compressing raw material exposure to agricultural commodity cycles. This substitution dynamic fragments traditional pricing power concentrated among legacy encapsulation specialists while opening margin capture for room-temperature stable formulations.
Pricing Analysis
Long-term offtake contracts dominate liposomal formulation procurement between validated manufacturers and hospital pharmacy committees, with spot purchasing limited to emergency deoxycholate volumes in endemic disease programs. Three-tier pricing structure across liposomal premium, deoxycholate standard, and micelle economy levels reflects nephrotoxicity risk profiles and sterile manufacturing compliance intensity. Cost compression in conventional deoxycholate tiers is intensifying because government tender mechanisms in India and Brazil prioritize acquisition price over length-of-stay economics. Government health programs exhibit highest price sensitivity, while United States academic medical centers with antifungal stewardship committees demonstrate lowest sensitivity due to pharmacoeconomic modeling of renal-sparing outcomes.
Supply Chain Analysis
Inventory buffers for hydrogenated soy phosphatidylcholine stretch to six months given agricultural commodity volatility and geographic concentration of chemical intermediate suppliers. Liposomal formulation supply concentrates in United States and European sterile manufacturing facilities, while deoxycholate production localizes in India and Brazil for government tender fulfillment. Raw material dependencies span phospholipid inputs, hydrogenated soy derivatives, and amphiphilic block copolymers for next-generation platforms. Single-source vulnerability for liposomal encapsulation expertise creates supply concentration risk. Distribution runs through direct manufacturer-to-hospital contracts for sterile injectables, with wholesale intermediaries serving conventional formulation volume in endemic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Amphotericin B market functions as a regulatory entrenchment story, where FDA sterility guidelines and EMA Good Manufacturing Practice standards create formidable compliance moats protecting validated sterile injectable infrastructure. Switching costs for hospital formularies dependent on established liposomal supply relationships reinforce incumbent positioning.
For Market Incumbents: Consolidate sterile manufacturing capacity through targeted facility upgrades in United States and European corridors where EMA Annex 1 compliance timelines filter competitor entry. Deepen backward integration into phospholipid supply chains to buffer hydrogenated soy phosphatidylcholine commodity volatility threatening margin stability. Channel control through direct hospital sales relationships defends against specialty pharmacy fragmentation of outpatient continuation therapy volumes. For New Entrants and Emerging Players: CDSCO accelerated approval pathway for essential medicines offers fastest regulatory trajectory for liposomal generics targeting Indian government leishmaniasis tenders. Brazil's ANVISA frameworks for sterile injectables present secondary entry corridor for import-dependent liposomal distribution networks. Research hospital pilot programs in Bavaria and biodefense procurement channels provide go-to-market validation for polymeric micelle platforms before commercial scale-up. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations possessing liposomal encapsulation expertise but lacking hospital direct sales infrastructure. Five-to-ten year viability hinges on successful technology transfer from retiring formulation scientist cohorts to next-generation development organizations. Watch for CDSCO approval announcements for liposomal generics as inflection signal for pricing compression in Indian tender markets.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO accelerated review enables faster market entry for essential medicine generics in India. |
| Manufacturing Scale-Up | EMA Annex 1 compliance investments filter sterile injectable capacity to validated facility operators. |
| Licensing Agreement | Micelle platform technology licensing fragments phospholipid supply chain dependence for European developers. |
| Long-term Supply Agreement | Direct hospital contracts bypass wholesale markup and secure formulary placement through GMP documentation. |
| Pipeline Diversification | Polymeric micelle development reduces nephrotoxicity liability without liposomal manufacturing complexity. |
Methodological Framework
Desk research of FDA sterility guideline filings, EMA GMP inspection reports, and WHO Essential Medicines List procurement databases preceded structured interviews with hospital pharmacy directors, sterile manufacturing plant managers, and national health program procurement officers. Secondary validation drew from CDSCO approval records, ANVISA regulatory frameworks, and customs trade data for phospholipid chemical intermediates. Bottom-up volume estimates from hospital formulary placement data triangulated against top-down market sizing from national health program tender disclosures.
Variance decomposition across formulation type, therapy area severity, and end-user channel dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured liposomal versus deoxycholate versus micelle platform splits, with CAGRs derived from pharmacoeconomic adoption curves in academic medical centers and government procurement volume trends in endemic regions. Forecast inputs incorporated EMA facility compliance timelines, CDSCO approval velocity, and phospholipid commodity price elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained FDA sterility guideline enforcement or accelerated CDSCO review pathways would require recalibration. Forecasts reflect documented assumptions regarding hospital infrastructure expansion rates and formulation scientist talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market