
 Fusion Biopsy Market | 2026-2036
Fusion Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Fusion Biopsy Market Intelligence
FDA 510(k) clearance requirements for MRI-ultrasound fusion devices is shifting the cost-of-entry calculus toward vendors with substantial clinical validation budgets. Koninklijke Philips N.V. leverages its installed base of MRI systems to bundle fusion software with hardware contracts. GE HealthCare sustains R&D intensity across both imaging modalities and targeting algorithms. KOELIS anchors its position through proprietary organ-tracking mechanics that reduce registration error.
Fusion biopsy combines multiparametric MRI lesion coordinates with real-time ultrasound via software registration, typically achieving spatial accuracy below 2.5 millimeters for targeted core sampling; its primary purpose is to improve cancer detection rates while reducing unnecessary tissue cores in prostate diagnostics. MRI-guided technology leads in precision metrics but robotic-assisted systems capture the fastest expansion as urologists seek standardized hand motion compensation. Needle biopsy dominates procedure volume, though vacuum-assisted instruments command premium placement in academic medical centers where larger tissue specimens support genomic profiling.
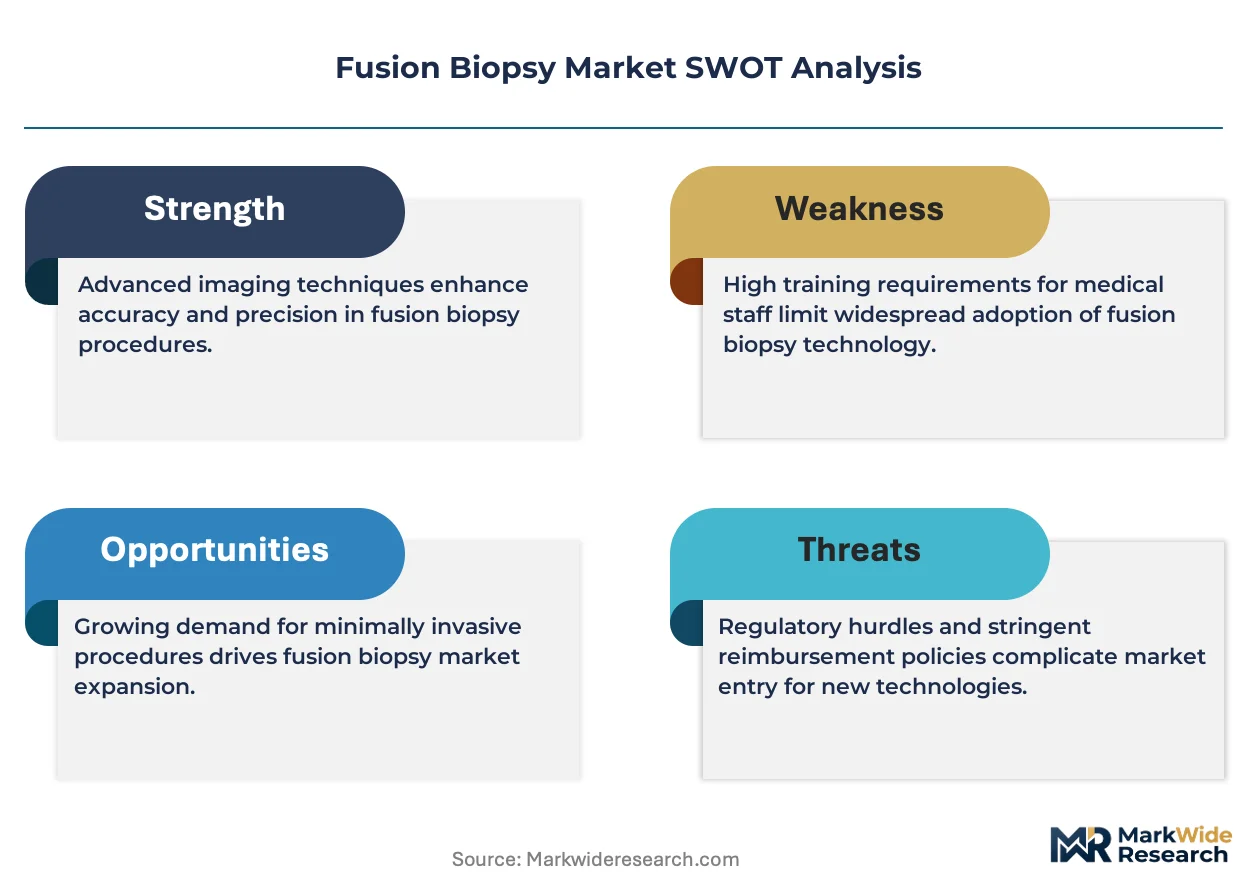
FDA software-as-a-medical-device frameworks and EU MDR Class IIa classification requirements jointly determine which fusion platforms achieve commercial access in their respective jurisdictions, with European notified bodies demanding more extensive clinical performance documentation since MDR implementation. Stakeholders must monitor how reimbursement authorities in Germany, Japan, and the United States differentially value targeted versus systematic biopsy pathways when allocating limited interventional radiology capacity.
Market Dynamics
The transition from systematic 12-core biopsy protocols to MRI-ultrasound fusion targeting is compressing procedure volumes while elevating per-case value capture for vendors with validated registration algorithms.
Growth Catalysts
- CMS reimbursement realignment:Medicare coverage decisions in the United States now favor targeted biopsy approaches, redirecting interventional urology capacity toward fusion platforms.
- Multiparametric MRI diffusion:Radiological infrastructure expansion in hospital systems creates downstream demand for compatible fusion software and needle guidance systems.
- Prostate cancer screening protocol updates:Clinical guideline revisions emphasizing precision localization are accelerating urology department procurement cycles for fusion-capable equipment.
Market Restraints
- Capital equipment intensity:Fusion biopsy requires coordinated MRI, ultrasound, and software investments that strain capital budgets at community hospital systems.
- Specialized operator dependency:Procedure success hinges on radiologist-urologist coordination, creating throughput bottlenecks where interventional radiology capacity is constrained.
- Reimbursement fragmentation:Private payor coverage for fusion biopsy varies across United States state markets, generating administrative burden and payment uncertainty.
Strategic Opportunities
- Outpatient ambulatory surgical centers:Freestanding urology clinics in the United States represent underpenetrated deployment sites for compact fusion systems with streamlined workflows.
- AI-enabled organ tracking:Machine learning convergence with electromagnetic tracking is opening software-only regulatory pathways that reduce hardware dependency.
- Japan's aging-screening infrastructure:METI-supported precision medicine initiatives are creating procurement incentives for prostate MRI fusion platforms in tertiary hospitals.
Industry Challenges
- Cross-modality calibration expertise:Fusion accuracy depends on MRI-ultrasound registration specialists whose training pipelines remain underdeveloped outside academic medical centers.
- Legacy ultrasound retrofit complexity:Integration with installed base equipment requires customized electromagnetic sensor mounting and software bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusion Biopsy Market |
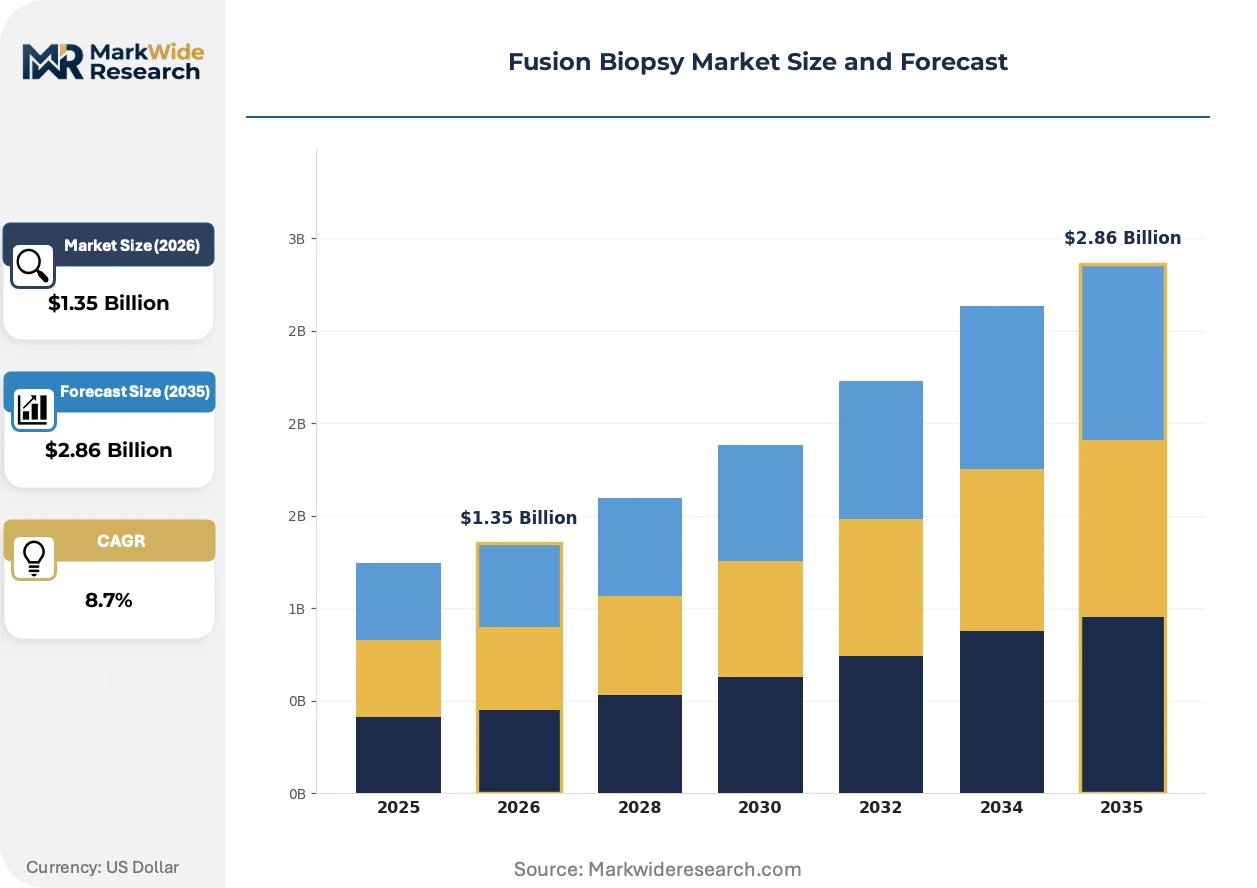
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Vacuum-Assisted Biopsy, Core Biopsy, Fine Needle Aspiration Technology: Ultrasound-Guided, MRI-Guided, CT-Guided, Robotic-Assisted End User: Hospitals, Diagnostic Laboratories, Cancer Centers, Outpatient Clinics Application: Prostate Cancer, Breast Cancer, Lung Cancer, Liver Cancer |
| Companies Covered | Eigen, BK Medical Holding Company, Inc., Koninklijke Philips N.V., ESAOTE SPA, Focal Healthcare, GE HealthCare, Hitachi Ltd., MedCom, KOELIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusion Biopsy Market Strategic Shifts & Innovations
Software-defined targeting is displacing hardware-centric differentiation across the fusion biopsy value chain, compressing development cycles and opening modular entry points for algorithm-focused vendors.
Deep learning-based organ deformation tracking is rewriting how fusion systems compensate for prostate motion during needle insertion. Academic medical centers in the United States are piloting these algorithms to reduce registration error below one millimeter. This capability is compressing the performance gap between robotic-assisted and manual fusion platforms.
EU MDR Class IIa clinical performance documentation requirements are extending certification timelines for fusion software vendors seeking European commercial access. Notified bodies now demand prospective validation studies that exceed prior CE marking thresholds. Vendors with existing FDA 510(k) clearances are leveraging that clinical package to accelerate MDR submissions.
Service unbundling is fragmenting how hospital systems acquire fusion capability. Procurement teams increasingly separate software licensing from hardware capital expenditure, favoring subscription models for algorithm updates. This pattern is most visible in United States integrated delivery networks where capital committees and operating budgets sit under different governance structures.
Fusion Biopsy Market Segmentation
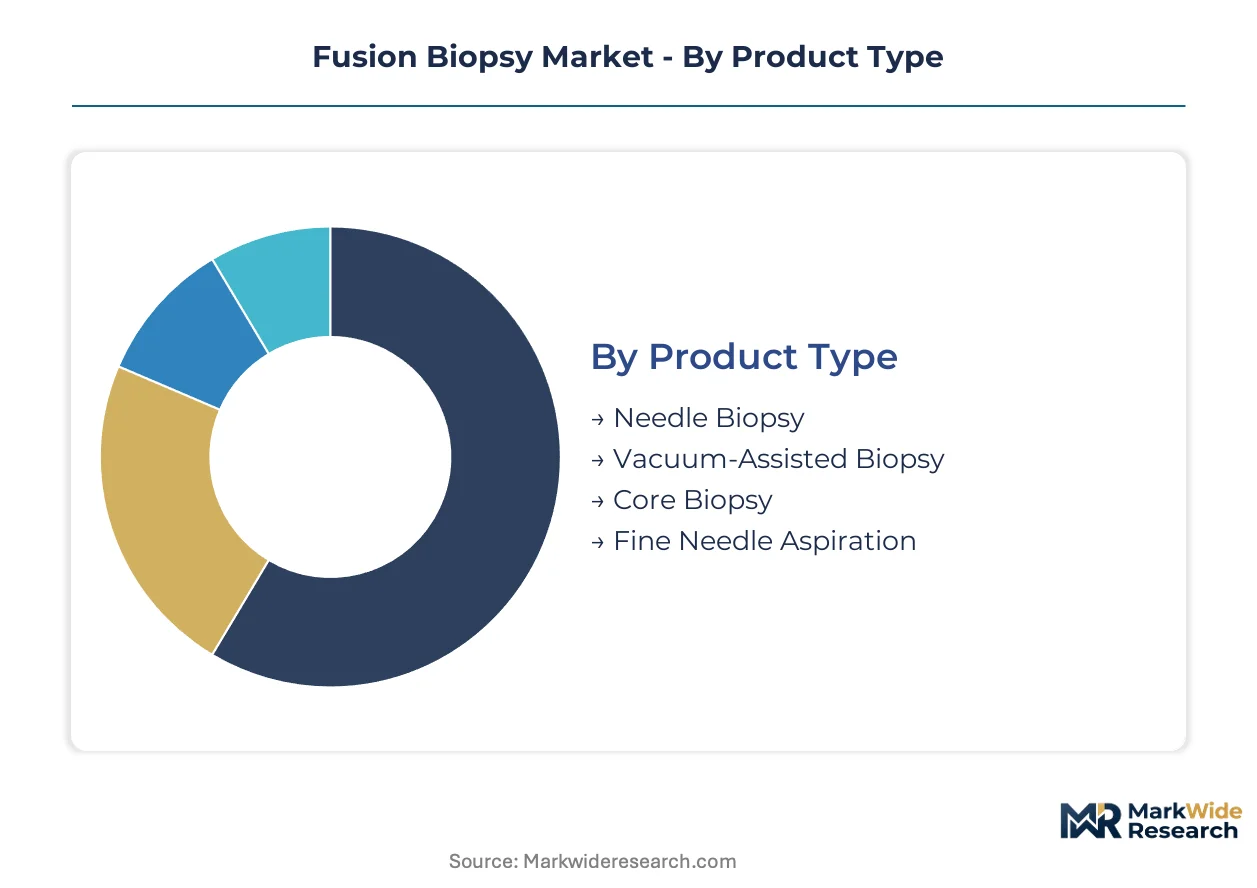
Fusion biopsy segmentation reveals distinct procurement patterns across hardware configurations and clinical settings. Each dimension carries implications for vendor pricing power, service bundling, and regulatory pathway complexity.
Product Type:
Standalone needle guidance systems dominate outpatient deployment, while integrated platforms with vacuum assistance concentrate in academic medical centers requiring larger tissue specimens.
- Needle Biopsy:Standard spring-loaded or coaxial needle systems deliver targeted core samples under fused imaging guidance. Demand concentrates in community hospital urology departments across the United States where Medicare reimbursement favors targeted over systematic approaches.
- Vacuum-Assisted Biopsy:Continuous suction mechanisms harvest larger contiguous tissue volumes through single insertion points. Academic medical centers in Germany and Japan deploy these instruments for genomic profiling workflows, though capital intensity limits community penetration.
- Core Biopsy:Automated cutting needles optimized for prostate tissue density characteristics.
- Fine Needle Aspiration:Cytology-focused sampling for rapid on-site evaluation in outpatient settings.
Volume placements concentrate in Needle Biopsy; the faster expansion belongs to Vacuum-Assisted Biopsy.
Technology:
Cost tiering separates premium robotic platforms from manual fusion systems, with reimbursement differentials driving technology selection across hospital capital budgets.
- Ultrasound-Guided:Real-time transrectal ultrasound fused with pre-procedure MRI coordinates represents the most deployed configuration. Community hospitals in the United States prioritize this modality for its lower hardware footprint and established CPT reimbursement codes.
- MRI-Guided:Direct intra-procedure MRI targeting achieves superior spatial precision for anterior lesions. Tertiary centers in Switzerland and Australia absorb the higher per-case cost for complex diagnostic scenarios where ultrasound penetration fails.
- CT-Guided:Alternative cross-sectional fusion for patients with MRI contraindications.
- Robotic-Assisted:Motorized needle positioning with hand motion compensation standardizes operator performance.
Ultrasound-Guided systems capture the highest placement volumes; Robotic-Assisted platforms are climbing the fastest as urologists seek reproducibility metrics.
End User:
Customer type determines workflow integration depth, with hospitals demanding full PACS connectivity and outpatient clinics prioritizing standalone operation.
- Hospitals:Integrated delivery networks in the United States anchor procurement volume, requiring EMR integration and multi-modality imaging compatibility. Urology departments within these systems drive fastest segment expansion as CMS policies redirect capacity toward targeted biopsy.
- Diagnostic Laboratories:Reference pathology operations influence upstream device selection through specimen quality requirements.
- Cancer Centers:NCI-designated comprehensive centers in the United States specify fusion platforms supporting research biobanking protocols.
- Outpatient Clinics:Freestanding urology practices in ambulatory surgical center settings seek compact systems with streamlined technician workflows.
Hospital systems dominate current installed base; Outpatient Clinics present the steepest expansion trajectory as procedure migration accelerates.
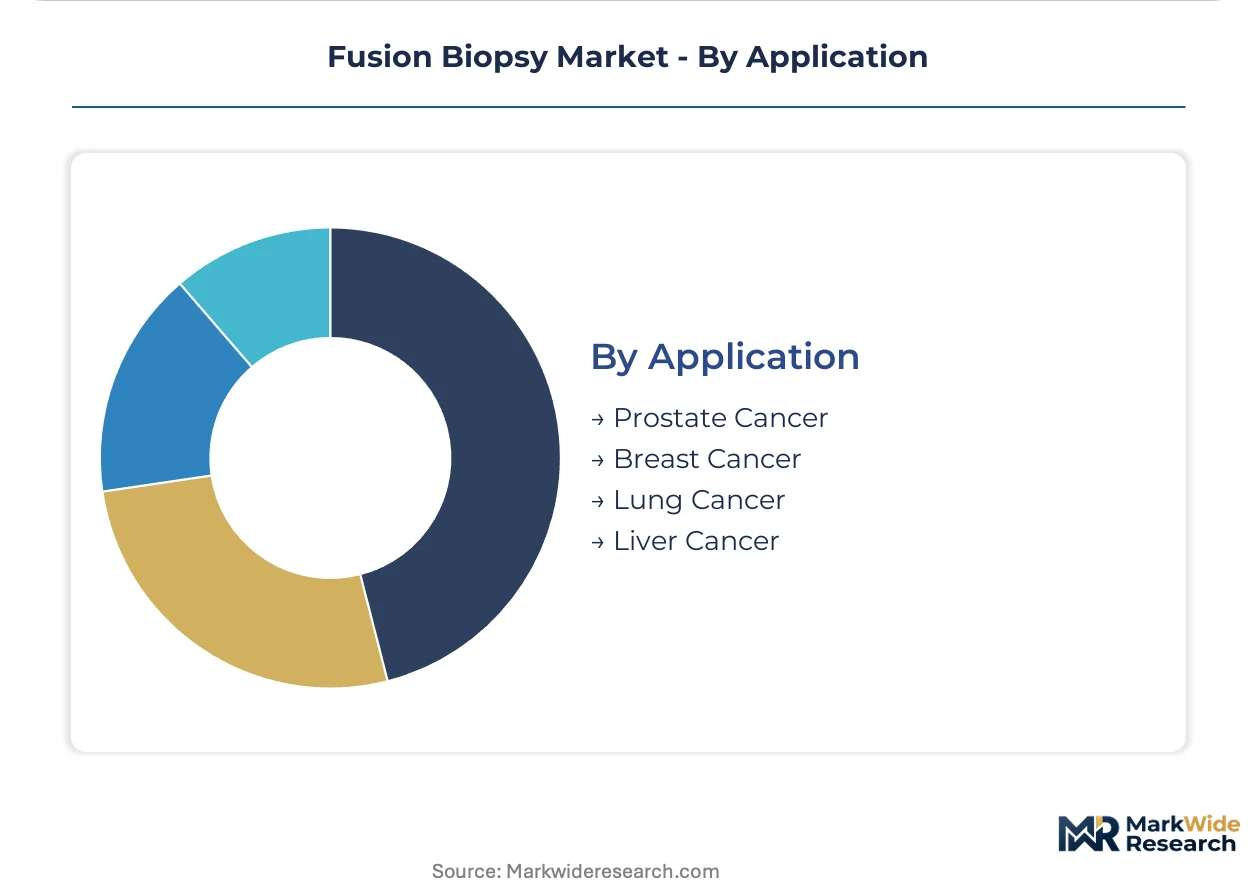
Application:
Disease-specific targeting protocols create divergent performance requirements for fusion software registration accuracy.
- Prostate Cancer:Multiparametric MRI fusion with transrectal ultrasound constitutes the primary commercial application. Screening protocol updates from the American Urological Association concentrate demand in United States urology practices.
- Breast Cancer:MRI-ultrasound fusion for biopsy of mammographically occult lesions serves secondary indications.
- Lung Cancer:Electromagnetic navigation bronchoscopy fusion with CT coordinates addresses peripheral nodule sampling.
- Liver Cancer:Contrast-enhanced ultrasound fusion for hepatocellular carcinoma characterization in cirrhotic patients.
Prostate Cancer applications command the dominant placement volume; Liver Cancer fusion protocols are gaining share fastest in East Asian tertiary centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate MRI-ultrasound fusion device manufacturing for Asia-Pacific distribution. Singapore's biomedical park incentives attract European vendors establishing regional headquarters. These zones compress customs clearance times and reduce landed costs for precision medical equipment.
United States
CMS reimbursement realignment toward targeted biopsy protocols drives hospital procurement cycles. FDA 510(k) clearance pathways for software-as-a-medical-device accelerate vendor market entry. The Cleveland Clinic and Johns Hopkins medical corridors anchor clinical validation studies for registration algorithm performance.
Germany
EU MDR Class IIa clinical performance documentation requirements extend certification timelines for fusion platforms. The country's statutory health insurance system maintains differential reimbursement rates for systematic versus targeted biopsy procedures. Munich and Heidelberg university hospital clusters pioneer vacuum-assisted biopsy adoption for genomic profiling workflows.
Japan
METI-supported precision medicine initiatives create procurement incentives for prostate MRI fusion systems. PMDA regulatory harmonization with FDA standards streamlines dual-market submissions for algorithm vendors. Tokyo and Osaka tertiary centers deploy robotic-assisted platforms for standardized hand motion compensation.
Switzerland
Swissmedic certification requirements demand prospective validation studies exceeding prior CE marking thresholds. The country's cantonal hospital procurement consortia negotiate bundled software-hardware contracts. Zurich and Geneva academic medical centers absorb higher per-case costs for MRI-guided direct intra-procedure targeting of anterior lesions.
Australia
TGA approval pathways for electromagnetic tracking fusion systems align with FDA 510(k) clinical packages. Medicare Benefits Schedule updates increasingly cover targeted biopsy approaches over systematic protocols. Sydney and Melbourne integrated delivery networks pilot AI-enabled organ deformation tracking to reduce registration error below one millimeter.
Fusion Biopsy Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated platform segments. The vendor base clusters around three strategic archetypes: imaging equipment conglomerates bundling fusion software with MRI contracts, standalone algorithm developers pursuing software-only regulatory pathways, and targeted biopsy instrument specialists. Dominant competitive moves include strategic partnerships between ultrasound manufacturers and AI tracking developers, plus geographic expansion through distributor networks in Asia-Pacific markets.
Within the imaging conglomerate tier, Koninklijke Philips N.V. and GE HealthCare occupy positions anchored by installed MRI base leverage. KOELIS exemplifies the focused specialist archetype, representing proprietary organ-tracking mechanics that reduce registration error. These three companies collectively illustrate how vendor strategy diverges between hardware bundling and algorithm differentiation.
| Leading Market Players |
|---|
| Eigen |
| BK Medical Holding Company, Inc. |
| Koninklijke Philips N.V. |
| ESAOTE SPA |
| Focal Healthcare |
| GE HealthCare |
| Hitachi Ltd. |
| MedCom |
| KOELIS |
| Others |
Cost & Logistics Intelligence
Captive software development within imaging conglomerates anchors both supply security and pricing power, as vendors like Koninklijke Philips N.V. and GE HealthCare bundle fusion algorithms with MRI hardware contracts to lock in multi-year service revenues and deflect standalone software competitors.
Pricing Analysis
Short lead-time premiums for FDA 510(k) cleared systems command pricing advantages over emerging MDR Class IIa platforms awaiting European certification. Three-tier pricing structure across premium robotic-assisted, standard manual fusion, and economy needle guidance tiers reflects certification grade and after-sales service bundling. Pricing pressure stems from software-only entrants pursuing SaMD pathways that bypass hardware capital intensity. Community hospital systems exhibit highest price sensitivity; academic medical centers absorb premium tiers for genomic profiling compatibility.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand, while distributor networks serve outpatient clinic penetration. Component sourcing concentrates in Germany for precision electromagnetic sensors, Japan for robotic positioning actuators, and the United States for AI training compute infrastructure. Supply chains draw from rare earth magnets for tracking arrays, specialized ultrasound transducers, and high-field MRI coil assemblies. Single-source vulnerability in PACS integration middleware creates procurement risk. Distribution runs through regional equipment specialists with biomedical engineering certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA software-as-a-medical-device pathways lower entry barriers for algorithm specialists, forcing hardware-dependent incumbents to acquire or partner to defend installed base positions.
For Market Incumbents: Deploy algorithmic differentiation through AI-enabled organ tracking acquisitions to offset hardware commoditization. Secure multi-year GPO contracts with United States integrated delivery networks before reimbursement policies fully shift. Backward integration into electromagnetic sensor manufacturing reduces single-source dependency from German component suppliers. For New Entrants and Emerging Players: Launch via software-only regulatory pathways targeting outpatient ambulatory surgical centers underserved by capital-intensive robotic platforms. Concentrate initial deployment in Japan's METI-supported precision medicine corridors where procurement incentives favor new algorithm vendors. White-space exists in AI-driven organ deformation tracking for manual fusion system retrofits. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by imaging conglomerates seeking algorithmic capabilities to bundle with MRI contracts. Long-term viability favors vendors with dual FDA-PMDA regulatory packages and recurring SaaS revenue streams. Watch for CMS reimbursement parity decisions between robotic-assisted and manual fusion as inflection signals for hardware versus software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Organ Tracking Acquisition | Machine learning convergence with electromagnetic arrays compresses registration error below one millimeter for academic centers. |
| SaMD Regulatory Pathway Investment | FDA 510(k) software-only clearances bypass hardware capital intensity and accelerate outpatient clinic penetration. |
| GPO Contract Consolidation | Multi-year agreements with United States integrated delivery networks lock out emerging algorithm competitors. |
| Japan METI Corridor Partnership | Precision medicine procurement incentives in Tokyo and Osaka tertiary centers create beachhead for dual-market submissions. |
| Reimbursement Strategy Alignment | CMS coverage decisions favoring targeted biopsy redirect hospital capital committees toward fusion-capable equipment. |
Research Approach
FDA 510(k) filings, PMDA submission databases, and CMS Medicare reimbursement records formed the secondary backbone, cross-referenced with primary interviews of urology department heads, hospital biomedical engineers, GPO contracts managers, and interventional radiology specialists. Bottom-up and top-down triangulation validated vendor shipment estimates against hospital procurement databases and installed base surveys.
Bottom-up modeling segmented by technology tier, end-user facility type, and application across the projection horizon, with top-down checks against imaging equipment capital expenditure flows. CAGRs derived from procedure volume migration curves and per-case value capture trajectories. Forecast inputs incorporated multiparametric MRI diffusion rates and reimbursement policy shift probabilities.
Regulatory timeline delays, reimbursement policy reversals, and AI algorithm performance failures are the dominant revision risks to modeled adoption curves. Forecasts reflect assumptions about radiologist-urologist coordination capacity expansion and software-hardware unbundling velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Inhalable Biologics Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Stem Cell Banking Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market