
 Anti-Neoplastic Pharmaceutical Agents Market | 2026-2036
Anti-Neoplastic Pharmaceutical Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Neoplastic Pharmaceutical Agents Market Outlook
EMA's evolving oncology drug assessment framework is broadening the evidentiary standards required for market authorization across European member states. Bayer AG leverages its radiopharmaceutical pipeline to anchor leadership in targeted alpha therapy. AbbVie Inc. sustains competitive intensity through its hematology franchise, while Pfizer Inc. differentiates via biosimilar scale and oncology portfolio breadth.
Anti-neoplastic pharmaceutical agents comprise synthetic and biologically derived compounds designed to inhibit malignant cell proliferation through cytotoxic, cytostatic, or immunomodulatory mechanisms, typically formulated as parenteral solutions, oral solid dosages, or antibody-drug conjugates requiring cold-chain distribution. These agents serve primarily to extend progression-free survival and overall survival in hematologic and solid tumor malignancies. Targeted therapies command premium positioning due to biomarker-driven patient selection and companion diagnostic requirements. Immunotherapy segments attract accelerated investment as checkpoint inhibitors demonstrate durable responses in previously refractory populations. Monoclonal antibodies retain manufacturing complexity advantages that protect margin pools from commoditization pressures.
FDA, EMA, and WHO harmonization initiatives on biosimilar interchangeability standards shape competitive entry dynamics and pricing corridors for established molecules. National reimbursement authorities in Germany, France, and Japan apply health technology assessment thresholds that filter market access for novel agents. Stakeholders must monitor real-world evidence generation requirements and value-based contracting pilots that increasingly determine formulary placement and procurement terms.
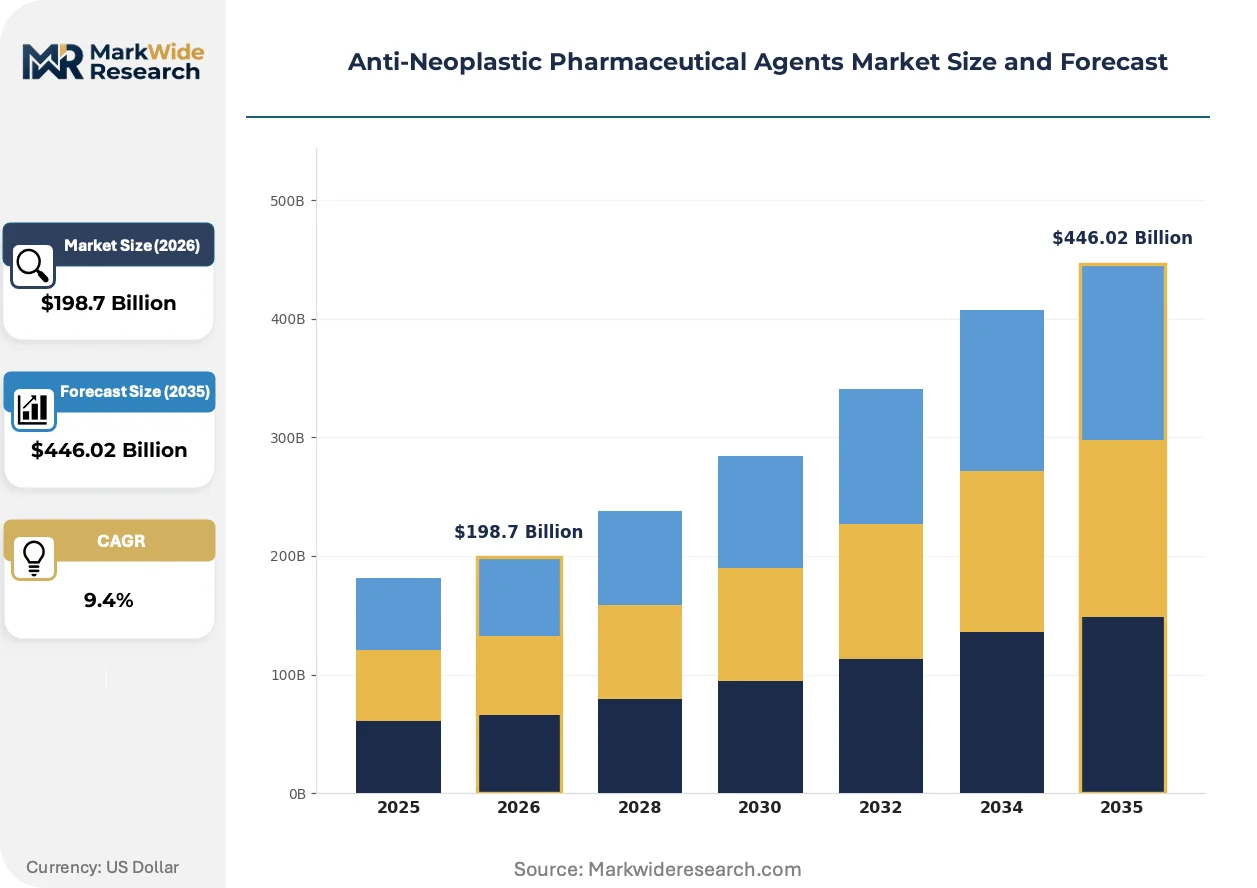
Market Dynamics
FDA's accelerated approval pathways compress oncology development timelines while companion diagnostic mandates reshape clinical trial design and commercialization requirements across therapeutic categories.
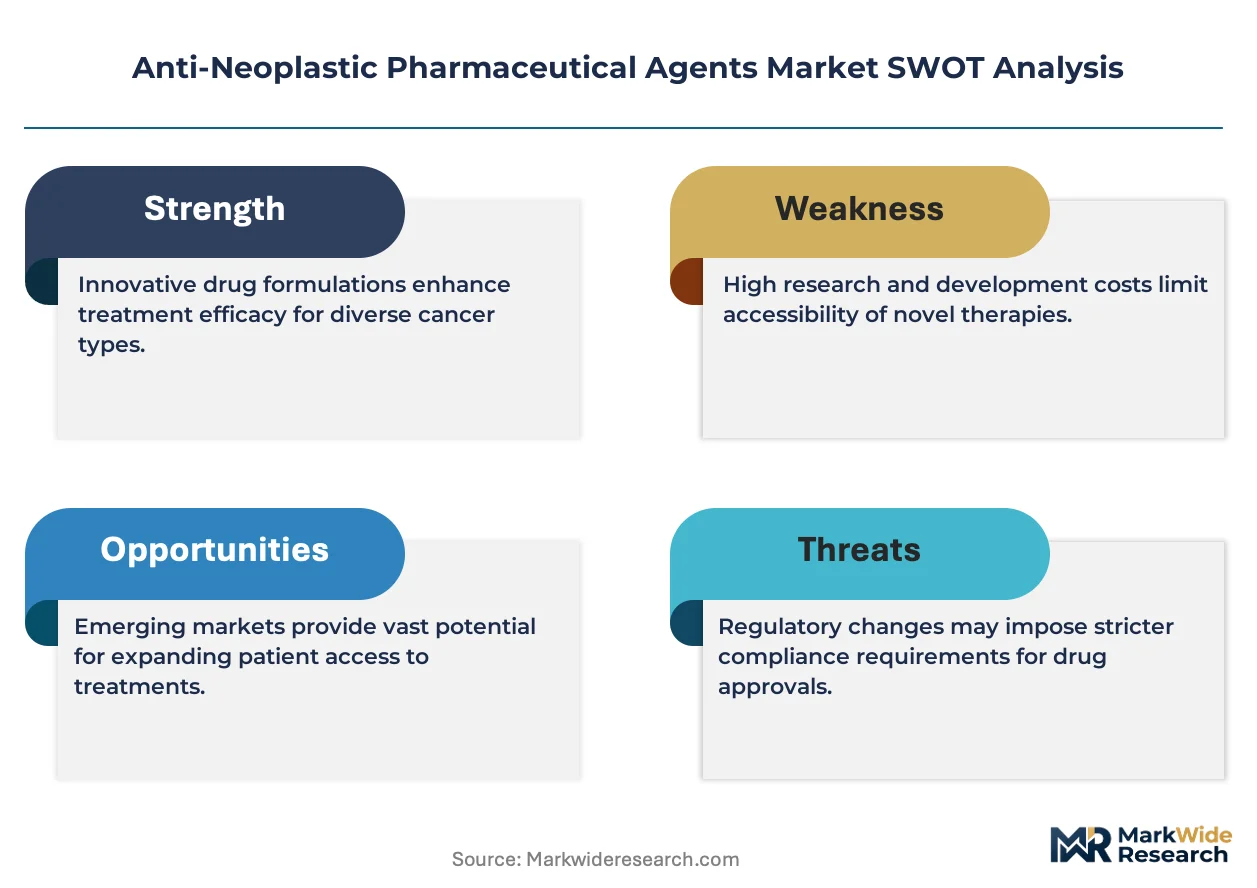
Growth Catalysts
- Breakthrough Therapy Designation:FDA's expedited review framework truncates Phase II-to-approval intervals for agents demonstrating substantial survival advantages over existing standards.
- Biomarker-Driven Patient Stratification:Next-generation sequencing adoption in tertiary oncology centers enables precision enrollment that improves response rates and accelerates label expansion.
- China:NMPA's priority review vouchers for innovative oncology drugs attract multinational trial investment and local manufacturing partnerships.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient synthesis for cytotoxic agents concentrates in Indian and Chinese contract manufacturers, creating single-source vulnerability.
- Health Technology Assessment Thresholds:Germany's IQWiG and France's HAS apply incremental cost-effectiveness ratio ceilings that delay or restrict reimbursement for premium-priced immunotherapies.
- Substitution Pressure:Biosimilar trastuzumab and rituximab entrants compress pricing corridors for originator monoclonal antibodies in European tenders.
Strategic Opportunities
- Radiopharmaceutical Expansion:Targeted alpha therapy pipelines for prostate and neuroendocrine malignancies address unmet needs in metastatic castration-resistant populations.
- Japan:PMDA's Sakigake designation system offers priority consultation and shortened review timelines for first-in-class oncology agents.
- Real-World Evidence Integration:FDA's Project Real World Evidence enables supplemental indications based on electronic health record and claims data, reducing confirmatory trial burdens.
Industry Challenges
- Cold-Chain Distribution Complexity:Antibody-drug conjugates and cellular therapies require uninterrupted cryogenic logistics that strain specialty pharmacy networks.
- Companion Diagnostic Co-Development:Synchronized PMA submissions for therapeutics and IVDs create regulatory interdependencies that extend launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Neoplastic Pharmaceutical Agents Market |
| Market Size in 2026 | $198.7 Billion |
| Market Size in 2035 | $446.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapeutic Agents, Targeted Therapies, Monoclonal Antibodies, Immunotherapy Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Leukemia End User: Hospitals, Clinics, Research Institutions, Homecare |
| Companies Covered | Bayer AG, AbbVie Inc., Pfizer Inc., Johnson & Johnson, Amgen Inc., F. Hoffmann-La Roche Ltd., Novartis AG, AstraZeneca Inc., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Neoplastic Pharmaceutical Agents Market Strategic Shifts
Antibody-drug conjugate engineering and radioligand therapy manufacturing are redrawing competitive boundaries as developers pursue tissue-specific cytotoxic delivery mechanisms.
Antibody-drug conjugates with cleavable linker technologies and bystander-killing payloads are absorbing development investment from conventional chemotherapy platforms. Oncology biotechs and large-cap pharmas alike prioritize ADC pipelines for solid tumor indications where checkpoint inhibitors underperform. The technology is absorbing clinical trial capacity and manufacturing scale that previously served small-molecule cytotoxics, compressing the addressable market for traditional platinum agents and taxanes.
EMA's oncology drug assessment framework now mandates comparative effectiveness evidence against standard-of-care rather than placebo, elevating trial costs and duration. The revised evidentiary standard favors agents with head-to-head survival data and disadvantages single-arm accelerated approvals. European member states are responding with earlier scientific advice engagement and adaptive trial designs to satisfy both EMA and national HTA bodies.
Hospital system consolidation in the United States concentrates oncology procurement through integrated delivery networks and specialty pharmacy carve-outs. Community oncology practices face absorption into hospital outpatient departments or affiliation with larger networks to access 340B pricing and payer contracts. This concentration is most visible in Texas, Florida, and California where large health systems command regional referral patterns and formulary influence.
Anti-Neoplastic Pharmaceutical Agents Market Segmentation
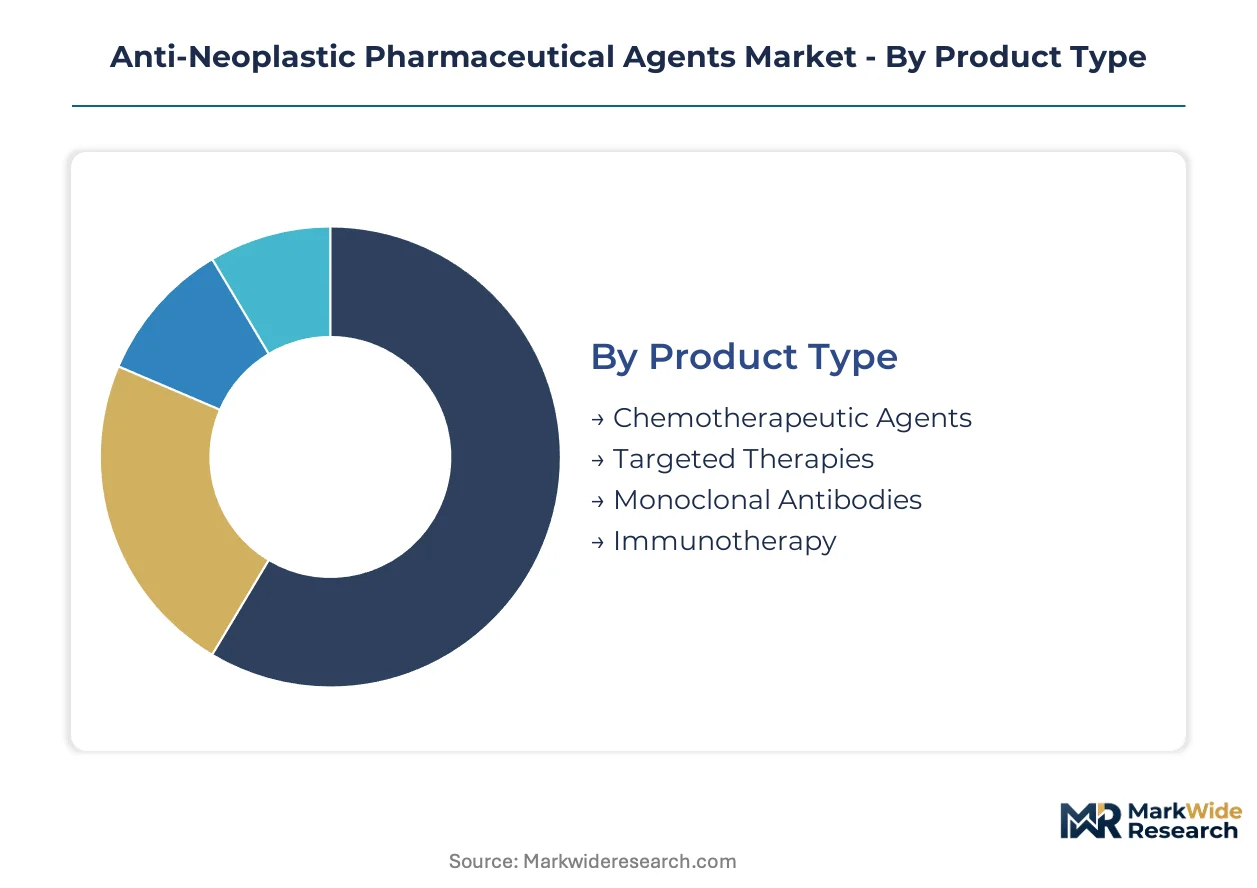
Segmentation in anti-neoplastic pharmaceuticals determines pricing power, distribution infrastructure, and regulatory pathway selection. Product type and administration route dictate manufacturing scale, cold-chain requirements, and site-of-care economics.
Product Type:
Technology platforms differentiate by mechanism of action, biomarker dependency, and manufacturing complexity.
- Targeted Therapies:Small-molecule inhibitors and signal transduction modulators require companion diagnostic alignment. Demand concentrates in tertiary oncology centers with next-generation sequencing capabilities, driven by biomarker-driven patient selection and premium reimbursement for molecularly defined populations.
- Immunotherapy:Checkpoint inhibitors and cell-based therapies activate host immune responses against malignancies. Procurement volumes cluster in United States academic medical centers and specialized cancer institutes, anchored by durable response data in previously refractory indications and Medicare reimbursement for infused biologics.
- Chemotherapeutic Agents:Cytotoxic alkylating agents, antimetabolites, and mitotic inhibitors.
- Monoclonal Antibodies:Engineered immunoglobulins targeting tumor-associated antigens with Fc-effector functions.
Mature deployment sits with chemotherapeutic agents. Newer deployment is concentrated in immunotherapy.
Administration Route:
Route selection shapes site-of-care economics, patient adherence profiles, and pharmacy benefit design.
- Intravenous:Infused biologics and cytotoxics requiring supervised administration in oncology clinics or hospital outpatient departments. United States hospital systems drive procurement through 340B pricing programs and specialty pharmacy carve-outs, constrained by facility fee structures and nursing capacity.
- Oral:Small-molecule kinase inhibitors and hormonal agents enabling outpatient management. Germany's statutory health insurance funds and Japan's NHI reimbursement favor oral oncolytics for cost-efficient chronic administration, though adherence monitoring challenges persist.
- Subcutaneous:Monoclonal antibody formulations reducing infusion center burden.
- Intramuscular:Depot formulations and hormonal therapies for sustained release.
Volume concentration favors intravenous delivery in hospital-affiliated settings. Steepest expansion trajectory belongs to oral agents enabling community and home-based administration.
Therapy Area:
Oncology indications segment by prevalence, treatment paradigm maturity, and unmet medical need intensity.
- Lung Cancer:Non-small cell and small cell malignancies with high mutation burden and checkpoint inhibitor responsiveness. China's NMPA priority review and United States FDA breakthrough therapy designations accelerate approvals for EGFR, ALK, and PD-L1 directed agents in first-line settings.
- Breast Cancer:Hormone receptor-positive, HER2-positive, and triple-negative subtypes with established biomarker stratification. France's HAS and Germany's IQWiG apply differential HTA thresholds by line of therapy and biomarker status, shaping access for CDK4/6 inhibitors and antibody-drug conjugates.
- Colorectal Cancer:MSI-high and RAS wild-type subsets with evolving immunotherapy and targeted therapy integration.
- Leukemia:Acute and chronic myeloid and lymphoid malignancies with cell therapy disruption.
Commercial maturity anchors in breast cancer. Pipeline investment and regulatory acceleration concentrate in lung cancer.
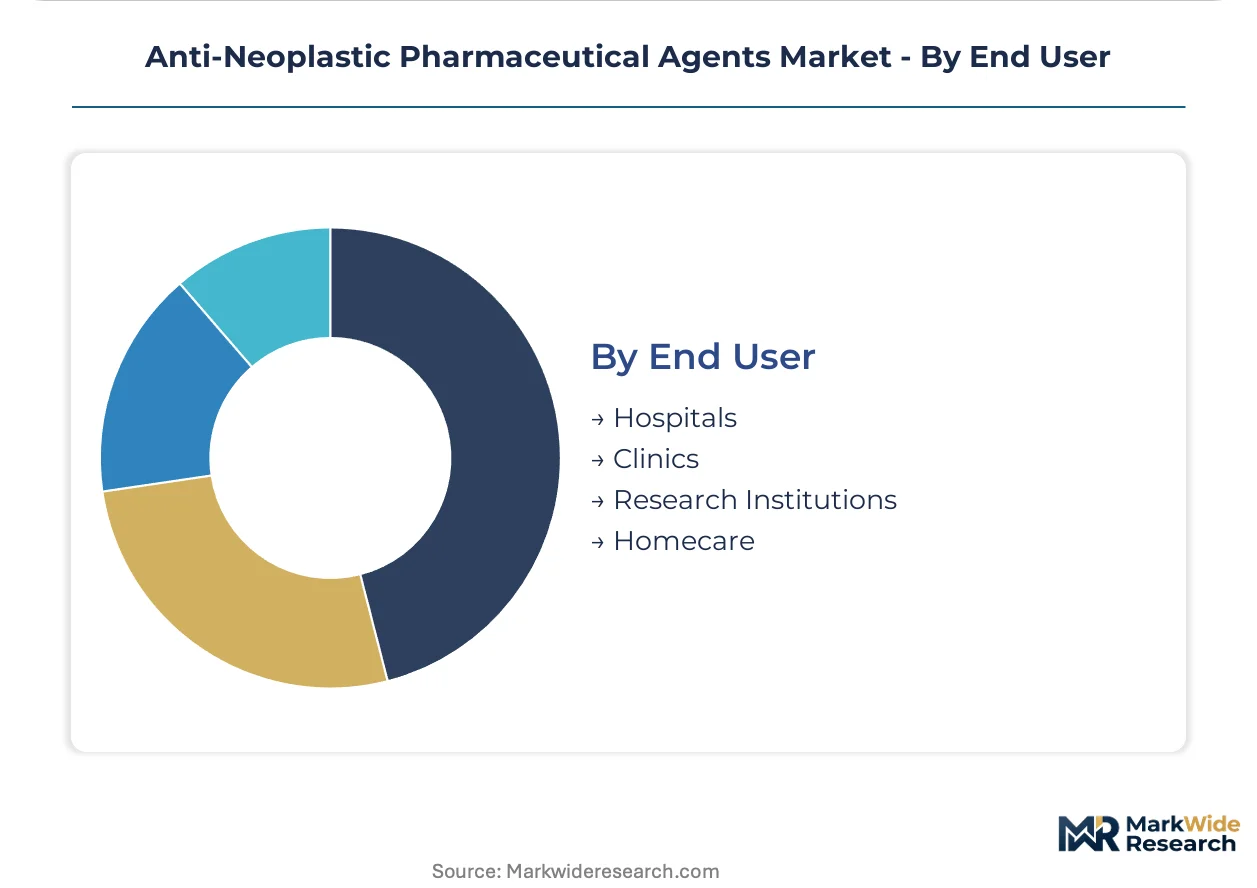
End User:
Site-of-care selection determines procurement channel, reimbursement mechanism, and patient access pathway.
- Hospitals:Integrated delivery networks and academic medical centers with infusion capacity, pathology infrastructure, and clinical trial access. United States health system consolidation in Texas, Florida, and California concentrates oncology procurement through centralized formularies and specialty pharmacy arrangements.
- Clinics:Community oncology practices and ambulatory infusion centers. Japan's clinic-based cancer care and European outpatient networks favor this channel for oral agents and subcutaneous biologics, though United States 340B differentials pressure independent practice economics.
- Research Institutions:Academic centers and contract research organizations driving early-phase development.
- Homecare:Specialty pharmacy and nursing-supported administration for selected oral and injectable agents.
Procurement volume dominance rests with hospitals. Channel expansion is gaining share fastest in homecare and specialty pharmacy models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina concentrates oncology clinical trials and biologics manufacturing, while Basel's pharmaceutical corridor anchors European radiopharmaceutical production. These specialized zones concentrate talent, regulatory expertise, and cold-chain infrastructure that shape regional competitive positioning.
United States
Hospital system consolidation in Texas, Florida, and California concentrates oncology procurement through integrated delivery networks. The FDA's breakthrough therapy designation accelerates Phase II-to-approval intervals for agents demonstrating substantial survival advantages. The MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor specialized cancer care and clinical trial enrollment.
Germany
IQWiG applies incremental cost-effectiveness ratio ceilings that filter market access for premium-priced immunotherapies. The statutory health insurance funds favor oral oncolytics for cost-efficient chronic administration. Heidelberg and Munich host academic medical centers with next-generation sequencing capabilities that drive biomarker-driven patient selection.
China
NMPA's priority review vouchers for innovative oncology drugs attract multinational trial investment. Local manufacturing partnerships with multinational pharmas expand biologics production capacity. Shanghai's Zhangjiang Hi-Tech Park concentrates biotech R&D and contract manufacturing organizations serving domestic and export markets.
Japan
PMDA's Sakigake designation system offers priority consultation and shortened review timelines for first-in-class oncology agents. The NHI reimbursement framework supports premium pricing for agents demonstrating clear clinical benefit. The Kanto region around Tokyo concentrates specialized cancer centers and pharmaceutical headquarters.
Switzerland
Swissmedic maintains alignment with EMA standards while offering streamlined pathways for radiopharmaceutical authorization. Basel's pharmaceutical corridor anchors radioligand therapy manufacturing and targeted alpha therapy development. The country's central European location supports cold-chain distribution across German, French, and Italian markets.
Anti-Neoplastic Pharmaceutical Agents Market Competitive Environment
United States-based producers anchor the immunotherapy and checkpoint inhibitor tier; European specialists hold radiopharmaceutical and antibody-drug conjugate capabilities. The market structure concentrates around large-cap pharmas with integrated oncology portfolios and biotechs with single-asset platforms. Three archetypes dominate: diversified pharmas with broad pipelines, radiopharmaceutical specialists with manufacturing complexity advantages, and biosimilar scale players compressing pricing corridors. Competitive moves center on M&A for ADC technology access and capacity expansion for cold-chain biologics distribution.
Among diversified pharmas with oncology breadth, Bayer AG exemplifies the radiopharmaceutical specialist archetype through its targeted alpha therapy focus. AbbVie Inc. occupies a position within the hematology franchise tier, while Pfizer Inc. sits within the biosimilar scale and portfolio breadth category. These three represent distinct strategic postures: manufacturing complexity protection, therapeutic area concentration, and commoditization defense through scale.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie Inc. |
| Pfizer Inc. |
| Johnson & Johnson |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| AstraZeneca Inc. |
| Merck & Co. Inc. |
| Others |
Value Chain & Pricing Dynamics
Cold-chain sustainability mandates from the FDA and EMA now gate qualified supply access and premium-tier pricing authorization for antibody-drug conjugates and cellular therapies. Manufacturers without validated cryogenic logistics infrastructure face exclusion from hospital system formularies and 340B procurement channels.
Pricing Analysis
Short lead-time premiums for radiopharmaceuticals with rapid isotope decay profiles command substantial markups over standard-order cycles, while spot inventory of cytotoxic APIs trades at discounts. Contract-based long-term offtake agreements anchor pricing for monoclonal antibodies, with differentiation driven by FDA breakthrough therapy designation and companion diagnostic bundling. Price erosion runs through biosimilar trastuzumab and rituximab tiers due to European tender compression. Community oncology practices exhibit highest price sensitivity; academic medical centers with 340B access show lowest.
Supply Chain Analysis
API synthesis for cytotoxic agents rests on Indian and Chinese contract manufacturers, with cold-chain biologics production concentrated in the United States, Switzerland, and Japan. Key inputs span platinum-based chemical precursors, recombinant cell lines, and medical-grade isotopes. Single-source vulnerability in isotope supply creates structural risk. Distribution runs through specialty pharmacy networks and hospital-affiliated infusion centers with 340B carve-outs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-neoplastic pharmaceutical market sits in a technology-transition phase where antibody-drug conjugates displace conventional chemotherapy platforms in solid tumor indications. ADC engineering with cleavable linker technologies now commands development investment that previously served platinum agents and taxanes.
For Market Incumbents: Lock in radiopharmaceutical manufacturing complexity advantages through captive isotope supply agreements and alpha-therapy pipeline expansion. Secure 340B contract pharmacy relationships to defend against biosimilar substitution pressure in European tender markets. Prioritize cold-chain capacity addition in Texas, Florida, and California hospital systems.
For New Entrants and Emerging Players: Direct-to-clinic digital platforms for oral oncolytic adherence monitoring offer the most penetrable white-space entry. Target Japan's clinic-based cancer care networks and Germany's statutory health insurance oral oncology preference. Pursue real-world evidence generation partnerships with integrated delivery networks as the primary go-to-market angle.
For Investors and Strategic Acquirers: FDA Project Real World Evidence supplemental indication approvals are the leading indicator that confirmatory trial burden reduction is shifting value creation timelines. The 5-10 year viability window favors acquisition targets with ADC linker-payload platforms and radioligand therapy manufacturing capabilities. Watch NMPA priority review voucher issuance rates as the inflection signal for China market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-driven patient stratification improves response rates and accelerates FDA breakthrough therapy designation. |
| Regulatory Approval Pathway | EMA's comparative effectiveness mandate elevates head-to-head survival data requirements for market authorization. |
| Manufacturing Scale-Up | Cold-chain biologics capacity expansion in hospital-affiliated specialty pharmacy networks secures 340B access. |
| Pipeline Diversification | Targeted alpha therapy for prostate and neuroendocrine malignancies addresses unmet castration-resistant populations. |
| Strategic Partnership | Companion diagnostic co-development with IVD manufacturers synchronizes PMA submissions and compresses launch timelines. |
Study Parameters
Multi-period observation of FDA accelerated approval designations, EMA oncology assessment framework revisions, and hospital system consolidation patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure tracking enabled triangulation across data sources.
Segment-weighting across product type, administration route, therapy area, and end user informed the analytical framework over the projection horizon. CAGRs were derived from modeled prescription volume trajectories and pricing corridor assumptions. Treatment line positioning and regional regulatory cluster differentiation served as key forecast inputs for immunotherapy and targeted therapy segments.
The model holds under stable reimbursement policy conditions; deviation in Medicare 340B program restructuring or EMA health technology assessment threshold tightening would shift volume and value trajectories. A small set of triggers—biosimilar interchangeability rulings, isotope supply disruptions, and real-world evidence regulatory expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Global Pegylated Proteins Market