
 Drug Resistant Pulmonary Tuberculosis Market | 2026-2036
Drug Resistant Pulmonary Tuberculosis Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Resistant Pulmonary Tuberculosis Market Foresight
Procurement among public health organizations is pivoting toward centralized national TB programs with pooled purchasing power. Johnson & Johnson anchors the market through its bedaquiline franchise and vertically integrated manufacturing of anti-TB compounds. Lupin leverages its generic portfolio to compete on price in multidrug-resistant regimens across emerging markets. Pfizer Inc. sustains relevance through its legacy moxifloxacin supply chains and hospital channel relationships.
Drug resistant pulmonary tuberculosis encompasses Mycobacterium tuberculosis strains unresponsive to isoniazid and rifampicin, requiring second-line agents such as fluoroquinolones, aminoglycosides, and diarylquinolines administered over 18-24 month cycles. The therapy area segments show multidrug-resistant TB occupying the largest patient pool while extensively drug-resistant TB commands premium pricing due to limited therapeutic options. Combination therapy leads product type demand as WHO guidelines prioritize multi-agent regimens to prevent further resistance amplification, with oral administration routes displacing injectable protocols in new treatment algorithms.
FDA orphan drug designations and WHO prequalification requirements shape product development timelines and market access pathways for novel anti-TB agents. India's CDSCO and South Africa's national health regulator enforce stringent bioequivalence standards for generic second-line drugs entering public sector tenders. Stakeholders must monitor regulatory harmonization between WHO, FDA, and national TB programs as treatment-shortening regimens advance through clinical validation.
Market Dynamics
WHO prequalification standards and novel oral regimens are compressing treatment timelines and reshaping procurement protocols across national TB programs. The shift from injectable to all-oral combination therapies is restructuring manufacturing priorities and supply chain configurations for second-line anti-TB agents.
Growth Catalysts
- Oral Regimen Transition:WHO endorsement of bedaquiline-pretomanid-linezolid combinations is eliminating injectable aminoglycoside requirements. National programs in high-burden countries are accelerating formulary updates to capture shortened 6-month treatment cycles.
- India's CDSCO Fast-Track:Accelerated approval pathways for bioequivalent second-line generics are compressing market entry timelines. Domestic manufacturers are scaling production of fixed-dose combinations to supply centralized procurement pools.
- Diagnostics-Convergent Therapy:Molecular resistance profiling via GeneXpert MTB/RIF Ultra is identifying MDR-TB and XDR-TB cases earlier. Treatment initiation rates are rising as laboratory networks expand in South Africa and Russia.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient production for fluoroquinolones and diarylquinolines concentrates in Chinese and Indian chemical manufacturing clusters. Geopolitical friction or environmental enforcement actions in these hubs disrupt downstream formulation supply.
- Therapy Duration Economics:18-24 month treatment cycles for pre-2019 regimens impose catastrophic patient costs and program budget strain. Adherence failures during extended therapy amplify resistance development and retreatment burden.
- Regulatory Divergence:Misalignment between FDA orphan drug timelines and WHO prequalification requirements creates dual-track validation costs. Developers face fragmented clinical trial designs to satisfy both pathways simultaneously.
Strategic Opportunities
- Sub-Saharan Africa Expansion:Underpenetrated diagnostic and treatment infrastructure in Nigeria, Ethiopia, and Kenya presents procurement growth potential. PEPFAR and Global Fund co-financing mechanisms are expanding program budgets for MDR-TB case detection.
- Regulatory Harmonization:WHO's transition to a unified prequalification standard for novel regimens is reducing redundant national registrations. Early movers aligning with this framework gain accelerated tender access across multiple programs.
- Point-of-Care Distribution:Decentralized treatment initiation at primary health centers is displacing centralized hospital-based care. Community-based directly observed therapy models are reducing patient travel burden and improving completion rates.
Industry Challenges
- Specialized Manufacturing Scale-Up:Potent compound handling requirements for diarylquinolines demand containment infrastructure investments. Contract manufacturers face qualification bottlenecks as demand for high-potency API synthesis outpaces certified capacity expansion.
- Resistance Surveillance Integration:National programs lack interoperable data systems linking laboratory resistance patterns to treatment outcome tracking. Fragmented informatics infrastructure impedes real-world evidence generation for regimen optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Resistant Pulmonary Tuberculosis Market |
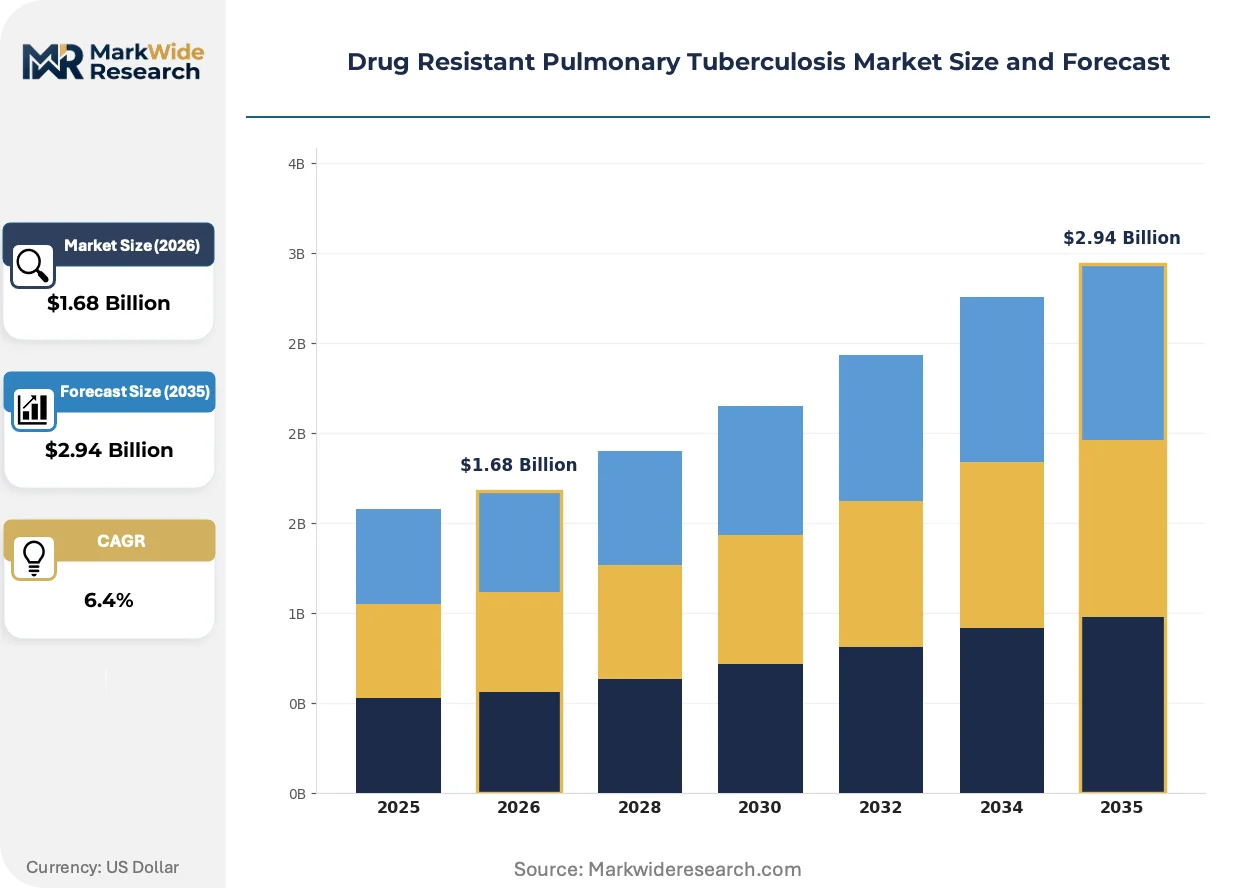
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Combination Therapy, Monotherapy, Supportive Care Therapy Area: Drug-Resistant TB, Multidrug-Resistant TB, Extensively Drug-Resistant TB, Total Drug-Resistant TB Administration Route: Oral, Intravenous, Inhalation, Subcutaneous End User: Hospitals, Clinics, Public Health Organizations, Research Laboratories |
| Companies Covered | Johnson & Johnson, Novartis AG, Sanofi, Pfizer Inc., Lupin, Hikma Pharmaceuticals, Endo International Plc, STI Pharma LLC, Macleods Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Resistant Pulmonary Tuberculosis Market Shifts & Advancements
Oral therapeutic innovation and regulatory pathway convergence are compressing development timelines while procurement centralization is restructuring competitive access. Three forces are actively reshaping market structure: technology decentralization, policy harmonization, and procurement model evolution.
All-oral combination regimens are decentralizing treatment delivery from tertiary hospitals to primary health centers. National TB programs in India and South Africa are deploying these protocols at scale following WHO guideline updates. The technology is compressing the clinical workforce requirement and enabling community-based care models previously infeasible with injectable therapy.
WHO's consolidated guidelines framework is eliminating country-specific regimen variations that complicated manufacturing planning. The policy is standardizing procurement specifications across prequalification-dependent programs. Generic manufacturers are responding with unified product dossiers rather than market-by-market customization.
Centralized pooled procurement through the Global Drug Facility is consolidating buyer power and compressing price negotiation cycles. National programs are aggregating demand forecasts to secure volume-based supply commitments. This concentration is most visible in India's national TB elimination program and South Africa's centralized tender system.
Drug Resistant Pulmonary Tuberculosis Market Segmentation
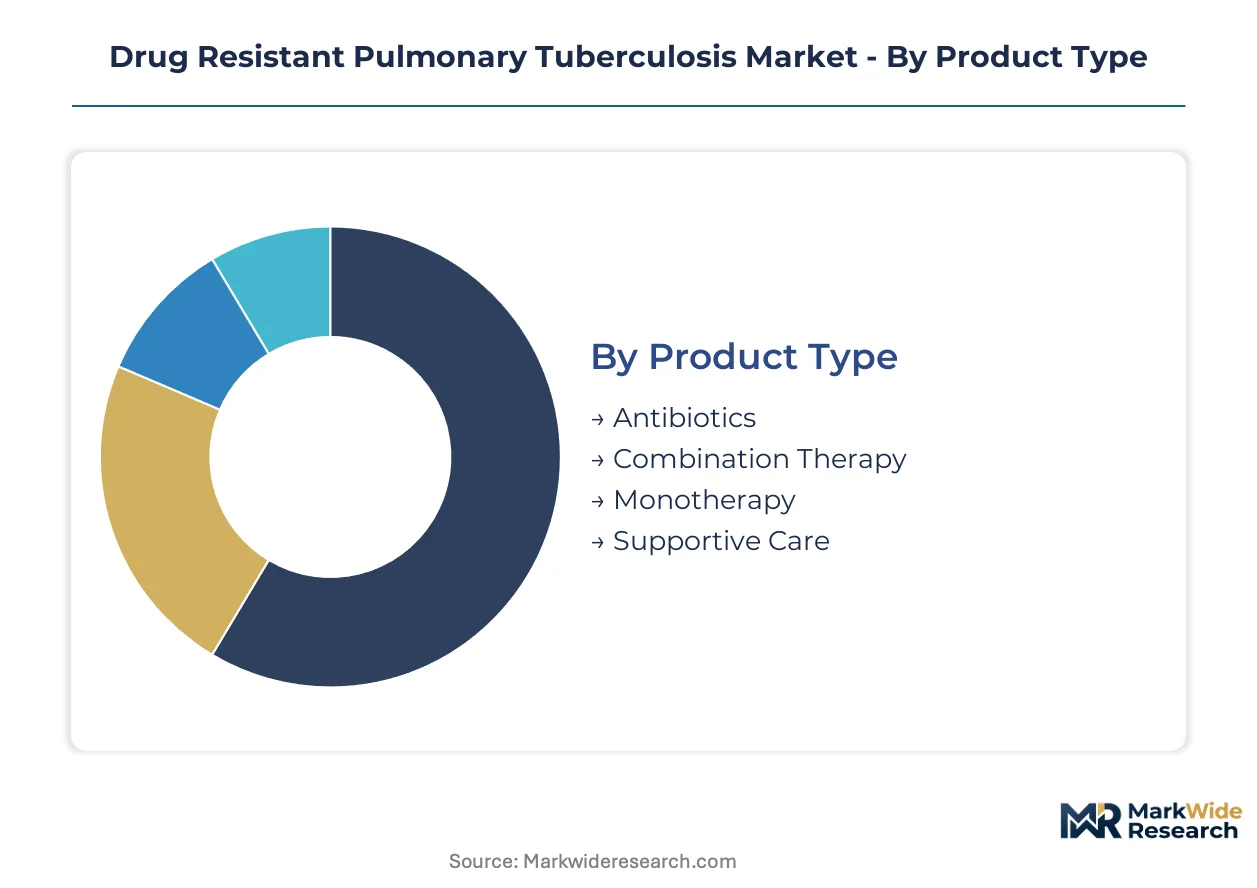
Treatment protocol complexity in drug-resistant pulmonary tuberculosis demands precise segmentation alignment with WHO guidelines, procurement channels, and patient stratification requirements. Each dimension reflects distinct regulatory pathways, reimbursement mechanisms, and supply chain configurations.
Product Type:
Procurement budgets prioritize regimen efficacy against resistance profiles and total cost of therapy completion.
- Antibiotics:Second-line agents including fluoroquinolones, aminoglycosides, and cycloserine form the pharmacological backbone of extended treatment protocols. Demand concentrates in India's national TB elimination program and South Africa's centralized tender system where aminoglycoside injectables persist in resource-limited settings despite WHO oral regimen recommendations.
- Combination Therapy:Fixed-dose combinations of bedaquiline, pretomanid, and linezolid deliver the 6-month all-oral regimens now endorsed by WHO. Public health organizations in high-burden countries are accelerating formulary updates to capture shortened treatment cycles and eliminate injectable requirements.
- Monotherapy:Single-agent use is restricted to specific resistance patterns or intolerance scenarios, with limited procurement outside salvage protocols.
- Supportive Care:Nutritional supplementation and adverse event management adjuncts support adherence in extended therapy cycles.
Volume sits with Antibiotics; growth tilts toward Combination Therapy.
Therapy Area:
Patient stratification by resistance severity determines agent selection, treatment duration, and monitoring intensity.
- Multidrug-Resistant TB:Resistance to isoniazid and rifampicin defines the largest addressable patient population requiring second-line fluoroquinolone-based regimens. Case detection is expanding in Russia's oblast-level laboratory networks and South Africa's GeneXpert-equipped primary health centers.
- Extensively Drug-Resistant TB:Additional resistance to fluoroquinolones and injectable agents commands premium therapeutic investment and specialized containment infrastructure. Limited therapeutic options drive demand for novel diarylquinolines in India's tertiary referral hospitals and South Africa's centralized MDR-TB treatment facilities.
- Drug-Resistant TB:Broad category encompassing any resistance beyond first-line agents, with heterogeneous treatment requirements.
- Total Drug-Resistant TB:Pan-resistant strains with minimal therapeutic options, managed through salvage regimens and investigational access programs.
Patient volume concentrates in Multidrug-Resistant TB; steepest expansion trajectory belongs to Extensively Drug-Resistant TB as molecular diagnostics improve case identification.
Administration Route:
Delivery mode selection hinges on healthcare infrastructure density, patient mobility constraints, and workforce availability for supervised administration.
- Oral:Tablets and fixed-dose combinations enable decentralized directly observed therapy at primary health centers, eliminating hospital-based injection requirements. WHO guideline updates are accelerating formulary transitions in India's national program and South Africa's provincial health systems.
- Intravenous:Aminoglycoside and capreomycin administration persists in settings lacking oral regimen access or with specific resistance patterns requiring parenteral agents.
- Inhalation:Investigational aerosolized delivery systems target localized pulmonary disease with reduced systemic exposure.
- Subcutaneous:Limited application for specific agents in outpatient settings with intermittent dosing requirements.
Procurement volume remains with Oral administration; Inhalation represents the emerging modality gaining investigational investment.
End User:
Facility type determines procurement channel, reimbursement mechanism, and regulatory oversight intensity.
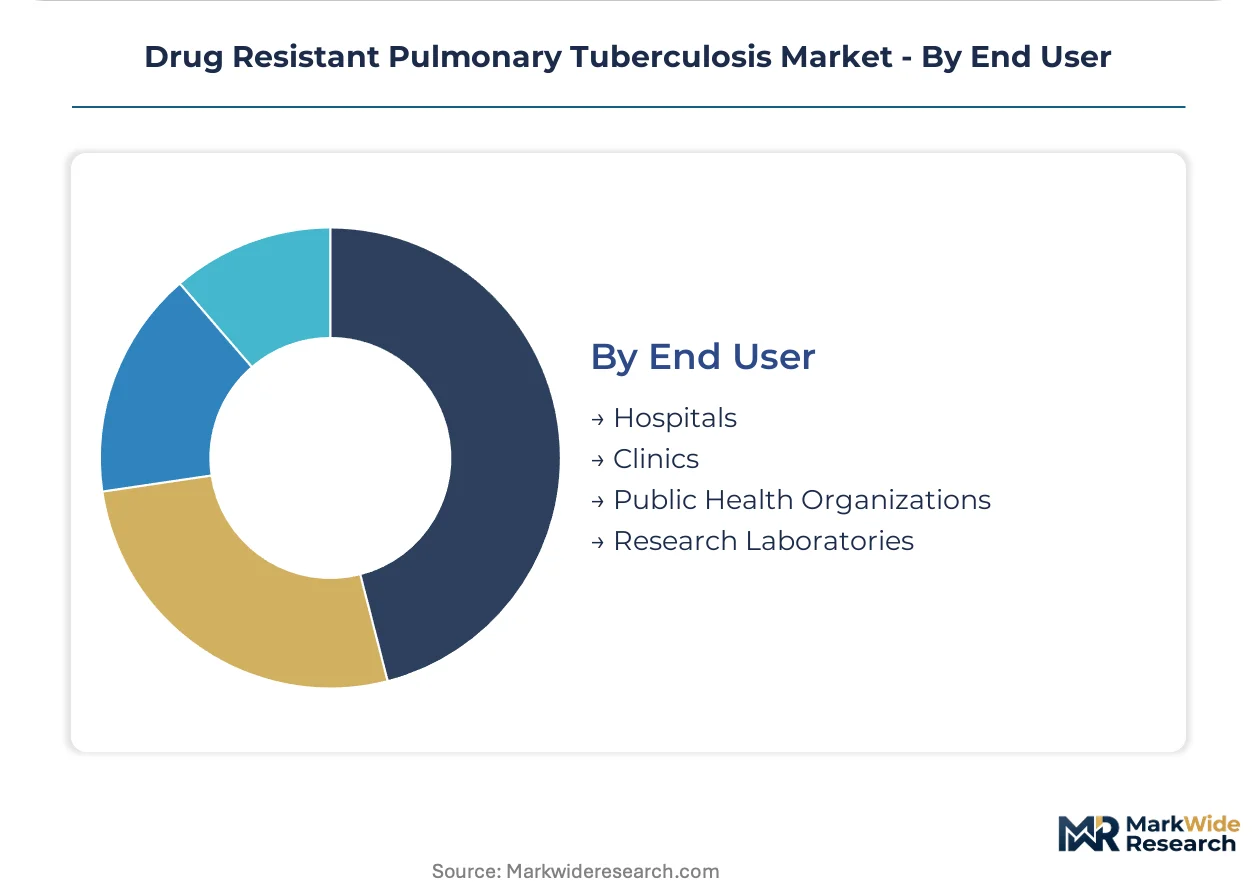
- Hospitals:Tertiary centers manage complex XDR-TB cases, adverse event monitoring, and surgical interventions for destroyed lung parenchyma. India's medical college hospitals and South Africa's centralized MDR-TB facilities anchor demand for intensive monitoring capabilities.
- Public Health Organizations:National TB programs and Global Fund implementers execute pooled procurement through the Global Drug Facility, consolidating buyer power across high-burden countries. Centralized tender systems in India and South Africa aggregate demand forecasts to secure volume-based supply commitments.
- Clinics:Primary health centers are expanding treatment initiation capacity following oral regimen decentralization, reducing patient travel burden.
- Research Laboratories:Reference facilities conduct resistance surveillance, culture confirmation, and clinical trial enrollment for novel agents.
Procurement concentration rests with Public Health Organizations; care delivery is decentralizing toward Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India, South Africa, and Russia concentrate the highest MDR-TB and XDR-TB case burdens, anchoring procurement demand for second-line therapies. National TB programs in these markets drive volume through centralized tender systems and Global Drug Facility participation.
India
India's National TB Elimination Program operates the world's largest public sector procurement pool for drug-resistant TB therapies. CDSCO fast-track approvals for bioequivalent second-line generics compress market entry timelines for domestic manufacturers. Mumbai and Delhi medical college hospitals anchor tertiary referral networks managing complex XDR-TB cases with novel diarylquinoline access.
South Africa
South Africa's provincial health systems deploy GeneXpert-equipped primary health centers to decentralize case detection and treatment initiation. The national health regulator enforces stringent bioequivalence standards for generic second-line drugs entering public tenders. KwaZulu-Natal and Gauteng provinces concentrate specialized MDR-TB treatment facilities with intensive monitoring capabilities.
Russia
Russia's oblast-level laboratory networks expand molecular resistance profiling to identify MDR-TB and XDR-TB cases earlier in the care cascade. The national pharmaceutical regulator maintains registration requirements aligned with WHO prequalification standards. Moscow and St. Petersburg anchor centralized procurement decisions for second-line anti-TB agents across the federal program.
United States
The United States sees concentrated demand through CDC-coordinated referral networks for imported drug-resistant TB cases. FDA orphan drug designations shape development timelines for novel anti-TB agents seeking market access. New York City and Los Angeles public health departments anchor specialized treatment programs with access to investigational regimens.
Brazil
Brazil's Sistema Único de Saúde integrates drug-resistant TB treatment into primary care networks with Ministry of Health procurement coordination. ANVISA registration pathways for second-line generics enable domestic manufacturing scale-up. São Paulo and Rio de Janeiro anchor reference laboratory networks conducting culture confirmation and resistance surveillance.
Drug Resistant Pulmonary Tuberculosis Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated oral regimen positioning and regional tender access. The market structure concentrates around vertically integrated pharmaceutical conglomerates with anti-TB manufacturing heritage and generic specialists competing on price in multidrug-resistant regimens. Three archetypes dominate: patented novel-agent developers, high-volume generic manufacturers, and hospital-channel legacy suppliers. Competitive moves center on regulatory harmonization alignment and manufacturing capacity expansion for high-potency API synthesis.
Within the patented-agent tier, Johnson & Johnson anchors market presence through bedaquiline franchise vertical integration. Lupin occupies the generic-specialist position competing on price across emerging market tenders. Pfizer Inc. exemplifies the legacy-supplier archetype sustaining relevance through established hospital channel relationships and fluoroquinolone supply chains.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis AG |
| Sanofi |
| Pfizer Inc. |
| Lupin |
| Hikma Pharmaceuticals |
| Endo International Plc |
| STI Pharma LLC |
| Macleods Pharmaceuticals Ltd. |
| Others |
Supply & Pricing Matrix
Centralized national TB programs with pooled purchasing power dominate procurement volumes, compressing price negotiations through volume-based tender commitments and Global Drug Facility aggregation. This buyer concentration forces manufacturers toward cost-recovery pricing models in public sector channels while preserving premium positioning for novel oral regimens with WHO prequalification status.
Pricing Analysis
Volume concentrates in generic second-line antibiotics where Indian and South African tenders drive cost-recovery pricing; margins concentrate in WHO-prequalified combination therapies with novel diarylquinoline content. Price differentiation rests on bioequivalence certification tier and manufacturing scale, with CDSCO-approved domestic producers commanding tender preference over import-dependent suppliers. Pricing pressure intensifies in aminoglycoside injectables as oral regimens displace parenteral protocols across national programs. Public health organizations exhibit highest price sensitivity; tertiary referral hospitals managing XDR-TB salvage cases demonstrate lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
Single-source vulnerability sits with fluoroquinolone and diarylquinoline API production concentrated in Chinese and Indian chemical manufacturing clusters. Active pharmaceutical ingredient synthesis draws from specialized containment infrastructure in these hubs, with downstream formulation distributed through WHO-prequalified manufacturing networks. Regulatory enforcement actions or environmental compliance events in these concentrated production zones cascade through global second-line therapy supply. Distribution runs through the Global Drug Facility to national program central warehouses, with last-mile delivery via provincial health systems to primary health centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification requirements erect a formidable cost-of-compliance barrier, with fragmented national registration pathways amplifying validation costs for non-aligned developers. This regulatory moat protects incumbent manufacturers with established dossier portfolios while filtering speculative entrants lacking sustained investment capacity.
For Market Incumbents: Anchor market position through backward integration into high-potency API synthesis capacity, securing captive supply of diarylquinoline intermediates against contract manufacturing bottlenecks. Deepen regulatory harmonization alignment with WHO's consolidated guidelines framework to streamline dossier submissions across multiple national programs. Defend against generic price erosion by accelerating fixed-dose combination development with pretomanid and linezolid content. For New Entrants and Emerging Players: Launch via decentralized primary health center distribution partnerships, bypassing entrenched hospital channel relationships held by legacy suppliers. Target underpenetrated Sub-Saharan African markets in Nigeria, Ethiopia, and Kenya where diagnostic infrastructure expansion outpaces therapy supply. Prioritize point-of-care directly observed therapy models that reduce patient travel burden and improve completion rates versus centralized hospital protocols. For Investors and Strategic Acquirers: The window for entry favors manufacturers with WHO-prequalified manufacturing infrastructure and established relationships with Global Fund procurement mechanisms. Acquisition targets should demonstrate regulatory dossier depth across multiple high-burden countries rather than single-market positioning. Monitor resistance surveillance data interoperability investments as the signal for national program consolidation and procurement centralization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Alignment | Unified dossier standards reduce redundant national registrations across India's CDSCO and South Africa's SAHPRA pathways. |
| High-Potency API Manufacturing Scale-Up | Containment infrastructure investments address qualification bottlenecks for bedaquiline and pretomanid synthesis. |
| Fixed-Dose Combination Development | Oral regimen innovation eliminates injectable requirements and compresses treatment timelines per WHO guideline updates. |
| Point-of-Care Distribution Partnerships | Primary health center deployment reduces patient travel burden and improves therapy completion rates in decentralized settings. |
| Resistance Surveillance Data Integration | Interoperable laboratory-to-treatment tracking systems enable real-world evidence generation for regimen optimization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across India, South Africa, and Russia. FDA orphan drug designations, WHO prequalification databases, ClinicalTrials.gov entries, and national tender documentation provided validation benchmarks. Bottom-up patient volume estimates by resistance profile converged with top-down procurement expenditure analysis through iterative triangulation.
Data-stream reconciliation across molecular diagnostics deployment rates, treatment initiation volumes, and regimen completion statistics informed the analytical framework across the analysis window. Segmentation modeling incorporated therapy area stratification, administration route evolution, and regional regulatory cluster differentiation. CAGRs derived from regression analysis of historical procurement volumes against projected case detection expansion and oral regimen adoption curves. Forecast inputs included GeneXpert MTB/RIF Ultra deployment timelines and national program formulary update schedules.
The model assumes a particular technology adoption path; alternative pathways for inhalation delivery systems or novel diagnostic-convergent therapy protocols would alter the outlook. Forecasts reflect assumptions regarding WHO guideline adherence rates, regulatory harmonization progress, and API supply continuity from concentrated manufacturing hubs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
H1N1 Vaccines Market