
 NF-KB Inhibitors Market | 2026-2036
NF-KB Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
NF-KB Inhibitors Market Foresight
China's biopharmaceutical manufacturing base is fragmenting as domestic CDMOs compete for NF-KB inhibitor contract production alongside established Western facilities. Takeda Pharmaceutical Company leverages its Osaka-based fermentation expertise to sustain biologics supply for autoimmune indications. Pfizer anchors North American small-molecule capacity through legacy chemistry platforms in Connecticut and Michigan. Amgen competes on antibody engineering depth, differentiating its pipeline through proprietary Fc-modification technologies.
NF-KB inhibitors comprise pharmacological agents that block nuclear factor-kappa B transcription factor activation through IKK complex inhibition, peptide interference, or decoy oligonucleotide binding, with molecular weights ranging from under 500 Da for synthetic small molecules to over 150 kDa for monoclonal antibodies; these compounds suppress pro-inflammatory cytokine cascades and oncogenic cell survival signals. Small molecules occupy the mature revenue base due to generic erosion of first-generation compounds, while antibodies capture expanding margin pools in refractory cancer settings. Biologics represent the fastest-growing product type as biosimilar competition lags and infusion-center reimbursement stabilizes.
FDA oncology review divisions, EMA's Committee for Medicinal Products for Human Use, and Japan's PMDA collectively enforce evolving immunogenicity testing standards that extend preclinical development timelines for novel biologic formats. The FDA's Project Optimus dose-optimization mandate is reshaping Phase I trial designs for small-molecule NF-KB pathway modulators, forcing sponsors to abandon maximum-tolerated-dose paradigms. Stakeholders must monitor how these regulatory shifts alter competitive positioning between antibody-dependent and antibody-independent mechanisms.
Market Dynamics
The FDA's Project Optimus dose-optimization mandate is forcing sponsors to abandon maximum-tolerated-dose paradigms for small-molecule NF-KB pathway modulators, extending Phase I timelines and reshaping competitive positioning between antibody-dependent and antibody-independent mechanisms.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy and fast track designations compress commercialization timelines for oncology biologics targeting refractory settings. Sponsors leverage these pathways to secure conditional market entry based on early efficacy signals.
- Biologics Manufacturing Scale-Up:Fermentation capacity expansion across Osaka-based facilities and Connecticut chemistry platforms supports antibody supply for autoimmune indications. CDMO competition is fragmenting production geography.
- Investigator-Initiated Study Sponsorship:The National Cancer Institute funds extensive combination regimen trials at academic medical centers, generating real-world evidence that drives hospital formulary adoption.
Market Restraints
- Immunogenicity Testing Burden:EMA's Committee for Medicinal Products for Human Use and Japan's PMDA enforce evolving standards that extend preclinical development timelines for novel biologic formats, adding 12-18 months to IND submission.
- Generic Erosion of Small-Molecule Base:Patent expiry on first-generation synthetic compounds compresses margins in the mature revenue segment, forcing portfolio pivots toward biologics.
- Input Cost Volatility:Recombinant protein production depends on stable supply of pharmaceutical-grade fetal bovine serum and chemically defined media components, with pricing fluctuations concentrated in North American and European supply chains.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:China's NMPA streamlined oncology review procedures create entry pathways for Western biologics, while domestic CDMOs compete for contract production alongside established facilities.
- Combination Regimen Expansion:Checkpoint inhibitor pairing protocols open new indication areas beyond monotherapy refractory settings, with academic medical centers leading protocol development.
- Decoy Oligonucleotide Formats:Peptide interference mechanisms and nucleic acid-based NF-KB suppression technologies represent white-space modalities distinct from established IKK complex inhibitors.
Industry Challenges
- Fc-Engineering Talent Scarcity:Antibody engineering depth requires specialized protein chemists and cell line development scientists, with competition for these skills intensifying between Amgen's proprietary modification platforms and emerging biotechs.
- Legacy System Integration:Hospital infusion centers must reconcile biologics reimbursement stabilization with electronic health record upgrades to support combination therapy tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NF-KB Inhibitors Market |
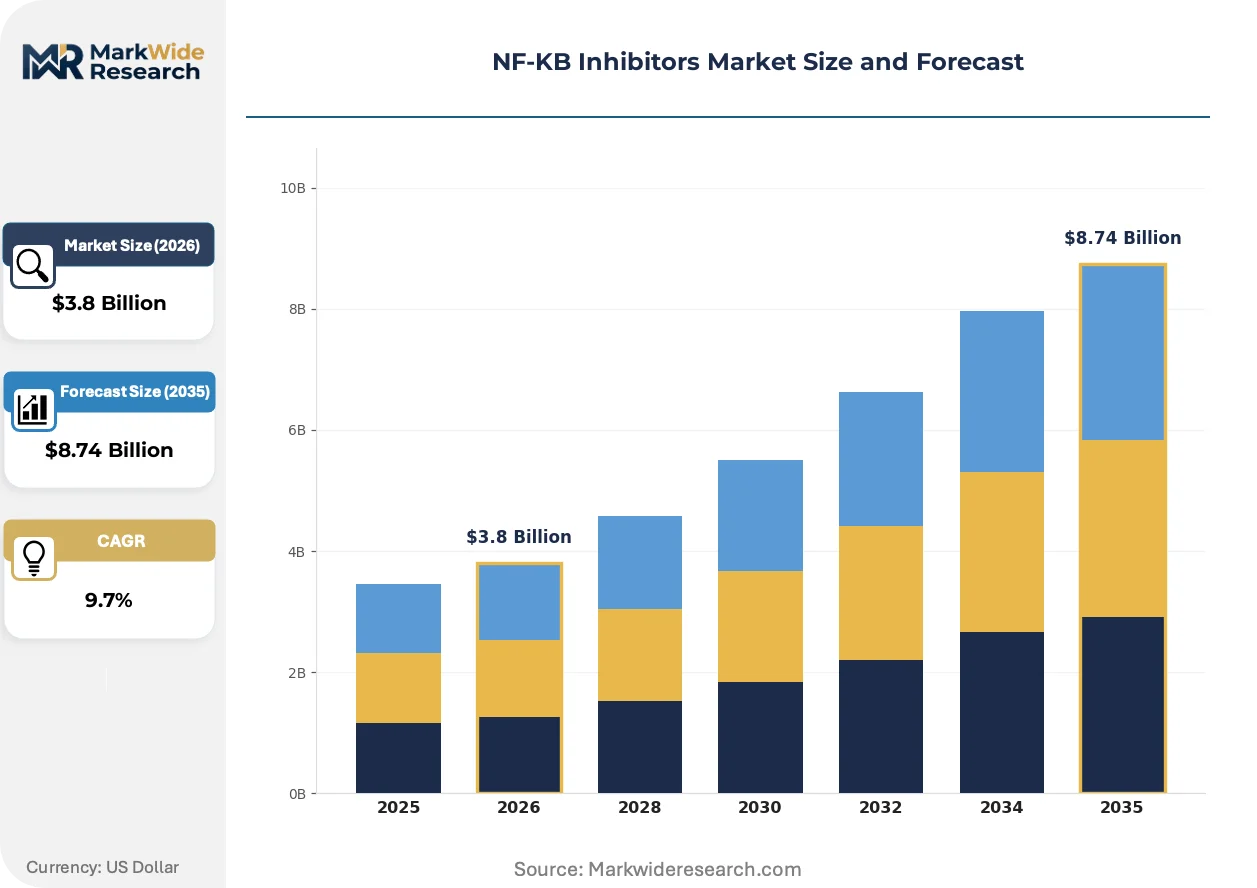
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Biologics, Peptides, Antibodies Therapy Area: Autoimmune Disorders, Cancer, Inflammatory Diseases, Infectious Diseases End User: Hospitals, Research Institutions, Pharmaceutical Companies, Clinics Distribution Channel: Direct Sales, Online Sales, Third-Party Distributors, Specialty Pharmacies |
| Companies Covered | Takeda Pharmaceutical Company, Pfizer, Amgen, Merck, Eisai, Mitsubishi Tanabe, Reata Pharmaceuticals, BioVie, Entero Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NF-KB Inhibitors Market Shifts & Advancements
Computational biology platforms are compressing target validation cycles for NF-KB pathway modulators, while regulatory science evolution and procurement model changes reshape how value flows through the value chain.
Artificial intelligence-driven molecular dynamics simulation is virtualizing the lead optimization process for small-molecule IKK complex inhibitors. Mid-cap biotechs and academic spinouts deploy these tools to reduce synthesis cycles by half. The technology is virtualizing traditional medicinal chemistry workflows, compressing the timeline between target identification and candidate nomination.
REACH regulation amendments and the EU Green Deal pharmaceutical manufacturing sustainability mandates impose solvent use restrictions on synthetic small-molecule production. Contract manufacturers in Germany and Switzerland retrofit legacy chemistry platforms to meet ECHA reporting thresholds. Small-molecule segments face the steepest compliance cost increases, accelerating geographic production shifts toward facilities with renewable energy sourcing.
Hospital procurement committees now require health technology assessment submissions alongside traditional clinical data packages for formulary inclusion. Academic medical centers in the United States and university hospitals in Germany lead this transition, displacing physician-directed purchasing with centralized pharmacy and therapeutics committee governance. This behavioral shift concentrates buying power and compresses switching cycles for incumbent agents.
NF-KB Inhibitors Market Segmentation
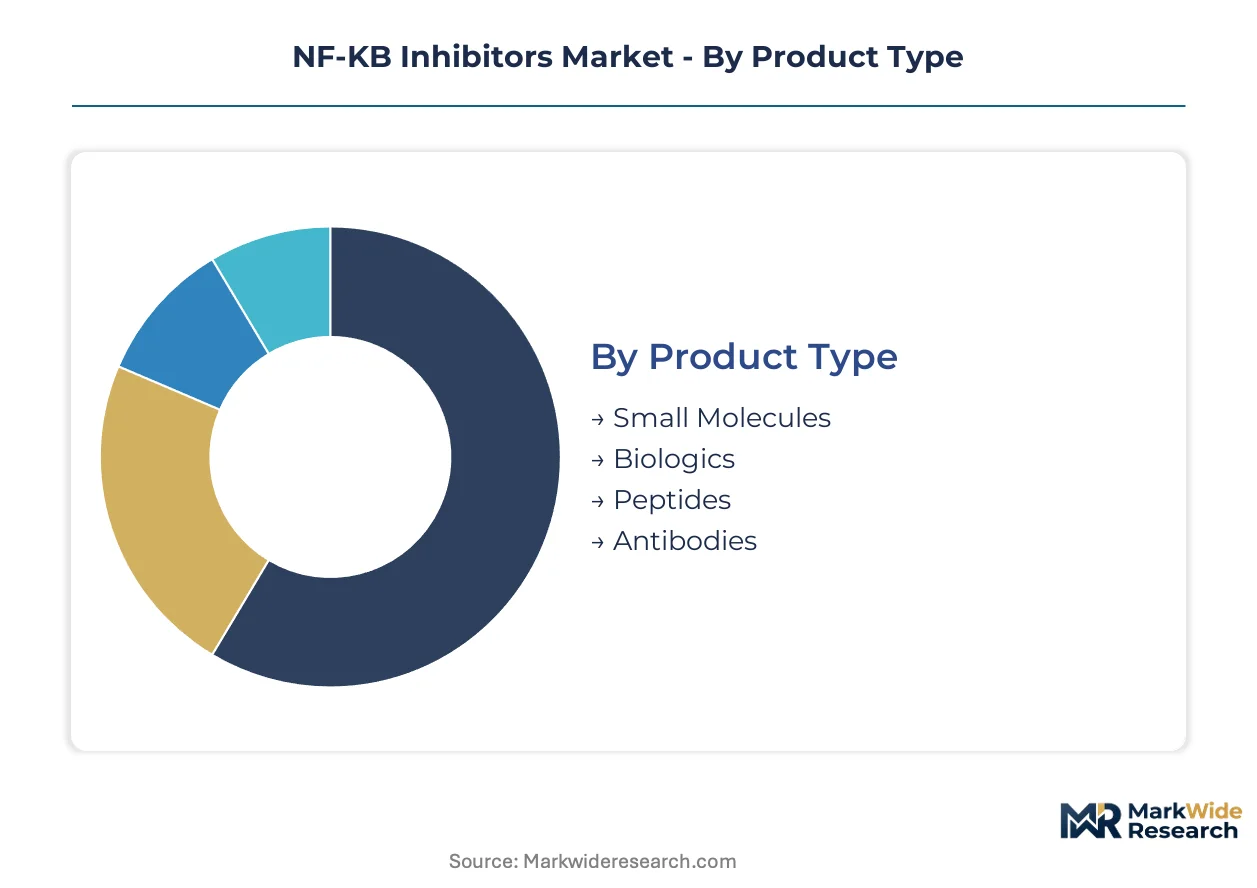
NF-KB inhibitors demand heterogeneous technical support across molecular formats, with biologics requiring cold-chain logistics and infusion-center training while small molecules need formulary navigation assistance. Service intensity directly correlates with product complexity and reimbursement pathway intricacy.
Product Type:
After-sales service intensity escalates with molecular weight and storage requirements, creating divergent margin structures across manufacturing modalities.
- Small Molecules:Synthetic compounds under 500 Da leverage established oral dosing protocols and ambient storage conditions. Hospital pharmacies in the United States prioritize these agents for outpatient oncology regimens due to familiar reimbursement coding and minimal cold-chain burden.
- Biologics:Recombinant proteins and monoclonal antibodies exceeding 150 kDa demand refrigerated distribution, infusion-center administration, and patient monitoring programs. Osaka-based fermentation facilities and Connecticut chemistry platforms anchor supply for autoimmune indications, with CDMO competition fragmenting production geography.
- Peptides:Intermediate molecular weight compounds require specialized formulation expertise to address stability and bioavailability challenges.
- Antibodies:Fc-modification technologies differentiate pipeline candidates, with proprietary engineering platforms commanding premium positioning in refractory cancer settings.
Small molecules hold the largest share; momentum sits with biologics.
Therapy Area:
Cost tier stratification separates chronic disease maintenance from acute oncology interventions, with pricing power concentrating in refractory indications.
- Autoimmune Disorders:Rheumatoid arthritis and inflammatory bowel disease indications generate recurring revenue through long-term administration. Takeda Pharmaceutical Company sustains supply through legacy fermentation expertise, with infusion-center reimbursement stabilizing demand in North American markets.
- Cancer:Solid tumor and hematologic malignancy applications command premium pricing within academic medical center procurement frameworks. The National Cancer Institute sponsors extensive investigator-initiated combination studies, generating real-world evidence that drives formulary adoption.
- Inflammatory Diseases:Chronic obstructive pulmonary disease and dermatologic conditions represent volume opportunities with compressed margins due to competitive generic pressure.
- Infectious Diseases:Emerging applications in viral pathogenesis modulation attract early-stage development funding from specialized biotech investors.
Oncology applications command premium positioning; autoimmune disorders deliver volume stability.
End User:
Customer type determines purchasing authority, with centralized pharmacy committees displacing physician-directed procurement in high-volume settings.
- Hospitals:Academic medical centers anchor demand for combination regimens, with pharmacy and therapeutics committees governing formulary inclusion through health technology assessment protocols. Electronic health record upgrades support combination therapy tracking requirements.
- Research Institutions:National Cancer Institute-funded laboratories generate preclinical validation data that shapes subsequent commercial development priorities.
- Pharmaceutical Companies:Sponsors leverage accelerated approval pathways to compress timelines between Phase I initiation and conditional market entry.
- Clinics:Community oncology practices concentrate on oral small-molecule dispensing with limited infusion capacity.
Hospital systems concentrate purchasing power; research institutions shape pipeline direction.
Distribution Channel:
Supply concentration varies by product thermal stability and regulatory handling requirements, with specialty channels capturing biologics margin pools.
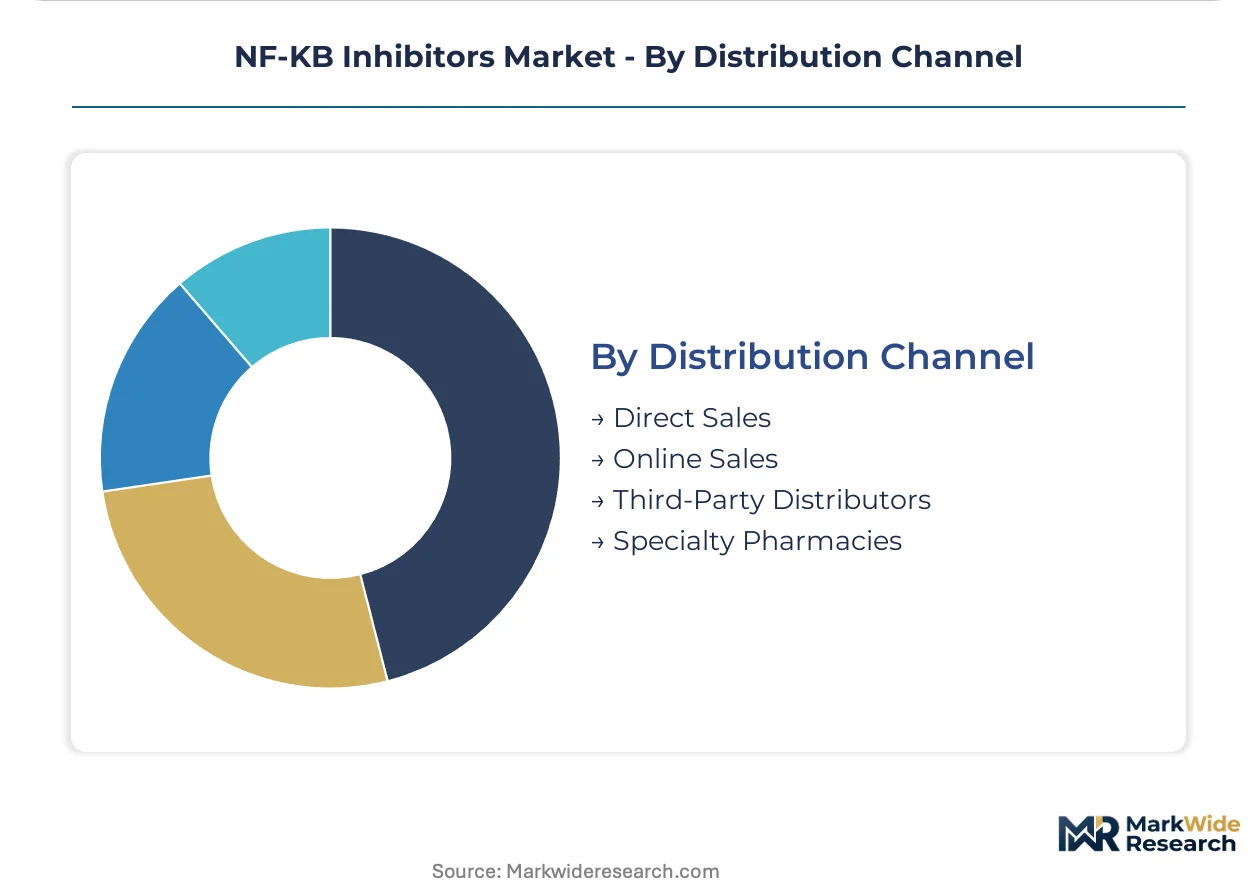
- Direct Sales:Manufacturer-led distribution dominates biologics supply to hospital infusion centers, with field reimbursement specialists supporting prior authorization navigation. Amgen and Pfizer deploy dedicated account teams for academic medical center penetration.
- Specialty Pharmacies:Cold-chain-capable distributors capture high-touch patient support services for self-administered biologics, with adherence programs extending therapy duration.
- Third-Party Distributors:Regional wholesalers handle small-molecule volume for community pharmacy networks with standardized storage protocols.
- Online Sales:Digital procurement portals gain traction for research-grade compounds and reference standards, with institutional purchasing cards streamlining requisition workflows.
Direct sales channels retain biologics margin; specialty pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA anchors the dominant geography through accelerated approval pathways and National Cancer Institute sponsorship of combination regimen trials. Investigator-initiated studies at academic medical centers generate real-world evidence that drives hospital formulary adoption. Procurement concentration in the United States shapes global pricing benchmarks and clinical trial design standards.
United States
Academic medical centers in Boston and Houston expand procurement of NF-KB inhibitors for oncology combination regimens. The FDA's Project Optimus dose-optimization mandate extends Phase I timelines for small-molecule pathway modulators. Connecticut and Michigan chemistry platforms anchor North American small-molecule manufacturing capacity for autoimmune indications.
Germany
University hospitals in Munich and Heidelberg lead health technology assessment submissions for formulary inclusion of biologic NF-KB inhibitors. ECHA reporting thresholds under REACH amendments drive solvent use restrictions on synthetic small-molecule production. Contract manufacturers in the Rhine-Ruhr region retrofit legacy chemistry platforms to meet EU Green Deal pharmaceutical sustainability mandates.
Japan
Osaka-based fermentation facilities sustain biologics supply for autoimmune indications through Takeda's legacy manufacturing expertise. PMDA immunogenicity testing standards extend preclinical development timelines for novel biologic formats. The Kansai region concentrates antibody engineering talent and cell line development capabilities for Fc-modification technologies.
China
Domestic CDMOs in Shanghai and Suzhou compete for NF-KB inhibitor contract production alongside established Western facilities. NMPA streamlined oncology review procedures create entry pathways for Western biologics seeking market access. The Yangtze River Delta biopharmaceutical manufacturing base fragments as local players expand fermentation and chemistry platform capabilities.
Switzerland
Swissmedic enforces evolving standards for biologic development that align with EMA Committee for Medicinal Products for Human Use requirements. Basel and Zurich anchor specialized formulation expertise for peptide-based NF-KB suppression technologies. Contract research organizations in the Lake Geneva region support decoy oligonucleotide preclinical validation for emerging modalities.
NF-KB Inhibitors Market Competitive Landscape
Capability concentration sits with antibody engineering specialists; scale advantage sits with diversified pharmaceutical conglomerates. The market structure tiers between biologics innovators with proprietary Fc-modification platforms and small-molecule incumbents defending mature revenue bases against generic erosion. Three archetypes dominate: fermentation-based biologics manufacturers, synthetic chemistry platform operators, and peptide/nucleic acid modality specialists. Competitive moves concentrate on capacity expansion in Osaka and Connecticut manufacturing clusters, plus strategic partnerships to secure CDMO access in China's fragmenting production geography.
Among diversified pharmaceutical conglomerates, Takeda Pharmaceutical Company and Pfizer occupy positions spanning biologics and small-molecule segments. Takeda leverages Osaka-based fermentation expertise to sustain supply for autoimmune indications. Pfizer anchors North American capacity through legacy chemistry platforms. Amgen sits within the biologics innovation tier, differentiating through antibody engineering depth and proprietary Fc-modification technologies. These three entities exemplify how geographic manufacturing concentration and molecular format specialization determine competitive positioning.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company |
| Pfizer |
| Amgen |
| Merck |
| Eisai |
| Mitsubishi Tanabe |
| Reata Pharmaceuticals |
| BioVie |
| Entero Therapeutics |
| Others |
Supply & Pricing Matrix
Single-source dependency on pharmaceutical-grade fetal bovine serum from North American and European supply chains determines both pricing tier spreads and supply chain shape for NF-KB inhibitor manufacturing. Cost compression in small-molecule segments accelerates geographic production shifts toward facilities with renewable energy sourcing, while biologics command premium positioning through cold-chain infrastructure investments.
Pricing Analysis
United States hospital procurement committees pay 15-25% premiums over German university hospital systems for equivalent biologic NF-KB inhibitors due to infusion-center reimbursement stabilization and prior authorization support services. Three-tier pricing structure across premium, standard, and economy levels separates Fc-modified antibodies from conventional monoclonals from oral small-molecule generics. Price differentiation hinges on immunogenicity testing documentation and proprietary cell line development heritage. Cost compression in synthetic small-molecule segments intensifies as patent expiry erodes first-generation compound margins, forcing portfolio pivots toward biologics. Community oncology practices exhibit highest price sensitivity due to limited infusion capacity and formulary budget constraints, while academic medical centers prioritize clinical efficacy data over acquisition cost.
Supply Chain Analysis
Export-control regimes on dual-use biologics manufacturing equipment limit technology transfer to CDMOs in China's Yangtze River Delta, constraining capacity expansion for Western sponsors. Manufacturing gravity centers on Japan's Osaka fermentation corridor, Connecticut-Michigan chemistry platforms, and Switzerland's specialized peptide formulation clusters. Raw material dependencies include recombinant protein production feeds, chemically defined media components, and pharmaceutical-grade solvents subject to REACH amendments. Single-source vulnerability concentrates in fetal bovine serum supply from North American and European collection facilities. Distribution runs through manufacturer-led direct sales for hospital infusion centers, with specialty pharmacies capturing self-administered biologics margin pools through cold-chain logistics and patient adherence programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across China's biopharmaceutical manufacturing base creates entry niches as domestic CDMOs compete for contract production alongside established Western facilities. Hospital procurement centralization displaces physician-directed purchasing, opening specialized service provider opportunities.
For Market Incumbents: Build manufacturing moats through captive fermentation capacity in Osaka and Connecticut chemistry platforms to defend against biosimilar competition and generic small-molecule erosion. Anchor supply security through backward integration into cell line development capabilities and proprietary Fc-modification technologies. Secure hospital formulary position by embedding field reimbursement specialists within academic medical center pharmacy and therapeutics committees. Prioritize health technology assessment submission capabilities to meet centralized procurement governance requirements. For New Entrants and Emerging Players: Pursue decoy oligonucleotide and peptide interference modalities as white-space technologies distinct from established IKK complex inhibitors. Target China's NMPA streamlined oncology review pathway for Western biologics seeking market access under reduced regulatory friction. Penetrate the Asia-Pacific autoimmune indication segment where domestic CDMO competition has fragmented production geography and created partnership opportunities. Establish go-to-market position through investigator-initiated study sponsorship aligned with National Cancer Institute funding priorities. For Investors and Strategic Acquirers: The market sits at a modality-transition phase that favors antibody engineering specialists with proprietary Fc-modification platforms over small-molecule incumbents defending eroding revenue bases. Long-term viability over the next decade hinges on securing manufacturing scale in renewable-energy-sourced facilities and navigating evolving FDA Project Optimus dose-optimization mandates. Acquisition targets should demonstrate cell line development depth and cold-chain distribution infrastructure. Watch for inflection signals in biosimilar approval velocity for reference biologics and CDMO consolidation patterns in China's fragmenting production geography.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Osaka fermentation expansion supports biologics supply for autoimmune indications through Takeda's legacy expertise. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses commercialization timelines for oncology biologics in refractory settings. |
| Pipeline Diversification | Decoy oligonucleotide formats open white-space modalities beyond established IKK complex inhibition mechanisms. |
| Strategic Partnership | CDMO alliances in China's Yangtze River Delta secure contract production capacity amid fragmenting geography. |
| Clinical Trial Advancement | National Cancer Institute-sponsored combination studies generate real-world evidence driving hospital formulary adoption. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation across molecular format segments ensured analytical robustness.
Scenario-bracketing framed the analytical approach across the analysis window, with sensitivity testing on immunogenicity testing timeline extensions and biosimilar entry velocity. Segmentation dimensions modeled include product type, therapy area, end user, and distribution channel complexity. CAGRs derived from normalized growth rate convergence across independent forecasting approaches. Industry-specific inputs incorporated fermentation capacity utilization rates and health technology assessment submission success patterns.
Macroeconomic conditions sit as an overlay; deviation in biologics reimbursement policy, pharmaceutical input commodity pricing, or trade restriction intensity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval pathway efficiency and manufacturing scale-up feasibility. Material shifts in FDA Project Optimus implementation scope or EMA immunogenicity testing standard evolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Olaparib API Market