
 Global Recombinant Proteins Market | 2026-2036
Global Recombinant Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recombinant Proteins Market Foresight
Skilled bioprocess engineers familiar with transient transfection workflows is collapsing across North America and Europe, forcing contract manufacturers to raise retention premiums and extend project timelines. Thermo Fisher Scientific leverages its integrated Gibco media-to-protein pipeline to capture pharmaceutical outsourcing contracts. Merck KGaA anchors European supply through its BioReliance testing and MilliporeSigma filtration franchises. Sino Biological competes on cost-engineered HEK293 and CHO expression platforms, undercutting Western peers on bulk cytokine tenders.
Recombinant proteins are heterologous polypeptides produced via engineered host cells—bacterial, yeast, insect, or mammalian systems—where cloned genes drive expression of target molecules with defined post-translational modifications, purity grades, and endotoxin thresholds for therapeutic or analytical use. Their primary purpose spans drug substance manufacturing, assay calibration, and cell culture supplementation in regulated environments. Cytokines and growth factors command premium positioning within the product type taxonomy as CAR-T and stem cell therapy developers scale GMP procurement. Expression systems technology differentiates vendor capabilities, with transient mammalian platforms capturing share from stable cell line approaches in early-phase biopharma workflows.
FDA biologics guidance, EMA GMP Annex 1 revisions, and ISO 13485 diagnostics standards collectively elevate documentation burdens for protein suppliers seeking multi-jurisdiction market access. These frameworks compel investment in quality management systems, audit trails, and host cell protein clearance validation that smaller producers struggle to fund. Stakeholders must weigh captive expression investments against supplier consolidation risks as qualification timelines lengthen and geographic concentration of manufacturing assets intensifies.
Market Dynamics
Transient mammalian expression platforms are compressing stable cell line development timelines, forcing vendors to reconfigure capacity allocation between early-phase speed and late-phase scale economics.
Growth Catalysts
- FDA biologics guidance:Accelerated approval pathways for cell therapies multiply demand for GMP-grade cytokines with validated documentation trails.
- CAR-T manufacturing workflows:Commercial-scale autologous cell production requires exponential growth factor inputs, pulling specialized recombinant protein volumes upward.
- Chinese CDMO expansion:Domestic mammalian expression capacity buildouts for export markets concentrate procurement power in East Asian supply hubs.
Market Restraints
- Fetal bovine serum cost volatility:Mammalian cell culture media inputs face price instability from livestock supply shocks and ethical sourcing constraints.
- Supplier qualification concentration:End users in Germany, Switzerland, and the United States lock into audited vendor lists, raising switching costs and freezing out emerging producers.
- Host cell protein clearance limits:Residual immunogenic protein detection thresholds tighten faster than analytical method sensitivity advances, constraining batch release.
Strategic Opportunities
- India biopharma manufacturing:CDSCO streamlined approval corridors and PLI scheme incentives attract recombinant protein investment for domestic and export supply.
- Continuous bioprocessing integration:Perfusion-based mammalian expression converges with real-time quality analytics to enable ton-scale protein output from compact footprints.
- ISO 13485 diagnostics tier:In vitro diagnostic manufacturers seek recombinant protein reference standards with certified metrological traceability, opening premium pricing tiers.
Industry Challenges
- Transient transfection expertise scarcity:Skilled bioprocess engineers capable of optimizing plasmid-to-protein yields command retention premiums that compress contract manufacturer margins.
- GMP Annex 1 compliance timelines:EMA contamination control revisions extend facility qualification periods, delaying revenue recognition for new production lines.
- Multi-jurisdiction dossier divergence:FDA, EMA, and NMPA filing requirements for host cell protein specifications lack harmonization, duplicating analytical validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recombinant Proteins Market |
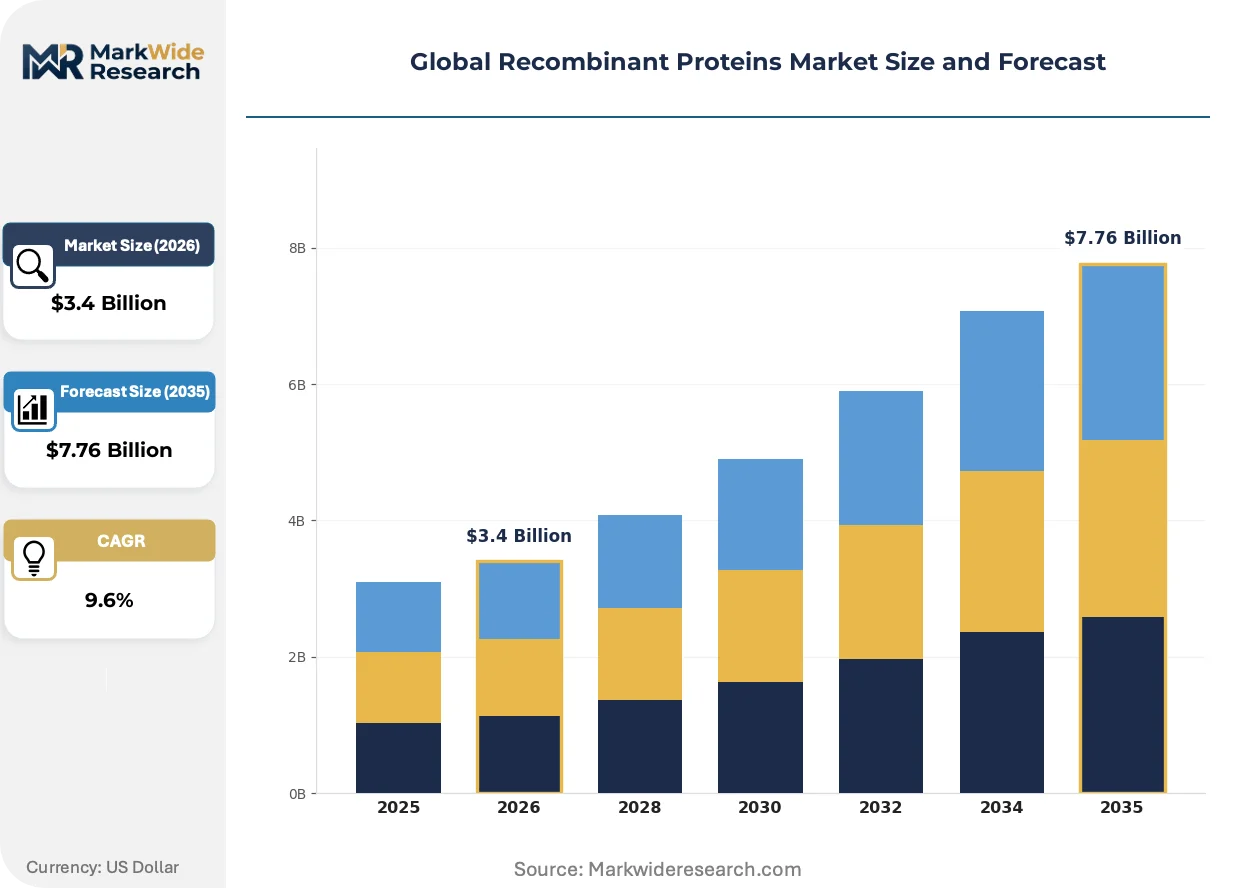
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.76 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormones, Cytokines, Enzymes, Antibodies, Vaccines Technology: Gene Cloning, Protein Engineering, Expression Systems, Purification Methods, Bioinformatics Tools Application: Biopharmaceuticals, Food Additives, Agriculture, Diagnostics, Research & Development End User: Pharmaceutical Companies, Biotech Firms, Academic Institutions, Diagnostic Laboratories, Agricultural Firms |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Bio-Techne, Bio-Rad Laboratories, GenScript Biotech, Sino Biological, Abcam plc, Proteintech Group, BPS Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recombinant Proteins Market Shifts & Advancements
Expression system diversification is fragmenting vendor specialization patterns as buyers prioritize speed-to-clinic over single-platform loyalty in early development phases.
Automated transient transfection workstations are fragmenting the traditional stable cell line monopoly in preclinical protein production. Biopharmaceutical discovery groups at contract research organizations now specify 4-week turnaround guarantees for milligram-scale material. This compression is eroding the economic case for early-phase stable pool investment and reallocating capital toward modular, disposable bioreactor infrastructure.
EMA GMP Annex 1 revisions on contamination control strategy now mandate closed-system processing for Grade A interventions in aseptic manufacturing. European recombinant protein suppliers must retrofit isolator technology or restrict operator access protocols, elevating facility capital intensity. German and Swiss producers with existing barrier technology capture qualification advantages as buyers consolidate approved vendor lists.
Cell therapy developers now unbundle cytokine procurement from media supply agreements, conducting separate competitive tenders for GMP-grade growth factors. This disintermediation pressures incumbent media-to-protein integrated suppliers to defend position through analytical service bundling rather than captive chemistry. The pattern concentrates in United States and Chinese manufacturing clusters where CAR-T process development teams negotiate direct cytokine sourcing from specialized recombinant protein houses.
Global Recombinant Proteins Market Segmentation
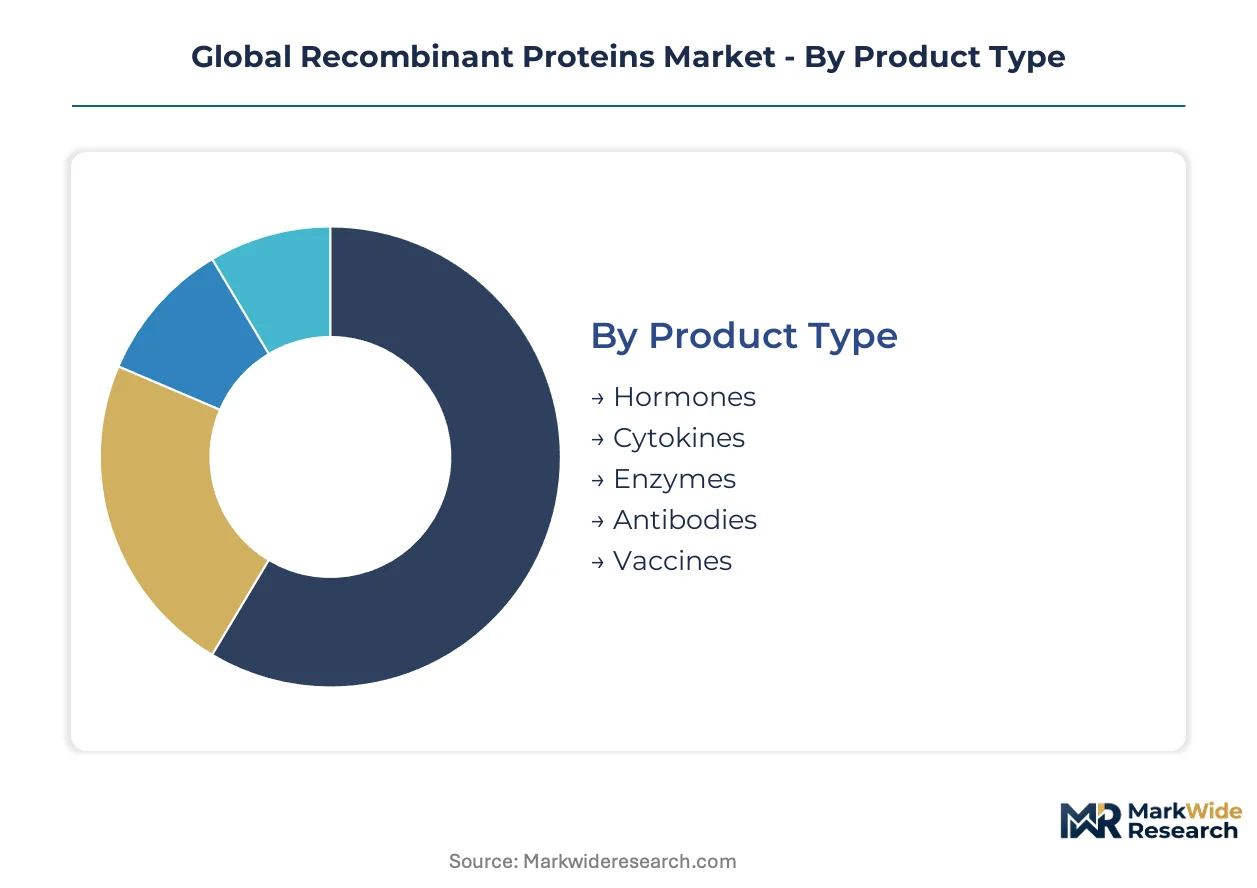
Recombinant protein segmentation reflects divergent regulatory burdens across therapeutic versus analytical applications. FDA biologics guidance, EMA GMP Annex 1, and ISO 13485 diagnostics standards each impose distinct purity, documentation, and host cell protein clearance thresholds that reshape vendor specialization and buyer procurement patterns.
Product Type:
Regulatory differentiation separates pharmaceutical-grade cytokines from research-use hormones through endotoxin limits and GMP documentation depth.
- Cytokines:These signaling polypeptides require sub-picogram endotoxin thresholds and validated host cell protein clearance for CAR-T and stem cell therapy manufacturing. Demand concentrates in United States and Chinese manufacturing clusters where FDA and NMPA cell therapy approvals multiply GMP procurement volumes.
- Antibodies:Monoclonal and polyclonal recombinant formats serve as therapeutic drug substances, diagnostic reagents, and affinity purification ligands. Biopharmaceutical companies in Germany and Switzerland lock into long-term supply agreements with audited vendors to secure EMA-compliant documentation trails for commercial release.
- Hormones:Insulin analogs and growth hormones dominate therapeutic applications with established pharmacopeial monographs.
- Enzymes:Industrial and diagnostic catalysts face lower purity tiers than injectable-grade segments.
- Vaccines:Recombinant subunit and virus-like particle formats require specialized adjuvant compatibility testing.
Established volume favors cytokines; emerging adoption favors antibodies.
Technology:
Cost tier stratification separates premium mammalian expression from economy bacterial platforms through post-translational modification fidelity.
- Expression Systems:Mammalian, yeast, insect, and bacterial hosts each yield distinct glycosylation patterns that determine therapeutic eligibility. Transient mammalian platforms capture early-phase biopharma workflows in Boston and San Diego clusters where speed-to-clinic overrides per-gram economics.
- Purification Methods:Chromatography, filtration, and precipitation sequences remove host cell proteins, endotoxins, and aggregates to specified thresholds. CDMOs in China expand affinity resin capacity to serve export markets demanding EMA and FDA-validated clearance protocols.
- Gene Cloning:Vector design and host cell line development establish expression stability foundations.
- Protein Engineering:Fusion tags and site-directed mutagenesis optimize stability and activity profiles.
- Bioinformatics Tools:Sequence optimization and structure prediction accelerate construct design cycles.
Premium positioning concentrates in mammalian expression; cost-engineered competition clusters in bacterial alternatives.
Application:
Application maturity determines margin structure, with therapeutic manufacturing commanding qualification premiums over analytical and industrial uses.
- Biopharmaceuticals:Drug substance and cell culture supplement applications impose the most stringent GMP, pharmacopeial, and host cell protein documentation burdens. FDA accelerated approval pathways for gene and cell therapies concentrate cytokine demand in United States manufacturing corridors.
- Diagnostics:In vitro diagnostic reference standards and immunoassay components require ISO 13485 certification and metrological traceability. European IVD manufacturers in France and Germany seek recombinant protein suppliers with notified body accreditation for CE-marked kit integration.
- Research & Development:Discovery-phase protein procurement tolerates research-grade specifications at reduced price points.
- Food Additives:Enzyme preparations face FSSAI, FDA, and EFSA safety evaluations for consumption.
- Agriculture:Biopesticide and feed enzyme applications navigate EPA and national agrochemical registration pathways.
Margin concentration favors biopharmaceuticals; volume expansion favors diagnostics.
End User:
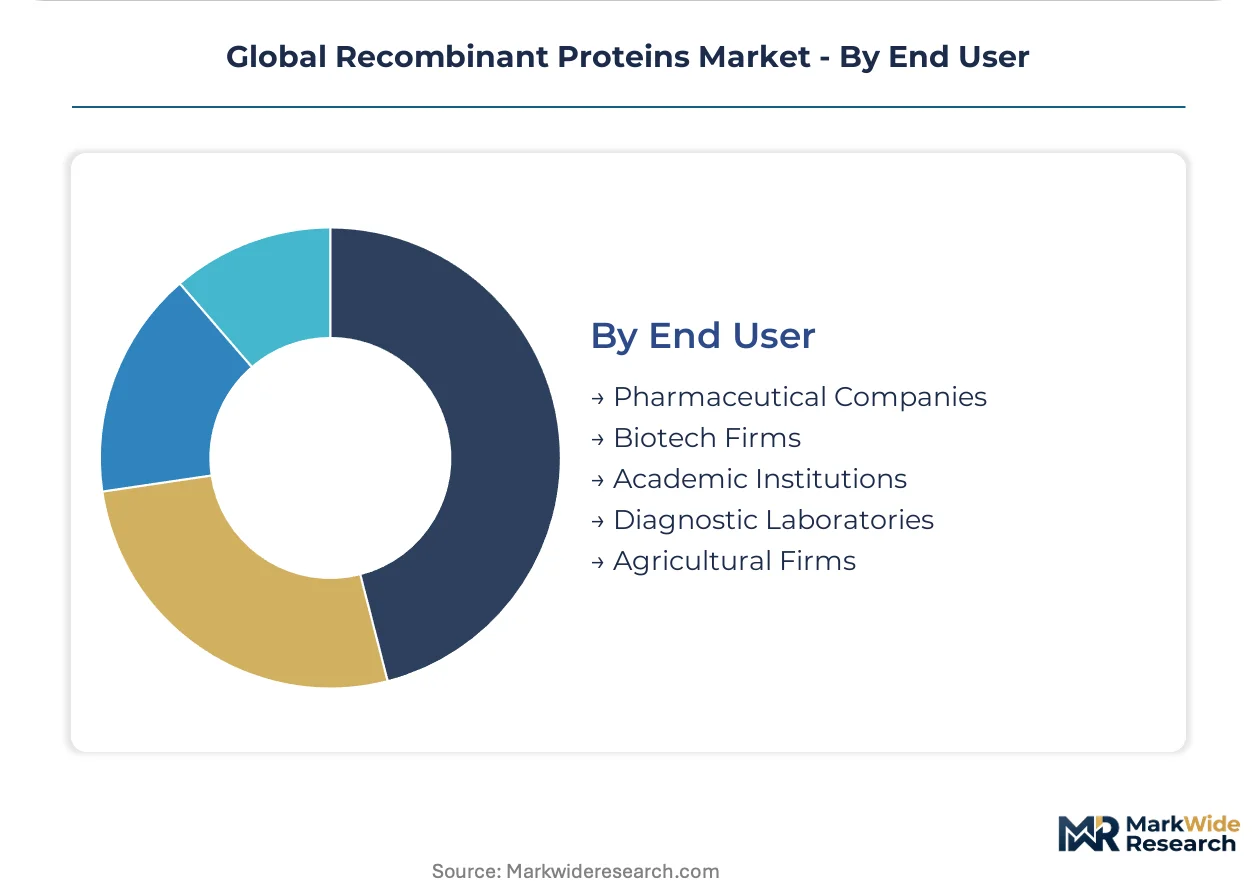
Customer type dictates procurement sophistication, with pharmaceutical companies demanding audit-intensive vendor qualification that academic institutions bypass.
- Pharmaceutical Companies:Large-scale biologics manufacturers require multi-year supply agreements with locked pricing, dedicated capacity, and regulatory filing support. Swiss and German headquarters teams enforce EMA GMP Annex 1 compliance through on-site vendor audits and closed-system processing mandates.
- Biotech Firms:Venture-backed developers prioritize transient platform speed and flexible batch sizing for clinical candidate progression. Cambridge and South San Francisco clusters negotiate milestone-based procurement contracts with CDMO partners.
- Academic Institutions:Grant-funded research groups optimize for catalog availability and educational pricing tiers.
- Diagnostic Laboratories:Clinical and reference labs seek lot-to-lot consistency for assay validation stability.
- Agricultural Firms:Seed and crop protection companies evaluate recombinant proteins for field efficacy and regulatory registration cost.
Procurement complexity favors pharmaceutical companies; flexibility demands favor biotech firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for cell therapies anchor United States demand, while EMA contamination control mandates reshape European supplier qualification. Chinese CDMO capacity buildouts and India's PLI incentives fragment manufacturing gravity across three continents.
United States
CAR-T commercial manufacturing and stem cell therapy workflows multiply GMP-grade cytokine procurement volumes. FDA biologics guidance on accelerated approval pathways tightens documentation requirements for host cell protein clearance. The Greater Boston and San Diego biotech clusters concentrate transient mammalian platform adoption as speed-to-clinic overrides per-gram economics.
Germany
EMA GMP Annex 1 revisions on closed-system processing elevate capital intensity for aseptic recombinant protein production. German pharmaceutical headquarters enforce vendor qualification through on-site audits and barrier technology mandates. The Rhine-Main and Upper Bavaria regions concentrate EMA-compliant CDMO capacity as buyers consolidate approved supplier lists.
China
Domestic mammalian expression capacity buildouts for export markets concentrate procurement power in East Asian supply hubs. NMPA cell therapy approval pathways multiply demand for GMP-grade growth factors with validated documentation trails. The Yangtze River Delta and Pearl River Delta clusters expand HEK293 and CHO platform capacity to serve FDA and EMA export requirements.
Switzerland
Swissmedic pharmaceutical manufacturing standards and EMA alignment create qualification advantages for barrier-technology-equipped producers. Basel and Zurich headquarters of large biologics manufacturers lock into multi-year supply agreements with audited vendors. The Swiss Romandy region anchors specialized recombinant protein capacity for injectable-grade therapeutic applications.
India
CDSCO streamlined approval corridors and PLI scheme incentives attract recombinant protein investment for domestic and export supply. Contract manufacturers in Maharashtra and Gujarat expand bacterial and yeast expression capacity to serve research-grade and diagnostic-tier demand. The Hyderabad-Genome Valley cluster builds mammalian platform expertise for biopharmaceutical outsourcing contracts.
Global Recombinant Proteins Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in recombinant protein supply. The upper tier combines media-to-protein pipelines with regulatory filing support capabilities. Three archetypes dominate: integrated life science conglomerates with end-to-end workflows, CDMOs with mammalian expression specialization, and catalog suppliers with cost-engineered bacterial platforms. Capacity expansion and qualification-driven vendor consolidation represent the dominant competitive moves as end users lengthen approved supplier lists.
Among integrated life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying the media-to-protein pipeline archetype, while Merck KGaA anchors European supply through testing and filtration franchise integration. Sino Biological sits within the cost-engineered expression platform tier, representing competitive positioning on bulk cytokine tenders against Western peers. These three companies illustrate the geographic and capability fragmentation shaping procurement decisions across United States, European, and Chinese manufacturing clusters.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Bio-Techne |
| Bio-Rad Laboratories |
| GenScript Biotech |
| Sino Biological |
| Abcam plc |
| Proteintech Group |
| BPS Bioscience |
| Others |
Supply & Pricing Matrix
HEK293 and CHO platform scale economies in Chinese CDMOs compress per-gram production costs for bulk cytokines while elevating price floors for GMP-grade materials in German and Swiss facilities. This divergence concentrates supply-side pricing power among barrier-technology-equipped producers serving FDA and EMA qualification protocols.
Pricing Analysis
Geographic price spreads between Yangtze River Delta manufacturing clusters and Rhine-Main production hubs exceed threefold for equivalent GMP-grade cytokines. Pricing stratifies across pharmaceutical-grade, diagnostic-tier, and research-use certification levels, with endotoxin documentation depth as the primary differentiation driver. Cost compression in bulk bacterial expression is intensifying because Sino Biological and GenScript Biotech expand HEK293 capacity for export tenders. Academic institutions exhibit highest price sensitivity; CAR-T developers show lowest sensitivity due to captive qualification timelines.
Supply Chain Analysis
China, Germany, and the United States anchor recombinant protein manufacturing capacity across distinct quality tiers. Mammalian cell culture media draws from fetal bovine serum suppliers in Australia and New Zealand, affinity resin producers in the United States, and filtration membrane manufacturers in Germany. Single-source vulnerability concentrates in validated plasmid DNA supply for transient transfection workflows. Distribution runs through audited vendor lists maintained by Swiss and German pharmaceutical headquarters, with direct procurement emerging in United States biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical procurement teams that unbundle cytokine sourcing from media supply agreements, fragmenting incumbent bundling strategies.
For Market Incumbents: Compound analytical service bundling with GMP-grade production to defend against specialized recombinant protein houses capturing direct cytokine tenders from CAR-T developers. Expand barrier-technology capacity in the Swiss Romandy region to exploit EMA GMP Annex 1 qualification advantages. Invest in host cell protein clearance validation to tighten batch release thresholds beyond emerging competitor capabilities. For New Entrants and Emerging Players: Rapid-turnaround transient transfection services for preclinical milligram-scale production represent the most penetrable white-space target, as Boston and San Diego biotech clusters prioritize four-week delivery guarantees. Target ISO 13485 diagnostic-tier reference standards with certified metrological traceability for European IVD manufacturers. Pursue milestone-based procurement contracts with venture-backed developers in Cambridge and South San Francisco. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CDMOs with locked multi-year supply agreements and dedicated capacity arrangements. Long-term viability rests on regulatory filing support capabilities and multi-jurisdiction dossier expertise. Target acquisition archetype: mid-scale mammalian expression specialists with existing FDA master files and EMA compliance history. Signal to watch: CAR-T therapy approval velocity at FDA and NMPA as cytokine demand multiplier.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Annex 1 Compliance Investment | EMA contamination control mandates retrofit isolator technology, elevating capital barriers for European suppliers. |
| Transient Platform Speed Guarantee | Four-week turnaround contracts capture preclinical protein demand from Boston and San Diego biotech clusters. |
| Host Cell Protein Clearance Validation | FDA biologics guidance tightens detection thresholds, favoring producers with advanced analytical method investment. |
| Multi-Jurisdiction Dossier Harmonization | FDA, EMA, and NMPA filing divergence duplicates validation expenditure, rewarding regulatory expertise concentration. |
| Cytokine Procurement Unbundling | CAR-T developers conduct separate competitive tenders, disintermediating integrated media-to-protein suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA biologics guidance documents, EMA GMP Annex 1 revisions, and ISO 13485 certification databases. Primary interviews engaged bioprocess engineering directors, regulatory affairs leads at recombinant protein suppliers, CAR-T manufacturing heads, and diagnostic procurement managers. Secondary validation drew from ClinicalTrials.gov cell therapy enrollment data, CDSCO PLI scheme disclosures, and customs records of affinity resin imports. Bottom-up capacity utilization estimates triangulate against top-down biopharmaceutical production forecasts.
Segmentation dimensions modeled span product type, expression system technology, application tier, and end-user sophistication across the projection horizon. CAGRs derive from capacity expansion announcements, qualification timeline data, and therapeutic pipeline progression rates. Forecast inputs incorporate CAR-T therapy approval trajectories at FDA and NMPA, plus mammalian expression platform adoption curves in Chinese CDMOs.
Underlying assumptions cover sustained cell therapy manufacturing scale-up, stable fetal bovine serum supply from Australia and New Zealand, and continued EMA-FDA regulatory alignment on host cell protein specifications, with deviation risk concentrated in transient transfection expertise scarcity and multi-jurisdiction dossier divergence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
6-Azauracil Market