
 Macrolide Antibiotics Market | 2026-2036
Macrolide Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Macrolide Antibiotics Market Foresight
Generic formulation revenue is narrowing as price erosion in oral azithromycin compresses margins across mature markets. Pfizer Inc. sustains branded positioning through specialty injectable macrolides in hospital channels. Teva Pharmaceutical Industries Ltd. leverages vertical manufacturing scale to dominate generic oral suspension supply. Sun Pharmaceutical Industries Ltd. anchors its portfolio on cost-optimized production from Indian facilities serving regulated and emerging markets.
Macrolide antibiotics constitute a class of bacteriostatic agents characterized by a large lactone ring with attached deoxy sugars, typically synthesized through fermentation of Streptomyces species followed by semi-synthetic modification to improve acid stability and tissue penetration. These agents inhibit bacterial protein synthesis by binding reversibly to the 50S ribosomal subunit, delivering broad-spectrum coverage against Gram-positive cocci, atypical pathogens, and select intracellular organisms in respiratory, dermatologic, and genitourinary infections. Azithromycin occupies the largest volume position due to once-daily dosing convenience and superior tissue half-life, while fidaxomicin commands premium positioning in Clostridioides difficile infections where narrow-spectrum targeting reduces microbiome disruption. Respiratory infection applications retain dominant value share though skin infection indications are gaining traction as outpatient clinics expand point-of-care testing for atypical pathogens.
FDA antimicrobial stewardship mandates and EMA pharmacovigilance reporting requirements shape prescribing patterns by restricting empiric macrolide use pending susceptibility confirmation. CDSCO manufacturing facility inspections and WHO prequalification standards determine export eligibility for Indian generic producers supplying procurement programs. Stakeholders must monitor evolving resistance surveillance data from CDC and ECDC to anticipate formulary restrictions that could redirect development investment toward next-generation ketolide derivatives.
Market Dynamics
FDA antimicrobial stewardship mandates and EMA pharmacovigilance tightening are forcing hospital formulary committees to restrict empiric macrolide prescribing, compressing volume in traditional respiratory indications while redirecting development investment toward narrow-spectrum ketolide derivatives.
Growth Catalysts
- Homecare infusion expansion:Hospital discharge protocols in the United States are accelerating outpatient parenteral antimicrobial therapy, driving demand for stable macrolide formulations suitable for home administration.
- CDSCO export clearance:Indian manufacturing facilities achieving WHO prequalification status are unlocking procurement contracts with UN agencies and emerging market governments for generic azithromycin supply.
- Point-of-care pathogen identification:Rapid molecular diagnostics in dermatology clinics are detecting atypical bacterial skin infections, expanding macrolide use beyond traditional respiratory applications.
Market Restraints
- Fermentation input volatility:Streptomyces culture media and carbohydrate feedstock costs fluctuate with agricultural commodity markets, squeezing margins for fermentation-dependent macrolide production.
- Indian supply concentration:Over half of generic oral azithromycin API originates from facilities clustered in Gujarat and Telangana, creating geographic vulnerability to monsoon-related logistics disruptions.
- Resistance surveillance mandates:CDC and ECDC reporting requirements for macrolide-resistant Streptococcus pneumoniae are triggering formulary restrictions that limit empiric prescribing in community-acquired pneumonia.
Strategic Opportunities
- Sub-Saharan procurement programs:WHO prequalified Indian manufacturers are securing multi-year supply agreements with Global Fund and national HIV/TB programs for azithromycin as opportunistic infection prophylaxis.
- Clostridioides difficile positioning:Narrow-spectrum fidaxomicin formulations are capturing premium hospital pharmacy slots as microbiome-preserving alternatives to vancomycin in recurrent infection protocols.
- Continuous manufacturing adoption:FDA quality guidance on advanced manufacturing technologies is creating first-mover advantage for facilities converting from batch fermentation to integrated continuous processing.
Industry Challenges
- Stewardship compliance complexity:Hospital antimicrobial management teams must integrate susceptibility testing delays into clinical workflows, requiring IT system upgrades and physician protocol retraining.
- Cross-contamination control:Multi-product fermentation facilities face heightened regulatory scrutiny regarding beta-lactam and macrolide segregation during campaign changeovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macrolide Antibiotics Market |
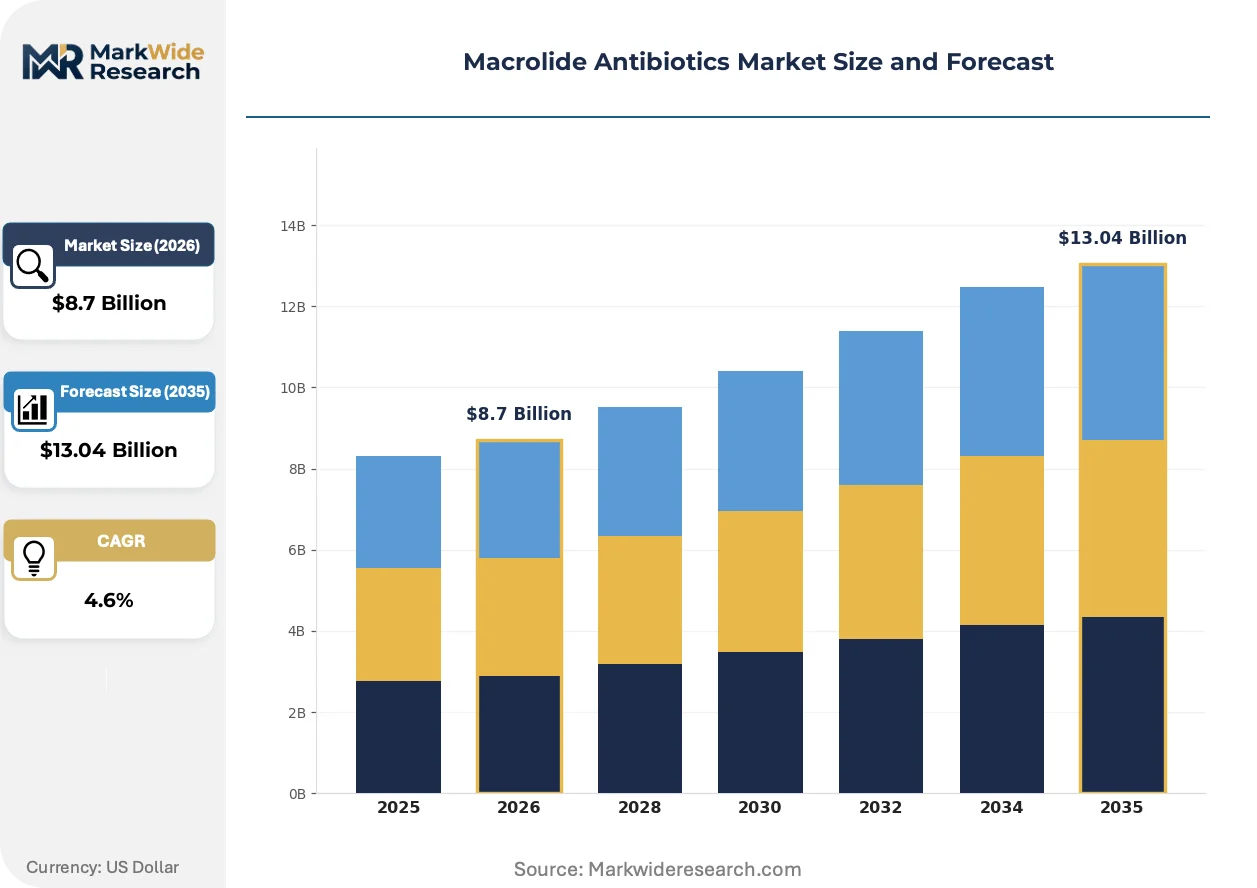
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azithromycin, Erythromycin, Clarithromycin, Fidaxomicin Application: Respiratory Infections, Skin Infections, Gastrointestinal Infections, STDs End User: Hospitals, Clinics, Pharmacies, Homecare Settings Form: Tablets, Oral Suspensions, Injections, Topical Preparations |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Sun Pharmaceutical Industries Ltd., Novartis AG, Abbott Laboratories, Alkem Laboratories Ltd., Zydus Lifesciences Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macrolide Antibiotics Market Shifts & Advancements
Digital therapeutics integration and advanced manufacturing modalities are compressing development timelines while regulatory science evolution is redefining acceptable evidence standards for antimicrobial approval pathways.
Bioprocess digital twin technology is virtualizing fermentation optimization for macrolide API production. Contract manufacturers in South Korea and Singapore are deploying these platforms to reduce batch failure rates and accelerate scale-up from laboratory to commercial volumes. The technology is virtualizing traditional empirical process development, enabling real-time parameter adjustment that cuts campaign validation timelines by months.
EMA's revised clinical trial guidance for antibacterial agents now permits streamlined non-inferiority designs in documented resistant infections. This regulatory flexibility is accelerating ketolide candidate advancement through Phase II/III transitions. European hospital pharmacy and therapeutics committees are responding by reserving formulary slots for agents with demonstrated activity against macrolide-resistant pathogens.
Hospital purchasing cooperatives in Germany and France are consolidating antimicrobial procurement under single-source framework agreements with compliance-linked pricing. These arrangements bundle susceptibility testing infrastructure with drug supply, displacing traditional multi-vendor antibiotic purchasing. The shift is most visible in academic medical centers where stewardship metrics determine contract renewal terms.
Macrolide Antibiotics Market Segmentation
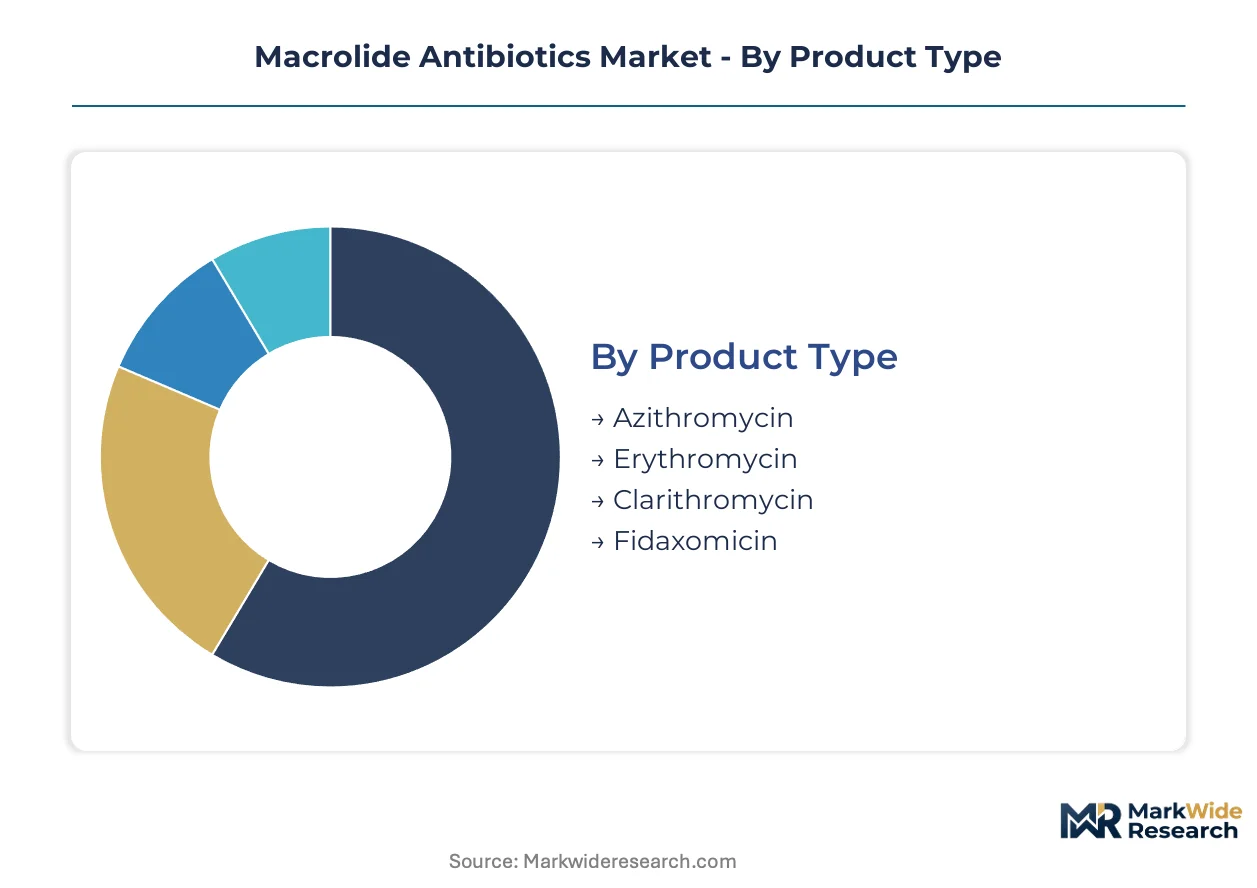
Macrolide antibiotics exhibit pronounced demand heterogeneity across molecular structures, clinical indications, and care delivery settings. Segmentation reveals how formulation chemistry, infection site specificity, and patient acuity collectively shape procurement patterns and margin structures.
Product Type:
Cost tier stratification across the macrolide class reflects fermentation complexity, semi-synthetic modification requirements, and spectrum breadth.
- Azithromycin:Fifteen-membered azalide ring structure delivers acid stability and extended tissue half-life supporting once-daily dosing. Demand concentrates in Indian export markets and UN procurement programs for respiratory and genitourinary protocols, driven by generic manufacturing scale and WHO prequalification penetration.
- Fidaxomicin:Narrow-spectrum macrocyclic antibiotic with minimal systemic absorption and preserved gut microbiome integrity. Hospital pharmacy slots in Germany and France are expanding uptake for recurrent Clostridioides difficile protocols, constrained by premium pricing relative to vancomycin.
- Clarithromycin:Six-membered cladinose sugar modification improves gastric acid tolerance over erythromycin base.
- Erythromycin:First-generation fourteen-membered macrolide with established Helicobacter pylori eradication protocols.
Azithromycin commands the established base. The steepest expansion runs through fidaxomicin.
Application:
Clinical indication segmentation tracks pathogen epidemiology, diagnostic testing penetration, and stewardship protocol stringency.
- Respiratory Infections:Community-acquired pneumonia and atypical pathogen coverage represent the historical volume anchor. Outpatient clinic prescribing in the United States faces CDC resistance surveillance constraints, compressing empiric use pending rapid molecular diagnostic confirmation.
- Skin Infections:Atypical bacterial detection through point-of-care molecular platforms is redirecting macrolide utilization from respiratory to dermatology settings. European dermatology clinics in France and Germany are expanding prescription volumes for Bartonella and atypical mycobacterial protocols.
- Gastrointestinal Infections:H. pylori eradication and C. difficile recurrence prevention drive hospital formulary placement.
- STDs:Chlamydia trachomatis and Neisseria gonorrhoeae prophylaxis protocols sustain public health procurement demand.
Respiratory applications retain volume leadership. Skin infection indications are climbing the fastest.
End User:
Customer type segmentation reflects care setting acuity, reimbursement structure, and antimicrobial stewardship integration depth.
- Hospitals:Inpatient parenteral formulations and restricted formulary access for narrow-spectrum agents characterize procurement. German and French academic medical centers are consolidating purchasing under single-source framework agreements with compliance-linked pricing.
- Homecare Settings:Outpatient parenteral antimicrobial therapy expansion in the United States is creating demand for stable macrolide formulations suitable for home infusion. Hospital discharge protocols are accelerating this channel's growth trajectory.
- Clinics:Point-of-care diagnostic integration is reshaping prescribing authority for respiratory and dermatology indications.
- Pharmacies:Generic oral azithromycin dispensing dominates retail volume with compressed margins.
Hospitals command the established base. The steepest expansion runs through homecare settings.
Form:
Delivery modality segmentation tracks patient compliance economics, manufacturing process complexity, and stability requirements.
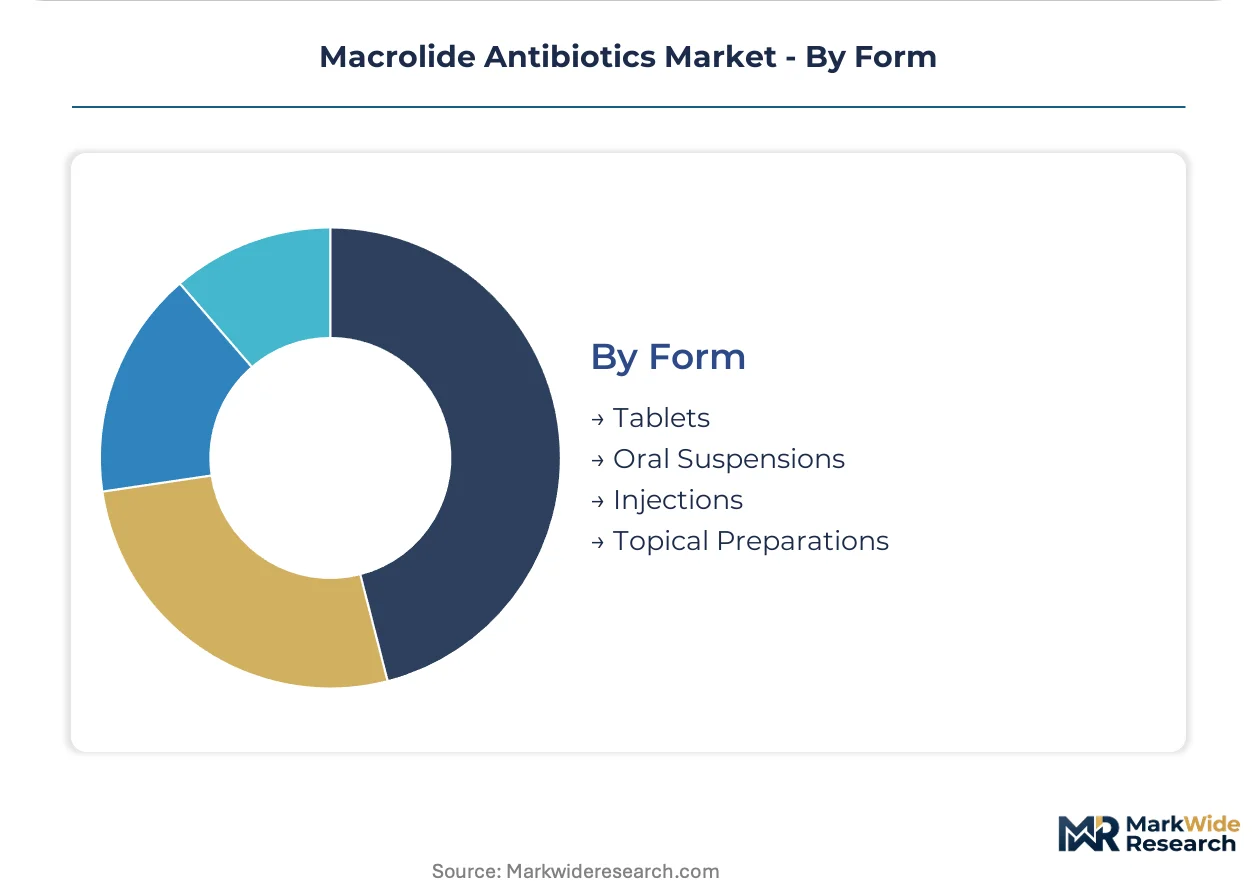
- Tablets:Solid oral dosage forms dominate outpatient compliance economics with established bioequivalence pathways for generic substitution. Indian manufacturers in Gujarat and Telangana are scaling film-coated azithromycin tablet production for regulated market export.
- Injections:Parenteral formulations for inpatient and homecare administration require sterile manufacturing capacity with higher barrier to entry. Pfizer maintains branded positioning through specialty injectable macrolides in hospital channels.
- Oral Suspensions:Pediatric and geriatric compliance applications with distinct taste-masking and stability formulation requirements.
- Topical Preparations:Dermatology-directed delivery with localized action and minimized systemic exposure.
Tablets command the established base. The steepest expansion runs through injections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturing clusters supply over half of global generic azithromycin feedstock, concentrating fermentation capacity in Gujarat and Telangana while regulated markets tighten procurement standards around antimicrobial stewardship compliance.
United States
Hospital discharge protocols are accelerating outpatient parenteral antimicrobial therapy, creating demand for stable macrolide formulations suitable for home infusion. FDA antimicrobial stewardship mandates restrict empiric prescribing pending rapid molecular diagnostic confirmation. Hospital purchasing cooperatives in academic medical centers are consolidating procurement under single-source framework agreements with compliance-linked pricing.
Germany
Academic medical centers are expanding fidaxomicin formulary placement for recurrent Clostridioides difficile protocols as microbiome-preserving alternatives to vancomycin. EMA pharmacovigilance reporting requirements shape prescribing patterns by restricting empiric macrolide use. The Rhine-Ruhr and Bavarian hospital networks are piloting bundled procurement arrangements that tie antimicrobial supply to susceptibility testing infrastructure.
India
Domestic manufacturers are scaling generic azithromycin production for WHO prequalification and UN procurement program eligibility. CDSCO manufacturing facility inspections determine export access to regulated markets. API production concentrates in Gujarat and Telangana facilities, with Hyderabad-based fermentation complexes achieving vertical integration from Streptomyces culture to finished dosage export.
France
Dermatology clinics are expanding macrolide prescriptions for atypical bacterial skin infections detected through point-of-care molecular platforms. ANSM pharmacovigilance frameworks align with EMA stewardship guidance to limit empiric respiratory prescribing. The Paris-Saclay hospital cluster is consolidating antimicrobial purchasing under outcome-linked contracts that reward narrow-spectrum agent utilization.
South Korea
Contract manufacturers are deploying bioprocess digital twin technology to virtualize fermentation optimization for macrolide API production. MFDS regulatory alignment with FDA quality guidance on advanced manufacturing creates first-mover advantage for continuous processing adoption. Seoul-Incheon biopharma corridors are attracting technology licensing partnerships from Indian generic producers seeking fermentation scale-up expertise.
Macrolide Antibiotics Market Competitive Landscape
Branded specialty manufacturers and vertically integrated generic producers split the market along formulation complexity lines. The structure consolidates around fermentation-dependent API supply and finished dosage manufacturing scale. Three archetypes dominate: multinational innovators with hospital channel access, Indian generic exporters with WHO prequalification status, and contract fermentation specialists with bioprocess technology platforms. Competitive moves center on backward integration into API supply and strategic partnerships for advanced manufacturing technology licensing.
Within the branded hospital channel tier, Pfizer Inc. and Merck & Co., Inc. occupy positions anchored on specialty injectable formulations and narrow-spectrum portfolio development. Among vertically integrated generic exporters, Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. exemplify the scale-driven archetype, with the former representing Israeli-Ltd. structure and the latter anchoring Indian manufacturing cost optimization for regulated and emerging market supply. These entities sit within a competitive set where WHO prequalification status and CDSCO inspection compliance determine procurement eligibility for multi-year supply agreements.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Sun Pharmaceutical Industries Ltd. |
| Novartis AG |
| Abbott Laboratories |
| Alkem Laboratories Ltd. |
| Zydus Lifesciences Ltd. |
| Others |
Supply & Pricing Matrix
Monsoon-related logistics disruptions in Gujarat and Telangana determine both pricing tier spreads and supply chain shape, compressing margins for fermentation-dependent producers while amplifying premiums for WHO-prequalified manufacturers with geographic diversification.
Pricing Analysis
FDA antimicrobial stewardship mandates and EMA pharmacovigilance requirements dictate the pricing tier structure across the macrolide class, separating premium fidaxomicin hospital slots from commoditized oral azithromycin. Three-tier pricing separates narrow-spectrum specialty injectables from standard generic tablets and economy-grade oral suspensions. Cost compression in oral azithromycin intensifies because Indian API concentration enables aggressive generic competition. Public health procurement programs exhibit highest price sensitivity, while hospital pharmacy committees for C. difficile protocols demonstrate lowest sensitivity due to microbiome-preserving clinical requirements.
Supply Chain Analysis
Contract manufacturers in South Korea and Singapore hold advanced bioprocess capacity for fermentation optimization, while Indian facilities in Hyderabad and Ahmedabad anchor commodity API supply. Streptomyces culture media and carbohydrate feedstock dependencies draw from agricultural commodity markets in India and China. Single-source vulnerability concentrates in Gujarat and Telangana fermentation clusters exposed to seasonal logistics disruption. Distribution runs through hospital purchasing cooperatives in Germany and France, UN procurement programs, and retail pharmacy chains in regulated markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutics integration with point-of-care diagnostics creates platform-economics inflection, as rapid molecular testing interoperability reshapes prescribing authority and formulary access across outpatient and homecare channels.
For Market Incumbents: Pre-empt formulary displacement by embedding susceptibility testing infrastructure within hospital purchasing cooperatives, mirroring German and French bundled procurement models. Secure backward integration into Streptomyces fermentation capacity to defend against Indian API supply volatility. Anchor hospital channel access through compliance-linked pricing agreements that tie narrow-spectrum ketolide development to stewardship metric achievement.
For New Entrants and Emerging Players: Sub-Saharan WHO procurement programs for HIV/TB opportunistic infection prophylaxis represent the most penetrable entry point, given azithromycin demand concentration and prequalification pathway clarity. Homecare infusion settings in the United States offer secondary white-space as hospital discharge protocols accelerate outpatient parenteral therapy. Pursue technology licensing partnerships with South Korean contract manufacturers to shortcut fermentation scale-up timelines.
For Investors and Strategic Acquirers: The market sits at a stewardship-mandate consolidation phase that favors vertically integrated generic producers with WHO prequalification status and regulatory inspection track records. Long-term viability hinges on continuous manufacturing adoption and narrow-spectrum portfolio development. Monitor CDSCO inspection clearance rates and FDA quality guidance implementation as inflection indicators for supply-side competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | FDA quality guidance creates first-mover advantage for facilities converting from batch fermentation to integrated processing. |
| Bioprocess Digital Twin Deployment | South Korean contract manufacturers virtualize fermentation optimization, cutting campaign validation timelines by months. |
| WHO Prequalification Pathway Investment | CDSCO-inspected Indian facilities unlock multi-year Global Fund supply agreements for azithromycin prophylaxis programs. |
| Narrow-Spectrum Ketolide Pipeline Advancement | EMA streamlined trial guidance accelerates Phase II/III transitions for agents targeting macrolide-resistant pathogens. |
| Homecare Infusion Formulation Development | Stable parenteral macrolides capture outpatient antimicrobial therapy demand from United States hospital discharge protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CDC resistance surveillance databases. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were triangulated to converge volume and value estimates.
Forecast inputs span molecular structure, clinical indication, care delivery setting, and regional regulatory cluster across the projection horizon. CAGRs were derived from segmented demand modeling incorporating antimicrobial stewardship policy trajectory, generic manufacturing capacity expansion, and point-of-care diagnostic penetration rates. Resistance surveillance data from CDC and ECDC inform epidemiological assumptions for respiratory indication demand elasticity.
Stress conditions across monsoon logistics disruption severity, FDA stewardship mandate enforcement pace, and ketolide clinical trial success rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of CDSCO inspection clearance timelines and EMA pharmacovigilance guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market