
 Medical Biomimetics Market | 2026-2036
Medical Biomimetics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Biomimetics Market Analysis
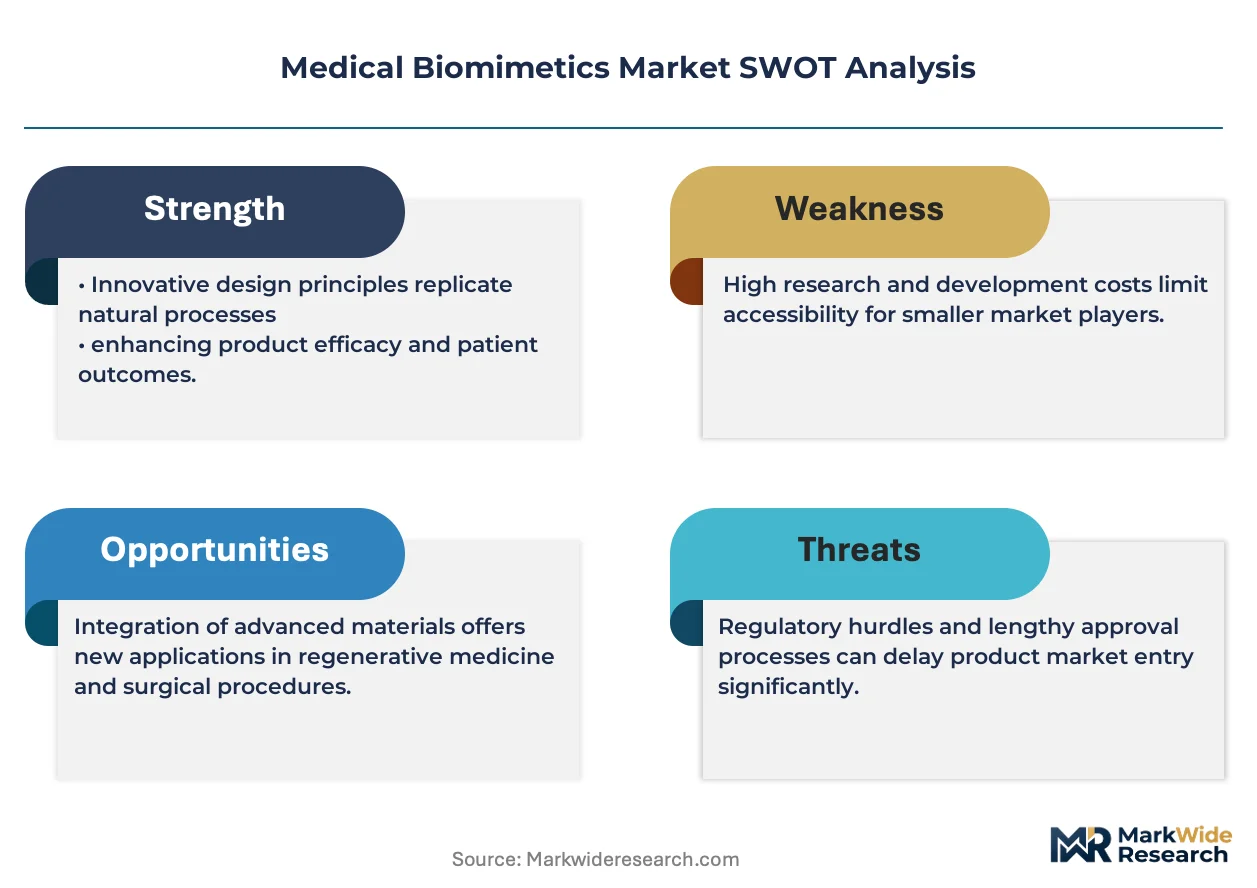
Modular implant configurations is shifting how orthopedic buyers evaluate surgical solutions, moving from standalone devices to integrated biomimetic systems. Stryker leverages its manufacturing scale to anchor supply of patient-specific scaffolds across North American hospitals. Medtronic competes through deep specialization in cardiac biomimetic grafts, while Zimmer Biomet dominates joint reconstruction with surface-modified titanium implants.
Medical biomimetics encompasses the engineering of synthetic materials and structures that replicate biological architectures, including hydroxyapatite-coated titanium scaffolds with 70-90% porosity designed to match human trabecular bone stiffness. These constructs serve to restore mechanical function while guiding cellular infiltration and vascularization in vivo. Implant applications command the largest revenue pool due to chronic orthopedic and cardiovascular disease burdens, though 3D-printed biomimetic scaffolds represent the fastest-expanding technology segment as point-of-care manufacturing matures. Surface modification techniques retain concentrated margins among high-volume hip and knee arthroplasty suppliers.
FDA's 510(k) and PMA pathways govern U.S. market access for biomimetic implants, while EMA's Medical Device Regulation enforces clinical evidence standards across European member states. Japan's PMDA maintains distinct biocompatibility testing protocols that shape product development priorities for Asia-Pacific entry. Stakeholders must monitor evolving reimbursement decisions for patient-specific implants as health technology assessment bodies weigh cost-effectiveness against functional outcomes.
Market Dynamics
Point-of-care 3D printing infrastructure is compressing lead times for patient-specific scaffolds from weeks to days, forcing orthopedic procurement teams to renegotiate supplier contracts and inventory commitments. This manufacturing proximity shift is redistributing margin pools away from centralized fabrication networks toward hospital-integrated production cells.
Growth Catalysts
- EMA Medical Device Regulation:Streamlined clinical evidence frameworks for biomimetic implants are accelerating CE marking timelines across European member states, enabling faster commercialization of hydroxyapatite-coated titanium constructs.
- Japan's PMDA biocompatibility protocols:Harmonization efforts with ISO 10993 standards are reducing redundant testing burdens for manufacturers seeking Asia-Pacific market entry, particularly for cardiovascular graft applications.
- Chronic orthopedic disease burden:Aging demographics in Germany and the United States are expanding addressable patient populations for joint reconstruction procedures utilizing surface-modified implant systems.
Market Restraints
- High-purity titanium powder costs:Volatility in aerospace-grade feedstock pricing is compressing margins for 3D-printed scaffold producers dependent on gas-atomized spherical powders.
- Supply concentration in Chinese rare earth processing:Dependence on single-source yttrium oxide for ceramic coating applications creates geopolitical exposure for European implant manufacturers.
- FDA PMA pathway duration:Extended clinical trial requirements for novel biomaterials delay revenue recognition by 18-36 months versus 510(k) cleared predicate devices.
Strategic Opportunities
- India's CDSCO fast-track approval:Recent regulatory reforms for Class C and D medical devices create expedited entry pathways for established European and North American biomimetic implant manufacturers.
- Electrospinning-nanoparticle composite convergence:Integration of antimicrobial silver nanoparticles with aligned fiber scaffolds addresses unmet infection prevention needs in spinal fusion applications.
- Direct-to-hospital digital distribution:Bypassing traditional implant distributor networks through surgeon-facing CAD/CAM platforms captures 15-20 point margin improvements for scaffold producers.
Industry Challenges
- Biofabrication technician scarcity:Shortage of trained personnel capable of operating multi-material bioprinters and maintaining sterile production environments limits point-of-care deployment velocity.
- ISO 13485 certification complexity:Evolving quality management system requirements for patient-specific device manufacturing demand substantial documentation infrastructure investments from mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Biomimetics Market |
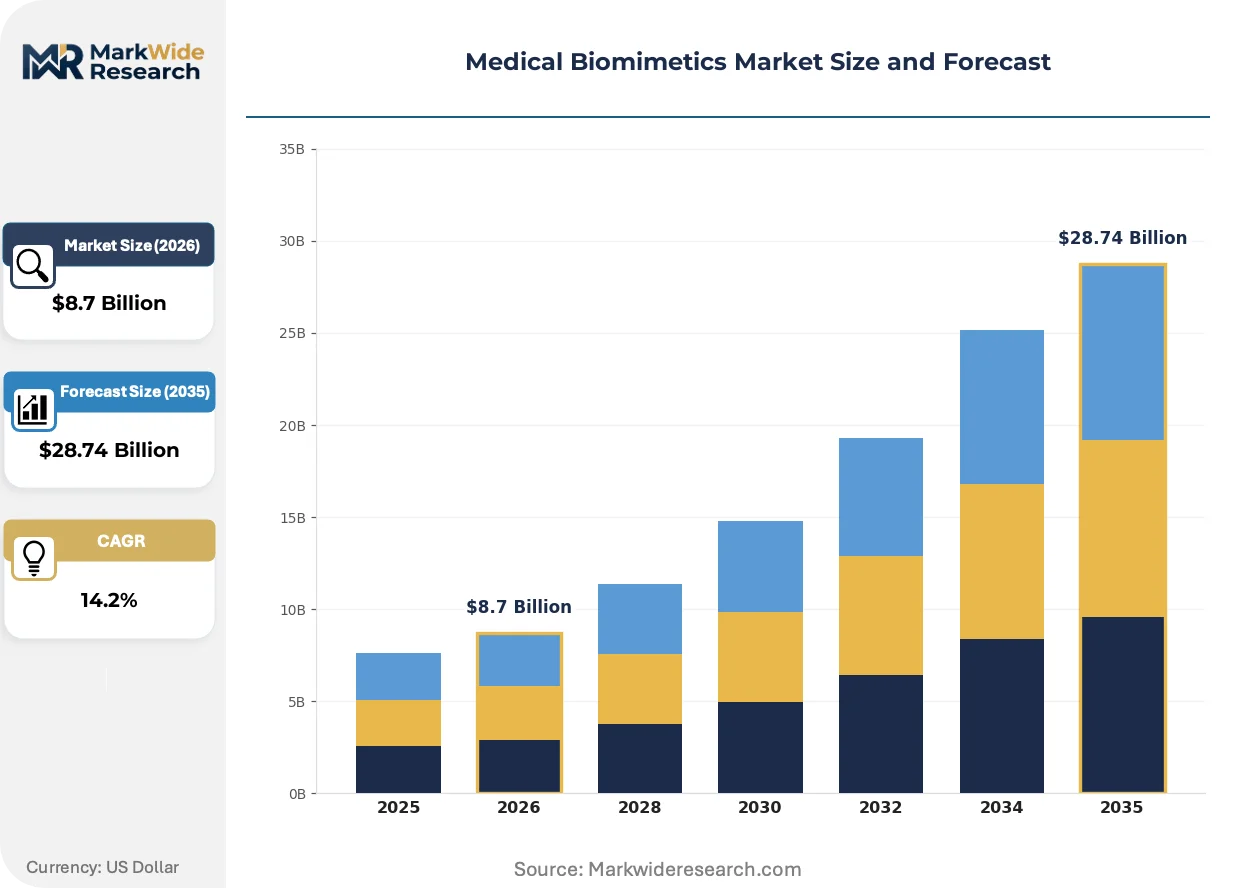
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Implants, Coatings, Grafts Technology: 3D Printing, Tissue Engineering, Surface Modification, Biofabrication Application: Orthopedics, Cardiology, Dentistry, Wound Healing End User: Hospitals, Research Labs, Clinics, Rehabilitation Centers |
| Companies Covered | Abbott, Stryker, Medtronic, Zimmer Biomet, BioHorizons, Osteopore International, Veryan Medical, SynTouch, CorNeat Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Biomimetics Market Emerging Trajectories
Computational design tools and in-situ monitoring systems are converging to enable real-time scaffold adaptation during surgical procedures. This capability set is redefining competitive differentiation beyond material composition toward intraoperative customization precision.
Gradient porosity titanium scaffolds produced via laser powder bed fusion are overtaking conventionally machined solid implants in complex acetabular reconstruction cases. Academic medical centers in the United States and Germany are adopting these constructs at accelerating cadence. The technology is overtaking established supply relationships by enabling same-day surgical planning-to-implant workflows that centralized manufacturing cannot match.
REACH restrictions on hexavalent chromium surface treatments are compelling European orthopedic suppliers to accelerate plasma electrolytic oxidation alternatives for titanium wear resistance. The regulation is forcing capital reallocation toward aqueous electrolyte coating lines and away from traditional anodization infrastructure. Knee arthroplasty manufacturers serving EU markets are responding with phased product line transitions scheduled across 2026-2028 compliance windows.
Surgeon preference is consolidating around implant systems offering bundled pre-operative planning software and intraoperative navigation compatibility. Traditional device-only procurement is yielding to integrated solution contracts spanning digital surgical planning, patient-specific instrumentation, and outcome tracking analytics. This pattern is most pronounced in German and Japanese hospital systems where procurement committees now evaluate total episode cost rather than unit device pricing.
Medical Biomimetics Market Segmentation
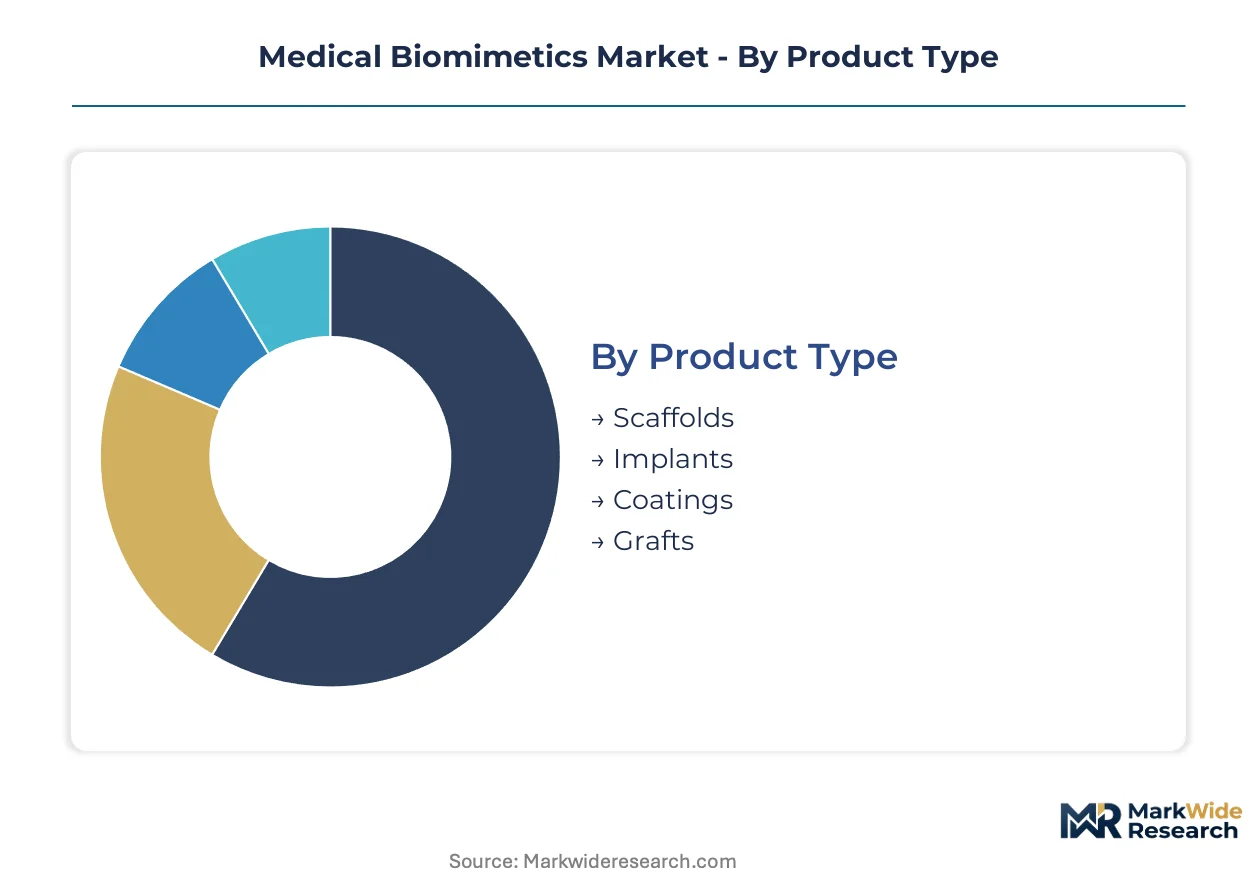
Segmentation in medical biomimetics reveals distinct margin structures and regulatory pathways that shape manufacturer strategy. Product type and technology categories separate high-volume commodity supply from premium patient-specific solutions.
Product Type:
Volume concentration sits with established hardware, while premium capture belongs to biologically active constructs.
- Scaffolds:Hydroxyapatite-coated titanium frameworks with 70-90% porosity replicate trabecular bone stiffness for load-bearing applications. German academic medical centers and United States orthopedic networks are expanding procurement of patient-specific lattice structures for complex acetabular reconstruction.
- Implants:Surface-modified titanium and cobalt-chrome constructs dominate hip and knee arthroplasty volumes. Stryker and Zimmer Biomet anchor supply across North American hospital systems through integrated digital planning platforms.
- Coatings:Plasma electrolytic oxidation and hydroxyapatite layers enhance osseointegration on metal substrates. REACH compliance deadlines are accelerating European manufacturer transition away from hexavalent chromium surface treatments.
- Grafts:Biological and synthetic vascular conduits address cardiovascular bypass and dialysis access procedures. Medtronic specializes in cardiac biomimetic graft applications with deep regulatory expertise across FDA and EMA pathways.
Mature deployment sits with Implants. Newer deployment is concentrated in Scaffolds.
Technology:
Manufacturing proximity to the surgical site now determines competitive positioning more than material composition alone.
- 3D Printing:Laser powder bed fusion and electron beam melting enable gradient porosity titanium constructs matched to patient anatomy. Point-of-care deployment in United States and German hospitals compresses lead times from weeks to days.
- Tissue Engineering:Cell-seeded scaffolds and organoid constructs target functional tissue restoration. Research labs in Japan and academic medical centers in Germany concentrate early-stage clinical translation efforts.
- Surface Modification:Plasma electrolytic oxidation and biomimetic mineralization enhance implant biocompatibility. European knee arthroplasty suppliers are reallocating capital toward aqueous electrolyte coating lines for REACH compliance.
- Biofabrication:Multi-material bioprinting integrates living cells with structural matrices for complex tissue architectures. Technician scarcity limits deployment velocity despite clinical demand for patient-specific constructs.
Established revenue capture sits with Surface Modification. Steepest expansion trajectory belongs to 3D Printing.
Application:
Chronic disease burden and reimbursement accessibility determine addressable patient populations across clinical specialties.
- Orthopedics:Joint reconstruction and spinal fusion command the largest revenue pool due to aging demographics in Germany and the United States. Surface-modified titanium implants and patient-specific scaffolds serve hip, knee, and complex trauma procedures.
- Cardiology:Vascular grafts and cardiac patches address coronary artery disease and congenital defects. Medtronic's specialization in this segment reflects distinct regulatory and clinical evidence requirements.
- Dentistry:Dental implants and alveolar bone regeneration scaffolds serve edentulism and periodontal reconstruction. Japanese and German markets concentrate premium ceramic and titanium implant demand.
- Wound Healing:Electrospun nanofiber dressings and antimicrobial scaffolds target chronic diabetic and pressure ulcers. Silver nanoparticle composite integration addresses unmet infection prevention needs.
Revenue concentration sits with Orthopedics. Gaining share fastest is Wound Healing.
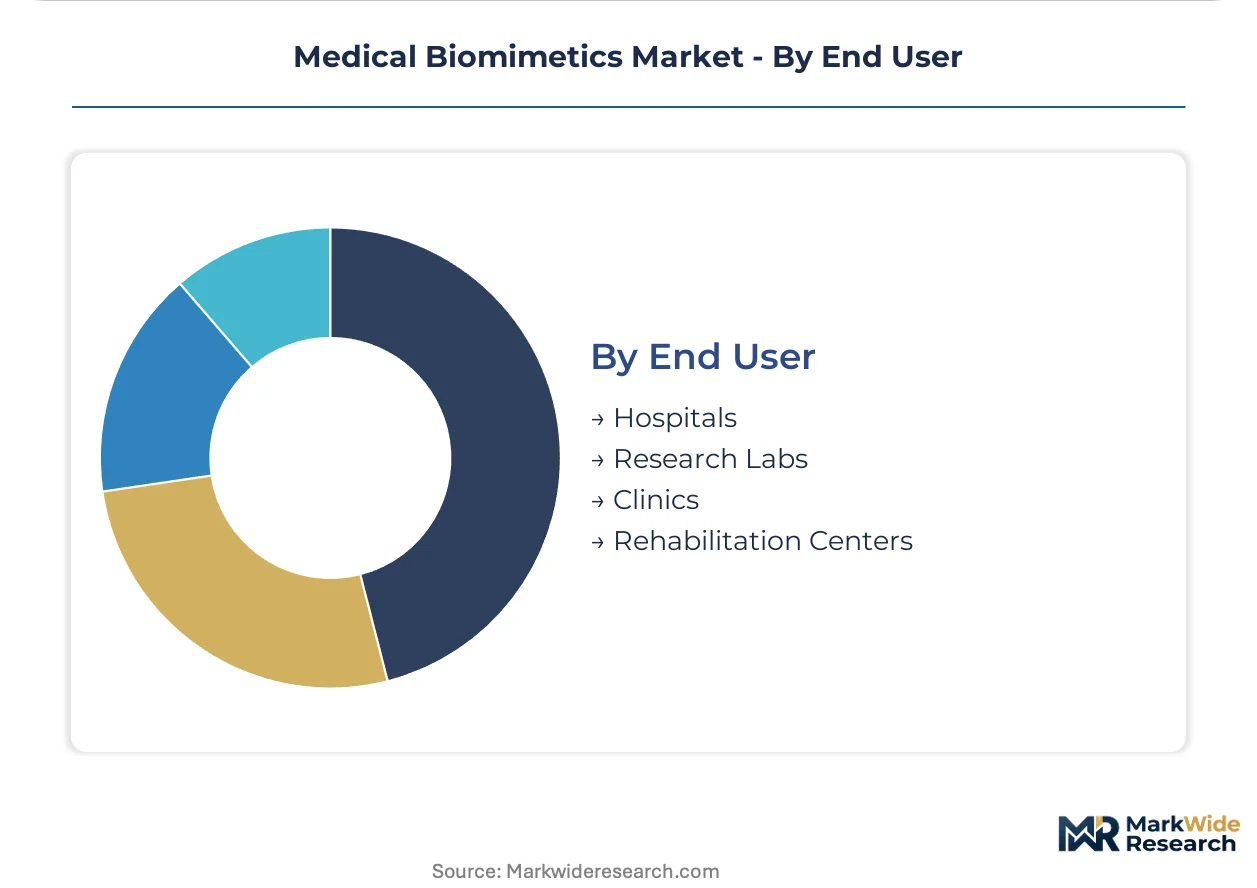
End User:
Procurement authority and technical capability separate institutional buyers from distributed clinical settings.
- Hospitals:Integrated health systems in the United States and Germany evaluate total episode cost through procurement committees spanning surgeons, administrators, and supply chain officers. Bundled contracts now span digital planning, patient-specific instrumentation, and outcome analytics.
- Research Labs:Academic medical centers and biotechnology institutes drive preclinical translation and regulatory evidence generation. German and Japanese research clusters concentrate biofabrication innovation.
- Clinics:Ambulatory surgical centers and specialty practices concentrate high-volume arthroplasty and dental implant procedures. Direct-to-hospital digital distribution platforms are compressing traditional distributor margins.
- Rehabilitation Centers:Post-acute facilities utilize biomimetic constructs for wound management and orthopedic recovery. Outcome-based reimbursement pressures shape device selection criteria.
Procurement volume sits with Hospitals. Emerging purchasing sophistication sits with Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device innovation zones in Massachusetts, Bavaria, and Osaka Prefecture concentrate biomimetic R&D infrastructure through targeted tax incentives and specialized workforce development programs.
United States
FDA's 510(k) and PMA pathways govern market access for hydroxyapatite-coated constructs, with orthopedic procurement committees in Boston and Minneapolis evaluating total episode costs. Massachusetts hosts dense clusters of 3D-printing scaffold developers serving academic medical centers.
Germany
EMA's Medical Device Regulation accelerates CE marking for biomimetic implants, while REACH compliance deadlines force coating line transitions in Baden-Württemberg. Stuttgart and Tübingen anchor laser powder bed fusion manufacturing for patient-specific acetabular reconstruction.
Japan
PMDA biocompatibility protocols shape product development priorities for cardiovascular graft applications, with harmonization efforts reducing redundant testing burdens. Osaka and Nagoya concentrate biofabrication research labs driving preclinical translation.
India
CDSCO fast-track approvals for Class C and D devices create expedited entry pathways for established scaffold manufacturers. Maharashtra and Karnataka host emerging hospital-integrated production cells targeting point-of-care deployment.
United Kingdom
NICE health technology assessments weigh cost-effectiveness of patient-specific implants against functional outcomes, influencing procurement decisions in NHS trusts. Cambridge and Oxford academic clusters concentrate electrospinning-nanoparticle composite research for spinal fusion applications.
Medical Biomimetics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the medical biomimetics value chain. Tier-one orthopedic manufacturers anchor supply through integrated digital planning platforms, while mid-scale scaffold producers capture premium margins via patient-specific customization capabilities. Strategic moves concentrate on point-of-care manufacturing partnerships and direct-to-hospital distribution bypasses.
Among diversified medical technology conglomerates, Stryker and Medtronic occupy positions spanning implant hardware and biologic solutions. Zimmer Biomet exemplifies the orthopedic-focused archetype with concentrated joint reconstruction portfolios. These three entities represent distinct competitive postures: manufacturing scale, cardiac specialization, and surface-modified titanium dominance respectively.
| Leading Market Players |
|---|
| Abbott |
| Stryker |
| Medtronic |
| Zimmer Biomet |
| BioHorizons |
| Osteopore International |
| Veryan Medical |
| SynTouch |
| CorNeat Vision |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-cleared patient-specific scaffolds and 510(k) predicate devices manifests in pricing premiums of 40-60 points and supply chain configurations that tether premium tiers to hospital-integrated production cells while commodity tiers flow through traditional distributor networks.
Pricing Analysis
Lead-time compression commands measurable price premiums across orthopedic procurement, with same-day surgical planning-to-implant workflows extracting 25-35 point markups over centralized fabrication alternatives. Pricing stratifies across premium patient-specific instrumentation, standard surface-modified titanium constructs, and economy-grade cobalt-chrome implants driven by customization depth and regulatory pathway complexity. Cost compression in standard-tier joint reconstruction hardware intensifies as point-of-care manufacturing democratizes access to patient-specific capabilities. Ambulatory surgical centers exhibit acute price sensitivity, while academic medical centers prioritize total episode cost frameworks over unit device pricing.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO fast-track pathway and Japan's PMDA localization incentives are reshaping sourcing strategies toward regional powder atomization and coating facilities. Feedstock supply concentrates in China for rare earth oxides, Germany for precision laser systems, and the United States for gas-atomized titanium powders. Single-source dependence on Chinese yttrium oxide for ceramic coating applications creates geopolitical exposure for European implant manufacturers. Distribution runs through surgeon-facing CAD/CAM platforms that bypass traditional implant distributors, capturing margin improvements for scaffold producers while compressing legacy channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser powder bed fusion is displacing conventionally machined solid implants in complex acetabular reconstruction, compressing technology transition timelines from years to procurement cycles.
For Market Incumbents: Anticipate margin erosion in standard-tier joint reconstruction hardware as point-of-care manufacturing democratizes patient-specific capabilities previously reserved for premium positioning. Defensive consolidation through backward integration into gas-atomized titanium powder production secures feedstock cost control against aerospace-grade pricing volatility. Reinforce hospital system partnerships through bundled digital planning software and intraoperative navigation compatibility to lock in integrated solution contracts before procurement committees complete vendor consolidation. For New Entrants and Emerging Players: Electrospinning-nanoparticle composite technology offers a technology-first wedge into spinal fusion applications where antimicrobial silver integration addresses unmet infection prevention needs underserved by established surface modification suppliers. White-space concentration sits with wound healing segments in rehabilitation centers and post-acute facilities where outcome-based reimbursement creates purchasing flexibility absent in hospital procurement committees. Direct-to-hospital digital distribution platforms bypass entrenched distributor relationships and capture 15-20 point margin improvements versus legacy channel economics. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale scaffold producers possessing ISO 13485 certification infrastructure and hospital-integrated production cell deployments given CDSCO fast-track approval tailwinds in India and point-of-care manufacturing adoption curves in Germany and the United States. Long-term viability over the projection horizon hinges on regulatory evidence generation capabilities spanning FDA PMA, EMA MDR, and PMDA harmonization pathways. Monitor surgeon preference consolidation around bundled pre-operative planning software as the inflection indicator for integrated solution contract penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Zimmer Biomet anchor supply through integrated digital planning platforms across North American orthopedic networks. |
| CE Marking Pathway | EMA's streamlined clinical evidence frameworks accelerate commercialization timelines for hydroxyapatite-coated titanium constructs. |
| Reimbursement Strategy | NICE health technology assessments in the United Kingdom weigh cost-effectiveness of patient-specific implants against functional outcomes. |
| Software Companion Development | Surgeon-facing CAD/CAM platforms enable direct-to-hospital distribution that bypasses traditional implant distributor networks. |
| Backward Integration | Mid-scale scaffold producers secure captive supply of gas-atomized titanium powder against aerospace-grade feedstock pricing volatility. |
Methodological Framework
Document review covered FDA 510(k) and PMA filings, EMA Medical Device Regulation submissions, hospital procurement databases, and GPO contracts, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification registries, and trade customs records for titanium powder and rare earth oxide imports. Bottom-up and top-down triangulation reconciled manufacturer shipment data with hospital implant utilization records.
Segment-level outputs across product type, technology, application, and end user dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from regression analysis against chronic orthopedic disease burden indicators, regulatory approval velocity metrics, and point-of-care manufacturing deployment rates. Forecast inputs incorporated PMDA biocompatibility protocol harmonization progress and REACH compliance deadline impacts on European coating line capital allocation.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway delays, geopolitical disruption to Chinese rare earth oxide supply, and surgeon adoption curves for real-time scaffold adaptation technologies. Forecasts reflect assumptions about reimbursement stability for patient-specific implants and technician training pipeline development for biofabrication operations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Non-Surgical Bio-Implants Market