
 Asia-Pacific Bacteriophages Therapy Market | 2026-2036
Asia-Pacific Bacteriophages Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bacteriophages Therapy Market Outlook
Modular phage cocktail formulations is rebalancing procurement decisions across hospital systems, allowing clinicians to customize lysin combinations against specific bacterial strains rather than relying on fixed-spectrum antibiotics. Intralytix Inc. leverages its proprietary phage bank architecture to sustain long-term supply agreements with research hospitals. Phagelux anchors its position through geographic dominance in East Asian food safety applications, while Adaptive Phage Therapeutics competes on technology leadership in personalized phage matching protocols.
Bacteriophages therapy deploys viruses that infect and lyse specific bacterial hosts, with formulations typically containing 10^9 plaque-forming units per milliliter and requiring cold-chain storage at 2-8°C to preserve viability. Engineered bacteriophages command premium positioning due to CRISPR-modified specificity that expands host range beyond natural isolates. Natural bacteriophages retain volume leadership in veterinary medicine applications across Southeast Asia, where cost constraints favor established isolation protocols. The infectious diseases segment attracts concentrated R&D investment as carbapenem-resistant Enterobacteriaceae outbreaks intensify clinical demand for alternatives to last-resort antibiotics.
Japan's PMDA operates accelerated review pathways for phage therapies targeting priority pathogens, while Australia's TGA maintains stringent manufacturing standards that shape product registration timelines for imported formulations. India's CDSCO is developing phage-specific regulatory guidelines under its broader biotherapeutics framework, though implementation remains uneven across state-level manufacturing inspections. Stakeholders must monitor regulatory harmonization progress between national agencies to anticipate market access sequencing and manufacturing localization requirements.
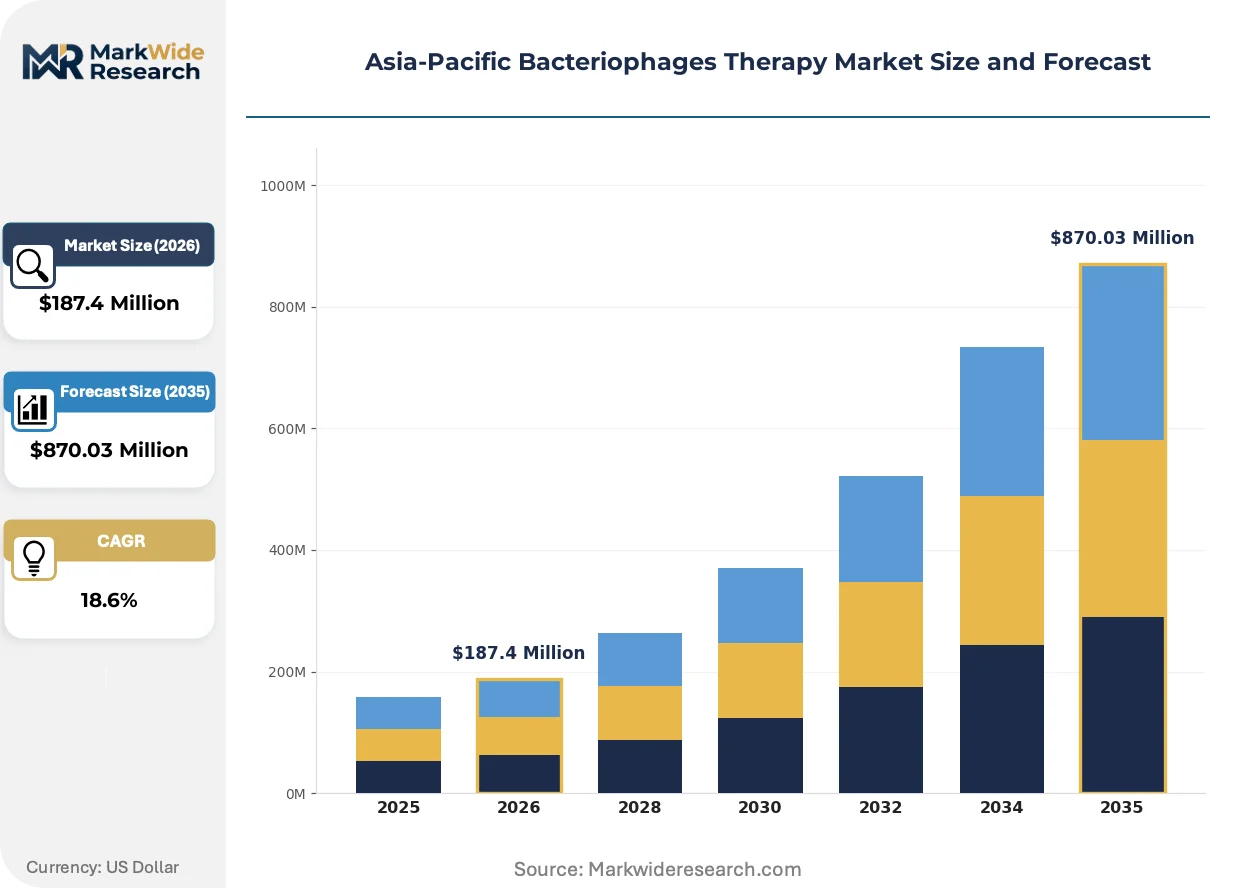
Market Dynamics
Modular phage cocktail architectures are redrawing competitive boundaries across Asia-Pacific hospital procurement, enabling therapeutic customization against polymicrobial infections while fragmenting traditional antibiotic supply relationships.
Growth Catalysts
- PMDA Accelerated Review Pathways:Japan's pharmaceutical regulator prioritizes phage therapies targeting carbapenem-resistant pathogens, compressing clinical trial-to-market timelines for qualified sponsors.
- Hospital Antimicrobial Stewardship Mandates:Australian tertiary care centers face binding reduction targets for broad-spectrum antibiotic consumption, creating procurement pull for targeted bacteriophage alternatives.
- CRISPR-Modified Host Range Expansion:Engineered phage platforms now lyse multiple bacterial species per formulation, collapsing the cost-per-pathogen economics that previously favored small-molecule cocktails.
Market Restraints
- Cold-Chain Infrastructure Gaps:2-8°C storage requirements for plaque-forming unit viability exclude rural Southeast Asian clinics lacking continuous refrigeration capacity.
- TGA Manufacturing Stringency:Australia's therapeutic goods regulator imposes GMP-equivalent standards on imported phage formulations, extending registration timelines for foreign suppliers.
- Natural Isolate Supply Concentration:Wild-type phage sourcing concentrates in established biobanks, creating dependency risks for manufacturers lacking proprietary isolation capabilities.
Strategic Opportunities
- Veterinary Medicine Underpenetration:Southeast Asian livestock operations present volume potential for cost-optimized natural phage formulations against Salmonella and E. coli contamination.
- CDSCO Phage-Specific Guidelines:India's biotherapeutics framework development signals forthcoming regulatory clarity that would unlock domestic manufacturing investment and export capacity.
- Personalized Phage Matching Protocols:Convergence of rapid bacterial diagnostics with phage susceptibility testing enables patient-specific therapy selection, commanding premium positioning in refractory infection cases.
Industry Challenges
- Phage Banking Standardization Delays:Absence of harmonized quality criteria for master seed stocks complicates multi-site clinical trials and cross-border formulation transfers.
- Formulation Scientist Talent Scarcity:Specialized expertise in phage-host range characterization and lysin stability engineering concentrates in limited academic and commercial centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bacteriophages Therapy Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Bacteriophages, Engineered Bacteriophages, Combination Therapies, Phage-Encapsulated Formulations End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies Application: Infectious Diseases, Antibiotic Resistance, Food Safety, Veterinary Medicine Delivery Mode: Injection, Oral, Topical, Aerosol |
| Companies Covered | Intralytix Inc., PhagePharm Biotech, Phagelux, Proteon Pharmaceuticals, Micreos, Armata Pharmaceuticals, PhagePro Inc., Adaptive Phage Therapeutics, BiomX, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bacteriophages Therapy Market Strategic Shifts
Active reformulation of bacteriophage delivery systems and regulatory engagement models is compressing development cycles while fragmenting traditional antimicrobial procurement hierarchies across Asia-Pacific healthcare systems.
Engineered phage lysin platforms are modularizing therapeutic development by decoupling bacterial targeting domains from cell-wall degradation enzymes. Australian research hospitals now specify custom lysin ratios in procurement tenders rather than accepting fixed-formulation products. This architectural shift is modularizing supplier relationships, enabling clinicians to reconfigure cocktails without switching vendors entirely.
PMDA's Sakigake designation system creates conditional early approval for phage therapies demonstrating efficacy against priority antimicrobial-resistant pathogens. Japanese sponsors gain post-market evidence collection obligations in exchange for truncated pre-market review periods. Hospital pharmacies in Tokyo and Osaka are restructuring formulary committees to accommodate these conditional-entry products.
Diagnostic-directed prescribing is consolidating bacteriophage procurement decisions into centralized hospital pharmacy committees with microbiology laboratory input. South Korean tertiary centers now require positive phage susceptibility reports before therapy authorization, displacing empiric initiation protocols. This behavioral shift concentrates demand validation in Seoul and Busan metropolitan hospital networks with integrated diagnostic-therapeutic workflows.
Asia-Pacific Bacteriophages Therapy Market Segmentation
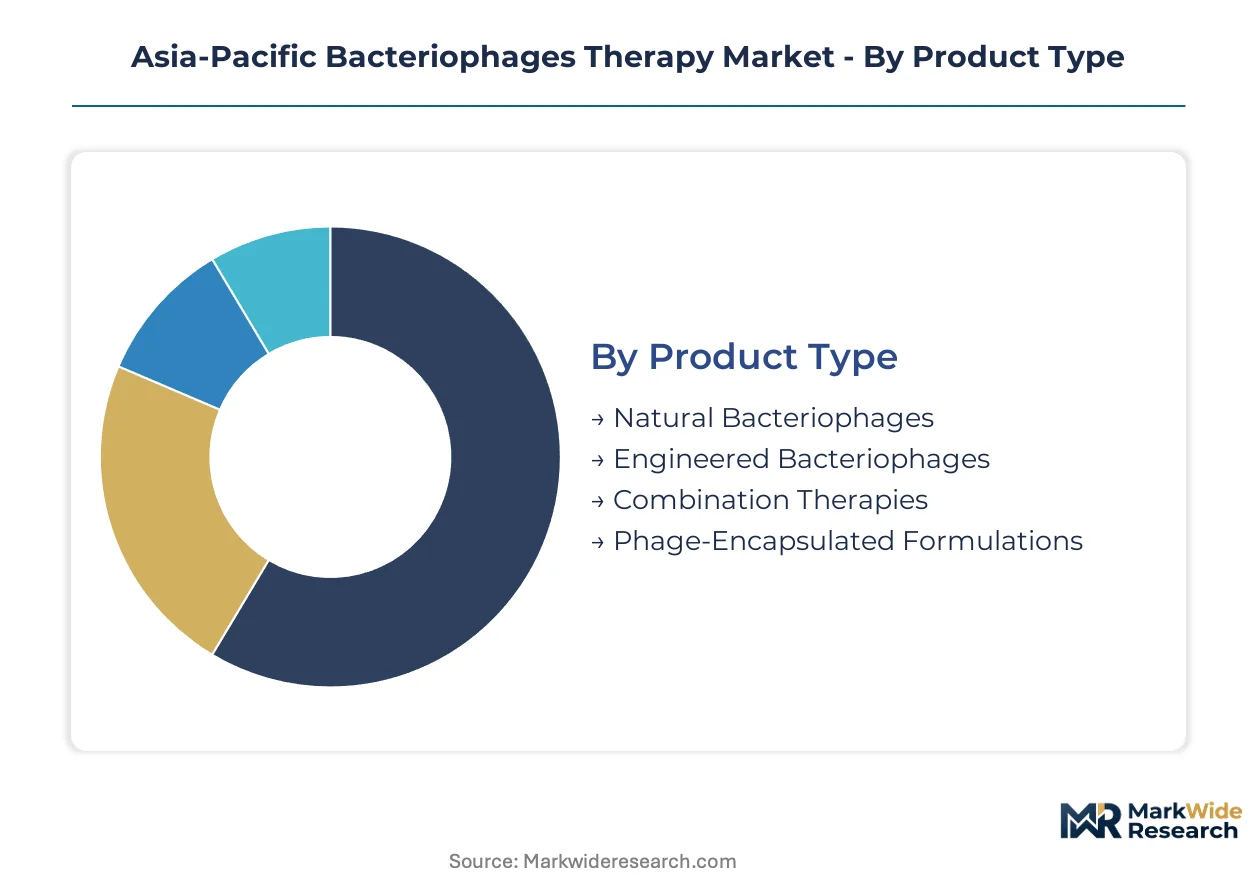
Segmentation in bacteriophage therapy reveals distinct procurement patterns across Asia-Pacific healthcare systems. Product architecture, end-user infrastructure, and delivery requirements each shape vendor positioning and regulatory pathway selection.
Product Type:
Integration depth varies sharply across product architectures—natural isolates deploy as standalone formulations while engineered variants embed within precision medicine protocols.
- Natural Bacteriophages:Wild-type viral isolates targeting specific bacterial hosts through evolved receptor binding. Demand concentrates in Thai and Vietnamese veterinary supply chains where cost sensitivity favors established isolation protocols over synthetic biology investments.
- Engineered Bacteriophages:CRISPR-modified phages with expanded host ranges and programmable lytic kinetics. Australian tertiary hospitals in Sydney and Melbourne are embedding these within antimicrobial stewardship programs as carbapenem-resistant infections intensify.
- Combination Therapies:Phage-antibiotic synergies or sequential regimens.
- Phage-Encapsulated Formulations:Liposome or polymer-encapsulated delivery systems.
Volume placements concentrate in natural bacteriophages; the faster expansion belongs to engineered bacteriophages.
End User:
Customer infrastructure maturity determines formulation complexity tolerance and cold-chain investment capacity.
- Hospitals:Tertiary care centers with integrated microbiology laboratories and pharmacy compounding facilities. Japanese university hospitals in Tokyo and Osaka are expanding phage therapy units under PMDA Sakigake conditional approval pathways.
- Clinics:Outpatient facilities with limited storage infrastructure. South Korean dermatology and ENT clinics in Seoul metropolitan area are adopting topical phage preparations for localized infections where refrigeration constraints are manageable.
- Research Institutions:Academic medical centers and contract research organizations.
- Pharmaceutical Companies:Biopharma sponsors developing proprietary phage banks.
Procurement scale peaks at hospitals; research institutions are climbing the fastest in terms of pipeline engagement.
Application:
Therapeutic focus areas map directly to regulatory priority designations and reimbursement pathway availability.
- Infectious Diseases:Systemic bacterial infections including sepsis, pneumonia, and complicated urinary tract infections. Australian hospitals face binding antimicrobial stewardship targets that accelerate phage therapy formulary inclusion for refractory cases.
- Antibiotic Resistance:Infections caused by multidrug-resistant organisms including carbapenem-resistant Enterobacteriaceae and methicillin-resistant Staphylococcus aureus. Japanese PMDA priority pathogen list directs accelerated review resources toward phage sponsors targeting these specific resistance profiles.
- Food Safety:Phage-based biocontrol in livestock and processing environments.
- Veterinary Medicine:Animal health applications in aquaculture and poultry production.
Clinical revenue concentrates in infectious diseases; antibiotic resistance applications are gaining share fastest as regulatory incentives align.
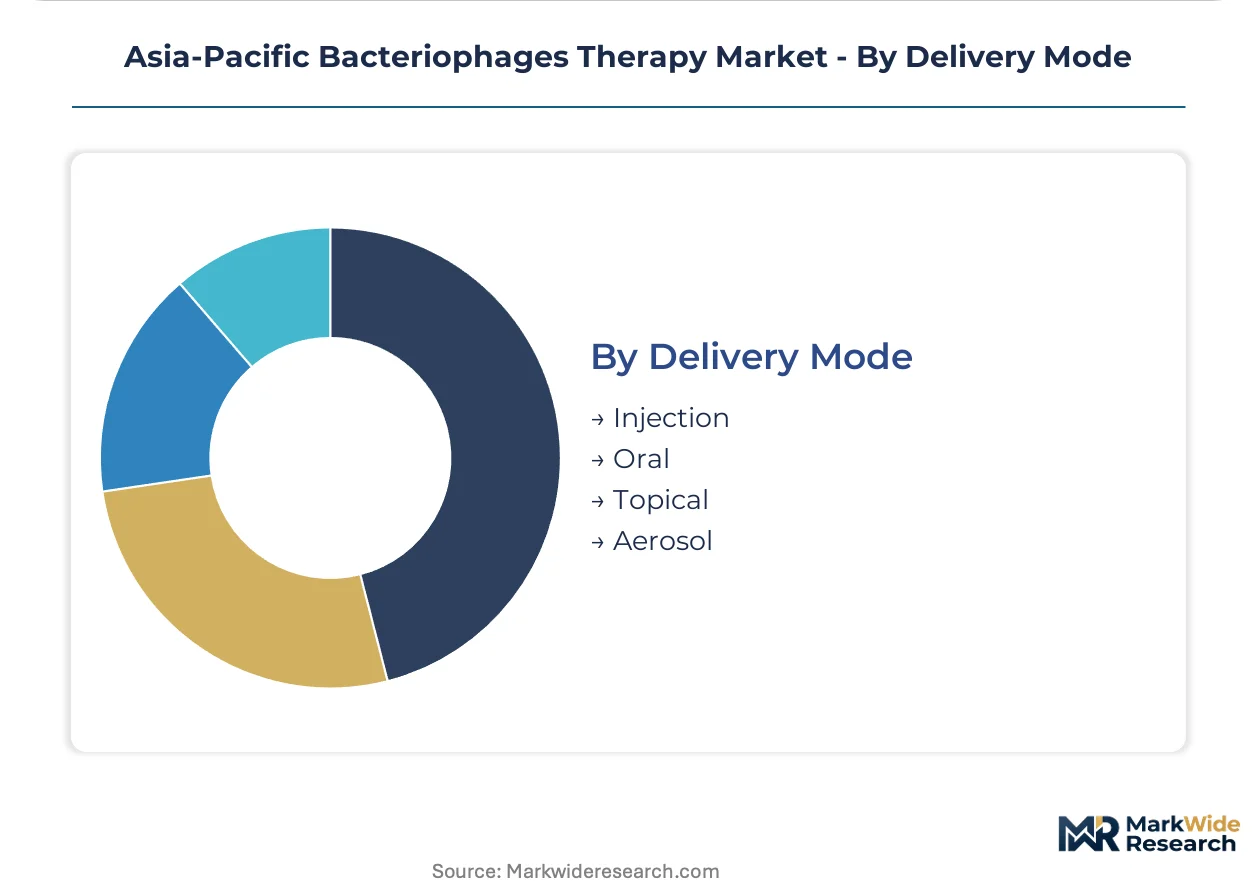
Delivery Mode:
Route of administration dictates manufacturing scale, stability requirements, and distribution partnership structures.
- Injection:Intravenous or intramuscular administration of purified phage suspensions. South Korean hospital networks in Busan and Daegu are standardizing injectable phage protocols for bloodstream infections with centralized pharmacy preparation.
- Oral:Enteric-coated capsules or liquid formulations for gastrointestinal infections. Australian compounding pharmacies are developing patient-specific oral phage preparations under TGA special access schemes.
- Topical:Creams, gels, or wound dressings for localized skin and soft tissue infections.
- Aerosol:Nebulized formulations for respiratory tract infections.
Injectable volumes dominate hospital procurement; topical delivery is expanding most quickly in outpatient settings with lower infrastructure barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phage therapy production concentrates in North American and European biobanks, while Asia-Pacific consumption accelerates through hospital procurement mandates and regulatory streamlining across Japan, Australia, and South Korea.
Japan
Tokyo and Osaka university hospitals drive clinical demand through PMDA Sakigake conditional approval pathways for carbapenem-resistant infections. The national pharmaceutical regulator prioritizes phage sponsors targeting priority pathogens on its antimicrobial resistance list. Kanto region medical centers are restructuring pharmacy committees to accommodate conditional-entry phage products with post-market evidence obligations.
Australia
Sydney and Melbourne tertiary hospitals embed engineered phage formulations within binding antimicrobial stewardship reduction targets. The Therapeutic Goods Administration imposes GMP-equivalent manufacturing standards on imported formulations, extending registration timelines for foreign suppliers. Victorian hospital networks are standardizing injectable phage protocols for bloodstream infections with centralized pharmacy preparation.
South Korea
Seoul metropolitan dermatology and ENT clinics adopt topical phage preparations for localized infections where refrigeration constraints remain manageable. The Ministry of Food and Drug Safety oversees phage therapy oversight alongside the national health insurance review system. Busan and Daegu hospital networks require positive phage susceptibility reports before therapy authorization, displacing empiric initiation protocols.
India
Maharashtra and Gujarat pharmaceutical manufacturing zones anticipate domestic production scale-up pending CDSCO phage-specific guideline finalization. The national pharmaceutical regulator is developing biotherapeutics framework clarity that would unlock manufacturing investment and export capacity. Telangana research institutions concentrate pipeline engagement for veterinary phage applications against livestock Salmonella contamination.
Singapore
Biomedical research parks attract phage banking infrastructure investment from regional sponsors seeking ASEAN distribution hubs. The national pharmaceutical regulator maintains alignment with international GMP standards for biotherapeutics importation. Biopolis research clusters host contract development organizations specializing in phage-host range characterization for Southeast Asian bacterial strain collections.
Asia-Pacific Bacteriophages Therapy Market Competitive Environment
The competitive structure tilts toward technology-led specialists with proprietary phage bank architectures and geographic-focused food safety applicators. Player concentration remains moderate, with distinct capability clusters separating clinical therapeutic developers from veterinary and biocontrol suppliers. Two dominant archetypes occupy the landscape: biobank-anchored therapy providers with personalized matching protocols, and regional formulation specialists with cost-optimized natural isolate supply chains. Competitive moves center on strategic partnerships with hospital systems for long-term supply agreements, and geographic licensing to navigate fragmented national regulatory pathways.
Among North American biotherapeutics developers, Intralytix Inc. and Adaptive Phage Therapeutics occupy positions within the proprietary phage bank tier, while Phagelux anchors the East Asian food safety application segment. These three exemplify divergent strategic positioning—Intralytix represents the biobank-sustained supply agreement model, Adaptive Phage Therapeutics sits within the personalized matching protocol specialization, and Phagelux demonstrates geographic concentration in non-clinical biocontrol markets. Each archetype faces distinct capability requirements: clinical-grade GMP manufacturing for hospital-facing developers, rapid strain isolation for personalized therapy providers, and cost-optimized fermentation scale for agricultural applicators.
| Leading Market Players |
|---|
| Intralytix Inc. |
| PhagePharm Biotech |
| Phagelux |
| Proteon Pharmaceuticals |
| Micreos |
| Armata Pharmaceuticals |
| PhagePro Inc. |
| Adaptive Phage Therapeutics |
| BiomX |
| Others |
Value Chain & Pricing Dynamics
Japanese hospital formulary committees demanding GMP-equivalent documentation for imported phage formulations are forcing foreign suppliers to absorb certification costs or localize manufacturing, compressing margins while elevating domestic producers with established quality infrastructure.
Pricing Analysis
Margin tightening in engineered phage tiers reflects CRISPR-platform amortization costs and cold-chain logistics premiums. Three-tier pricing structure across premium-engineered, standard-natural, and economy-veterinary levels separates hospital procurement from livestock applications. Cost-down pressure on natural isolate formulations accelerates because Southeast Asian veterinary buyers prioritize unit economics over host-range precision. Clinics in Seoul and Busan metropolitan areas exhibit highest price sensitivity due to limited reimbursement pathways, while Australian tertiary hospitals accept premium positioning for stewardship-mandated alternatives.
Supply Chain Analysis
Australia's TGA manufacturing stringency and Japan's PMDA localization incentives are reshaping sourcing patterns toward domestic biobank development. Supply concentrates in established North American and European phage repositories, with emerging capacity in Indian pharmaceutical zones pending CDSCO guideline finalization. Master seed stock preparation, purified lysin production, and cold-chain distribution equipment constitute critical input dependencies. Single-source vulnerability pervades wild-type isolate sourcing from legacy biobanks. Distribution runs through hospital pharmacy committees with integrated microbiology laboratory networks in Tokyo, Sydney, and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
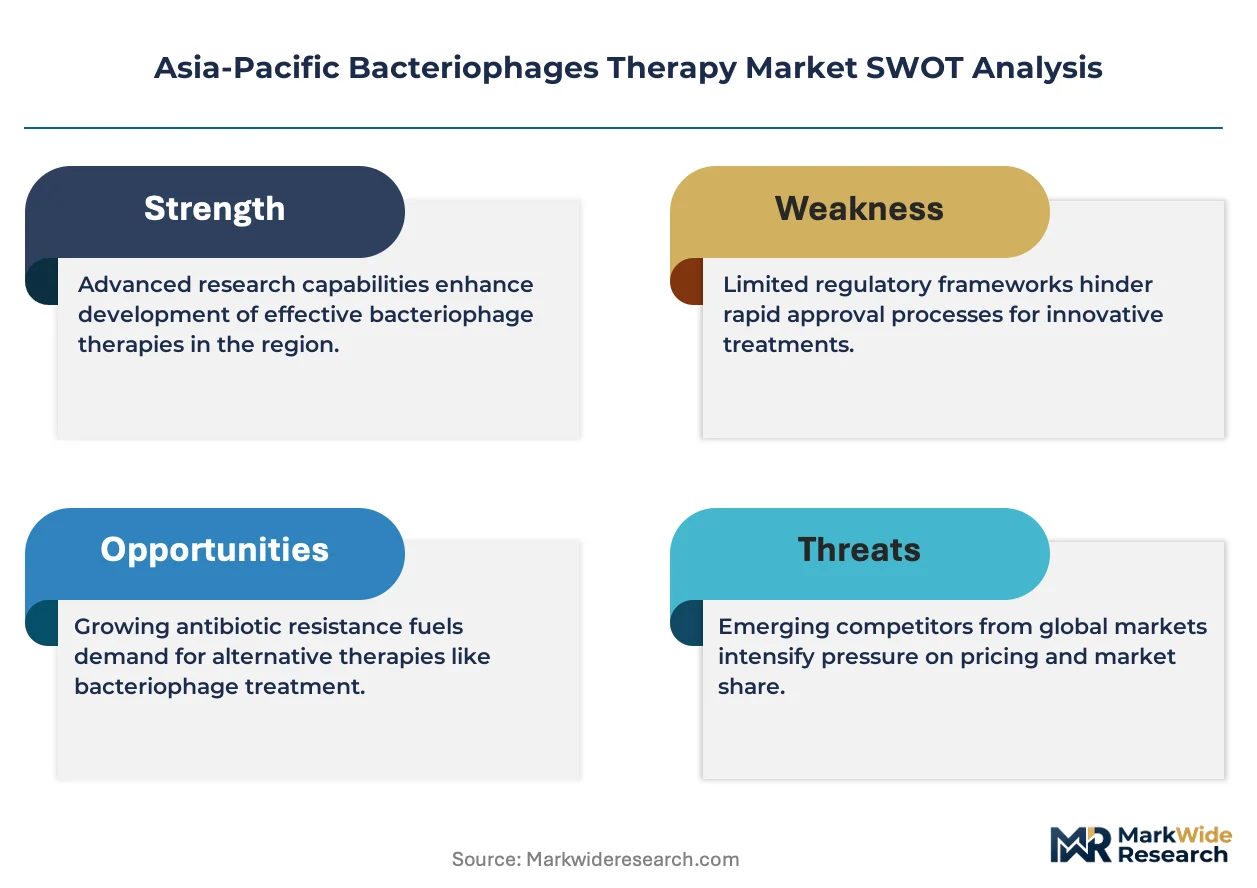
Regulatory harmonization delays between national agencies are forcing subscale phage developers into partnership or exit, consolidating competitive control among biobank-anchored specialists with multi-market registration capabilities.
For Market Incumbents: Anchor proprietary phage bank architectures through long-term supply agreements with Australian and Japanese hospital systems facing binding antimicrobial stewardship mandates. Deepen backward integration into master seed stock preparation to reduce dependency on external biobank licensing. Invest in GMP-equivalent manufacturing localization ahead of CDSCO guideline implementation to preempt Indian market access barriers. For New Entrants and Emerging Players: Launch via veterinary supply chain partnerships in Thai and Vietnamese livestock operations where cost-optimized natural formulations face limited regulatory friction. Target Southeast Asian aquaculture biocontrol applications as the most penetrable segment given minimal cold-chain infrastructure requirements. Pursue white-label manufacturing arrangements with established fermentation facilities to bypass capital-intensive GMP buildout. For Investors and Strategic Acquirers: Re-rating potential sits with personalized phage matching protocol developers given convergence of rapid bacterial diagnostics with susceptibility testing workflows. Acquisition target archetype: mid-cap specialists with proprietary isolation capabilities and existing PMDA or TGA registration pathways. Watch for CDSCO phage-specific guideline publication as inflection indicator unlocking Indian manufacturing investment and export capacity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Phage Bank Infrastructure Investment | Proprietary biobank architectures secure long-term supply agreements with Tokyo and Osaka university hospitals under PMDA pathways. |
| GMP Manufacturing Localization | Domestic production capacity in Maharashtra and Gujarat pharmaceutical zones anticipates CDSCO guideline finalization for market access. |
| Diagnostic-Therapeutic Integration | Phage susceptibility testing convergence with rapid bacterial diagnostics enables patient-specific therapy selection in South Korean hospital networks. |
| Veterinary Formulation Scale-Up | Cost-optimized natural phage production targets Southeast Asian livestock operations with manageable refrigeration requirements. |
| Regulatory Harmonization Engagement | Multi-agency coordination between PMDA, TGA, and MFDS accelerates cross-border clinical trial standardization and formulation transfers. |
Study Parameters
Independent corroboration across hospital formulary directors, pharmaceutical regulatory affairs leads, phage therapy clinical investigators, and veterinary supply chain managers underwrites the qualitative findings. Secondary validation draws from PMDA Sakigake designation records, TGA biotherapeutics registration databases, CDSCO draft guideline consultations, and Australian antimicrobial stewardship program reports. Bottom-up demand modeling from hospital procurement volumes and top-down market sizing from biobank capacity disclosures were cross-referenced to establish analytical consistency.
Rate-of-change decomposition across natural versus engineered phage product architectures, hospital versus clinic versus veterinary end-user infrastructure tiers, and injectable versus oral versus topical delivery modes structured the projection framework. CAGRs were derived from segment-level growth trajectory analysis incorporating regulatory pathway velocity, cold-chain investment cycles, and diagnostic-therapeutic integration timelines. Modeled inputs included phage susceptibility testing adoption curves in South Korean metropolitan hospital networks and CDSCO guideline implementation probability assessments.
PMDA regulatory priority shifts, TGA manufacturing standard revisions, and CDSCO guideline publication delays are the dominant revision risks. Forecasts reflect documented assumptions regarding national agency coordination momentum and hospital procurement mandate enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Amoxicillin Market