
 Becker Muscular Dystrophy Market | 2026-2036
Becker Muscular Dystrophy Market Size, Share, and Industry Trends Forecast 2026-2036
Becker Muscular Dystrophy Market Analysis
Modular treatment protocols combining corticosteroid maintenance with intermittent gene therapy dosing is recalibrating how payers evaluate lifetime cost of care. Sanofi leverages its rare disease infrastructure to anchor European distribution of neuromuscular therapies. Sarepta Therapeutics specializes in antisense oligonucleotide platforms and dominates exon-skipping development pipelines. Pfizer competes through manufacturing scale and navigates regulatory complexity across multiple jurisdictions.
Becker Muscular Dystrophy constitutes a progressive X-linked recessive neuromuscular disorder characterized by mutations in the DMD gene producing partially functional dystrophin protein, with onset typically in adolescence and variable progression rates affecting skeletal and cardiac muscle function. The condition demands sustained multidisciplinary management spanning cardiomyopathy surveillance, respiratory support, and mobility preservation. Gene therapy segments attract capital due to curative intent, while corticosteroids retain volume leadership as the chronic maintenance standard. Intravenous delivery modes command premium positioning for hospital-administered biologics, though subcutaneous formulations gain traction in homecare settings where patient convenience drives formulary decisions.
The FDA's accelerated approval pathway and the EMA's PRIME designation for rare diseases create dual-track regulatory momentum that compresses development timelines and shapes trial design standards. REACH compliance and ISO 13485 quality management requirements impose manufacturing rigor that filters contract production capabilities and concentrates supply among validated facilities. Stakeholders must weigh portfolio prioritization against evolving payer evidence thresholds for gene therapy reimbursement.
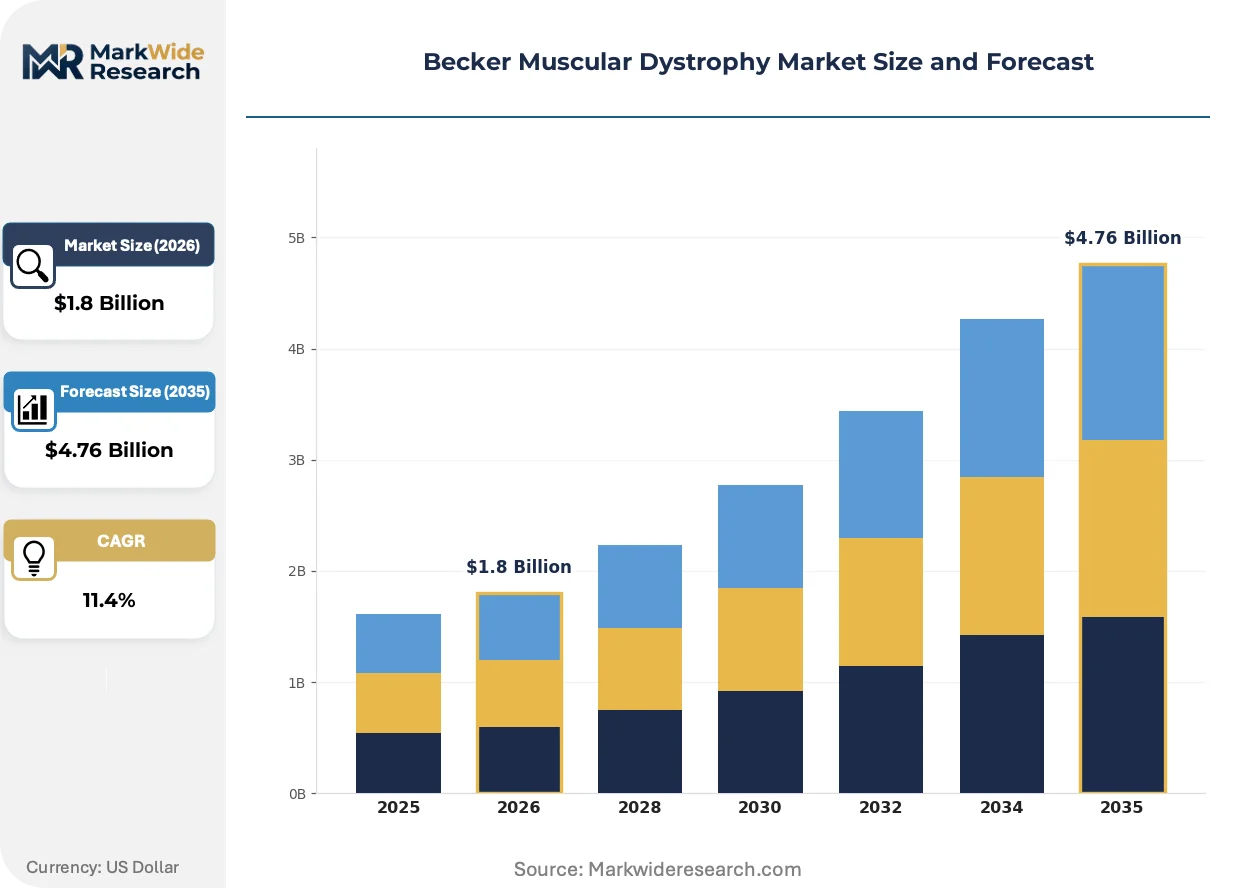
Market Dynamics
The Becker Muscular Dystrophy market pivots on FDA's accelerated approval pathway compressing gene therapy commercialization timelines from decade-long horizons to actionable investment cycles. This regulatory velocity is restructuring how developers sequence clinical programs and how payers model lifetime cost-benefit frameworks for curative interventions.
Growth Catalysts
- EMA PRIME Designation:The European Medicines Agency's priority medicines scheme fast-tracks neuromuscular therapy assessments, compressing pre-market authorization phases and attracting development capital toward orphan indications.
- Specialty Clinic Networks:Dedicated neuromuscular centers in the United States, Germany, and Japan are consolidating patient access pathways and generating real-world evidence that supports regulatory submissions and reimbursement negotiations.
- Exon-Skipping Platforms:Antisense oligonucleotide technologies targeting specific DMD gene mutations are expanding addressable patient populations beyond traditional corticosteroid-reliant cohorts.
Market Restraints
- Manufacturing Concentration:ISO 13485-compliant viral vector production facilities cluster in North America and Western Europe, creating supply bottlenecks that limit gene therapy scale-up for Becker Muscular Dystrophy indications.
- Reimbursement Evidence Thresholds:Payers in Germany and Japan are demanding extended follow-up data before covering one-time curative therapies, stretching cash conversion cycles for developers.
- Cardiac Surveillance Burden:Progressive cardiomyopathy monitoring requirements impose sustained healthcare utilization costs that complicate pharmacoeconomic modeling for novel interventions.
Strategic Opportunities
- Subcutaneous Formulation Migration:Home-administered delivery modes are opening addressable markets beyond hospital-centric infusion centers, particularly in Japanese and German ambulatory care networks.
- Modular Treatment Protocols:Corticosteroid maintenance paired with intermittent gene therapy dosing is creating new reimbursement categories that blend chronic and curative funding mechanisms.
- US Orphan Drug Exclusivity:The FDA's seven-year market exclusivity provision for rare disease therapies is incentivizing portfolio prioritization toward Becker Muscular Dystrophy over more competitive neuromuscular indications.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production expertise concentrates among a limited pool of bioprocess engineers, constraining capacity expansion timelines.
- REACH Compliance Complexity:Chemical safety registration requirements for oligonucleotide components are extending European supply qualification periods and raising working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Becker Muscular Dystrophy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Corticosteroids, Antisense Oligonucleotides, Exon Skipping Delivery Mode: Intravenous, Oral, Subcutaneous, Local End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Neuromuscular Disorders, Genetic Disorders, Rare Diseases, Muscle Degeneration |
| Companies Covered | Sanofi, Vertex Pharmaceuticals, Sarepta Therapeutics, Italfarmaco, Edgewise Therapeutics, Pfizer, Roche, ReveraGen BioPharma, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Becker Muscular Dystrophy Market Emerging Trajectories
Gene therapy manufacturing scale-up and regulatory science convergence are compressing development timelines while fragmenting traditional stakeholder control over patient access pathways. These forces are redistributing value capture across the care continuum.
Micro-dystrophin gene delivery systems are expanding into ambulatory infusion settings, enabling treatment administration outside traditional academic medical centers. Community-based neurology practices in the United States are adopting these platforms to retain patient populations previously referred to tertiary centers. This geographic decentralization is expanding into suburban and rural markets where specialty clinic density has historically limited trial enrollment and commercial penetration.
REACH compliance and EMA's evolving guidance on advanced therapy medicinal products are imposing batch-release documentation requirements that filter contract manufacturing capabilities. European developers are responding by consolidating supply relationships with validated viral vector facilities in Germany and Switzerland. The regulatory friction most acutely affects mid-stage programs lacking capital to build captive manufacturing infrastructure.
Patient advocacy organizations are reshaping trial design standards by demanding earlier pediatric enrollment and functional outcome measures beyond surrogate biomarkers. These preferences are displacing traditional six-minute walk test endpoints in favor of upper limb function assessments that reflect Becker Muscular Dystrophy's variable progression patterns. The behavioral shift is most visible in United States and Japanese regulatory submissions, where agency-industry-advocate triangulation is establishing new evidentiary precedents.
Becker Muscular Dystrophy Market Segmentation
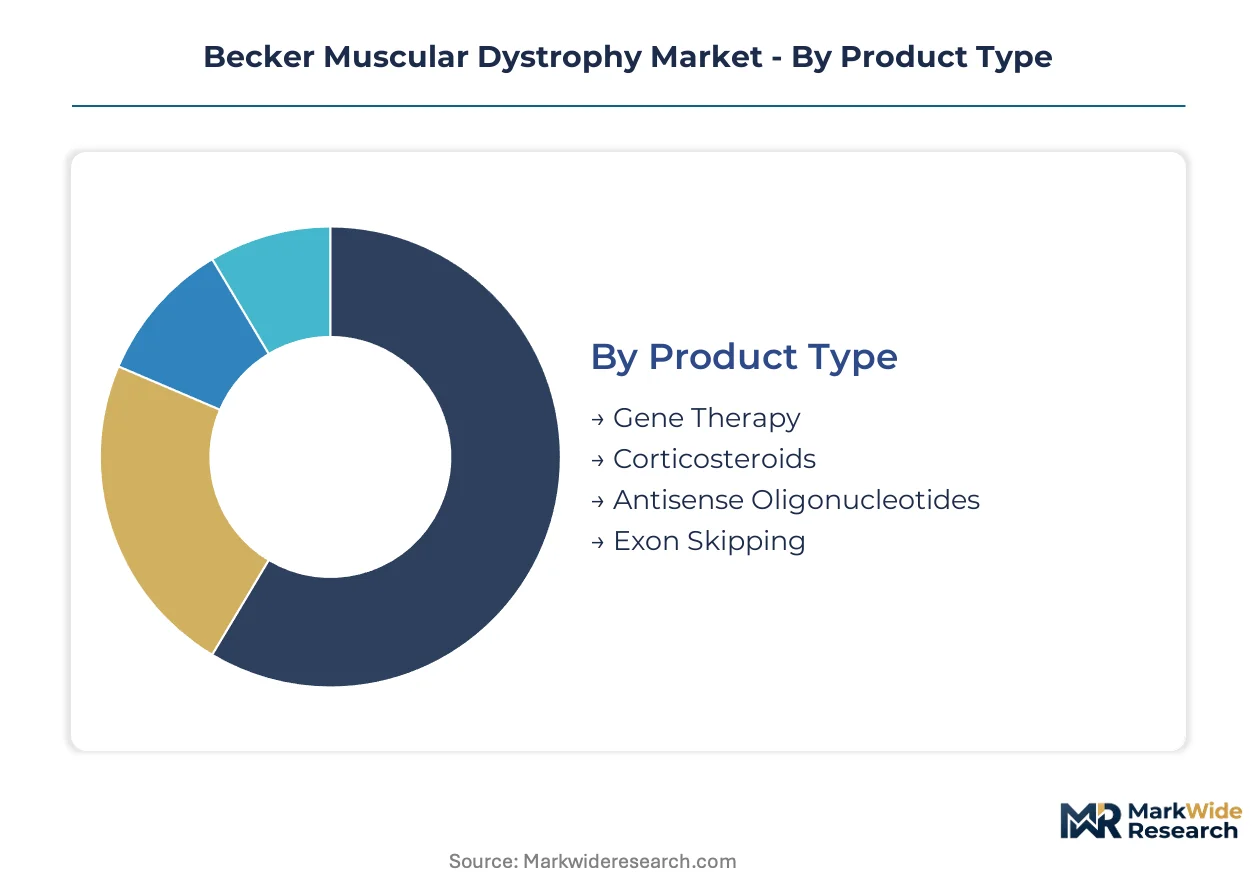
Segmentation in Becker Muscular Dystrophy therapeutics reveals how treatment protocols evolve from chronic maintenance toward curative intent. Upgrade cycles between corticosteroid regimens and gene therapy interventions are reshaping prescribing patterns across care settings.
Product Type:
Replacement dynamics between chronic maintenance standards and emerging curative platforms are redistributing development capital across molecular modalities.
- Gene Therapy:Micro-dystrophin delivery via adeno-associated viral vectors targets root genetic pathology with single-administration curative intent. United States academic medical centers in Boston and Philadelphia are consolidating early adoption cohorts as FDA accelerated approvals compress commercialization timelines for developers with validated manufacturing partnerships.
- Corticosteroids:Prednisone and deflazacort regimens remain the chronic maintenance backbone, preserving ambulatory function through anti-inflammatory mechanisms. German statutory health insurers maintain volume leadership in Europe, though Japanese reimbursement frameworks are tightening evidence requirements for long-term pediatric exposure.
- Antisense Oligonucleotides:Sequence-specific RNA targeting enables mutation-directed intervention for splice-site variants.
- Exon Skipping:Phosphorodiamidate morpholino oligomers restore reading frame functionality in amenable deletion mutations.
Volume placements concentrate in Corticosteroids; the faster expansion belongs to Gene Therapy.
Delivery Mode:
Cost tier stratification separates hospital-administered biologics from self-administered maintenance therapies, with reimbursement codes adapting to site-of-care migration.
- Intravenous:Infusion-center administration of viral vector gene therapies and high-dose corticosteroid pulses demands specialized nursing infrastructure and cardiac monitoring capabilities. United States hospital outpatient departments command premium reimbursement rates that offset complex logistics, though German ambulatory infusion networks are capturing share through integrated care contracts.
- Subcutaneous:Home-administered antisense oligonucleotides and depot corticosteroid formulations reduce healthcare utilization burdens. Japanese homecare nursing agencies are expanding capacity to support subcutaneous exon-skipping protocols, enabled by METI-directed telemedicine infrastructure investments.
- Oral:Daily corticosteroid tablets dominate pediatric initiation protocols.
- Local:Intramuscular depot injections address focal muscle group deterioration.
Hospital-centric administration retains value concentration; subcutaneous migration is climbing the fastest among delivery innovations.
End User:
Patient volume distribution reflects geographic concentration of neuromuscular specialty expertise and payer network configurations.
- Hospitals:Tertiary academic centers in the United States, Germany, and Japan coordinate multidisciplinary care including cardiomyopathy surveillance and respiratory support. Cleveland Clinic and Heidelberg University Hospital anchor referral networks that consolidate gene therapy eligibility screening and adverse event management protocols.
- Clinics:Dedicated neuromuscular centers in suburban United States markets and German metropolitan regions are decentralizing access beyond traditional academic hubs. These facilities are capturing maintenance therapy volumes through extended-hour infusion scheduling and patient navigation services.
- Homecare:Subcutaneous administration training and remote monitoring platforms are expanding addressable populations.
- Pharmacies:Oral corticosteroid dispensing retains chronic prescription volume leadership.
Hospital systems anchor therapeutic complexity; clinic networks are gaining share fastest through geographic expansion.
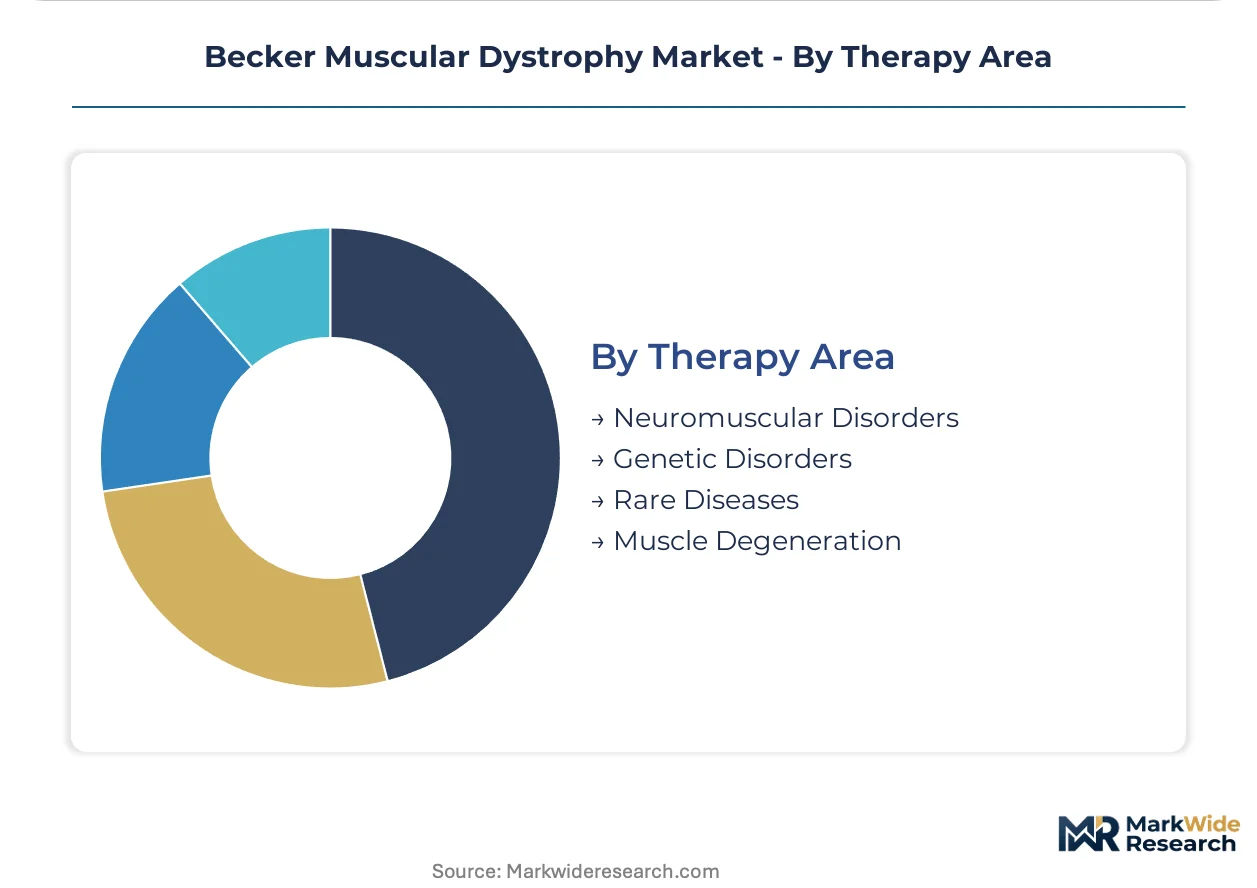
Therapy Area:
Application focus determines regulatory pathway selection and evidentiary standards for market authorization.
- Neuromuscular Disorders:Skeletal muscle function preservation drives functional outcome endpoints and payer value assessment. FDA guidance on upper limb function measures is displacing six-minute walk tests in United States trial designs, reflecting Becker Muscular Dystrophy's variable ambulatory progression patterns.
- Genetic Disorders:DMD gene mutation specificity enables stratified medicine approaches and companion diagnostic development. EMA PRIME designation criteria prioritize genetic confirmation standards that align European and Japanese regulatory submissions.
- Rare Diseases:Orphan drug exclusivity provisions incentivize portfolio prioritization.
- Muscle Degeneration:Histopathological outcome measures support mechanistic claims.
Neuromuscular specialization commands development investment; genetic disorder framing is expanding most quickly through diagnostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States orphan drug tax credits and Japanese regenerative medicine zones concentrate gene therapy development capital. Germany's statutory health insurance framework anchors European reimbursement negotiations. These fiscal instruments reshape where clinical trials initiate and manufacturing capacity expands.
United States
FDA accelerated approvals for micro-dystrophin gene therapies compress commercialization timelines for developers with validated manufacturing partnerships. The Orphan Drug Tax Credit covers half of clinical trial costs, attracting venture capital toward Becker Muscular Dystrophy pipelines. Boston and Philadelphia academic medical centers anchor early adoption networks for hospital-administered biologics.
Germany
G-BA health technology assessments demand extended follow-up data before covering one-time curative therapies, stretching cash conversion cycles for gene therapy developers. REACH compliance for oligonucleotide components extends European supply qualification periods. Heidelberg University Hospital coordinates multidisciplinary care networks that consolidate gene therapy eligibility screening across Baden-Württemberg.
Japan
PMDA regenerative medicine product designation fast-tracks neuromuscular therapy assessments under the Act on Securing Quality, Efficacy and Safety of Products. METI-directed telemedicine infrastructure investments expand homecare nursing capacity for subcutaneous exon-skipping protocols. Tokyo metropolitan neuromuscular centers generate real-world evidence supporting regulatory submissions across Asia-Pacific.
United Kingdom
NICE single technology appraisals impose cost-effectiveness thresholds that filter gene therapy reimbursement for rare disease indications. MHRA post-Brexit regulatory autonomy enables accelerated access partnerships with developers. London and Oxford research clusters concentrate antisense oligonucleotide platform development through university-industry consortia.
Switzerland
Swissmedic parallel consultation procedures align market authorization timelines with EMA assessments, reducing regulatory friction for developers with European strategies. Federal orphan drug reimbursement guarantees minimum revenue thresholds for approved therapies. Basel and Zurich viral vector manufacturing facilities supply validated production capacity to mid-stage gene therapy programs lacking captive infrastructure.
Becker Muscular Dystrophy Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across molecular modality segments. The market structure fragments between pharmaceutical majors with rare disease infrastructure and biotechnology firms with platform-specific expertise. Three archetypes dominate: integrated pharmaceutical conglomerates with neuromuscular portfolios, antisense oligonucleotide platform specialists, and gene therapy developers with viral vector manufacturing partnerships. Competitive moves concentrate on strategic licensing agreements for exon-skipping technologies and consolidation of specialty clinic distribution networks.
Among integrated pharmaceutical conglomerates, Sanofi and Pfizer occupy positions anchored by rare disease commercial infrastructure and manufacturing scale. Sarepta Therapeutics exemplifies the platform-specialist archetype, with its development concentration in antisense oligonucleotide and gene therapy modalities for DMD-related indications. These three companies represent distinct competitive vectors: Sanofi leverages European distribution networks, Pfizer navigates multi-jurisdictional regulatory complexity, and Sarepta dominates exon-skipping pipeline development through sequence-specific RNA targeting expertise.
| Leading Market Players |
|---|
| Sanofi |
| Vertex Pharmaceuticals |
| Sarepta Therapeutics |
| Italfarmaco |
| Edgewise Therapeutics |
| Pfizer |
| Roche |
| ReveraGen BioPharma |
| Novartis |
| Others |
Supply Flow & Price Mechanics
Viral vector production labor costs in North America and Western Europe cascade through three-tier pricing structure across premium, standard, and economy levels for Becker Muscular Dystrophy therapies. ISO 13485-certified facility scarcity in Germany and Switzerland elevates manufacturing premiums for gene therapy developers lacking captive capacity, while REACH compliance extends supply qualification timelines and raises working capital thresholds for oligonucleotide components.
Pricing Analysis
Margin tightening in hospital-administered gene therapy tiers reflects viral vector manufacturing concentration and specialized cardiac monitoring requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery mode complexity, with intravenous infusion commanding premiums over subcutaneous alternatives. Japanese statutory health insurers demonstrate highest price sensitivity for one-time curative therapies, while United States academic medical centers absorb premium positioning through orphan drug reimbursement frameworks.
Supply Chain Analysis
Bioprocess engineer scarcity in Boston and Philadelphia viral vector clusters constrains capacity expansion timelines for micro-dystrophin manufacturing. Supply concentrates in United States, Germany, and Switzerland for validated AAV production, with plasmid DNA and cell culture media dependencies drawing from specialized chemical suppliers. Single-source vulnerability pervades mid-stage developers lacking captive facilities. Distribution runs through hospital outpatient departments and dedicated neuromuscular infusion networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Becker Muscular Dystrophy therapeutics operate as supply-constrained markets where ISO 13485-compliant viral vector manufacturing bottlenecks prop pricing power for validated facility operators. Capacity scarcity in North American and European production clusters elevates returns for incumbents with secured manufacturing partnerships.
For Market Incumbents: Deploy manufacturing partnership exclusivity to lock in viral vector capacity ahead of competitor pipeline maturation. Secure backward integration into plasmid DNA supply to reduce single-source exposure for gene therapy programs. Counter emerging antisense oligonucleotide specialists through extended real-world evidence generation that satisfies German G-BA and Japanese PMDA follow-up data requirements.
For New Entrants and Emerging Players: Launch via subcutaneous formulation development targeting Japanese homecare nursing networks and German ambulatory infusion contracts. Penetrate suburban United States clinic markets where geographic decentralization outpaces academic center capacity. Prioritize modular treatment protocols that blend corticosteroid maintenance with intermittent gene therapy dosing to access blended reimbursement categories.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-stage gene therapy developers with validated EMA PRIME designations and secured Swiss or German manufacturing partnerships. Five-to-ten year viability hinges on regulatory exclusivity duration and payer evidence threshold navigation. Monitor FDA accelerated approval conversion rates to full approval as the decisive inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive viral vector capacity in Basel and Zurich reduces supply risk for EMA submissions. |
| Regulatory Approval Pathway | FDA accelerated approval compresses commercialization timelines for micro-dystrophin programs. |
| Licensing Agreement | Exon-skipping technology partnerships expand addressable patient populations beyond corticosteroid cohorts. |
| Pipeline Diversification | Antisense oligonucleotide platforms hedge against gene therapy manufacturing bottlenecks. |
| Reimbursement Strategy | Modular treatment protocols blend chronic and curative funding mechanisms for payer acceptance. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with formulary database audits and CMS Medicare coverage determinations. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated pipeline stage assumptions and reimbursement trajectory expectations. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Historical trendline analysis of corticosteroid maintenance volumes and gene therapy early adoption curves established baseline growth patterns. Segmentation dimensions encompassed molecular modality, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from polynomial curve fitting of approval velocity and manufacturing capacity expansion rates, incorporating patient advocacy influence on trial design standards and evolving evidentiary requirements for upper limb function endpoints.
Regulatory approval delays, manufacturing capacity shortfalls, and payer evidence threshold escalations are the dominant revision risks. Forecasts reflect assumptions regarding FDA accelerated approval conversion success and EMA PRIME designation retention. Material deviation in viral vector production scalability or German G-BA reimbursement decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
CMO and CDMO Biotechnology Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Cell and Tissue Preservation Market