
 Bacterial Conjunctivitis Drugs Market | 2026-2036
Bacterial Conjunctivitis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial Conjunctivitis Drugs Market Outlook
Indian generic API manufacturers is shifting toward finished ophthalmic dosage forms, tightening supply-side competition for branded incumbents. Bausch + Lomb leverages its North American distribution network to sustain pharmacy channel dominance. Novartis AG anchors European market share through specialized ocular antibacterial formulations. Pfizer Inc. competes on manufacturing scale for broad-spectrum fluoroquinolone eye drops.
Bacterial conjunctivitis drugs comprise antimicrobial agents formulated for ocular surface administration, typically at concentrations between 0.3% and 0.5% active pharmaceutical ingredient in sterile, preserved or preservative-free vehicles, designed to eradicate gram-positive and gram-negative pathogens while minimizing corneal epithelial toxicity. These products serve primary care and ophthalmology settings where rapid bacterial clearance prevents complications and reduces transmission. Topical antibiotics occupy the largest revenue share due to direct site delivery and minimized systemic exposure, while combination therapy segments gain traction where polymicrobial or resistant presentations require multi-mechanism coverage. Eye drop formulations lead volume consumption for adult outpatient cases, though ointment bases retain preference in pediatric populations where dosing compliance challenges persist.
FDA pharmacovigilance requirements and EMA antimicrobial resistance frameworks shape product development pathways, with both agencies tightening post-market surveillance for recurrent-use ophthalmic antibiotics. The EPA monitors manufacturing discharge of active pharmaceutical ingredients, adding environmental compliance costs to production economics. India's CDSCO enforces bioequivalence standards for generic entrants, raising quality barriers for export-oriented suppliers. Stakeholders must monitor evolving resistance surveillance data and regulatory pressure on preservative systems to align R&D priorities with future compliance thresholds.
Market Dynamics
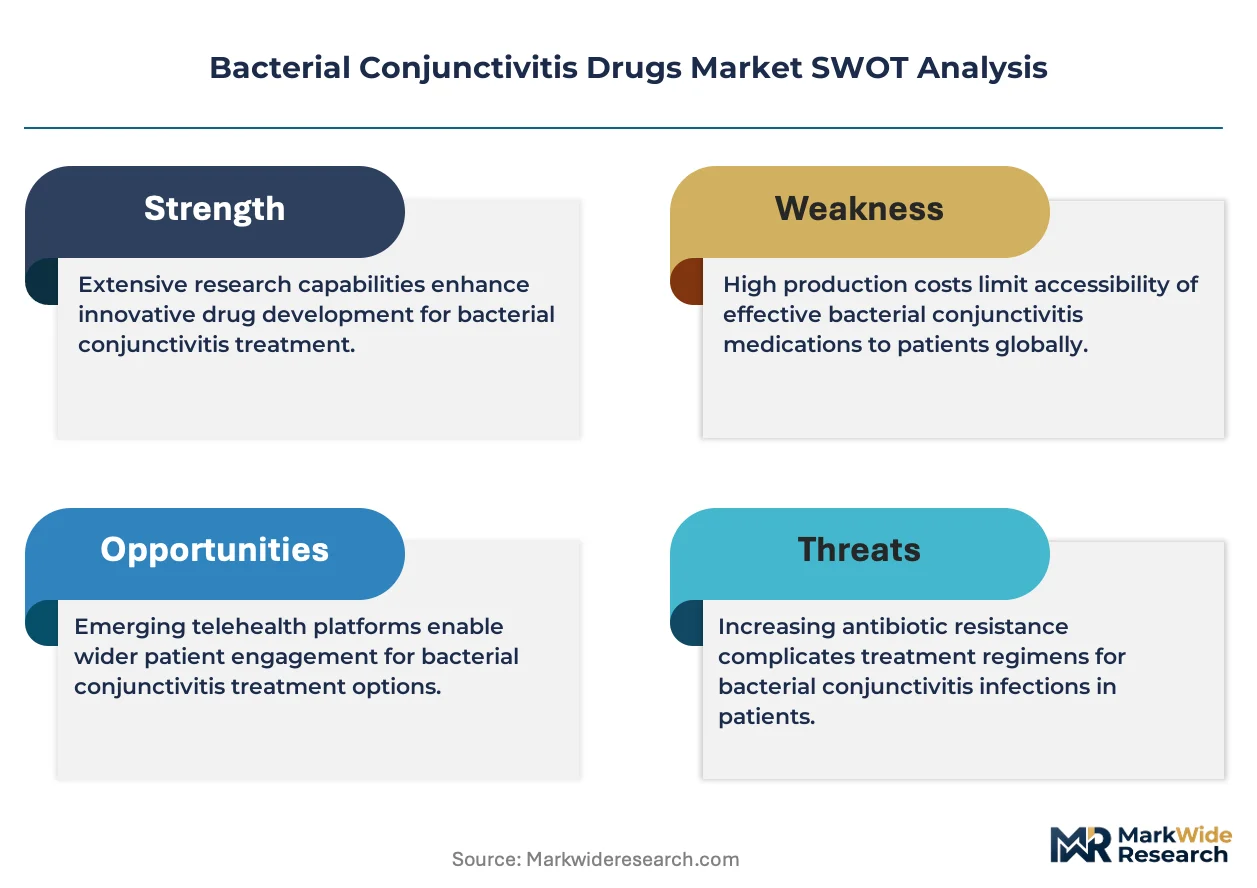
Antimicrobial stewardship mandates from FDA and EMA are compressing prescribing windows for broad-spectrum ophthalmic antibiotics, forcing manufacturers to demonstrate superior resistance profiles against gram-positive and gram-negative pathogens within shorter clinical trial timelines.
Growth Catalysts
- Pediatric ophthalmology expansion:Specialized clinics in the United States and Germany are escalating prescriptions for topical antibiotic eye drops in children under five, where bacterial conjunctivitis incidence peaks seasonally.
- EMA antimicrobial resistance frameworks:Post-market surveillance requirements are accelerating development of narrow-spectrum alternatives with documented pathogen-specific efficacy data.
- Preservative-free formulations:Toxicity-minimizing vehicle technologies are capturing preference in dry-eye-comorbid patient populations requiring recurrent dosing.
Market Restraints
- API supply concentration:Indian generic manufacturers control critical intermediate supply for fluoroquinolone eye drops, exposing branded formulators to export restriction risk.
- Generic substitution pressure:CDSCO bioequivalence standards enable rapid entry of low-cost alternatives, eroding price premiums for originator products within 18-24 months of patent expiry.
- Environmental discharge compliance:EPA manufacturing effluent limits on active pharmaceutical ingredients add filtration and treatment capital requirements to production economics.
Strategic Opportunities
- Combination therapy segments:Polymicrobial infection presentations are creating demand for multi-mechanism coverage products pairing antibiotics with anti-inflammatory agents.
- Ointment base innovation:Pediatric populations with dosing compliance challenges represent underserved demand for prolonged-contact formulations with simplified administration schedules.
- Japan's PMDA streamlined pathways:Orphan drug designation for resistant-strain-targeting formulations offers accelerated review timelines for novel mechanisms.
Industry Challenges
- Corneal toxicity assessment capacity:Specialized ocular toxicology expertise remains concentrated among contract research organizations in the United States and Switzerland, creating bottlenecks for formulation iteration cycles.
- Multinational pharmacovigilance harmonization:Divergent FDA and EMA adverse event reporting timelines complicate global product launches and require redundant safety database infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacterial Conjunctivitis Drugs Market |
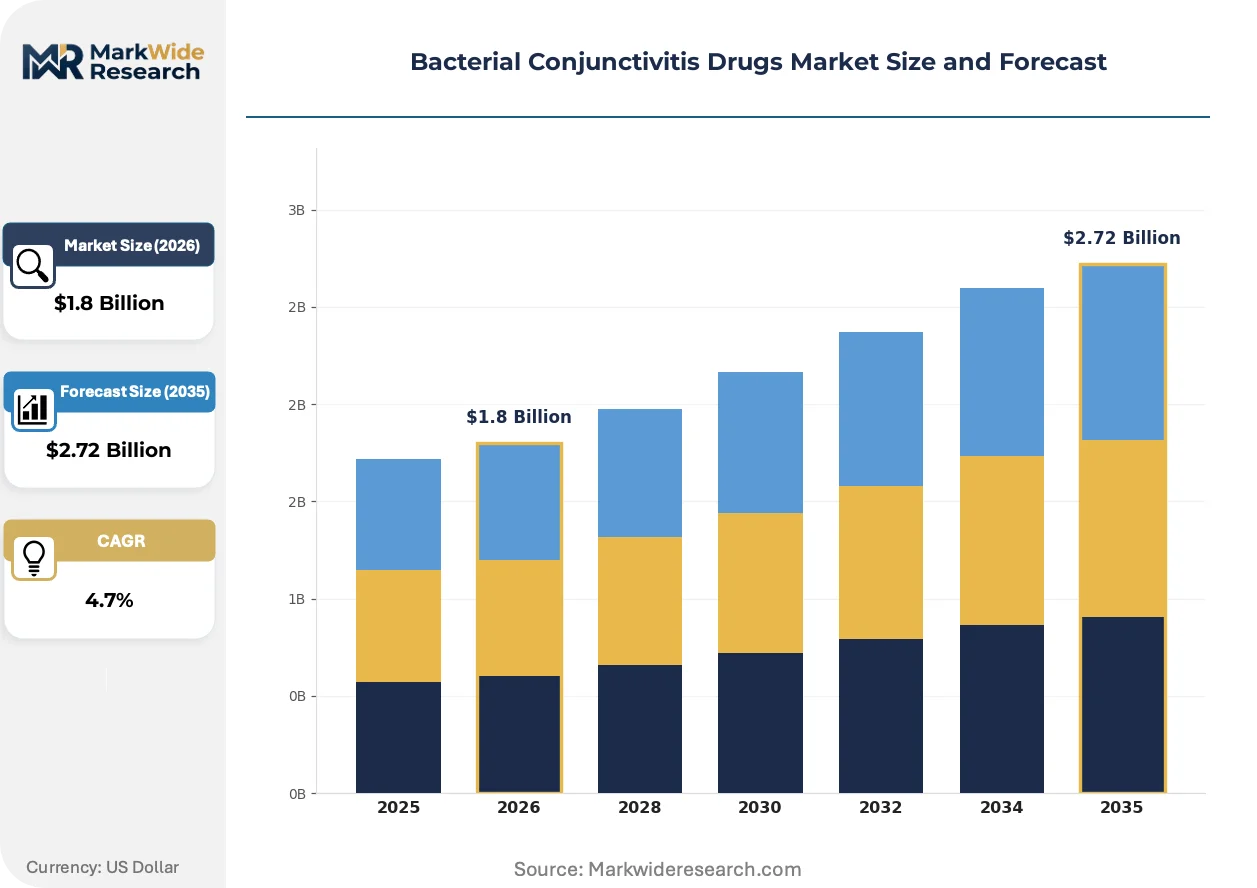
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Topical Antibiotics, Oral Antibiotics, Antiseptic Solutions, Combination Therapy Formulation: Ointment, Eye Drops, Gel, Solution End User: Hospitals, Clinics, Homecare, Pharmacies Ingredient Type: Ciprofloxacin, Ofloxacin, Chloramphenicol, Others |
| Companies Covered | AbbVie Inc., Bausch + Lomb, Novartis AG, Santen Pharmaceutical Co., Ltd., Alcon Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Limited, Pfizer Inc., Johnson & Johnson Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial Conjunctivitis Drugs Market Strategic Shifts
Preservative system chemistry and delivery vehicle engineering are converging to address the dual imperatives of antimicrobial efficacy and ocular surface tolerability that now dominate product differentiation.
Nanostructured lipid carrier technology is unifying hydrophobic active pharmaceutical ingredient solubility with controlled release kinetics in ophthalmic formulations. Mid-sized specialty manufacturers in Germany and Japan are piloting these vehicles for fluoroquinolone compounds with poor aqueous stability. The technology is unifying previously separate formulation development tracks for immediate-release drops and sustained-release depots into single-platform product architectures.
REACH restrictions on quaternary ammonium compounds are compelling reformulation of benzalkonium chloride-preserved antibiotics across European markets. Manufacturers must validate alternative preservation systems—polyquaternium-1, sodium perborate, or proprietary ionic buffers—through full stability and antimicrobial efficacy programs. Ophthalmology clinics in France and Italy are experiencing temporary supply interruptions as suppliers complete these transitions.
Direct-to-clinic distribution models are displacing traditional wholesale pharmacy channels for high-volume ambulatory care accounts. Integrated delivery networks in the United States are consolidating purchasing for affiliated primary care and ophthalmology practices, extracting volume-based concessions that bypass retail markup structures. This concentration is most visible in the southeastern and midwestern states where hospital system expansion has created geographically dense provider networks.
Bacterial Conjunctivitis Drugs Market Segmentation
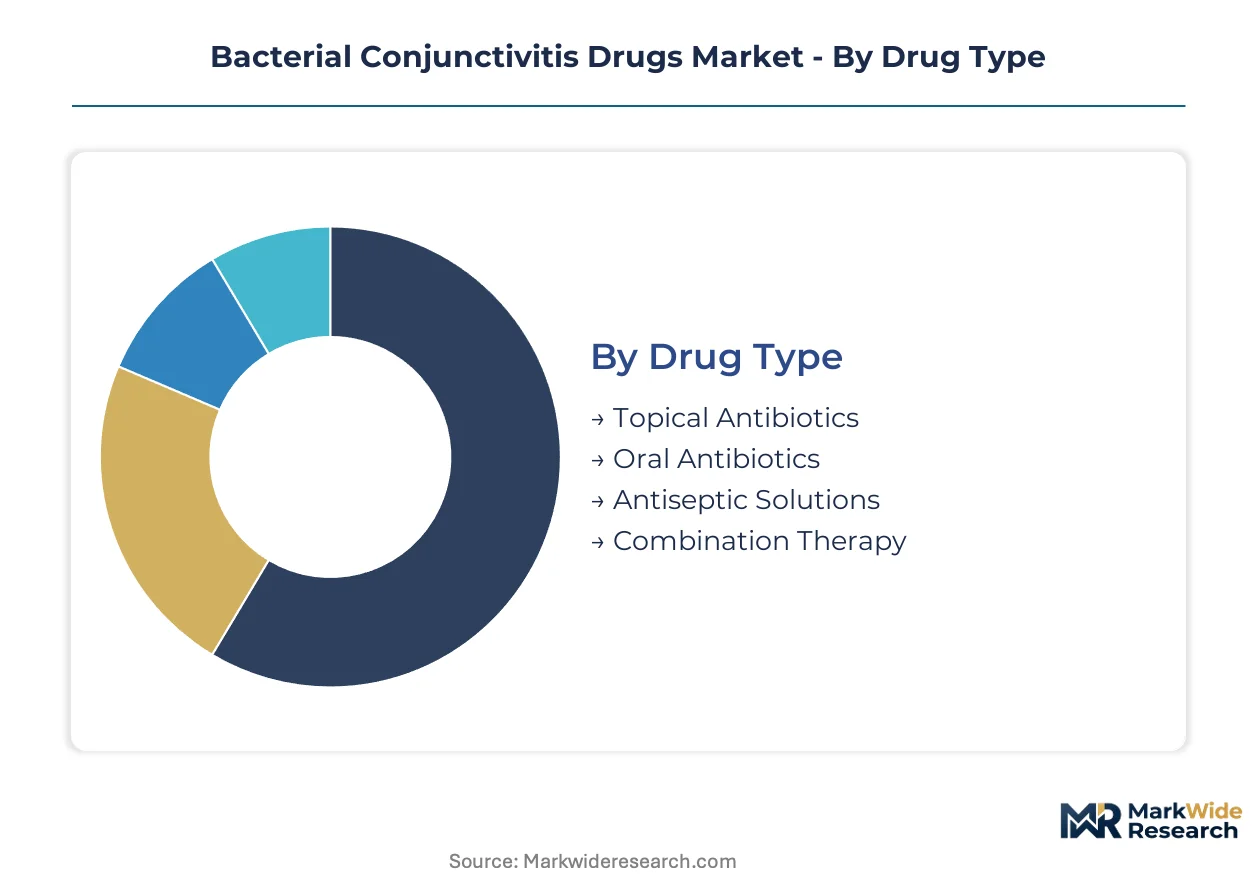
Segmentation in bacterial conjunctivitis drugs reveals how formulation preferences, delivery settings, and active ingredient selection drive purchasing decisions across ambulatory and institutional channels. Manufacturers align R&D investments with the specific efficacy, compliance, and safety requirements that dominate each segment.
Drug Type:
Standardization dominates high-volume segments while combination therapies demand customized development pathways for polymicrobial presentations.
- Topical Antibiotics:Formulated as sterile aqueous or oil-based vehicles delivering 0.3% to 0.5% active pharmaceutical ingredient directly to the ocular surface. Demand concentrates in United States ambulatory settings where rapid bacterial clearance and minimized systemic exposure guide prescribing. FDA pharmacovigilance requirements for recurrent-use products are compressing development timelines for resistance-profile documentation.
- Combination Therapy:Multi-mechanism products pairing antibiotics with anti-inflammatory agents for polymicrobial or resistant presentations. Germany and Japan are escalating prescriptions where diagnostic uncertainty or treatment failure drives coverage expansion. EMA antimicrobial stewardship frameworks favor these formulations when narrow-spectrum monotherapy proves insufficient.
- Oral Antibiotics:Systemic agents reserved for complicated cases or patients unable to tolerate topical administration.
- Antiseptic Solutions:Non-antibiotic antimicrobial options used as adjunctive therapy or in settings with resistance concerns.
Most installed capacity flows through Topical Antibiotics. Expansion is steepest in Combination Therapy.
Formulation:
Cost tiering separates premium preservative-free vehicles from standard preserved formulations, with ointment bases commanding pediatric premiums.
- Eye Drops:Aqueous solutions in unit-dose or multi-dose containers enabling self-administration and rapid onset. Adult outpatient cases in Japan and United States drive volume consumption where convenience and dosing precision matter. Preservative-free variants capture preference among dry-eye-comorbid populations requiring recurrent dosing.
- Ointment:Semisolid petrolatum or mineral oil bases providing prolonged contact time and simplified dosing schedules. Pediatric populations with compliance challenges in Germany and France represent underserved demand. REACH restrictions on quaternary ammonium compounds are forcing reformulation of preserved ointment lines.
- Gel:Viscous vehicles balancing residence time with cosmetic acceptability.
- Solution:Lower-viscosity aqueous preparations for initial irrigation or diagnostic applications.
Manufacturing throughput centers on Eye Drops. Pediatric prescribing is shifting fastest toward Ointment.
End User:
Application setting determines packaging scale, regulatory pathway, and reimbursement complexity for each customer type.
- Clinics:Primary care and ophthalmology practices prescribing first-line therapy for uncomplicated bacterial conjunctivitis. Southeastern and midwestern United States integrated delivery networks are consolidating purchasing for affiliated practices. Direct-to-clinic distribution models are displacing traditional wholesale pharmacy channels for high-volume accounts.
- Hospitals:Institutional settings managing complicated cases, nosocomial transmission risk, or surgical prophylaxis requirements.
- Homecare:Self-administered therapy following initial diagnosis or for recurrent conditions.
- Pharmacies:Retail dispensing channels handling prescription fulfillment and patient counseling.
Prescription volume concentrates in Clinics. Homecare channels are expanding most quickly as telemedicine diagnosis enables remote treatment initiation.
Ingredient Type:
Supply concentration for fluoroquinolone intermediates shapes competitive dynamics across active pharmaceutical ingredient categories.
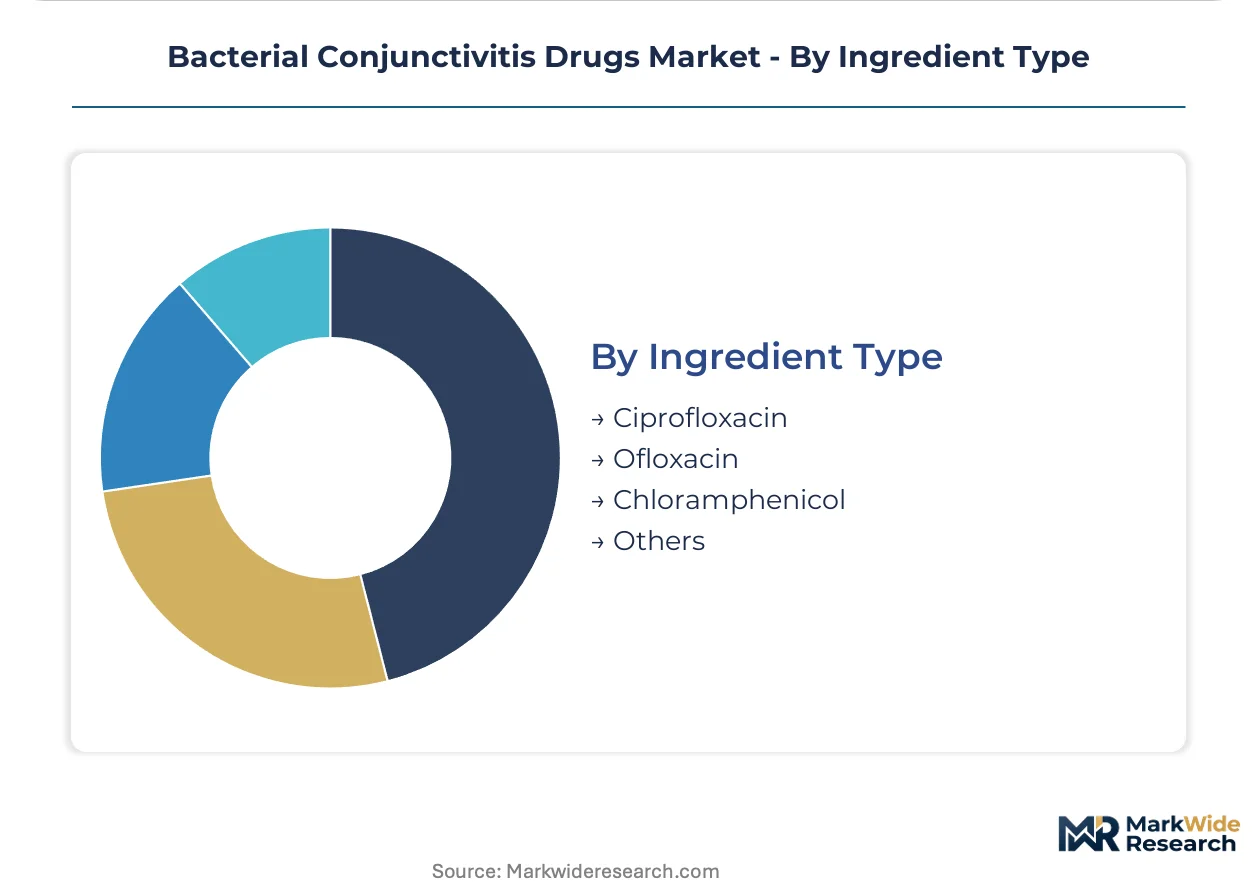
- Ciprofloxacin:Broad-spectrum fluoroquinolone with established efficacy against gram-negative pathogens. Indian generic API manufacturers control critical intermediate supply, exposing branded formulators to export restriction risk. CDSCO bioequivalence standards enable rapid entry of low-cost alternatives.
- Ofloxacin:Second-generation fluoroquinolone with improved gram-positive coverage and favorable corneal penetration profiles.
- Chloramphenicol:Historical broad-spectrum antibiotic with bone marrow toxicity concerns limiting use in developed markets.
- Others:Narrow-spectrum alternatives including aminoglycosides and macrolides for resistance-targeted therapy.
Production scale favors Ciprofloxacin. Development investment is shifting fastest toward narrow-spectrum alternatives under EMA antimicrobial resistance frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate formulation capacity to jurisdictions with streamlined bioequivalence pathways and lower environmental compliance burdens. Cost-of-compliance gaps between mature and emerging regulatory regimes now determine where sterile ophthalmic manufacturing clusters consolidate.
United States
Pediatric ophthalmology clinics in the Southeast and Midwest are escalating prescriptions for topical antibiotic eye drops in children under five. FDA pharmacovigilance requirements for recurrent-use products are compressing development timelines for resistance-profile documentation. Integrated delivery networks in Texas and Florida are consolidating purchasing for affiliated primary care practices, extracting volume-based concessions that bypass retail markup structures.
Germany
Specialized ocular antibacterial formulations command premium positioning in ambulatory ophthalmology settings across Bavaria and North Rhine-Westphalia. EMA antimicrobial stewardship frameworks favor narrow-spectrum alternatives when diagnostic uncertainty drives coverage expansion. REACH restrictions on quaternary ammonium compounds are forcing reformulation of benzalkonium chloride-preserved antibiotics, with temporary supply interruptions visible in Baden-Württemberg manufacturing clusters.
Japan
Orphan drug designation for resistant-strain-targeting formulations offers accelerated PMDA review timelines for novel mechanisms in the Kanto and Kansai regions. Dry-eye-comorbid patient populations requiring recurrent dosing are capturing preference for preservative-free variants. Tokyo-based specialty manufacturers are piloting nanostructured lipid carrier technology for fluoroquinolone compounds with poor aqueous stability.
India
Generic API manufacturers in Maharashtra and Gujarat are shifting toward finished ophthalmic dosage forms, tightening supply-side competition for branded incumbents. CDSCO bioequivalence standards enable rapid entry of low-cost alternatives, eroding price premiums for originator products within 18-24 months of patent expiry. Hyderabad and Ahmedabad clusters face EPA-aligned environmental discharge compliance costs for active pharmaceutical ingredient manufacturing effluent.
Bacterial Conjunctivitis Drugs Market Competitive Environment
United States producers anchor one tier through integrated delivery network contracting and direct-to-clinic distribution scale; European specialists hold formulation differentiation through preservative-free vehicle technologies and narrow-spectrum development pipelines. The vendor base stratifies across three archetypes: diversified pharmaceutical conglomerates with ophthalmology divisions, pure-play eye care companies with dedicated manufacturing infrastructure, and generic API-to-formulation integrators from South Asia. Competitive positioning hinges on backward integration into active pharmaceutical ingredient supply and geographic expansion through regional pharmacovigilance harmonization.
Among diversified pharmaceutical conglomerates, AbbVie Inc. and Pfizer Inc. exemplify scale-driven archetypes with manufacturing breadth for broad-spectrum fluoroquinolone coverage. Novartis AG occupies a position within the European specialist tier, anchoring market presence through ocular antibacterial formulation expertise. Bausch + Lomb represents the pure-play eye care model, leveraging North American distribution infrastructure to sustain pharmacy channel dominance.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bausch + Lomb |
| Novartis AG |
| Santen Pharmaceutical Co., Ltd. |
| Alcon Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Limited |
| Pfizer Inc. |
| Johnson & Johnson Private Limited |
| Others |
Value Chain & Pricing Dynamics
Fluoroquinolone active pharmaceutical ingredient costs flow from Indian and Chinese intermediate manufacturers through formulation tolling in Germany and Japan before stratifying into premium preservative-free, standard preserved, and economy generic tiers at pharmacy and clinic channels.
Pricing Analysis
Distributor margins compress as direct-to-clinic distribution models displace wholesale pharmacy channels for high-volume ambulatory accounts. Three-tier pricing structure across premium preservative-free, standard benzalkonium chloride-preserved, and economy generic tiers separates formulations by toxicity profile and regulatory certification grade. Cost compression in the economy tier intensifies as CDSCO bioequivalence standards enable rapid Indian generic entry. Pediatric ointment formulations command the lowest price sensitivity due to compliance-driven caregiver preference.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for pharmaceutical manufacturing are reshaping sourcing patterns for export-oriented API suppliers. Active pharmaceutical ingredient supply concentrates in Maharashtra and Gujarat, India, with formulation finishing clustered in Bavaria, Germany and Kanto, Japan. Critical dependencies include fluoroquinolone intermediates, quaternary ammonium preservatives, and sterile packaging components. Single-source vulnerability runs through Indian generic API manufacturers controlling ciprofloxacin intermediate supply. Distribution runs through integrated delivery networks in the United States and specialized ophthalmology distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in preservative-free formulation premiums and backward integration into API supply, with cost-down drivers emerging from nanostructured lipid carrier platform standardization.
For Market Incumbents: Acquire sterile ophthalmic manufacturing infrastructure in India to secure API-to-formulation integration against export restriction risk. Defensive consolidation should prioritize narrow-spectrum development pipelines qualifying for Japan's PMDA orphan drug pathways, while channel control investments target southeastern United States integrated delivery network contracting. For New Entrants and Emerging Players: Pediatric ointment formulations represent the most penetrable white-space segment, with compliance-driven caregiver preference creating pricing power in Germany and France. Direct-to-clinic distribution partnerships with ambulatory ophthalmology networks offer the strongest go-to-market angle for bypassing entrenched pharmacy channel markups. For Investors and Strategic Acquirers: Consolidation pressure builds where CDSCO bioequivalence standards have eroded originator price premiums within 18-24 months of patent expiry. Long-term viability favors targets with captive preservative-free vehicle technology and established EMA regulatory dossiers. The signal to watch is FDA pharmacovigilance tightening on recurrent-use ophthalmic antibiotics, which would accelerate narrow-spectrum acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Formulation Development | EMA REACH restrictions on benzalkonium chloride are forcing reformulation investments across European supply lines. |
| Backward Integration into API Supply | Indian PLI scheme incentives reduce cost exposure to fluoroquinolone intermediate export restrictions. |
| Nanostructured Lipid Carrier Platform | German and Japanese specialty manufacturers pilot unified immediate-sustained release architectures for poor aqueous stability compounds. |
| Direct-to-Clinic Distribution Expansion | United States integrated delivery networks in Texas and Florida extract volume concessions bypassing retail markup structures. |
| Narrow-Spectrum Regulatory Pathway Investment | Japan's PMDA orphan drug designation offers accelerated review timelines for resistant-strain-targeting mechanisms. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers against secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation anchored segment-level estimates.
Segment-weighting approaches applied drug type, formulation, end user, and active ingredient dimensions across the analysis window. CAGRs derived from patient population growth, prescribing pattern shifts, and regulatory approval velocity assumptions. Industry-specific inputs included antimicrobial stewardship mandate compliance costs and preservative system reformulation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA pharmacovigilance tightening, EMA REACH restriction expansion, and Indian API export policy shifts. Forecasts reflect documented assumptions without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market